
 Global Periodontal Market | 2026-2036
Global Periodontal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Periodontal Market Foresight
The split between premium implantology and commodity oral care is repositioning how manufacturers allocate R&D budgets across the periodontal value chain. Straumann AG leverages its Swiss manufacturing heritage to dominate the premium dental implant segment. Henry Schein competes through its extensive dental distributor network spanning North America and Europe. Dentsply Sirona anchors its position via integrated digital workflow solutions connecting diagnostics to restorative outcomes.
Periodontal science encompasses the prevention, diagnosis, and treatment of diseases affecting the supporting structures of teeth, including gingiva, periodontal ligament, and alveolar bone, with procedures ranging from non-surgical scaling to guided tissue regeneration using resorbable collagen membranes. The field serves both therapeutic intervention and long-term oral health maintenance across clinical and home settings. Dental implants command the highest margin pools within product type segments due to surgical complexity and material requirements. Disease management applications are outpacing preventive care in revenue growth as aging populations require intervention over maintenance protocols. Online sales channels are gaining share fastest among distribution channels, though dental distributors still control the bulk of professional-grade product flows.
The FDA regulates periodontal devices through its Center for Devices and Radiological Health, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on implantable products. Japan's PMDA maintains distinct approval pathways for regenerative periodontal materials that influence Japanese manufacturers' export strategies. China's NMPA is harmonizing its dental device classification system with international standards, altering market access timelines for foreign suppliers. Stakeholders must monitor how biomaterial innovation pipelines align with evolving sterilization and biocompatibility mandates across multiple jurisdictions.
Market Dynamics
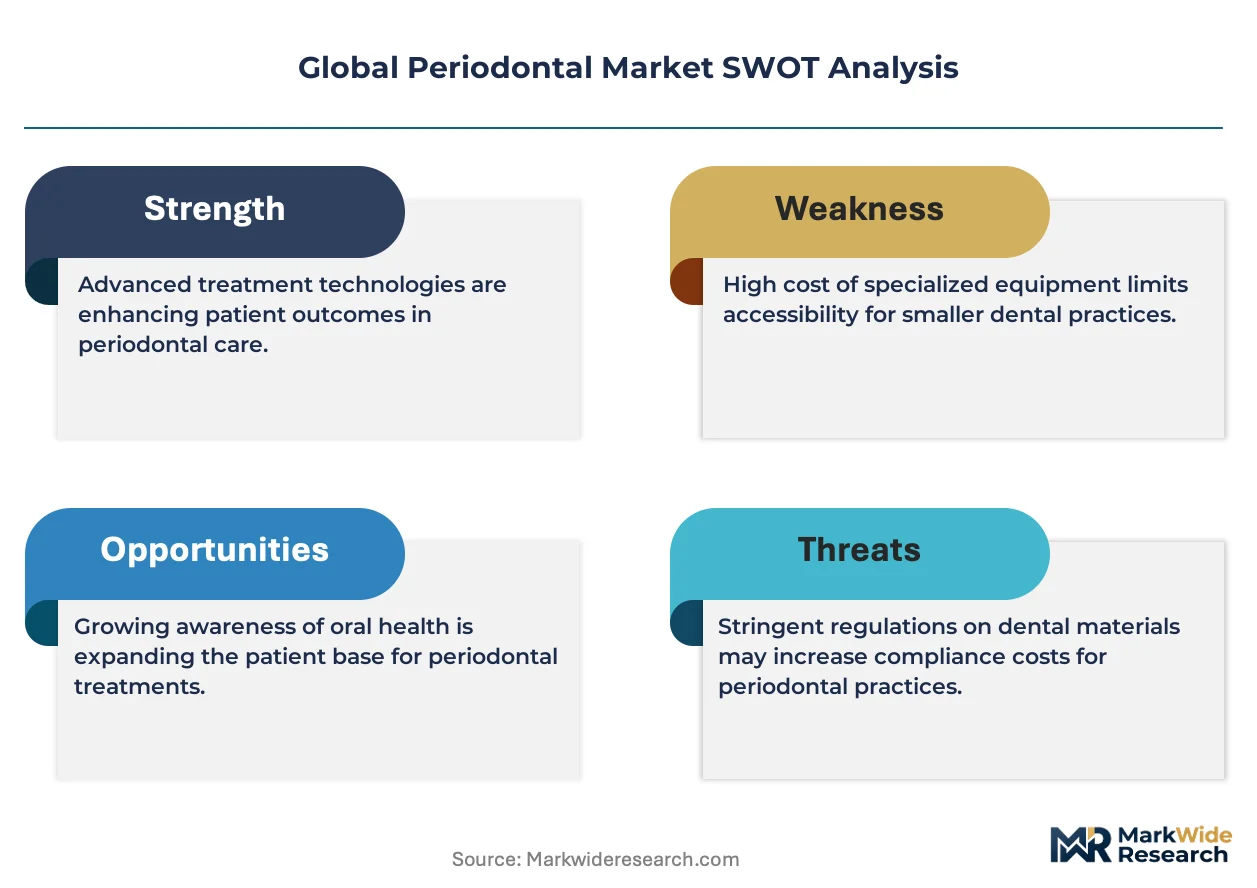
The periodontal market's central structural force is the FDA's accelerated pathway for novel biomaterials, which compresses development timelines and redirects capital toward regenerative materials while forcing incumbents to defend patent positions against faster-moving entrants.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements on implantable products elevate barriers for low-cost competitors, protecting premium positioning for compliant manufacturers.
- China's tier-one city consolidation:Private dental chains in Beijing, Shanghai, and Guangzhou are centralizing procurement, creating volume contracts that favor suppliers with integrated digital workflows.
- Resorbable collagen membranes:Advances in guided tissue regeneration materials are expanding the addressable patient pool beyond traditional implant candidates.
Market Restraints
- Titanium input volatility:Surgical implant manufacturing depends on aerospace-grade titanium supply chains concentrated in Russian and Chinese smelters, exposing margin compression risks.
- Japan's PMDA export friction:Distinct approval pathways for regenerative periodontal materials delay Japanese manufacturers' access to European and North American markets.
- Non-surgical scaling substitution:Ultrasonic debridement devices and air-polishing systems displace manual curettes in early-stage disease management, compressing commodity instrument demand.
Strategic Opportunities
- India's underpenetrated tier-2 cities:Dental clinic density in Lucknow, Jaipur, and Indore remains below saturation thresholds, offering first-mover positioning for equipment suppliers.
- Online professional channel emergence:Direct-to-clinic e-commerce platforms are bypassing traditional dental distributors in Brazil and Mexico, capturing price-sensitive volume.
- ISO 13485 harmonization:China's NMPA alignment with international quality management standards accelerates market access timelines for foreign implant manufacturers.
Industry Challenges
- Periodontal surgeon scarcity:Specialized training programs in Germany and Japan produce insufficient graduates to match implantology demand growth, constraining procedure volume expansion.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 18-24 month completion windows, delaying product launches regardless of clinical efficacy.
- Legacy practice management integration:Digital workflow adoption requires interoperability with entrenched radiology and billing systems, fragmenting upgrade cycles across clinic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Periodontal Market |
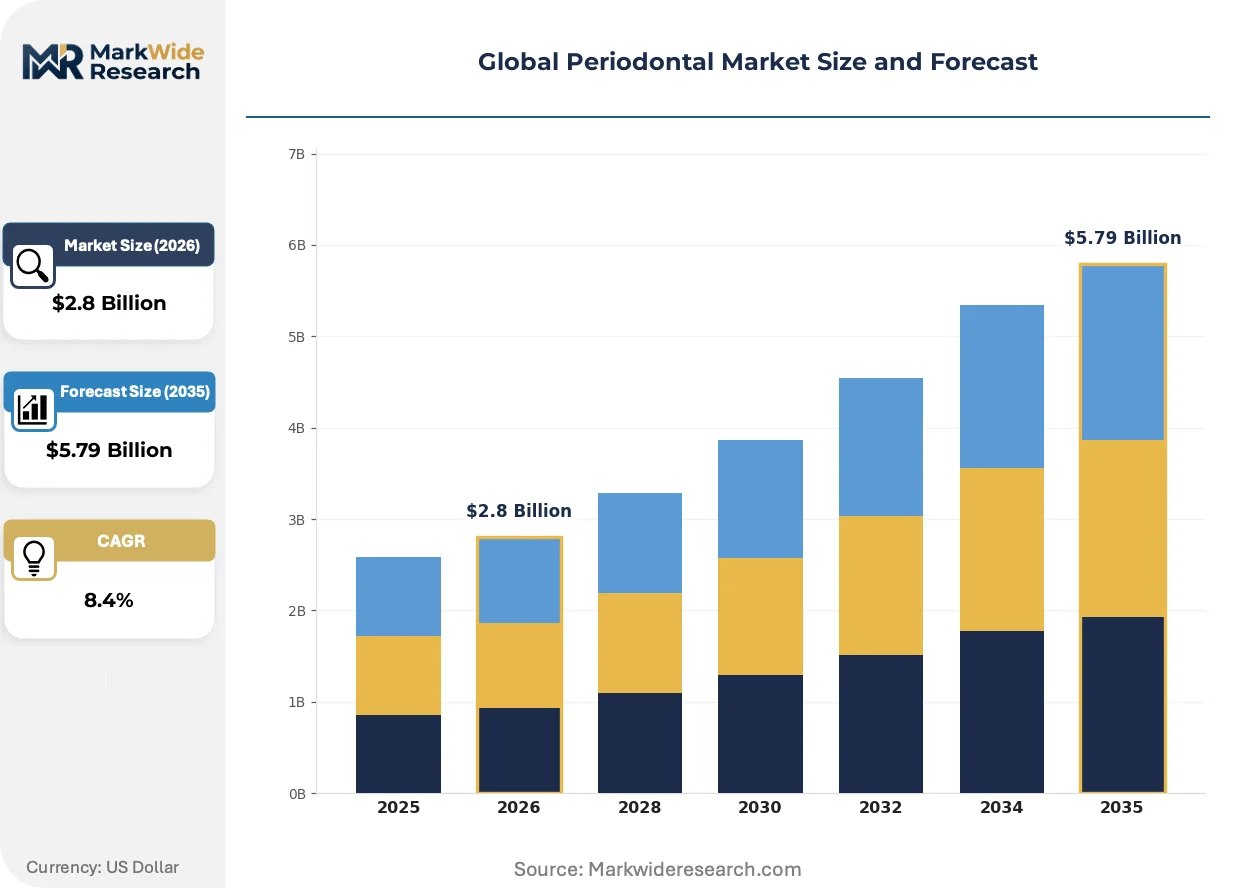
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hospital Equipment, Diagnostic Tools, Dental Implants, Oral Care Products End User: Dental Clinics, Hospitals, Research Organizations, Home Care Application: Periodontal Surgery, Oral Hygiene, Disease Management, Preventive Care Distribution Channel: Online Sales, Retail Pharmacies, Dental Distributors, Medical Supply Stores |
| Companies Covered | Dentsply Sirona, Straumann AG, 3M Company, Medtronic, Bausch Health Companies, Pfizer Inc., Henry Schein, Acteon Group, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Periodontal Market Shifts & Advancements
Digitization is collapsing the traditional separation between periodontal diagnostics and restorative execution, creating pressure for suppliers to deliver contiguous hardware-software ecosystems rather than standalone devices.
Intraoral scanning hardware paired with AI-powered bone-level assessment software is modularizing the diagnostic workflow. Multi-location dental groups in the United States are deploying these systems at replacement cycles of 36-42 months. The technology is modularizing how treatment planning interfaces with surgical guide fabrication, compressing the time between initial consultation and implant placement.
REACH restrictions on certain chemical sterilants are forcing material substitutions in membrane manufacturing. European implant suppliers face reformulation costs for collagen-based products previously dependent on glutaraldehyde cross-linking. German and Swiss manufacturers are accelerating biocompatible alternative development to maintain CE marking compliance without supply interruption.
Subscription-based equipment financing is displacing outright purchase models among independent dental practices. Third-party leasing platforms in Spain and Italy are capturing hardware placement decisions previously controlled by manufacturer captive finance arms. This shift is most visible in Southern European markets where practice ownership fragmentation persists and capital access remains constrained.
Global Periodontal Market Segmentation
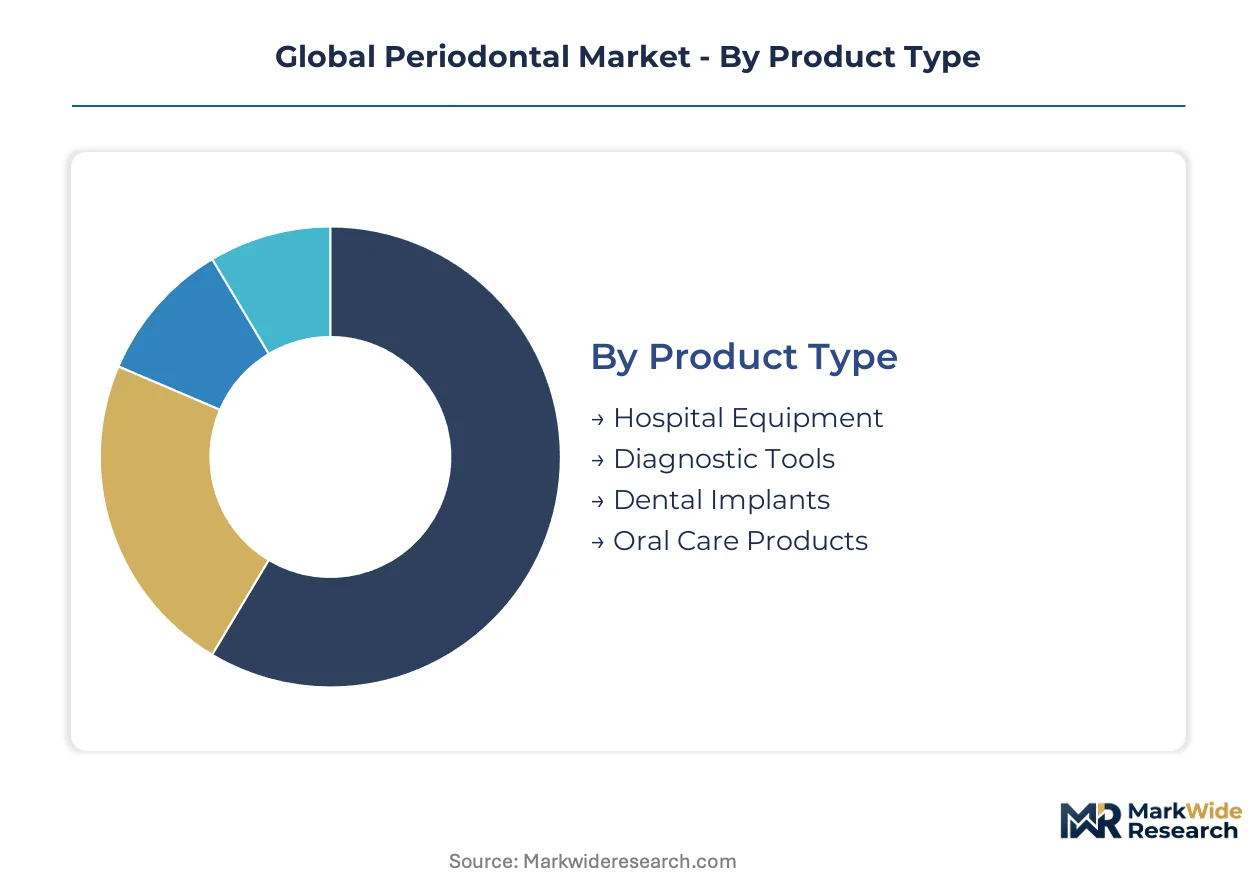
Periodontal market segmentation reveals how surgical complexity, reimbursement pathways, and procurement centralization fragment commercial opportunity across product hierarchies and customer types. Manufacturers must align portfolio depth with the margin and volume characteristics of each segment cluster.
Product Type:
Dental implants capture premium pricing through titanium alloy specifications and surgical placement protocols, while diagnostic tools and oral care products compete on volume throughput across broader patient populations.
- Dental Implants:Titanium-zirconium alloy constructions with surface-modified osseointegration coatings command surgical procedure premiums. Demand concentrates in Germany and Japan where aging demographics and private reimbursement sustain implantology volume.
- Diagnostic Tools:Intraoral scanners and digital radiography systems enable bone-level assessment workflows. China's tier-one cities are absorbing these at replacement cycles driven by private dental chain consolidation and digital workflow mandates.
- Hospital Equipment:Surgical motors and piezoelectric devices for osseous surgery.
- Oral Care Products:Therapeutic rinses and interdental cleaning systems for home maintenance protocols.
Mature deployment sits with Oral Care Products. Newer deployment is concentrated in Diagnostic Tools.
End User:
Customer type determines purchasing authority, with dental clinics controlling discretionary equipment decisions and hospitals managing capital expenditure through centralized procurement committees.
- Dental Clinics:Independent and chain-affiliated practices drive equipment replacement and consumable replenishment. Private chains in Beijing, Shanghai, and Guangzhou are centralizing procurement through volume contracts that favor integrated digital workflow suppliers.
- Hospitals:Academic medical centers and community hospitals manage periodontal surgery departments through capital budgeting cycles. Japan's hospital networks maintain distinct purchasing protocols for regenerative materials under PMDA reimbursement classifications.
- Research Organizations:University dental schools and clinical trial sites for biomaterial validation.
- Home Care:Direct-to-consumer therapeutic products bypassing professional channels.
Revenue concentration favors Dental Clinics. Regulatory complexity peaks with Hospitals.
Application:
Clinical purpose segments the market between intervention protocols requiring surgical authorization and maintenance regimens supported by recurring consumable purchases.
- Disease Management:Guided tissue regeneration and osseous surgery address moderate-to-advanced periodontitis. Aging populations in Germany and Japan are expanding the addressable pool beyond traditional implant candidates toward complex reconstruction cases.
- Preventive Care:Professional prophylaxis and patient education programs reduce disease progression. China's private dental chains are embedding preventive protocols into membership models to secure recurring revenue streams.
- Periodontal Surgery:Flap procedures and regenerative interventions requiring surgical suite infrastructure.
- Oral Hygiene:Professional cleaning and patient-administered maintenance protocols.
Margin protection is strongest in Periodontal Surgery. Volume scaling is fastest in Preventive Care.
Distribution Channel:
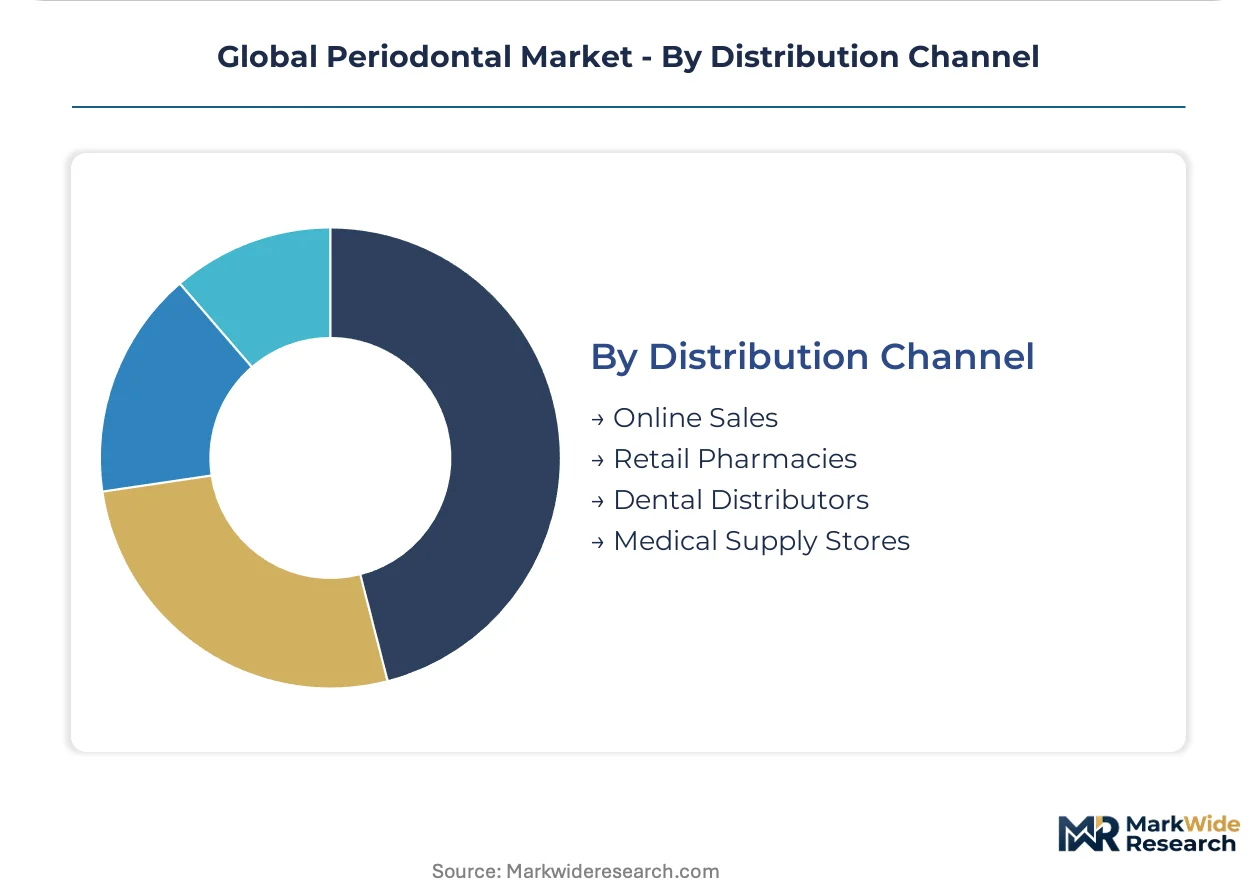
Channel structure determines price realization and customer access, with traditional distributors defending professional relationships while digital platforms capture price-sensitive volume.
- Dental Distributors:Henry Schein and regional specialists control professional-grade product flows through field sales relationships and inventory financing. North American and European clinic networks rely on these intermediaries for equipment installation and technical support.
- Online Sales:Direct-to-clinic platforms and professional marketplaces are gaining fastest in Brazil and Mexico, bypassing traditional distributor markups for consumables and small equipment.
- Retail Pharmacies:Consumer-facing therapeutic products and maintenance supplies.
- Medical Supply Stores:Institutional purchasing for hospital-based periodontal departments.
Relationship control sits with Dental Distributors. Channel expansion is accelerating through Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors periodontal equipment procurement intensity as private dental chains consolidate volume contracts across China's Yangtze River Delta corridor. Beijing and Guangzhou mirror this procurement centralization, while tier-two expansion lags.
United States
Multi-location dental groups deploy intraoral scanning systems at 36-42 month replacement cycles, concentrating demand in metropolitan corridors. FDA's Center for Devices and Radiological Health regulates periodontal devices through premarket notification pathways. Greater Boston and Pacific Northwest clusters drive AI-powered diagnostic adoption among academic-affiliated practices.
Germany
Aging demographics sustain implantology volume through private reimbursement frameworks, with Bavaria and North Rhine-Westphalia hosting dense specialist networks. EU Medical Device Regulation imposes stricter clinical evidence requirements on implantable products. Stuttgart's precision manufacturing corridor supplies surface-modified titanium-zirconium components to European implant fabricators.
Japan
PMDA maintains distinct approval pathways for regenerative periodontal materials, influencing domestic manufacturers' export sequencing. Tokyo-Osaka corridor exhibits surgeon scarcity relative to implantology demand growth. Kansai region's dental schools anchor specialized training programs producing insufficient graduates for procedure volume expansion.
China
Tier-one cities centralize procurement through private dental chains, while NMPA harmonizes dental device classification with international standards. Beijing-Tianjin-Hebei cluster accelerates market access timelines for foreign implant manufacturers. Pearl River Delta manufacturing bases supply resorbable collagen membrane components under REACH-compliant reformulation mandates.
Brazil
Direct-to-clinic e-commerce platforms bypass traditional dental distributors for consumables and small equipment, capturing price-sensitive volume. ANVISA regulates imported periodontal devices through registration pathways distinct from domestic production. São Paulo's private dental networks anchor equipment financing decisions previously controlled by manufacturer captive finance arms.
Global Periodontal Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specifications and surgical complexity tiers, with titanium-zirconium alloy constructions commanding procedure premiums against standard titanium offerings. The vendor base stratifies into Swiss-German precision manufacturers, North American integrated workflow suppliers, and Asian component fabricators. Three archetypes dominate: heritage implantology specialists leveraging manufacturing pedigree, distributor-network players capturing professional-grade flows, and digital workflow integrators connecting diagnostics to restorative outcomes. M&A activity concentrates on regenerative material pipelines and AI-powered diagnostic platforms.
Within the heritage manufacturing tier, Straumann AG and Dentsply Sirona occupy positions shaped by Swiss precision engineering and integrated digital ecosystems respectively. Henry Schein exemplifies distributor-network dominance through field sales relationships and inventory financing across North American and European clinic networks. 3M Company anchors the materials science vector with diversified healthcare positioning.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Straumann AG |
| 3M Company |
| Medtronic |
| Bausch Health Companies |
| Pfizer Inc. |
| Henry Schein |
| Acteon Group |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
REACH restrictions on glutaraldehyde cross-linking agents gate qualified supply for collagen membrane manufacturers while simultaneously anchoring premium-tier pricing access for German and Swiss producers with compliant reformulation capabilities. This environmental mandate fragments the supplier base into REACH-compliant premium tiers and reformulation-lagging standard tiers, with pricing power concentrating among manufacturers who absorbed biocompatible alternative development costs early.
Pricing Analysis
Value-based pricing anchors on surgical outcome metrics and implant survival rates rather than material input costs. Three-tier pricing structure across premium, standard, and economy levels separates titanium-zirconium alloy constructions with surface-modified osseointegration coatings from commodity titanium offerings. Cost compression in the economy tier is intensifying because ultrasonic debridement devices displace manual curettes in early-stage disease management. Private dental chains in China's tier-one cities exhibit lowest price sensitivity due to membership model revenue streams, while independent practices in Southern Europe remain most price-constrained.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Singapore, and Minneapolis anchor hub-and-spoke patterns for professional-grade periodontal equipment. Manufacturing draws from German precision engineering corridors for surface-modified components, Chinese Pearl River Delta bases for resorbable membrane materials, and Japanese titanium processing facilities for aerospace-grade inputs. Single-source vulnerability concentrates in Russian and Chinese titanium smelters supplying surgical implant fabricators. Distribution runs through Henry Schein's North American field sales network and regional dental distributor specialists across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Periodontal Market is becoming a vertical-integration race where control over regenerative material pipelines and digital workflow ecosystems determines margin capture. Players are pursuing backward integration into biocompatible membrane manufacturing to escape REACH-driven supply fragmentation.
For Market Incumbents: Extend digital workflow integration capabilities to capture procurement centralization in China's private dental chains. Incumbent manufacturers should deepen captive supply of resorbable collagen membranes to defend against faster-moving entrants exploiting FDA's accelerated biomaterial pathway. Priority defensive moves include ISO 13485 certification pre-positioning ahead of NMPA harmonization completion and field sales relationship fortification in North American clinic networks facing distributor bypass threats from direct-to-clinic platforms.
For New Entrants and Emerging Players: Dental distributor partnerships in Brazil and Mexico offer the most penetrable channel architecture for price-sensitive volume capture. New entrants should target India's tier-two cities—Lucknow, Jaipur, and Indore—where dental clinic density remains below saturation thresholds and first-mover positioning in equipment supply remains uncontested. Go-to-market execution should emphasize subscription-based equipment financing models that displace manufacturer captive finance arms in capital-constrained Southern European markets.
For Investors and Strategic Acquirers: FDA accelerated pathway approvals for novel biomaterials are the leading indicator that regenerative material pipelines will command acquisition premiums over traditional implant hardware. Long-term viability in this market hinges on portfolio exposure to AI-powered diagnostic platforms and contiguous hardware-software ecosystems rather than standalone device manufacturing. Acquisition target archetypes include mid-cap specialists with ISO 10993 biocompatibility testing completion and established PMDA export sequencing capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Material Pipeline Acquisition | Captures FDA accelerated pathway leverage against slower incumbent development timelines. |
| Digital Workflow Ecosystem Integration | Aligns with China's tier-one city procurement centralization favoring integrated suppliers. |
| ISO 13485 Certification Pre-Positioning | Accelerates NMPA market access timelines for foreign implant manufacturers. |
| Direct-to-Clinic Platform Launch | Bypasses traditional distributor markups in Brazil and Mexico price-sensitive segments. |
| Biocompatible Membrane Reformulation | Maintains CE marking compliance under REACH glutaraldehyde restrictions for European supply. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA approval databases, and NMPA classification harmonization notices, complemented by interviews with periodontal surgeons, dental clinic procurement managers, biomedical engineers at implant manufacturers, GPO contracts managers, and regenerative material R&D directors. Secondary validation drew from hospital procurement databases, dental distributor inventory disclosures, customs trade data for titanium and collagen inputs, and academic periodontal surgery outcome registries. Bottom-up demand modeling and top-down supply capacity assessment were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product type hierarchy, end-user purchasing authority, clinical application purpose, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand curves incorporating aging demographic coefficients and reimbursement pathway evolution. Forecast inputs included surgeon training program graduation rates, private dental chain consolidation velocity, and biomaterial innovation pipeline maturity.
Caveats apply where titanium supply disruptions, REACH restriction expansions, or PMDA export pathway modifications could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization timelines, procurement centralization velocity, and digital workflow adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Chile Dental Devices Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Dental Dam Market
Dental Devices
China Dental Implants Market
Dental Devices
United States Dental Implants Market
Dental Devices
India Dental Devices Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Dental Erbium Lasers Market