
 Dental Caries Market | 2026-2036
Dental Caries Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Caries Market Analysis
Preventive service revenue is tilting away from restorative procedures toward early-intervention protocols. Dentsply Sirona Inc. leverages its integrated imaging and treatment platforms to dominate chairside diagnostics. Henry Schein Inc. anchors distribution networks across North American dental practices. Septodont Holding S.A. specializes in bioceramic endodontic materials that command premium positioning in specialty clinics.
Dental caries constitutes a multifactorial infectious disease characterized by demineralization of enamel and dentin, with lesion progression measured by International Caries Detection and Assessment System scores. The condition drives industrial demand for fluoride-releasing restorative composites, silver diamine fluoride arrest agents, and non-invasive resin infiltration systems. Prevention-focused toothpaste formulations lead volume sales, while dental sealants represent the fastest-growing product category as school-based application programs expand. Diagnostic applications capture concentrated margins through AI-assisted caries detection hardware, whereas cosmetic whitening trails as a mature, promotion-dependent segment.
The FDA Center for Devices and Radiological Health governs dental material biocompatibility through ISO 10993-aligned clearance pathways, while the EPA regulates mercury amalgam waste disposal under effluent limitation guidelines. The European Medicines Agency's Medical Device Regulation imposes clinical evidence requirements that reshape sealant market access timelines. Stakeholders must monitor reimbursement policy shifts toward value-based preventive care models and decide whether to build direct-to-clinic service capabilities or deepen distributor partnerships.
Market Dynamics
The dental caries market pivots on a fundamental reimbursement shift from restorative intervention toward preventive protocols, with payors now rewarding early lesion detection and non-invasive arrest rather than drill-and-fill procedures.
Growth Catalysts
- School-Based Sealant Mandates:Brazil's public oral health programs now mandate dental sealant application in primary schools, creating institutional demand for biocompatible resin systems.
- AI-Assisted Detection:Machine learning algorithms integrated into intraoral scanners enable chairside caries risk stratification, accelerating adoption across North American pediatric practices.
- REACH Bioceramic Standards:The European Chemicals Agency's streamlined substance evaluation for calcium silicate-based materials reduces time-to-market for next-generation endodontic sealers.
Market Restraints
- Silver Price Volatility:Silver diamine fluoride arrest agents face input cost pressure from precious metal commodity swings, squeezing margins on pediatric formulations.
- Mercury Amalgam Phase-Out:The EPA's effluent limitation guidelines impose costly waste capture infrastructure on US practices still using legacy restoratives.
- Clinical Evidence Gaps:Resin infiltration systems lack long-term RCT data versus microabrasion for incipient lesions, slowing payer coverage decisions.
Strategic Opportunities
- Community Health Center Expansion:Federally qualified health centers in underserved US counties represent untapped volume for preventive service bundling.
- Tele-Dentistry Triage:Remote lesion assessment via smartphone imaging collapses geographic barriers to specialist referral in rural Australian regions.
- Japan's METI Preventive Subsidies:The Ministry of Economy, Trade and Industry's reimbursement codes for risk-based caries management incentivize predictive analytics platform deployment.
Industry Challenges
- Digital Workflow Integration:Chairside diagnostic hardware requires expensive PMS retrofitting and staff retraining, delaying ROI realization for mid-sized practices.
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity validation timelines stretch 18-24 months for novel fluoride-releasing monomers, compressing patent exclusivity windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Caries Market |
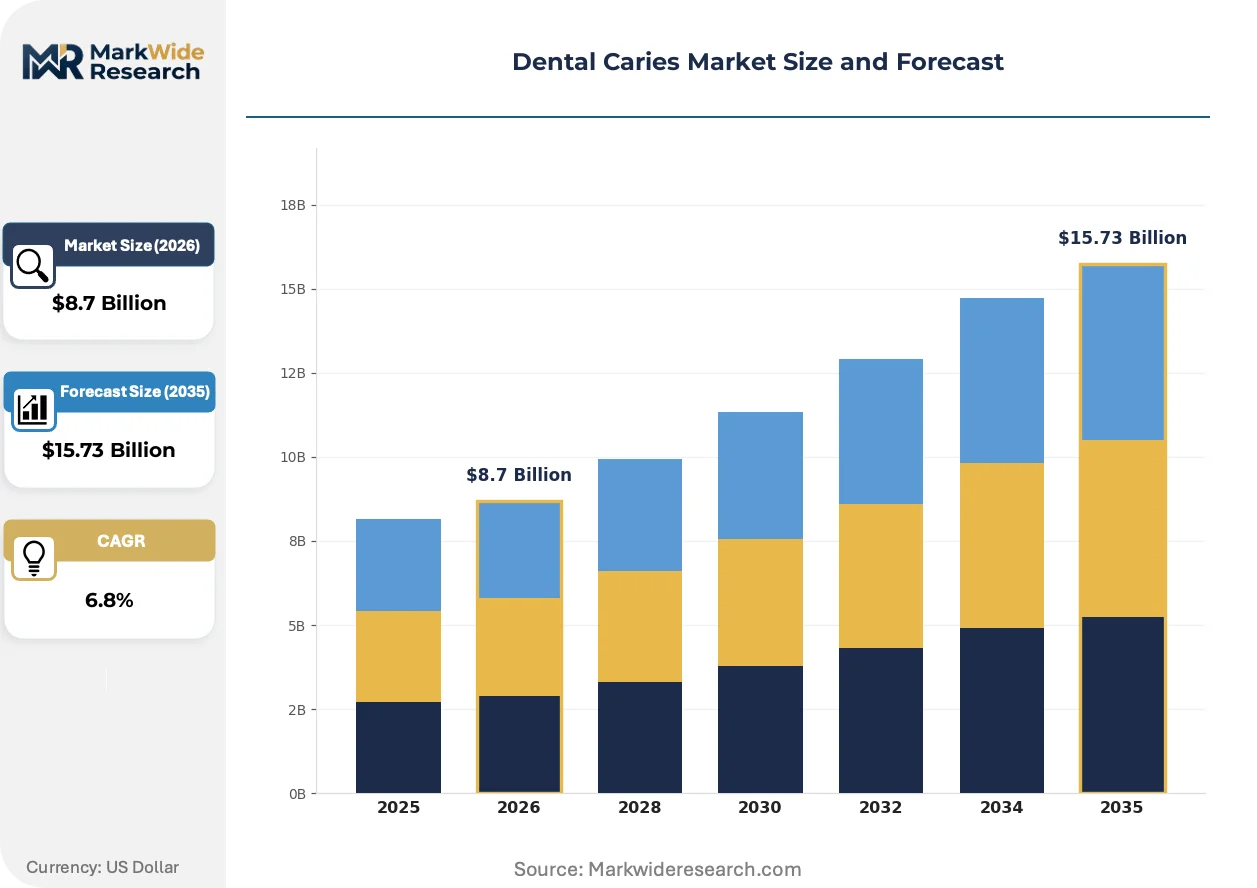
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Sealants, Whitening Products Application: Prevention, Treatment, Diagnostic, Cosmetic End User: Patients, Clinics, Research Facilities, Dental Schools Customer Type: Individuals, Families, Institutions, Professionals |
| Companies Covered | 3M Company, Dentsply Sirona Inc., Henry Schein Inc., Acteon Group, Quantum Dental Technologies Inc., Septodont Holding S.A., Coltene Group, Shofu Dental Corporation, VOCO GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Caries Market Emerging Trajectories
Three distinct vectors are restructuring competitive advantage in caries management: diagnostic automation, regulatory chemistry reform, and procurement centralization. Each trend compresses legacy business models while elevating platform-based service delivery.
Optical coherence tomography is collapsing the distinction between preventive monitoring and restorative intervention. Pediatric specialists in Scandinavian public health systems deploy sub-surface enamel imaging to arrest lesions before cavitation. The technology is collapsing fee-for-service revenue streams tied to operative dentistry.
The European Medical Device Regulation's clinical evidence requirements for Class IIa sealants have extended notified body review timelines. Manufacturers now commission prospective cohort studies rather than relying on predicate equivalence. Pediatric product lines face the steepest compliance cost escalation.
Group purchasing organizations now aggregate demand across multi-clinic dental service organizations, extracting volume discounts on consumables. Independent practices in Germany's KZVen contract regions face margin compression as procurement concentrates. The shift favors suppliers with direct-to-clinic logistics infrastructure over traditional distributor networks.
Dental Caries Market Segmentation
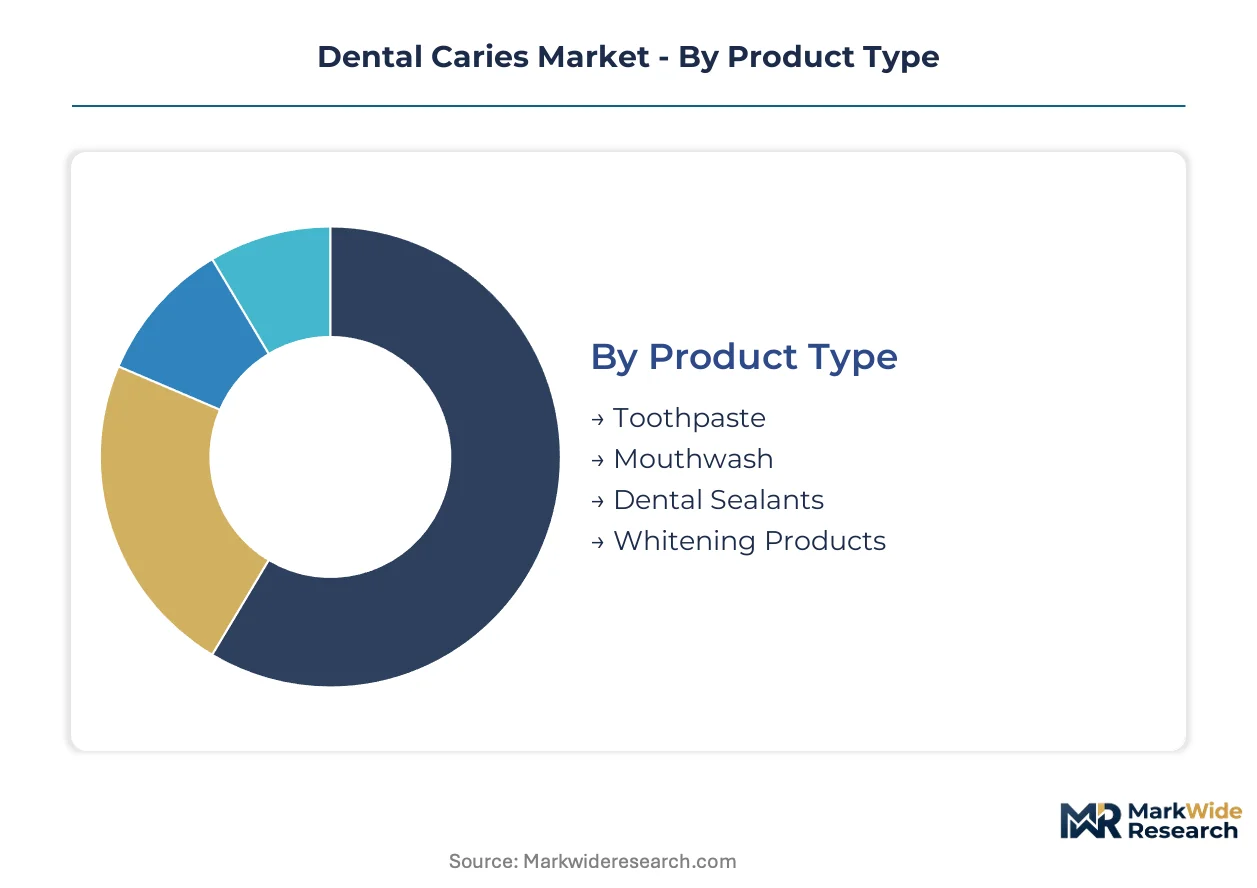
Dental caries market segmentation reveals divergent procurement rhythms across product categories. Prevention-focused consumables turn inventory rapidly through retail and institutional channels, while diagnostic hardware locks capital for years.
Product Type:
Cycle times vary dramatically: toothpaste and mouthwash rotate monthly through retail shelves, whereas dental sealants and whitening systems tie up working capital across quarterly or annual replenishment schedules.
- Toothpaste:Fluoride-releasing formulations dominate volume, with stannous fluoride and sodium fluoride variants commanding distinct price positions. Brazilian public health programs and North American pharmacy chains drive bulk procurement, though private-label compression squeezes branded margins in European mass retail.
- Dental Sealants:Resin-based pit-and-fissure sealants require precise viscosity control for school-based application programs. Brazil's mandatory primary school mandates and US federally qualified health center expansions concentrate demand for biocompatible light-cure systems.
- Mouthwash:Cetylpyridinium chloride and essential oil formulations serve daily adjunctive prevention, with institutional tenders from NHS England and Indian dental colleges shaping regional flavor and alcohol-content specifications.
- Whitening Products:Carbamide peroxide gels and hydrogen peroxide strips face maturity pressure, dependent on promotional intensity at US mass retailers and Australian pharmacy chains.
Toothpaste dominates installed base. Dental sealants are where expansion concentrates.
Application:
Cost tiers separate commodity prevention from premium diagnostics, with treatment occupying the contested middle ground where reimbursement shifts create margin volatility.
- Prevention:Fluoride varnish applications and sealant protocols generate recurring revenue through school-based and community health center contracts. Japanese METI preventive subsidies and Brazilian Smiling Brazil program disbursements direct procurement toward risk-stratified service bundles.
- Treatment:Composite restorations and silver diamine fluoride arrest agents face input cost pressure from resin monomer and precious metal commodity swings. US Medicaid reimbursement cuts and UK NHS banding revisions compress fee schedules for operative procedures.
- Diagnostic:AI-assisted intraoral scanners and optical coherence tomography systems capture concentrated margins through pediatric specialty practices in Scandinavian public health systems and North American dental service organizations.
- Cosmetic:Whitening procedures and aesthetic veneers trail as promotion-dependent segments, with Australian private fee-for-service practices and UAE dental tourism clinics sustaining discretionary spend.
Prevention commands volume throughput. Diagnostic applications capture the steepest margin expansion.
End User:
Customer concentration varies sharply: individual patients fragment demand across millions of transactions, while clinics and institutions aggregate purchasing power through group contracts and national tenders.
- Patients:Direct-to-consumer sales of toothpaste and mouthwash flow through supermarket, pharmacy, and e-commerce channels, with Indian urban households and German drugstore loyalty programs shaping flavor and packaging preferences.
- Clinics:Private practices and dental service organizations negotiate group purchasing organization contracts for sealants and diagnostic hardware, with Henry Schein and Patterson Dental distribution networks dominating North American logistics.
- Research Facilities:Universities and contract research organizations commission biocompatibility studies under ISO 10993 protocols, with EMA MDR clinical evidence requirements extending study timelines for novel fluoride-releasing monomers.
- Dental Schools:Training institutions in São Paulo, Mumbai, and Melbourne standardize on specific composite and endodontic material brands, creating captive demand that converts graduates to lifelong product loyalty.
Clinics anchor procurement volume. Research facilities concentrate highest-value transactions.
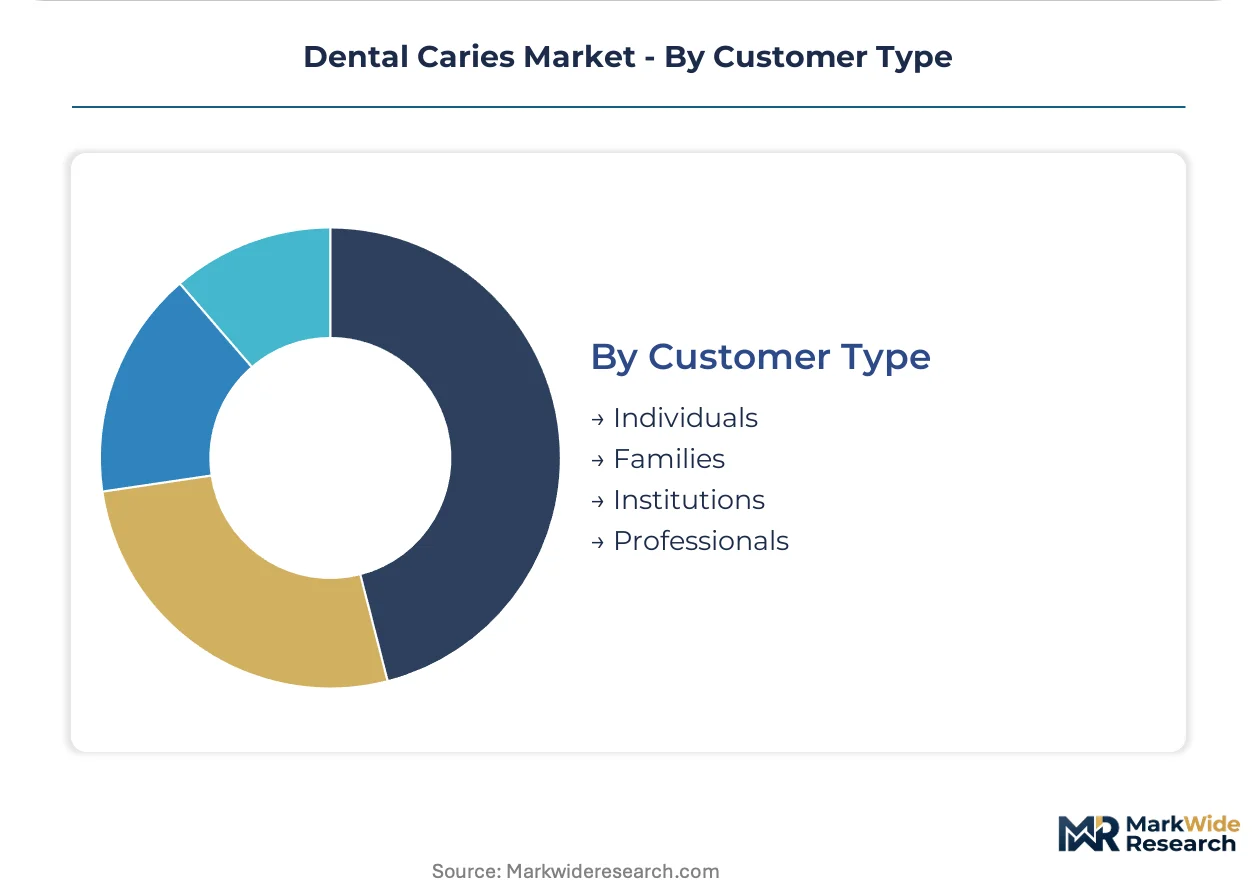
Customer Type:
Volume scale separates institutional tenders from individual purchases, with family units and professionals occupying intermediate positions where subscription and loyalty programs extract lifetime value.
- Individuals:Single-person households drive trial-size and travel-format toothpaste sales, with Japanese convenience store channels and UK supermarket self-checkout impulse placement optimizing basket economics.
- Families:Multi-person households purchase bulk formats and child-specific formulations, with Brazilian conditional cash transfer program eligibility linking oral hygiene product access to school attendance verification.
- Institutions:Prisons, military bases, and cruise lines procure institutional-size mouthwash and toothpaste under specifications mandating alcohol-free or security-compliant packaging, with US Federal Supply Schedule and NATO logistics codes standardizing sourcing.
- Professionals:Hygienists and dentists purchase prophylaxis paste and fluoride varnish through practice-specific distributors, with Canadian provincial regulatory colleges mandating specific infection control product categories.
Individuals generate transaction frequency. Institutions aggregate absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian public procurement exhibits the sharpest price elasticity, with school-based sealant tenders compressing margins, while Japanese preventive subsidies sustain premium positioning for AI-assisted diagnostics.
United States
Federally qualified health centers in underserved counties drive preventive service bundling, with Medicaid reimbursement shifts rewarding early lesion detection. The EPA's effluent limitation guidelines impose costly mercury amalgam waste capture infrastructure. Dallas-Fort Worth dental service organizations aggregate demand through Henry Schein and Patterson Dental distribution networks.
Brazil
The Smiling Brazil program mandates dental sealant application in primary schools, creating institutional volume for biocompatible resin systems. ANVISA accelerates clearance pathways for fluoride-releasing materials. São Paulo's dental schools standardize on specific composite brands, converting graduates to lifelong product loyalty.
Germany
KZVen contract regions concentrate procurement through group purchasing organizations, compressing margins for independent practices. The EMA's Medical Device Regulation imposes clinical evidence requirements that reshape sealant market access timelines. Baden-Württemberg's precision manufacturing clusters supply next-generation diagnostic hardware components.
Japan
METI preventive subsidies incentivize risk-based caries management and predictive analytics platform deployment. The PMDA governs biocompatibility testing for novel fluoride-releasing monomers. Osaka-Kobe industrial corridors manufacture optical coherence tomography systems for Scandinavian export markets.
Australia
Rural tele-dentistry triage via smartphone imaging collapses geographic barriers to specialist referral. The TGA regulates dental material safety under ISO 10993-aligned protocols. Melbourne's dental schools anchor training demand for resin infiltration systems and silver diamine fluoride arrest agents.
Dental Caries Market Vendor Landscape
Capability concentration sits with specialty bioceramic and diagnostic platform developers; scale advantage sits with integrated distribution and imaging conglomerates. The market structures around three tiers: multinational conglomerates with chairside-to-lab workflows, mid-cap regional formulators with institutional contract expertise, and niche technology developers with patent-protected detection algorithms. Dominant competitive moves include backward integration into biocompatibility testing laboratories and strategic partnerships with dental service organizations for captive consumables supply.
Within the integrated platform tier, Dentsply Sirona Inc. exemplifies the convergence of imaging hardware and treatment software, while Henry Schein Inc. anchors North American logistics scale through practice-facing distribution networks. Septodont Holding S.A. occupies a specialist position in bioceramic endodontic materials, commanding premium placement in European and Latin American specialty clinics.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona Inc. |
| Henry Schein Inc. |
| Acteon Group |
| Quantum Dental Technologies Inc. |
| Septodont Holding S.A. |
| Coltene Group |
| Shofu Dental Corporation |
| VOCO GmbH |
| Others |
Supply Flow & Price Mechanics
Silver price volatility in silver diamine fluoride formulations compresses margin spreads across pediatric arrest agents while simultaneously forcing procurement consolidation toward multi-year resin monomer contracts. This input-cost uncertainty stratifies pricing tiers between premium bioceramic sealants and commodity fluoride varnishes, and it reshapes supply chain geography toward Brazilian and German manufacturing clusters with captive raw material access.
Pricing Analysis
Consumables service contracts and extended warranty bundles on diagnostic hardware drive lifetime value capture beyond initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates AI-assisted intraoral scanners from basic light-cure units from disposable articulating paper. Pricing pressure stems from Brazilian public school sealant tenders and German KZVen group purchasing organization aggregation. Pediatric dental clinics exhibit highest price sensitivity due to Medicaid reimbursement compression, while Scandinavian public health systems show lowest sensitivity under value-based preventive care budgets.
Supply Chain Analysis
Resin monomer feedstock supply concentrates in Germany, China, and the United States, with bisphenol A-glycidyl methacrylate and urethane dimethacrylate drawing from petrochemical and specialty chemical streams. Silver nitrate for diamine fluoride formulations rests on precious metal mining concentration in Mexico and Peru. Single-source vulnerability in optical coherence tomography sensor components creates chokepoint exposure. Distribution runs through Henry Schein and Patterson Dental networks for North American clinics, while Septodont and VOCO maintain direct-to-specialist logistics in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-assisted caries detection hardware and school-based sealant mandates constitute a dual inflection disrupting traditional drill-and-fill revenue models. Preventive protocol reimbursement shifts and optical coherence tomography adoption are compressing operative dentistry margins while elevating diagnostic platform valuations.
For Market Incumbents: Insulate core sealant revenue through backward integration into biocompatibility testing laboratories, shortening ISO 10993 validation timelines for next-generation fluoride-releasing monomers. Deepen distributor partnerships with federally qualified health centers in underserved US counties to lock in preventive service bundling contracts before competitive entry.
For New Entrants and Emerging Players: Establish a beachhead in tele-dentistry triage platforms for rural Australian regions, where smartphone-based lesion assessment collapses geographic barriers to specialist referral. Target Japanese METI preventive subsidy channels with risk-stratified analytics software, leveraging reimbursement codes that incentivize predictive caries management deployment.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors specialty bioceramic developers with patent-protected endodontic sealers and AI detection algorithm holders. Long-term viability hinges on regulatory chemistry reform trajectories across EMA MDR and FDA clearance pathways. Watch for REACH streamlined substance evaluation announcements on calcium silicate materials as signal for next-generation sealer market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Testing Laboratory Acquisition | ISO 10993 validation timelines compress from 24 months toward 12 months for novel monomers. |
| Federally Qualified Health Center Partnership | Preventive service bundling contracts lock in recurring sealant volume across underserved US counties. |
| Tele-Dentistry Platform Launch | Smartphone triage collapses rural Australian geographic barriers to specialist caries referral. |
| AI Detection Algorithm Licensing | Chairside caries risk stratification integrates into Dentsply Sirona intraoral scanner workflows. |
| Calcium Silicate Sealer CE Marking | EMA MDR clinical evidence requirements reshape pediatric sealant market access timelines. |
Methodological Framework
A spread of perspectives from pediatric dental clinic operators, biomedical materials procurement managers, GPO contracts specialists, and regulatory affairs leads converged on the working assumptions. Primary interviews with sealant application program directors in Brazilian public health systems and Scandinavian optical coherence tomography deployment coordinators combined with secondary validation from FDA 510(k) filings, EMA MDR notified body guidance documents, ANVISA regulatory bulletins, and METI preventive subsidy disbursement records. Bottom-up demand modeling across product categories triangulated against top-down macroeconomic health expenditure projections.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, application, end user, and customer type plus regional regulatory cluster differentiation. CAGRs derived from historical volume trajectories and reimbursement policy elasticity modeling incorporated silver commodity price forecasting and school-based sealant mandate implementation schedules as industry-specific inputs.
Sensitivities concentrate around precious metal price swings, EMA MDR review timeline extensions, and Brazilian public procurement tender frequency. Cross-checking against WHO oral health expenditure benchmarks and OECD dental workforce density statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
South Africa Dental Devices Market
Dental Devices
South Korea Dental Devices Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Dental Calipers Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Forceps Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
US Dental Splint Market
Dental Devices
Global Periodontal Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
India Dental Devices Market
Dental Devices
Acrylic Teeth Market