
 North America Dental Lab Market | 2026-2036
North America Dental Lab Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dental Lab Market Analytics
Modular restoration bundles combining crowns, abutments, and screw-retained components is recalibrating how dental service organizations contract with fabrication partners. Glidewell Dental leverages its vertically integrated milling centers to control cost structures across zirconia and titanium product lines. National Dentex Labs anchors a multi-site network spanning over thirty states, competing on turnaround speed for high-volume clinic chains. Henry Schein, Inc. extends distribution reach through integrated supply agreements that lock in recurring lab service commitments.
A dental laboratory is a specialized manufacturing facility that fabricates custom oral prosthetics, restorative devices, and orthodontic appliances from patient-specific impressions or digital scans using materials such as zirconia, cobalt-chrome alloys, lithium disilicate glass-ceramic, and photopolymer resins, with primary purpose of delivering biocompatible, precision-fitted devices that restore masticatory function and aesthetic appearance under intraoral loading conditions. Crowns and bridges occupy the dominant revenue position due to replacement-driven demand from aging populations with failing restorations, while 3D printing represents the fastest-expanding technology segment as photopolymer and metal powder bed fusion systems displace conventional wax-and-cast workflows for surgical guides and removable appliances. Dentures retain substantial volume but face margin compression from low-cost digital denture protocols, whereas zirconia material demand climbs as monolithic full-contour crowns replace porcelain-fused-to-metal in posterior indications.
FDA 510(k) clearance requirements govern Class II dental device marketing authorization, while OSHA bloodborne pathogen standards enforce exposure control plans in lab environments handling patient-derived impressions. The EPA regulates methyl methacrylate and particulate emissions from traditional acrylic processing, pushing labs toward enclosed milling units and solvent recovery systems. State dental boards in California, New York, and Texas maintain distinct laboratory registration and technician certification rules that create compliance fragmentation. Stakeholders must monitor FDA draft guidance on additive manufacturing validation as the agency develops framework-specific requirements for 3D printed permanent restorations.
Market Dynamics
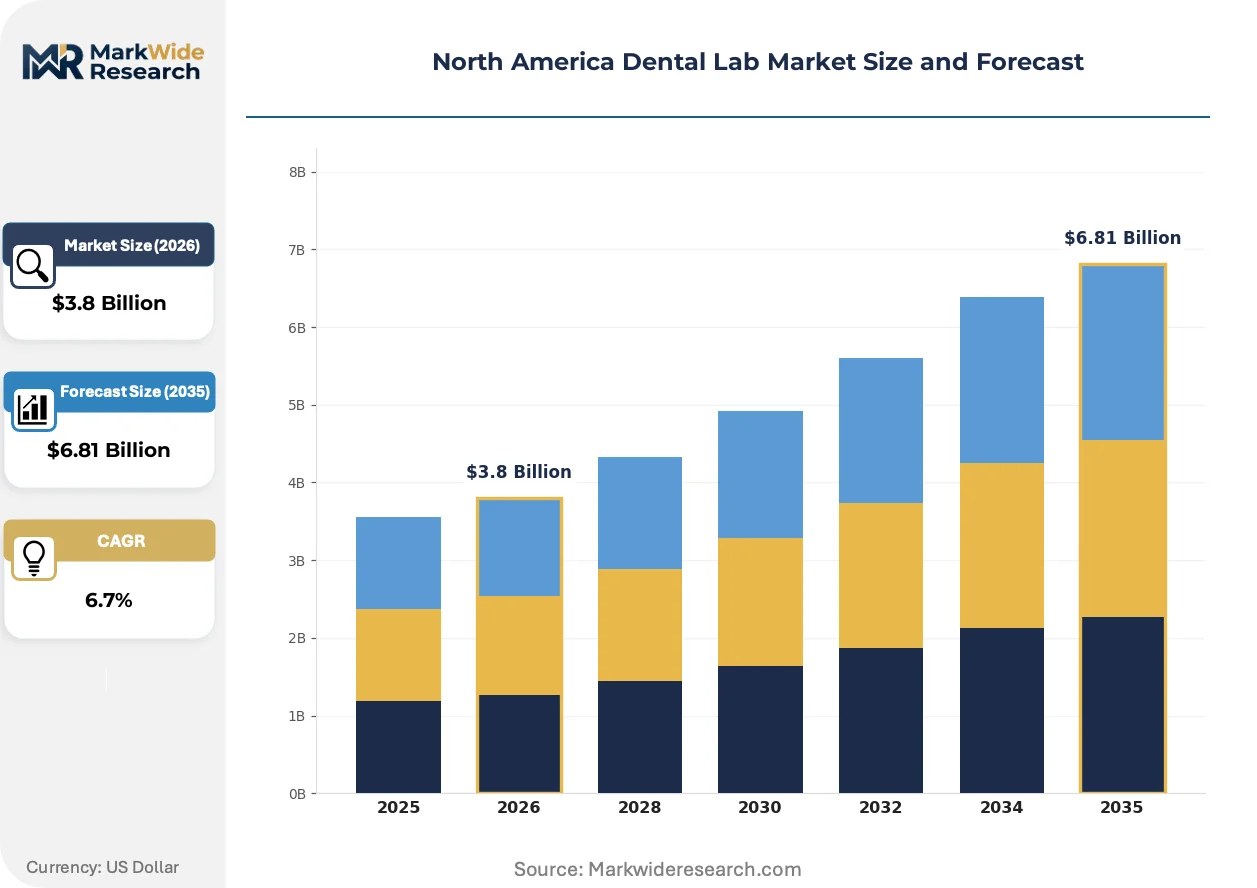
Digital workflows are compressing turnaround times for crown and bridge fabrication while dental service organizations consolidate purchasing power across multi-site networks. This structural shift is forcing independent laboratories to invest in CAD/CAM infrastructure or exit the market entirely.
Growth Catalysts
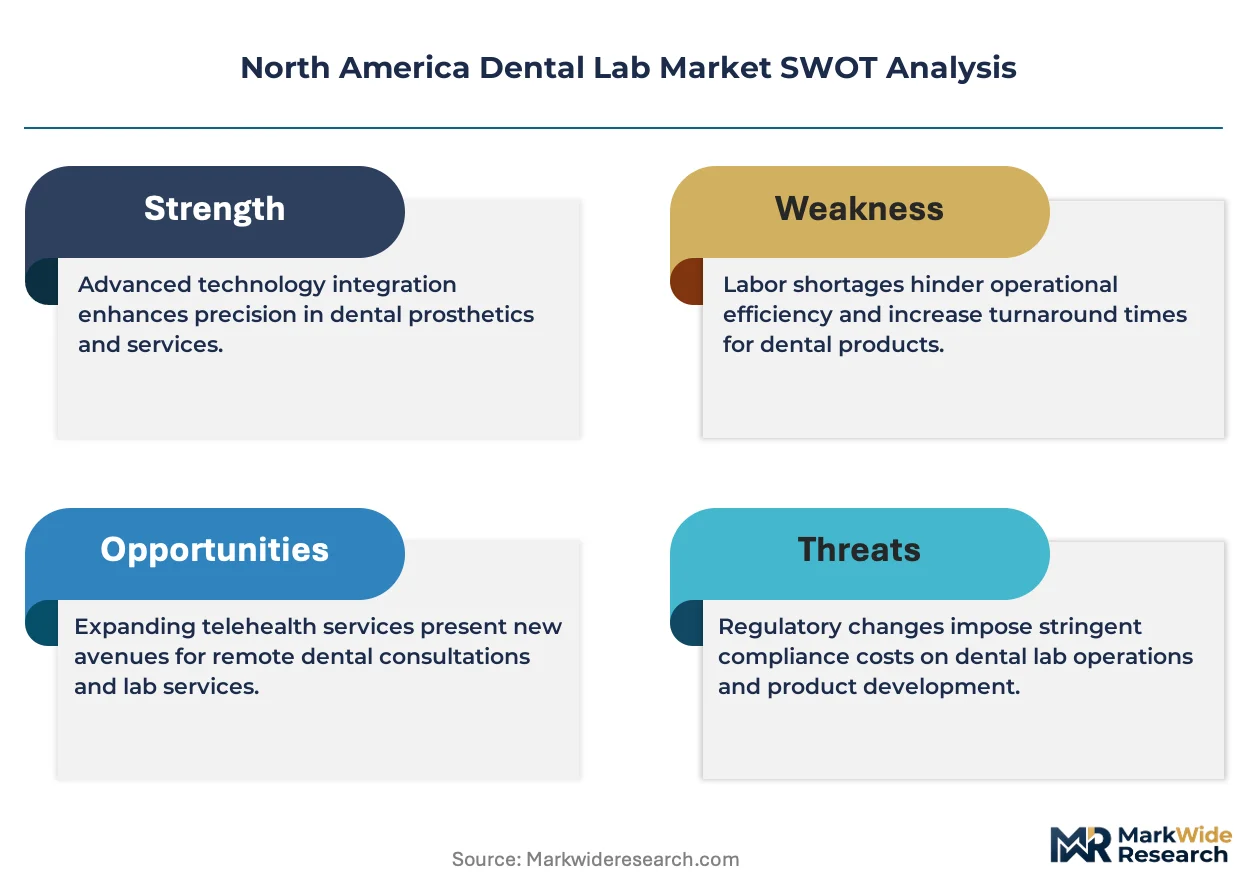
- OSHA Bloodborne Pathogen Standards:Enforcement of exposure control plans drives capital investment in enclosed milling systems and automated impression handling, accelerating lab modernization across the United States.
- Zirconia Monolithic Crowns:Material substitution away from porcelain-fused-to-metal in posterior indications expands addressable volume for full-contour digital fabrication workflows.
- Texas and Florida Lab Networks:Centralized production hubs serving dental service organizations achieve scale economies that independent operators cannot replicate.
Market Restraints
- Titanium and Cobalt-Chrome Alloy Costs:Price volatility in implant-grade metals squeezes margins on custom abutments and screw-retained components.
- California EPA Emissions Rules:Methyl methacrylate processing restrictions force costly solvent recovery system upgrades or workflow abandonment.
- Photopolymer Durability Ceiling:Current 3D printed denture base materials fail to match conventional acrylic fracture resistance, limiting permanent restoration applications.
Strategic Opportunities
- FDA Additive Manufacturing Draft Guidance:Finalized validation frameworks for 3D printed permanent restorations will unlock new product categories currently blocked by regulatory uncertainty.
- AI-Powered Design Automation:Machine learning tools converging with intraoral scanner data streams reduce technician labor hours per unit.
- Midwestern Dental School Partnerships:Untapped clinical training networks in Ohio and Illinois offer embedded lab service contracts with predictable volume commitments.
Industry Challenges
- CAD/CAM Technician Certification:Shortage of operators qualified to program milling strategies for complex implant bar geometries extends production bottlenecks.
- Multi-Scanner Integration:Incompatible file formats between intraoral scanner brands force redundant design workflows and error-prone manual conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dental Lab Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontics, Crowns, Bridges, Dentures End User: Dentists, Dental Clinics, Hospitals, Orthodontists Technology: CAD/CAM, 3D Printing, Milling, Casting Material: Metal, Porcelain, Composite, Zirconia |
| Companies Covered | Glidewell Dental, National Dentex Labs, DDS Lab, Keating Dental Lab, Argen, Leixir Dental Laboratory Group, Young Innovations, Inc., Henry Schein, Inc., Carestream Dental LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dental Lab Market Evolving Landscape
Photopolymer and metal powder bed fusion systems are displacing conventional wax-and-cast methodologies across surgical guide and removable appliance production. This technological pivot is compressing labor intensity while expanding geometric complexity capabilities.
Photopolymer vat polymerization is rewriting production economics for custom surgical guides. Large dental service organizations in California and Texas are deploying chairside printing units for same-day guide delivery. The technology is compressing traditional five-day outsourcing cycles into single-appointment workflows.
FDA draft guidance on additive manufacturing validation is forcing labs to rebuild quality management systems around layer-wise inspection protocols. The industrial consequence is delayed product launches for 3D printed permanent restorations. Implant-focused laboratories are responding by segregating R&D workflows from production lines to isolate regulatory risk.
Consolidated purchasing contracts now dominate procurement for high-volume clinic chains. Traditional distributor relationships are being displaced by direct lab-to-DSO agreements with locked volume commitments. Texas and Florida dental service organizations are leading this channel restructuring, leveraging multi-state scale to extract price concessions and dedicated production capacity.
North America Dental Lab Market Segmentation
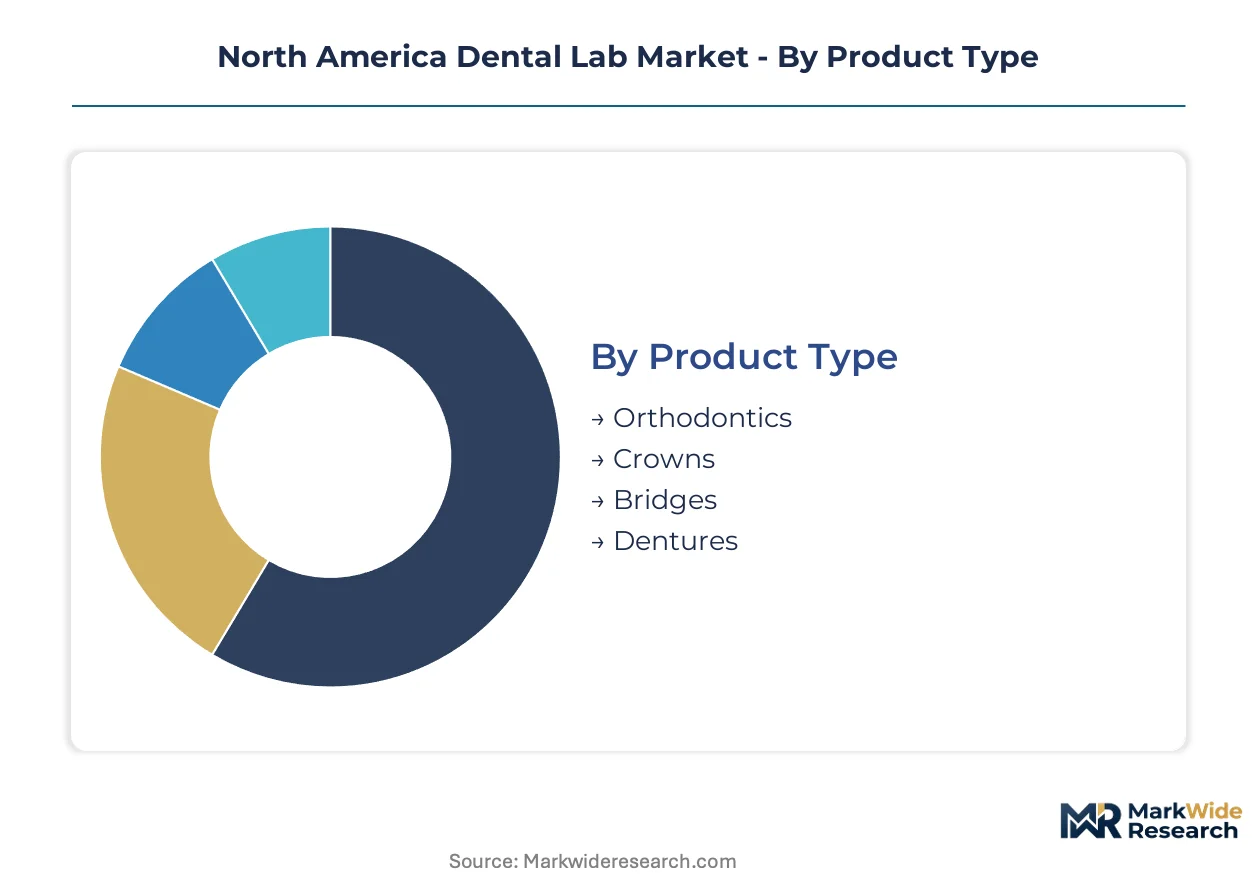
Segmentation in the North America dental lab market reveals how fabrication workflows, material choices, and customer procurement patterns split across distinct operational models. Understanding these divisions exposes where capital investment concentrates and which technology transitions reshape competitive positioning.
Product Type:
Customization intensity varies sharply across this category, from mass-produced aligners to patient-specific implant superstructures.
- Crowns:Monolithic zirconia and lithium disilicate glass-ceramic dominate posterior and anterior indications respectively. Texas and Florida dental service organizations drive volume through centralized procurement of full-contour digital crowns.
- Bridges:Multi-unit fixed prostheses require precision-milled or cast frameworks with ceramic veneering. California prosthodontic clinics anchor demand for implant-supported bridge fabrication.
- Dentures:Acrylic resin bases with composite or porcelain teeth serve edentulous populations. Digital denture protocols compress margins but expand access in Midwestern rural markets.
- Orthodontics:Clear aligner production and fixed appliance fabrication split between thermoformed polymer sheets and bonded brackets.
Most installed capacity flows through Crowns. Expansion is steepest in Orthodontics.
End User:
Procurement scale and technical sophistication create distinct service tiers across customer types.
- Dental Clinics:High-volume chains in California, Texas, and Florida negotiate direct lab contracts with locked capacity commitments. CAD/CAM integration demands compress turnaround expectations to 48-hour crown delivery.
- Dentists:Solo and small-group practices retain traditional distributor relationships. Price sensitivity sustains demand for economy-tier porcelain-fused-to-metal restorations.
- Orthodontists:Aligner fabrication and fixed appliance customization require specialized technician expertise. Clear aligner volume concentrates in suburban metropolitan corridors.
- Hospitals:Academic medical centers and oral surgery departments procure complex implant-supported prostheses. Maxillofacial reconstruction cases demand titanium frameworks and custom abutments.
Revenue concentration sits with Dental Clinics. Margin expansion is strongest in Hospitals.
Technology:
Capital intensity and labor displacement potential differentiate adoption curves across fabrication methods.
- CAD/CAM:Computer-aided design and milling systems enable same-day crown production. California labs lead scanner-to-miller integration for zirconia monolithic restorations.
- 3D Printing:Photopolymer vat polymerization and metal powder bed fusion displace wax-and-cast workflows. Surgical guide production expands fastest in Texas dental service organization networks.
- Milling:Subtractive machining of zirconia, titanium, and cobalt-chrome remains the workhorse for permanent restorations. Equipment amortization schedules favor high-throughput operations.
- Casting:Traditional lost-wax techniques persist for precious metal frameworks and complex implant bars. Labor costs push this method toward niche applications.
Equipment investment concentrates in Milling. Capability gaps are closing fastest in 3D Printing.
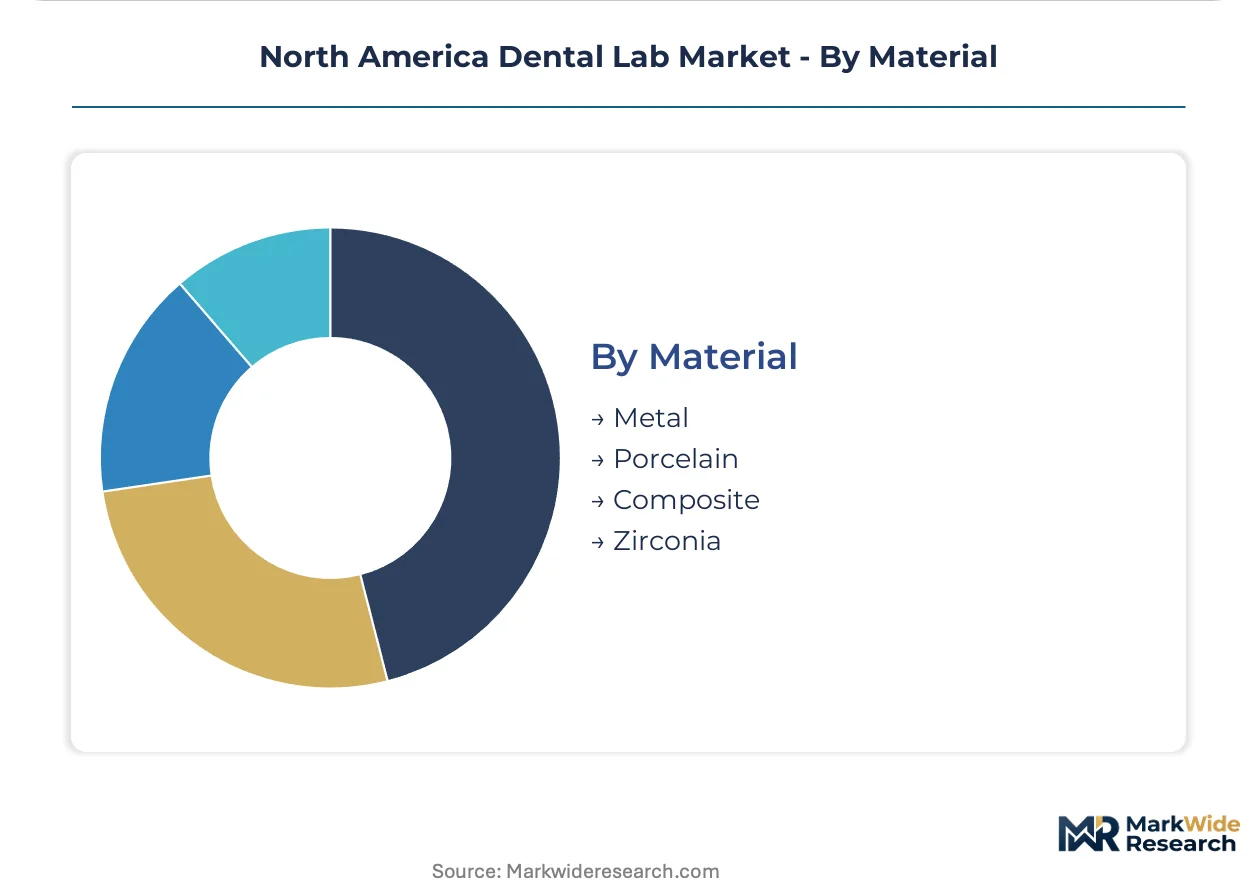
Material:
Performance specifications and regulatory pathways segment supply chains across biocompatibility grades.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal delivers fracture resistance for posterior monolithic crowns. FDA 510(k) clearance pathways for new formulations shorten time-to-market.
- Metal:Cobalt-chrome alloys and titanium serve implant abutments, bars, and removable partial denture frameworks. Price volatility in implant-grade metals squeezes fabrication margins.
- Porcelain:Feldspathic and glass-ceramic veneering materials layer over metal or zirconia substructures. Aesthetic layering techniques retain premium positioning in anterior indications.
- Composite:Resin-based provisional and definitive materials fill chairside and lab-fabricated temporary applications. Photopolymer formulations dominate 3D printed surgical guides.
Volume throughput centers on Zirconia. Substitution pressure is highest on Metal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American dental laboratory industry traces its modern scale to post-war prosthodontic manufacturing clusters that emerged in the northeastern United States during the 1950s, later dispersing to Sun Belt states as dental service organizations consolidated procurement networks across the continent.
United States
California, Texas, and Florida host the densest concentrations of centralized lab networks serving dental service organizations. FDA 510(k) clearance pathways for CAD/CAM milled restorations accelerate product launches from innovation hubs in Orange County and Dallas-Fort Worth. Southern California's prosthodontic corridor links academic medical centers with high-throughput fabrication facilities.
Canada
Ontario and Quebec anchor demand through Toronto and Montreal dental school partnerships that embed clinical training with lab service contracts. Health Canada regulates dental devices under the Medical Devices Regulations, requiring ISO 13485 quality management for commercial distribution. Vancouver's Pacific Northwest cluster specializes in digital denture workflows for rural British Columbia outreach programs.
Mexico
Border states including Baja California and Chihuahua supply cross-border fabrication services to southwestern US clinics seeking cost-advantaged production. COFEPRIS medical device registration requirements govern import-export compliance for biocompatible materials. Tijuana's maquiladora corridor houses precision milling operations serving California dental chains.
North America Dental Lab Market Competitive Landscape
The competitive structure tilts toward vertically integrated multi-site networks competing with specialized regional boutiques. Consolidation pressure from dental service organizations favors scale players with dedicated production capacity and locked volume commitments. Three archetypes dominate: national network operators with geographic redundancy, technology-integrated mills controlling material supply chains, and distributor-affiliated labs leveraging supply agreements. M&A activity concentrates on acquiring CAD/CAM capabilities, while strategic partnerships lock in scanner-to-miller data flows.
Among US-based fabricators, Glidewell Dental exemplifies the vertically integrated archetype through captive milling center networks, while National Dentex Labs occupies the multi-site scale position spanning interstate production hubs. Henry Schein, Inc. represents the distributor-anchored model extending procurement relationships into recurring lab service contracts. These three patterns illustrate how market access, manufacturing scale, and supply chain integration separate competitive tiers.
| Leading Market Players |
|---|
| Glidewell Dental |
| National Dentex Labs |
| DDS Lab |
| Keating Dental Lab |
| Argen |
| Leixir Dental Laboratory Group |
| Young Innovations, Inc. |
| Henry Schein, Inc. |
| Carestream Dental LLC |
| Others |
Value Network & Pricing Analysis
Captive milling center networks anchor both supply security and pricing power for large dental service organizations across California, Texas, and Florida. This backward integration into zirconia and titanium production insulates high-volume buyers from metal price volatility while compressing per-unit costs below independent lab benchmarks.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between dental service organizations and fabrication partners, with pricing stratifying across premium, standard, and economy tiers based on turnaround speed and material certification grade. FDA 510(k) clearance tier and ISO 13485 quality certification drive price differentiation between implant-grade and provisional restorations. Cost compression in economy-tier porcelain-fused-to-metal is intensifying because low-cost digital denture protocols displace conventional acrylic workflows. Solo and small-group practices exhibit highest price sensitivity, while hospital oral surgery departments show least sensitivity due to reimbursement insulation.
Supply Chain Analysis
ISO 13485 quality management certification gates supplier eligibility for US dental labs serving FDA-regulated device markets, with yttria-stabilized zirconia powder sourcing concentrated in Japan, Germany, and the United States. Implant-grade titanium and cobalt-chrome alloy feedstock draws from specialized metallurgical suppliers in Switzerland and the United States. Single-source vulnerability in photopolymer resin formulations for 3D printing creates exposure to formulation discontinuation risks. Distribution runs through direct lab-to-dental service organization agreements that displace traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in monolithic zirconia workflows where material substitution away from porcelain-fused-to-metal unlocks premium pricing with reduced labor intensity. Digital denture protocols compress production costs while expanding addressable volume in underserved rural corridors.
For Market Incumbents: Extend CAD/CAM technician training pipelines to resolve bottlenecks in complex implant bar programming. Lock in exclusive scanner-to-miller data integration agreements with intraoral scanner manufacturers to isolate proprietary workflows from file format fragmentation threats. Deepen backward integration into zirconia blank manufacturing to capture margin currently flowing to Japanese and German powder suppliers. For New Entrants and Emerging Players: Launch via chairside 3D printing units deployed directly into dental service organization operatories, bypassing centralized lab networks entirely. Target Midwestern dental school partnerships in Ohio and Illinois where embedded lab service contracts offer predictable volume with lower competitive density than California or Texas markets. Position around same-day surgical guide delivery as the differentiated value proposition. For Investors and Strategic Acquirers: Roll-up economics work for regional CAD/CAM-capable labs because dental service organization procurement consolidation demands geographic redundancy that fragmented independents cannot deliver alone. Acquisition focus should center on labs with existing FDA 510(k) clearances and validated quality management systems. The signal to watch is finalized FDA additive manufacturing guidance, which will unlock premium valuation multiples for 3D-printed permanent restoration capabilities currently trapped in regulatory uncertainty.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Infrastructure Investment | Enables 48-hour crown delivery commitments that secure dental service organization contracts. |
| ISO 13485 Certification Pathway | Opens hospital and academic medical center procurement channels requiring quality system validation. |
| Intraoral Scanner Partnership | Locks in seamless file format integration that reduces design workflow friction and error rates. |
| Midwestern Dental School Alliance | Captures embedded training contracts with volume predictability absent in competitive coastal markets. |
| Additive Manufacturing Validation | Positions for FDA-cleared 3D printed permanent restorations when guidance finalizes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental laboratory operations directors, prosthodontic clinic procurement managers, CAD/CAM technician supervisors, and dental service organization supply chain executives with secondary validation against FDA 510(k) clearance databases, EPA emissions compliance records, state dental board registration filings, and dental school clinical training contract disclosures. Bottom-up fabrication volume estimates triangulated against top-down dental service organization spending patterns.
Historical reference periods anchored the forecast window to post-pandemic recovery trajectories and digital workflow adoption curves observed across the analysis window. Segmentation modeling incorporated product type, end user procurement scale, fabrication technology, and material biocompatibility grade. CAGRs derived from unit volume projections calibrated to dental service organization expansion plans and intraoral scanner installation rates. Industry-specific inputs included zirconia material substitution elasticities and 3D printing equipment depreciation schedules.
Several conditions sit outside the modeled scope, including potential FDA reclassification of 3D printed permanent restorations, OSHA bloodborne pathogen standard enforcement intensity variations, and abrupt titanium alloy price spikes from geopolitical supply disruptions. A model refresh is warranted upon material change in FDA additive manufacturing guidance finalization or dental service organization M&A consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Radiometer Market
Dental Devices
Dental Regeneration Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Contouring Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Dental CAD Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental Sealants Market
Dental Devices
Orthodontics Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental Scalers Market
Dental Devices
Spain Dental Devices Market