
 Periodontal Scalers and Curettes Market | 2026-2036
Periodontal Scalers and Curettes Market Size, Share, and Industry Trends Forecast 2026-2036
Periodontal Scalers and Curettes Market Intelligence
Dental clinic procurement is pivoting toward ultrasonic and specialty curette portfolios as group practices replace solo practitioners across North America and Western Europe. Hu-Friedy Mfg. Co. LLC leverages its century-long heritage in hand-crafted stainless steel instruments to sustain premium positioning among periodontal specialists. Dentsply Sirona competes through integrated digital workflow ecosystems that bundle scaling systems with imaging platforms. Henry Schein Inc. controls distribution density via its direct sales force serving mid-market dental service organizations.
Periodontal scalers and curettes are precision hand or powered instruments designed for subgingival debridement, typically manufactured from surgical-grade stainless steel or titanium alloys with Rockwell hardness ratings exceeding 45 HRC to maintain edge integrity through repeated sterilization cycles. Their primary commercial purpose centers on removing calculus deposits and biofilm from root surfaces while preserving cementum during periodontal maintenance and active therapy. Ultrasonic scalers lead product type revenue due to higher unit pricing and recurring consumable attachment sales, whereas manual instruments anchor volume in emerging markets where capital equipment budgets remain constrained. Titanium material variants represent the fastest-growing segment as clinicians prioritize reduced hand fatigue and improved tactile feedback during extended procedures.
The FDA regulates these devices under 21 CFR 872.4820 as manual and powered dental scalers, requiring biocompatibility testing and sterilization validation for 510(k) clearance, while the EU Medical Device Regulation mandates clinical evidence and notified body conformity assessment for CE marking access. ISO 17664 standards govern reprocessing instructions that manufacturers must validate to support reusable instrument claims. Stakeholders should monitor how evolving sustainability mandates and single-use device taxation proposals in European markets reshape the economics of instrument reprocessing versus disposable alternatives.
Market Dynamics
Dental service organization consolidation is concentrating procurement authority into fewer decision-makers, compressing vendor margins while elevating instrument performance specifications and sterilization traceability requirements across North American and Western European markets.
Growth Catalysts
- Aging Demographics:Periodontal disease prevalence rises sharply among patients over 65, expanding maintenance procedure volumes in Germany, Japan, and the United States.
- EU MDR Compliance:Stricter clinical evidence requirements for reusable surgical instruments are accelerating replacement cycles as clinics upgrade to validated device portfolios.
- Titanium Alloy Adoption:Reduced hand fatigue during extended procedures drives specialist preference for lightweight instrument variants with Rockwell hardness exceeding 45 HRC.
Market Restraints
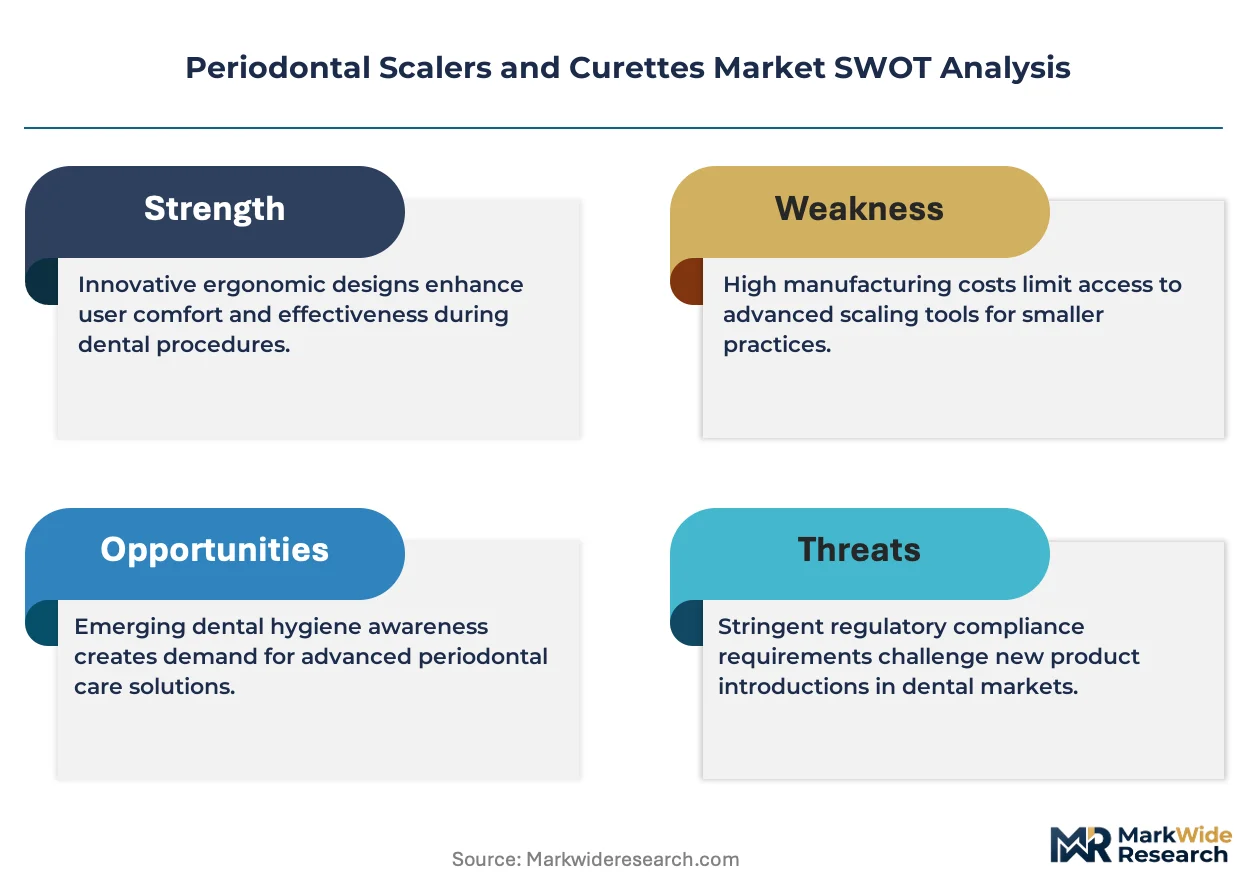
- Surgical-Steel Price Volatility:Nickel and chromium input cost fluctuations squeeze margin stability for manufacturers dependent on austenitic stainless grades.
- Single-Use Device Taxation:Proposed environmental levies in France and Italy threaten to disrupt the economics of disposable curette alternatives.
- 510(k) Pathway Complexity:FDA sterilization validation requirements extend clearance timelines for novel reprocessing claims, delaying market entry.
Strategic Opportunities
- Indian Dental Clinic Expansion:Underpenetrated tier-2 and tier-3 cities present volume growth potential for manual instrument portfolios suited to capital-constrained settings.
- Digital Workflow Integration:Convergence of ultrasonic scaling systems with intraoral imaging platforms creates bundled solution demand among group practices.
- Sustainability Mandates:EU Green Deal circular economy directives favor reusable instrument business models with validated reprocessing protocols.
Industry Challenges
- Master Craftsman Shortage:Hand-finished instrument production requires specialized grinding expertise that retiring European and Japanese toolmakers are not replenishing.
- Legacy Sterilizer Compatibility:New titanium variants face integration friction with existing autoclave infrastructure calibrated for stainless steel thermal profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Periodontal Scalers and Curettes Market |
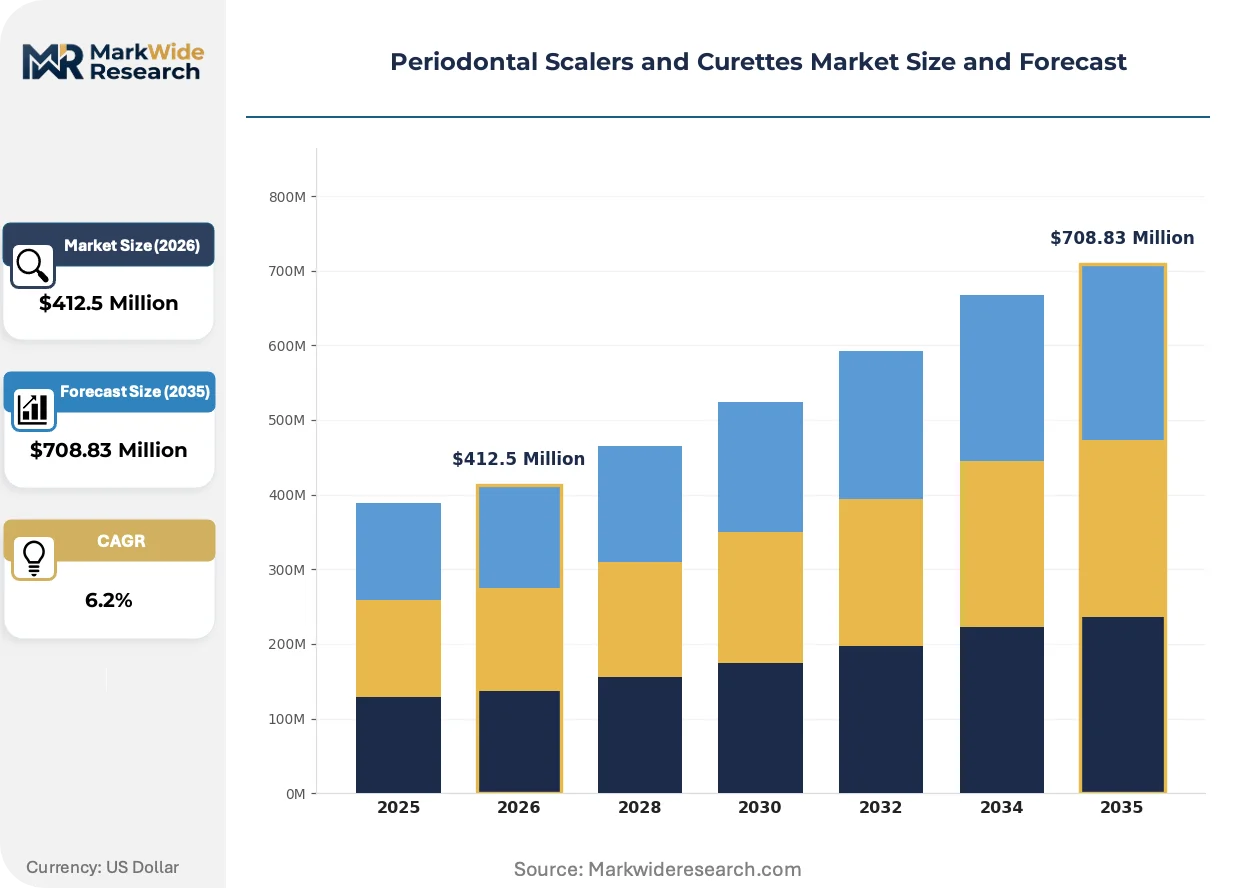
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $708.83 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Scalers, Ultrasonic Scalers, Hand Instruments, Specialty Curettes End User: Dentists, Dental Clinics, Hospitals, Research Laboratories Material: Stainless Steel, Plastic, Titanium, Carbon Steel Application: Periodontal Disease Treatment, Scaling, Root Planing, Oral Hygiene |
| Companies Covered | Hu-Friedy Mfg. Co. LLC, Dentsply Sirona, Den-Mat Holdings LLC, A-dec Inc., Henry Schein Inc., Kerr Corporation, Coltene Whaledent Pvt. Ltd., EMS Medical, Micron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Periodontal Scalers and Curettes Market Strategic Shifts & Innovations
Instrument intelligence and material science advances are compressing the gap between manual tactile precision and powered efficiency, while regulatory transparency requirements reshape how manufacturers document device lifecycles.
Adaptive ultrasonic tip technology with embedded pressure sensors is rewriting procedural safety protocols by providing real-time feedback on root surface contact force. Periodontal specialists in the United States and Switzerland are adopting these systems fastest, with group practice procurement committees mandating their inclusion in equipment tenders. The technology is rewriting liability exposure calculations as insurers begin recognizing quantified force documentation in malpractice coverage assessments.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing reprocessing instruction overhauls across the instrument supply base. Manufacturers must now validate sterilization cycle counts and edge degradation curves with notified body oversight, adding documentation burden but creating competitive differentiation for compliant portfolios. German and French dental clinics are responding by consolidating purchases around vendors with established post-market surveillance systems.
Group dental organizations are unbundling after-sales service from capital equipment contracts, instead negotiating direct maintenance agreements with third-party sterilization validation specialists. This purchasing behavior shift disrupts traditional manufacturer revenue models built on bundled service margins. The pattern is most visible across Dental Service Organization networks in Texas, Florida, and California, where procurement teams prioritize total cost of ownership transparency over upfront equipment discounts.
Periodontal Scalers and Curettes Market Segmentation
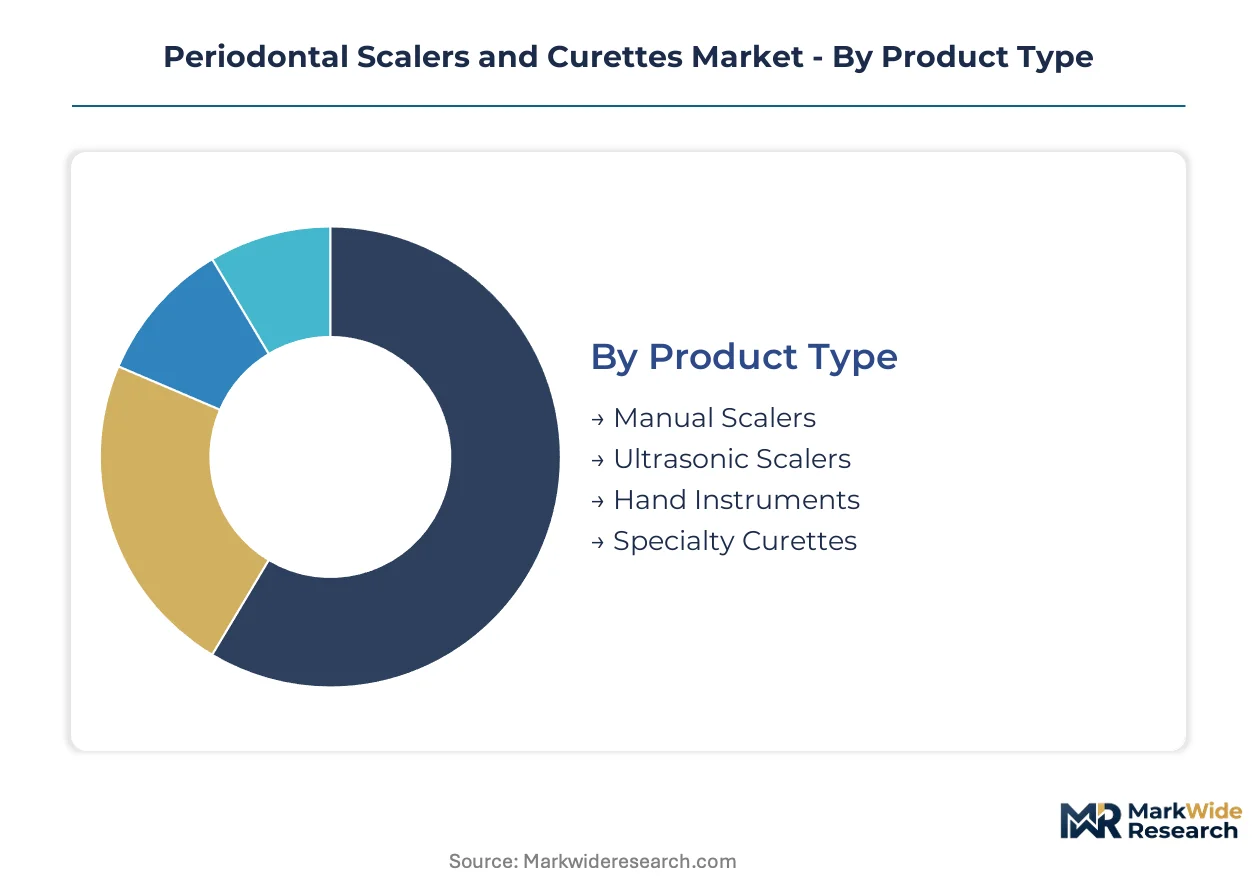
Periodontal instrument procurement varies sharply across clinical settings and procedural requirements. Material selection and power source configurations determine both upfront capital allocation and lifetime operational economics for dental practices.
Product Type:
Customization versus standardization tension runs deepest here, with powered systems demanding integration investment while manual portfolios offer plug-and-play flexibility.
- Manual Scalers:Hand-finished stainless steel instruments with precisely ground cutting edges require no electrical infrastructure. Demand clusters in India's tier-2 and tier-3 cities where capital equipment budgets remain constrained and sterilization protocols favor simplicity.
- Ultrasonic Scalers:Piezoelectric or magnetostrictive systems generate cavitation for calculus removal at 18-45 kHz frequencies, commanding premium pricing through recurring tip replacement revenue. United States group dental practices drive procurement concentration as bundled imaging integration becomes a tender requirement.
- Hand Instruments:Curettes and sickle scalers with ergonomic handle designs target extended procedural comfort.
- Specialty Curettes:Gracey and universal patterns with site-specific angulation serve complex subgingival access.
Leading the category by volume: Manual Scalers. Growing fastest: Ultrasonic Scalers.
End User:
Procurement authority concentrates differently across this axis, with institutional buyers demanding validation documentation that solo practitioners often bypass.
- Dentists:Individual practitioners prioritize instrument longevity and tactile feedback over technology integration. Germany's master craftsman heritage sustains preference for hand-finished European steel in solo periodontal practices.
- Dental Clinics:Multi-chair facilities with centralized sterilization departments drive standardization and traceability requirements. Texas and Florida Dental Service Organizations now mandate ultrasonic systems with embedded pressure sensors across their networks.
- Hospitals:Academic medical centers require research-grade documentation and training program compatibility.
- Research Laboratories:Histology and biofilm studies demand specialized tip geometries and material purity standards.
Dental Clinics dominate procurement volume. Research Laboratories expand most quickly as periodontal-systemic disease linkages attract funding.
Material:
Performance specifications and fatigue economics diverge substantially across metallurgical choices.
- Stainless Steel:Austenitic grades 304 and 316L with 45+ HRC hardness ratings dominate instrument production. Nickel price volatility from Indonesian and Russian supply disruptions squeezes margin stability for manufacturers dependent on these grades.
- Titanium:Ti-6Al-4V alloy variants at roughly 60% the density of steel reduce hand fatigue during extended root planing procedures. Swiss periodontal specialists and United States group practices lead adoption as ergonomic claims enter malpractice liability calculations.
- Plastic:Single-use alternatives face proposed environmental levies in France and Italy.
- Carbon Steel:Higher hardness potential offers edge retention advantages but requires more rigorous corrosion protection.
Stainless Steel anchors volume leadership. Titanium claims the steepest expansion trajectory.
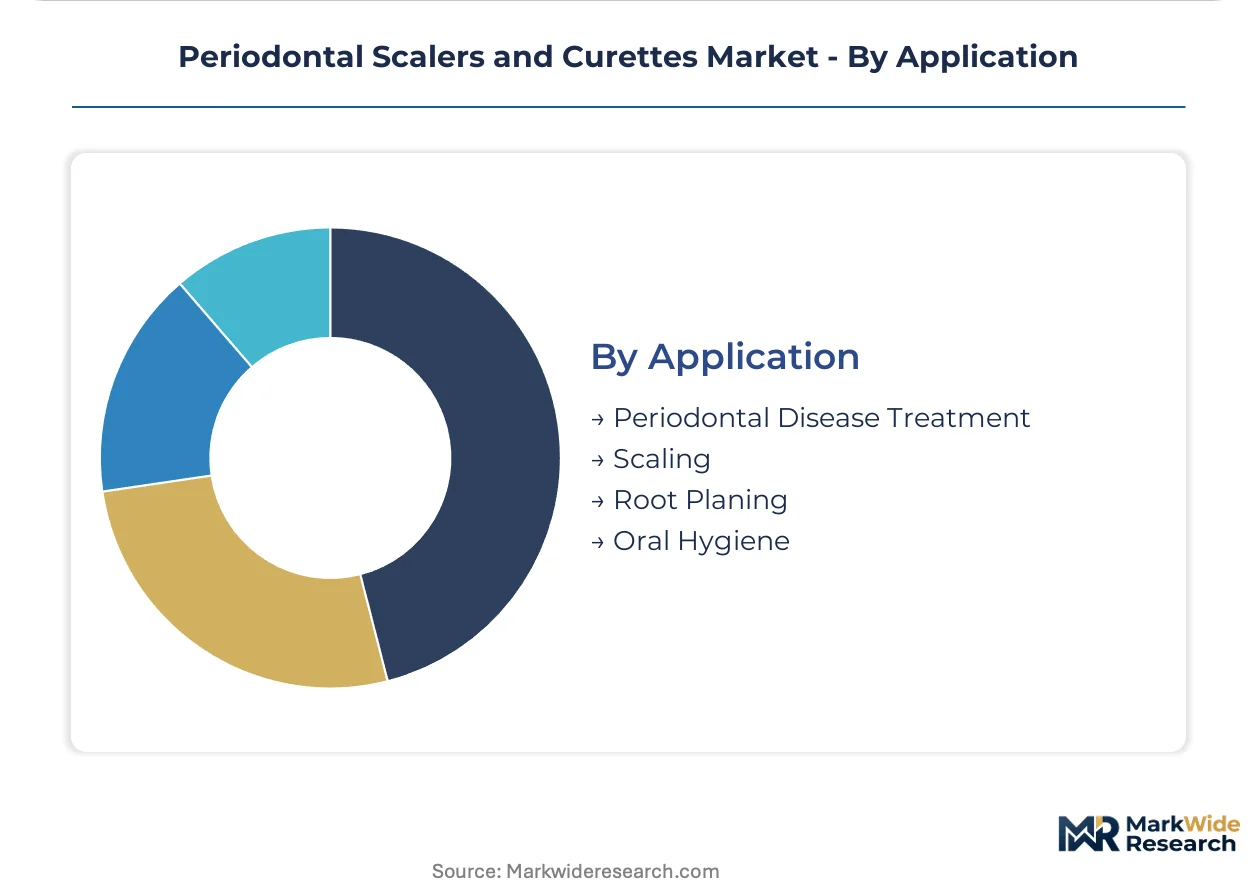
Application:
Procedural reimbursement codes and clinical outcomes measurement reshape demand patterns across therapeutic categories.
- Periodontal Disease Treatment:Active therapy for moderate-to-severe cases combines scaling with adjunctive antimicrobial protocols. Japan's aging population drives maintenance procedure volume as 65+ demographic penetration exceeds 29%.
- Scaling:Supragingival debridement represents the highest-frequency procedure across general dentistry.
- Root Planing:Subgingival cementum modification demands precise tactile control and validated edge geometry.
- Oral Hygiene:Prophylactic maintenance protocols emphasize biofilm disruption over calculus removal.
Scaling procedures generate highest volume. Periodontal Disease Treatment applications climb fastest as diagnostic criteria tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, Switzerland, and the United States, while consumption spreads across aging dental markets in Japan, Western Europe, and North America. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance timelines creates asynchronous product launch cycles across jurisdictions.
United States
Dental Service Organizations in Texas, Florida, and California drive procurement centralization, mandating ultrasonic systems with embedded pressure sensors across multi-chair networks. FDA sterilization validation requirements under 21 CFR 872.4820 extend clearance timelines for novel reprocessing claims. The Dallas-Fort Worth metro anchors distribution density for mid-market instrument portfolios serving consolidated group practices.
Germany
Master craftsman heritage sustains preference for hand-finished European steel in solo periodontal practices across Bavaria and Baden-Württemberg. EU MDR Unique Device Identification mandates force reprocessing instruction overhauls with notified body oversight. The Stuttgart industrial cluster concentrates precision grinding expertise for surgical-grade instrument production.
Japan
Aging demographics expand maintenance procedure volumes as 65+ demographic penetration exceeds 29%, particularly in Tokyo and Osaka metropolitan areas. METI standards govern medical device quality management systems alongside PMDA marketing approval pathways. The Nagoya medical device corridor hosts specialized manufacturers serving domestic periodontal specialists.
Switzerland
Periodontal specialists in Zurich and Geneva lead titanium alloy adoption as ergonomic claims enter malpractice liability calculations. Swissmedic mandates clinical evidence for reusable surgical instruments under harmonized EU MDR requirements. The Basel region concentrates precision metallurgy expertise for lightweight Ti-6Al-4V instrument variants.
India
Tier-2 and tier-3 cities present volume growth potential for manual instrument portfolios suited to capital-constrained clinical settings across Maharashtra and Gujarat. CDSCO medical device rules require import licensing and quality certification for foreign manufacturers. The Mumbai-Pune corridor anchors distribution networks serving underpenetrated secondary dental markets.
Periodontal Scalers and Curettes Market Key Industry Players
Top-tier vendors anchor premium hand-crafted positioning, while mid-market distributors compete on procurement consolidation access. The vendor base stratifies across three tiers: heritage manufacturers with century-long stainless steel expertise, integrated dental equipment conglomerates bundling imaging workflows, and distribution-heavy service organizations penetrating Dental Service Organization networks. Two dominant competitive moves define current positioning: backward integration into precision grinding capabilities to offset retiring European toolmakers, and strategic partnerships with third-party sterilization validation specialists to unbundle after-sales service from capital contracts.
Within the heritage manufacturer tier, Hu-Friedy Mfg. Co. LLC exemplifies century-long positioning in hand-finished stainless steel instruments. Dentsply Sirona occupies a position among integrated equipment conglomerates bundling scaling systems with digital imaging platforms. Henry Schein Inc. represents the distribution-heavy archetype, with direct sales force density penetrating mid-market dental service organizations across North American metropolitan corridors.
| Leading Market Players |
|---|
| Hu-Friedy Mfg. Co. LLC |
| Dentsply Sirona |
| Den-Mat Holdings LLC |
| A-dec Inc. |
| Henry Schein Inc. |
| Kerr Corporation |
| Coltene Whaledent Pvt. Ltd. |
| EMS Medical |
| Micron Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-validated reusable portfolios and unvalidated manual instruments manifests in both procurement premiums and supply chain sourcing patterns. Tier-1 manufacturers command price premiums through notified body oversight documentation while commodity producers compete on spot inventory availability in capital-constrained markets.
Pricing Analysis
Short lead-time availability commands substantial premiums as Dental Service Organizations consolidate procurement calendars around quarterly capital allocation cycles. Three-tier pricing structure across premium, standard, and economy levels separates titanium-alloy validated systems from stainless steel hand-finished instruments and unbranded commodity alternatives. Price differentiation hinges on sterilization cycle validation documentation and ergonomic certification tier. Cost compression in the standard tier is intensifying because nickel price volatility from Indonesian supply disruptions squeezes austenitic stainless producers. Solo practitioners in Germany's master craftsman corridor exhibit lowest price sensitivity, while India's tier-2 clinic networks drive volume through aggressive spot purchasing.
Supply Chain Analysis
Direct-to-clinic channels handle hyperscale Dental Service Organization demand while distributor networks serve fragmented solo practitioner bases across secondary markets. Manufacturing gravity centers on Germany, Switzerland, and the United States for precision grinding capabilities, with India anchoring manual instrument assembly for emerging market price points. Raw material feeds draw from Indonesian nickel, Russian chromium, and Chinese titanium sponge. Single-source vulnerability concentrates in European master craftsman expertise as retiring toolmakers are not replenishing specialized grinding knowledge. Distribution runs through Henry Schein's direct sales force density in North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master craftsman capacity scarcity props pricing power for validated instrument portfolios as European and Japanese grinding expertise retires without replacement. This supply-constrained dynamic favors incumbents with captive precision manufacturing capabilities.
For Market Incumbents: Cement defensible positioning through backward integration into precision grinding capabilities as Stuttgart and Solingen craftsman pools shrink. Acquire sterilization validation specialist firms to unbundle service revenue from capital equipment contracts before Dental Service Organization procurement committees mandate third-party maintenance agreements. Titanium alloy adoption by United States group practices creates margin expansion opportunity for validated lightweight portfolios. For New Entrants and Emerging Players: Capture white-space opportunity in India's tier-2 and tier-3 cities through manual instrument portfolios optimized for capital-constrained clinic budgets and simplified sterilization protocols. Target Maharashtra and Gujarat dental markets with distributor partnerships that bypass established multinational sales force density. Digital workflow integration capabilities represent the most penetrable entry angle as group practices demand ultrasonic-imaging bundled tenders. For Investors and Strategic Acquirers: Re-rating potential sits with precision grinding specialists given EU MDR documentation mandates forcing clinic consolidation around validated device portfolios. Long-term viability over the next decade favors manufacturers with notified body relationships and established post-market surveillance infrastructure. Watch for inflection signals in Dental Service Organization RFP language shifting from upfront equipment discounts toward total cost of ownership transparency requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Grinding | Captures retiring European craftsman expertise before capacity exits permanently. |
| Third-Party Sterilization Validation Partnership | Unbundles service revenue streams as Dental Service Organizations demand transparency. |
| Titanium Alloy Portfolio Expansion | Addresses ergonomic liability calculations entering malpractice coverage assessments. |
| Digital Workflow Platform Integration | Bundles ultrasonic scaling with intraoral imaging to meet group practice tender requirements. |
| EU MDR Documentation Investment | Creates competitive moat through notified body-validated reprocessing instruction overhauls. |
Research Approach
Multi-period observation of instrument procurement patterns, sterilization protocol adoption curves, and regulatory clearance timelines anchored the trend analysis, supplemented by interviews with periodontal specialists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare procedure reimbursement data, and dental equipment customs records. Bottom-up clinic procurement surveys triangulated against top-down manufacturer shipment estimates.
Input-output matrix modeling connected raw material cost drivers through manufacturing value-add stages to end-user pricing across product type, material, and end-user segmentation dimensions. CAGRs were derived from regression analysis of historical procedure volume correlations with demographic penetration patterns. Forecast inputs incorporated titanium alloy adoption elasticity, Dental Service Organization consolidation velocity, and EU Green Deal circular economy directive implementation timelines across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to master craftsman retirement rates, nickel supply disruption persistence, and single-use device taxation passage in European parliaments. Projections reflect documented assumptions regarding sterilization validation cost trajectories and group practice procurement centralization speed. Periodic stress-testing of base assumptions against regulatory filing delays and commodity price spike scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Implants Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Dental Implants Market
Dental Devices
Dental Contouring Market
Dental Devices
Dental Caries Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental CAD Market
Dental Devices
Global Periodontal Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Dental Irrigation Devices Market