
 Global Cartilage Repair-Cartilage Regeneration Market | 2026-2036
Global Cartilage Repair-Cartilage Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cartilage Repair-Cartilage Regeneration Market Foresight
Sports injury recovery is expanding as a priority application within cartilage repair, drawing investment from orthopedic device manufacturers and regenerative medicine platforms. Smith & Nephew plc leverages its sports medicine portfolio to anchor positions in arthroscopic delivery systems for cartilage procedures. Zimmer Biomet competes through specialized biologics divisions focused on osteochondral allograft solutions. Stryker Corporation extends its reach via integrated operating room technologies that support matrix-induced autologous chondrocyte implantation workflows.
Cartilage repair and regeneration encompasses surgical and biological interventions that restore articular hyaline cartilage using autologous cells, scaffolds, or growth factors to achieve load-bearing joint surfaces. These procedures typically target chondral defects measuring 1–10 cm² in the knee, ankle, or hip, with hyaline-like tissue formation requiring 12–24 months for functional maturation. Cell-based therapy dominates current clinical practice, though scaffold-based regeneration represents the fastest-growing segment as resorbable collagen and hyaluronic acid matrices improve cell retention and reduce revision rates. Injectable hydrogels command premium positioning due to minimally invasive delivery potential, while microfracture remains a mature, cost-constrained option with inferior long-term durability.
FDA biologics regulations and EMA advanced therapy medicinal product frameworks shape product development timelines and commercial access across the United States and European markets. ISO 13485 quality management standards and WHO tissue banking guidelines further govern manufacturing consistency and allograft sourcing integrity. Stakeholders must monitor evolving reimbursement decisions for cell-based interventions by CMS and national health technology assessment bodies, as coverage determinations will dictate adoption velocity irrespective of clinical efficacy gains.
Market Dynamics
Cell-based therapy manufacturing is automating at scale, compressing production timelines for autologous chondrocyte implantation while FDA and EMA streamline advanced therapy medicinal product pathways. This automation push is redrawing competitive boundaries between centralized bioreactor facilities and distributed tissue processing networks.
Growth Catalysts
- EMA Advanced Therapy Medicinal Product Framework:The centralized EU procedure accelerates market access for cell-based cartilage therapies across Germany, France, and Italy. Manufacturers gain predictable review timelines.
- Sports Medicine Infrastructure:Professional athlete rehabilitation protocols now mandate biological joint restoration over arthroplasty for defects under 10 cm². This clinical preference drives hospital procurement.
- Injectable Hydrogel Platforms:Minimally invasive delivery systems reduce operating room time and enable outpatient procedures. Orthopedic clinics in the United States are converting surgical suites to accommodate same-day cartilage repair.
Market Restraints
- Allograft Supply Concentration:Osteochondral graft sourcing depends on a limited network of accredited tissue banks in the United States and Germany. Donor availability fluctuates seasonally.
- CMS Reimbursement Uncertainty:Medicare coverage determinations for autologous cell therapies remain inconsistent across US hospital referral regions. Payers classify many procedures as experimental.
- Microfracture Cost Floor:The mature bone marrow stimulation technique anchors pricing expectations at levels that undercut biological regeneration margins. Health systems default to cheaper options.
Strategic Opportunities
- Japan's Regenerative Medicine Safety Law:Conditional approval pathways enable earlier commercialization for cell therapies meeting surrogate endpoints. Manufacturers can generate real-world evidence post-launch.
- Veterinary Orthopedics:Equine and companion animal cartilage repair represents an underserved application with premium pricing tolerance. Regulatory barriers are lower than human medicine.
- 3D Bioprinting Convergence:Integration of patient-specific imaging, bioink formulation, and robotic deposition enables custom scaffold geometries. Academic medical centers are piloting point-of-care manufacturing.
Industry Challenges
- Cell Culture Technician Shortage:GMP-compliant bioprocessing expertise is scarce in orthopedic device companies transitioning to biologics. Training programs cannot scale fast enough.
- ISO 13485-to-GMP Facility Overlap:Manufacturers must maintain dual quality systems for device and cell therapy operations. Audit complexity multiplies compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cartilage Repair-Cartilage Regeneration Market |
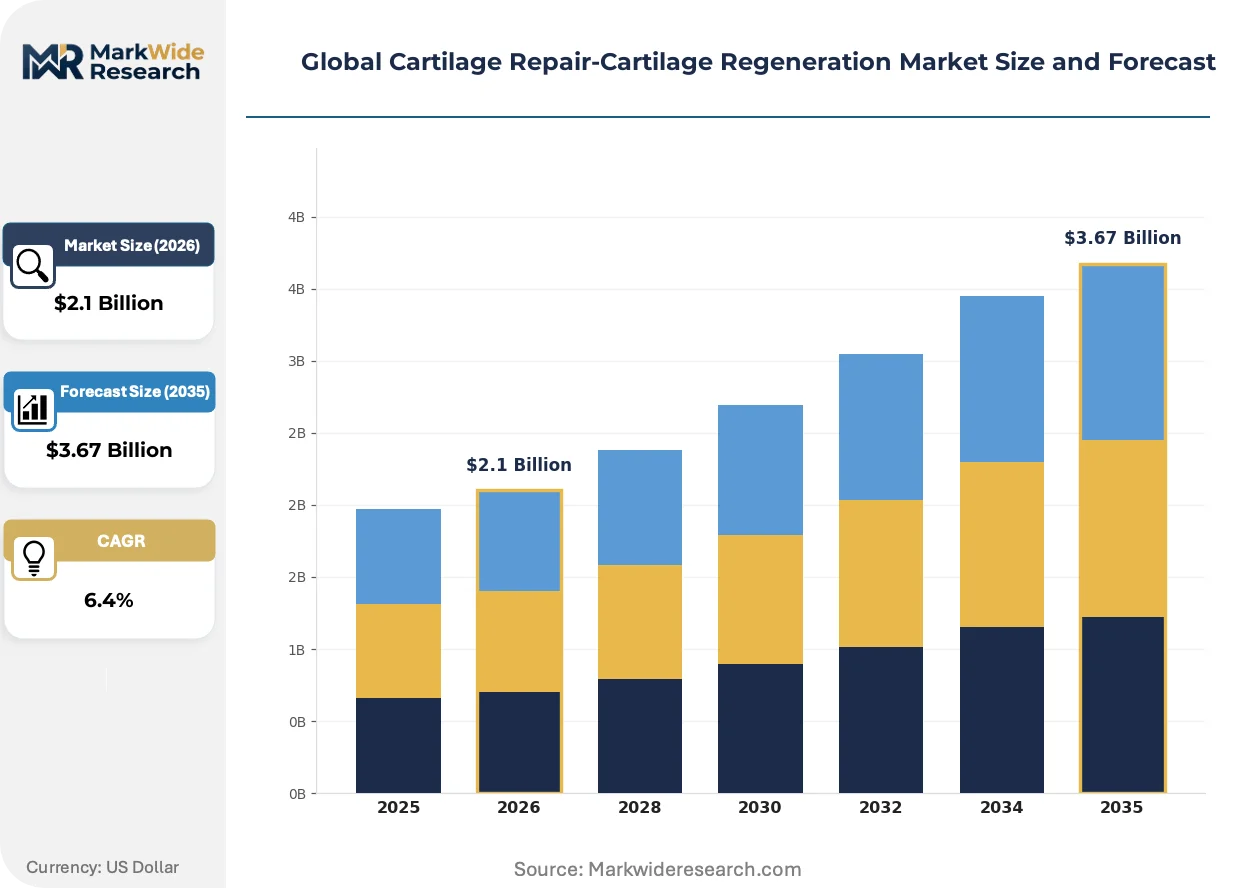
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Chondrocyte Implantation, Microfracture, Osteochondral Autograft Transplantation, Matrix-induced Autologous Chondrocyte Implantation, Injectable Hydrogels Application: Osteoarthritis Treatment, Sports Injury Recovery, Traumatic Cartilage Defects, Degenerative Joint Disease, Joint Reconstruction End User: Orthopedic Clinics, Ambulatory Surgical Centers, Regenerative Medicine Centers, Physical Therapy Providers, Specialized Sports Facilities Technology: Cell-based Therapy, Tissue Engineering, Scaffold-based Regeneration, Gene Therapy, Biomaterial Implants |
| Companies Covered | Smith & Nephew plc, Zimmer Biomet, DePuy Synthes, Stryker Corporation, Vericel Corporation, Arthrex, Inc., Anika Therapeutics, CONMED Corporation, AlloSource, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cartilage Repair-Cartilage Regeneration Market Shifts & Advancements
Bioreactor automation is collapsing the cost structure of autologous chondrocyte expansion, enabling decentralized processing closer to surgical sites. This shift is attracting orthopedic device manufacturers into biologics manufacturing.
Single-use bioreactor systems are automating cell expansion for cartilage repair therapies, eliminating open-culture contamination risks. Mid-size orthopedic companies lacking in-house bioprocessing expertise are licensing automated platform technologies from contract manufacturers. This automation is compressing the 4-6 week autologous cell expansion cycle toward 2-3 weeks, reducing patient dropout between biopsy and implantation.
REACH registration requirements for novel scaffold polymers are forcing European manufacturers toward established biomaterial chemistries. Collagen and hyaluronic acid formulations with existing dossiers gain preference over synthetic alternatives. German orthopedic suppliers are consolidating around resorbable matrices with demonstrated biodegradation profiles to avoid lengthy substance authorization timelines.
Hospital value analysis committees now require health economic evidence for cartilage repair technologies, displacing surgeon preference as the primary purchase determinant. US academic medical centers are piloting bundled payment models that reward durable functional outcomes at 24 months. This procurement evolution favors suppliers with longitudinal patient registry data over those with only short-term clinical trial endpoints.
Global Cartilage Repair-Cartilage Regeneration Market Segmentation
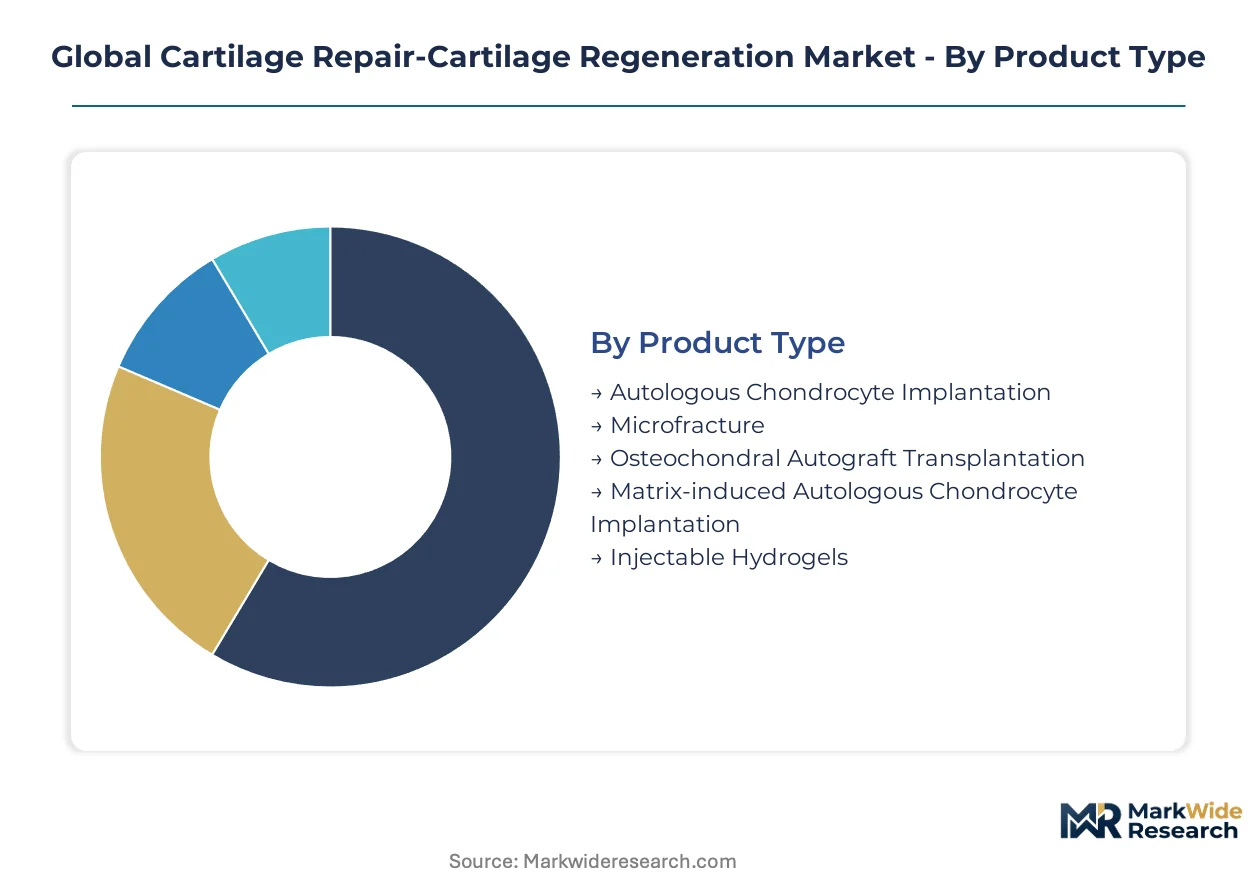
Cartilage repair technologies span standalone surgical interventions and integrated bioprocessing workflows, with segmentation revealing where capital equipment investments concentrate versus where consumable platforms dominate. Understanding these integration patterns clarifies procurement cycles and margin structures across the value chain.
Product Type:
Standalone cartilage repair procedures anchor hospital orthopedic departments, while embedded bioprocessing systems are reshaping ambulatory surgical economics through decentralized cell expansion.
- Autologous Chondrocyte Implantation:Two-stage surgical protocol requiring arthroscopic biopsy followed by cultured cell implantation after 4–6 week expansion. Demand clusters in Germany and the United States where EMA centralized procedures and CMS regional coverage determinations create divergent access patterns.
- Injectable Hydrogels:Single-session delivery of crosslinked collagen or hyaluronic acid matrices bearing autologous or allogeneic cells. Orthopedic clinics in the United States are converting surgical suites to accommodate same-day procedures, compressing revenue per case but expanding patient throughput.
- Microfracture:Mature bone marrow stimulation technique using awl perforation of subchondral bone.
- Osteochondral Autograft Transplantation:Mosaicplasty procedure harvesting cylindrical plugs from non-weight-bearing joint surfaces.
- Matrix-induced Autologous Chondrocyte Implantation:Third-generation cell therapy combining scaffold matrices with expanded chondrocytes.
Volume placements concentrate in Autologous Chondrocyte Implantation; the faster expansion belongs to Injectable Hydrogels.
Application:
Cost tier differentiation separates acute traumatic interventions reimbursed through surgical codes from chronic disease management competing against pharmacological alternatives.
- Sports Injury Recovery:Biological joint restoration protocols for professional and elite amateur athletes with defects under 10 cm². Professional sports franchises in the United States and football clubs in Germany now mandate cartilage preservation over arthroplasty for career-extending outcomes.
- Osteoarthritis Treatment:Early-intervention biological approaches targeting cartilage defects preceding end-stage joint failure. Academic medical centers in the United States are piloting bundled payment models that reward 24-month functional durability, favoring suppliers with longitudinal registry data.
- Traumatic Cartilage Defects:Acute injury repair from falls, vehicular accidents, or occupational trauma.
- Degenerative Joint Disease:Progressive cartilage loss management competing against hyaluronic acid injections and eventual arthroplasty.
- Joint Reconstruction:Adjunct biological procedures combined with ligament repair or osteotomy.
Surgical reimbursement codes concentrate volume in Sports Injury Recovery; steepest expansion trajectory appears in Osteoarthritis Treatment as payers seek alternatives to joint replacement.
End User:
Customer type segmentation tracks capital intensity, with hospital-based orthopedic clinics absorbing high fixed costs while ambulatory settings prioritize disposable platform economics.
- Orthopedic Clinics:Hospital-affiliated or independent practices performing 100+ cartilage procedures annually. United States metropolitan markets show consolidation toward multi-specialty groups capturing professional athlete referrals and workers' compensation cases.
- Ambulatory Surgical Centers:Outpatient facilities converting to same-day cartilage repair through minimally invasive platforms. Lower overhead structures enable competitive pricing against hospital outpatient departments.
- Regenerative Medicine Centers:Specialized facilities combining cell processing with surgical delivery.
- Physical Therapy Providers:Post-operative rehabilitation and conservative management settings.
- Specialized Sports Facilities:Team-affiliated medical centers and high-performance training institutes.
Procedure economics concentrate volume in Orthopedic Clinics; Ambulatory Surgical Centers are climbing the fastest as site-of-service shifts accelerate.
Technology:
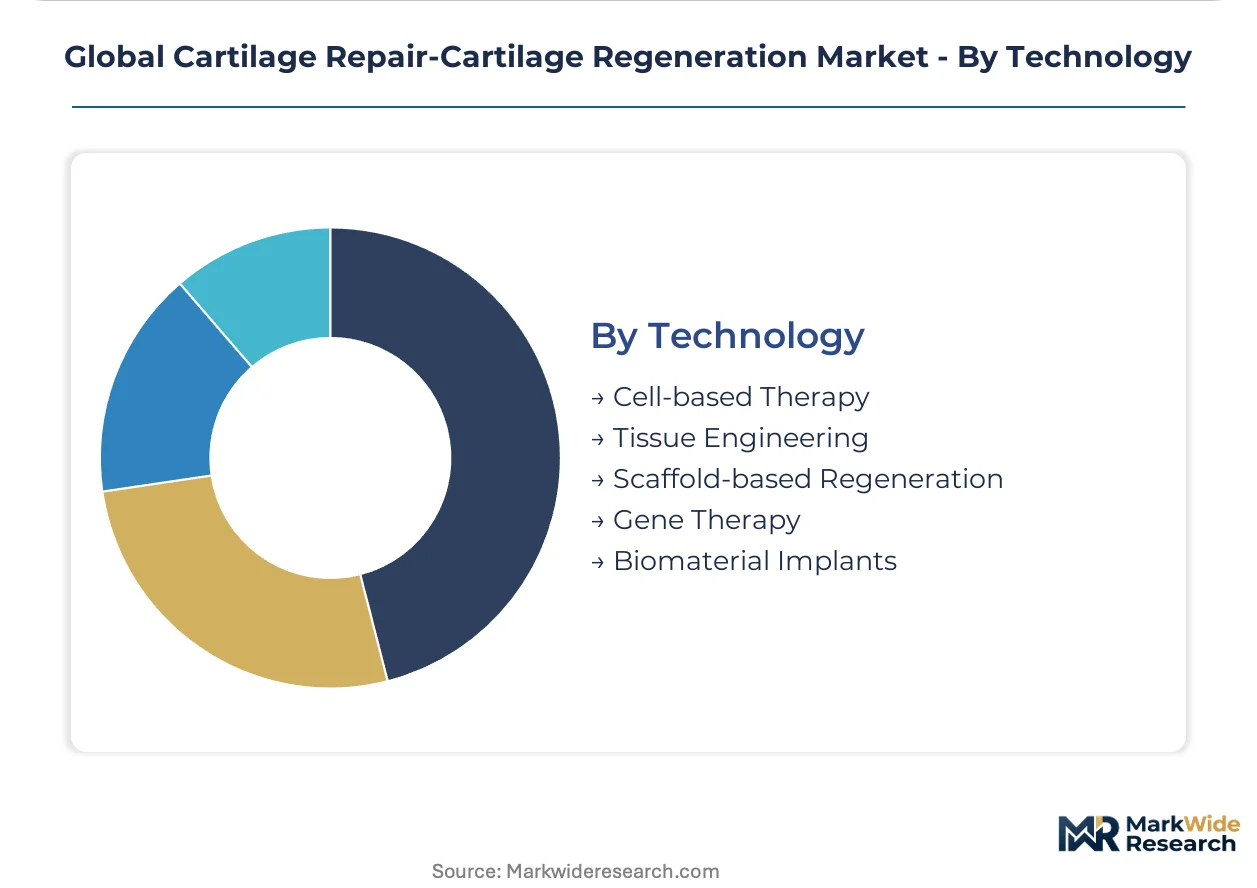
Maturity curves separate established cell-based platforms from emerging modalities still navigating regulatory validation.
- Cell-based Therapy:Autologous and allogeneic chondrocyte products expanded under GMP conditions. FDA biologics regulations and EMA advanced therapy medicinal product frameworks govern manufacturing consistency and commercial access across the United States and European markets.
- Scaffold-based Regeneration:Resorbable collagen and hyaluronic acid matrices improving cell retention and reducing revision rates. REACH registration requirements are forcing European manufacturers toward established biomaterial chemistries with existing dossiers.
- Tissue Engineering:Bioreactor-expanded cells combined with three-dimensional matrices.
- Gene Therapy:Viral vector delivery of growth factors or transcription factors to enhance chondrogenesis.
- Biomaterial Implants:Synthetic or natural polymer scaffolds without cellular components.
Clinical adoption concentrates in Cell-based Therapy; Scaffold-based Regeneration is gaining share fastest as manufacturing automation compresses cost structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States, while consumption concentrates in markets with high orthopedic procedure volumes and favorable reimbursement frameworks. Japan and South Korea are emerging as production hubs for automated bioprocessing equipment.
United States
Professional sports franchises and workers' compensation systems drive biological joint restoration demand for defects under 10 cm². FDA biologics regulations govern autologous chondrocyte implantation pathways, with CMS regional coverage determinations creating divergent access patterns across hospital referral regions. Boston and San Diego academic medical centers pilot bundled payment models rewarding 24-month functional durability.
Germany
Football club medical departments mandate cartilage preservation over arthroplasty for career-extending outcomes among elite athletes. EMA centralized procedures accelerate market access for cell-based therapies under advanced therapy medicinal product frameworks. The Rhine-Ruhr and Bavarian orthopedic clusters concentrate bioreactor manufacturing and GMP-compliant cell expansion facilities.
Japan
Aging demographics and rising sports participation expand the candidate pool for regenerative interventions targeting early-stage osteoarthritis. PMDA conditional approval pathways under the Regenerative Medicine Safety Law enable earlier commercialization for therapies meeting surrogate endpoints. Tokyo and Osaka metropolitan areas host specialized regenerative medicine centers combining cell processing with arthroscopic delivery.
Switzerland
Swissmedic oversight of advanced therapy medicinal products attracts biologics manufacturers seeking predictable regulatory timelines. Precision manufacturing capabilities in the Basel and Zurich regions support scaffold polymer production and medical device assembly. Private sports medicine clinics in Geneva and Lausanne serve professional athlete populations with premium-priced biological restoration protocols.
United Kingdom
NHS England specialized commissioning frameworks determine access to autologous cell therapies for traumatic cartilage defects. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards while enabling national flexibility. London teaching hospitals and Manchester orthopedic centers concentrate clinical trial activity for matrix-induced chondrocyte implantation procedures.
Global Cartilage Repair-Cartilage Regeneration Market Competitive Landscape
Top-tier vendors anchor the premium biologics segment, while mid-scale orthopedic device manufacturers compete through scaffold-based platforms and automated delivery systems. The vendor base stratifies across three tiers: integrated multinational conglomerates with sports medicine portfolios, specialized regenerative medicine pure-plays, and emerging contract manufacturers offering bioprocessing services. Strategic archetypes include bioreactor automation specialists, allograft tissue banks with captive supply networks, and point-of-care cell processing platforms. M&A activity concentrates on biologics capability acquisition, while geographic expansion targets Japan's conditional approval pathway and Germany's EMA centralized procedures.
Among UK- and Ireland-based conglomerates, Smith & Nephew plc represents the integrated sports medicine archetype, while Stryker Corporation exemplifies the operating room technology integrator. Zimmer Biomet occupies a position within the specialized biologics division tier, reflecting the orthopedic device-to-biologics transition pattern visible across the competitive set.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Zimmer Biomet |
| DePuy Synthes |
| Stryker Corporation |
| Vericel Corporation |
| Arthrex, Inc. |
| Anika Therapeutics |
| CONMED Corporation |
| AlloSource |
| Others |
Supply & Pricing Matrix
Hospital value analysis committees in the United States anchor procurement power, forcing suppliers toward outcome-based contracting models that tie reimbursement to 24-month functional durability metrics rather than upfront device costs.
Pricing Analysis
Margin tightening in cell-based therapy tiers reflects CMS reimbursement inconsistency across hospital referral regions. Three-tier pricing structure across premium biologics, standard scaffolds, and economy microfracture anchors market segmentation. Price differentiation hinges on GMP certification grade and longitudinal registry data depth. Academic medical centers show lowest price sensitivity; ambulatory surgical centers face acute cost compression.
Supply Chain Analysis
Single-source vulnerability sits with accredited tissue banks in the United States and Germany for osteochondral allograft sourcing. Manufacturing draws from collagen suppliers in Switzerland, hyaluronic acid processors in Japan, and bioreactor equipment fabricators in South Korea. Tariff exposure on imported scaffold polymers threatens margin stability. Distribution runs through orthopedic device distributors with hospital system exclusivity arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable hydrogel platforms are displacing two-stage autologous chondrocyte protocols, compressing treatment timelines from weeks to single sessions and rewriting site-of-service economics.
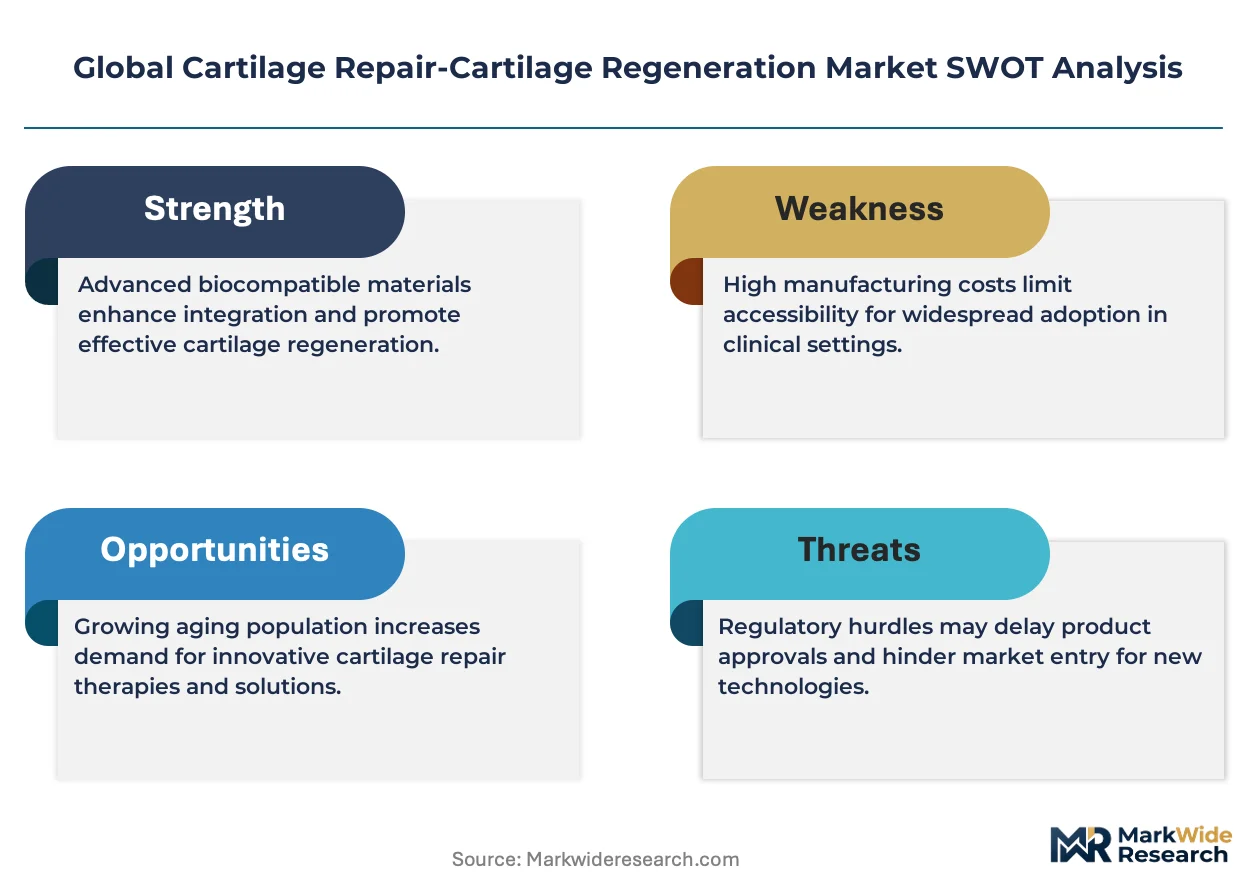
For Market Incumbents: To counter automated bioreactor entrants from contract manufacturers, Smith & Nephew and Zimmer Biomet should deepen backward integration into GMP-compliant cell expansion facilities in Germany's Bavarian cluster while locking hospital system partnerships through bundled outcome contracts. For New Entrants and Emerging Players: Japan's Regenerative Medicine Safety Law opens a window for conditional approval of cell therapies meeting surrogate endpoints, enabling post-launch real-world evidence generation and premium positioning in Tokyo-Osaka metropolitan corridors before EMA centralized procedures. For Investors and Strategic Acquirers: The window for entry favors automated bioprocessing platform specialists with ISO 13485-to-GMP dual quality capabilities, as orthopedic device conglomerates seek biologics manufacturing competence. Watch FDA advanced therapy medicinal product designation velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Automation Partnership | Compresses autologous cell expansion cycles from 4-6 weeks toward 2-3 weeks for orthopedic clinics. |
| EMA Centralized Procedure Navigation | Accelerates market access for cell-based therapies across Germany, France, and Italy under predictable timelines. |
| Hospital System Bundled Contracting | Aligns supplier revenue with 24-month functional outcomes required by US academic medical center pilots. |
| Veterinary Orthopedics Expansion | Captures premium pricing tolerance in equine and companion animal segments with lower regulatory barriers. |
| 3D Bioprinting Pilot Programs | Enables patient-specific scaffold geometries at academic medical centers pioneering point-of-care manufacturing. |
Research Methodology
FDA biologics filings, EMA advanced therapy medicinal product submissions, and CMS coverage determination databases formed the secondary backbone, cross-referenced with primary interviews of GMP facility directors, orthopedic surgeons, hospital purchasing committee members, and regenerative medicine center operators. Bottom-up procedure volume estimates triangulated against top-down market sizing from trade association data and regulatory pipeline tracking.
Bottom-up modeling of autologous chondrocyte implantation, injectable hydrogel, and scaffold-based procedure volumes across the United States, Germany, Japan, Switzerland, and the United Kingdom fed into top-down market validation. Segmentation dimensions included product type, application, end user, and technology maturity tier. CAGRs derived from procedure growth trajectories, reimbursement expansion patterns, and manufacturing automation adoption curves.
Caveats apply where CMS national coverage determinations, EMA advanced therapy medicinal product review timelines, or bioreactor automation scale-up delays could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market