
 Mouthwash Market | 2026-2036
Mouthwash Market Size, Share, and Industry Trends Forecast 2026-2036
Mouthwash Market Intelligence
Multi-pack bundling with travel-size formats is restructuring buyer choice in oral care aisles. Colgate-Palmolive Company leverages its dental professional channel to sustain trial-to-purchase conversion. Haleon plc anchors its portfolio around clinical efficacy claims that differentiate from cosmetic-positioned rivals. Procter & Gamble Company dominates mass retail shelf space through frequency-driving pack sizes.
Mouthwash comprises aqueous oral rinses formulated with antimicrobial agents, essential oils, fluoride, or alcohol at concentrations typically ranging from zero to 26.9 percent, designed to reduce plaque, freshen breath, or deliver therapeutic benefits between brushings. Therapeutic and natural-positioned product types command expanding shelf allocation as consumers migrate from basic cosmetic rinses toward function-forward formulations. Mint and herbal flavors lead volume while citrus variants attract younger adult trial segments seeking differentiated sensorial profiles.
The FDA regulates antiseptic mouthwash active ingredients under its over-the-counter drug monograph system, while EPA standards govern manufacturing effluent for alcohol-based production facilities. State-level professional dental board guidelines in California, Texas, and New York increasingly recommend therapeutic rinses as adjuncts to periodontal protocols, tightening the link between clinical endorsement and consumer purchase. Stakeholders must monitor evolving monograph rulings and professional channel certification requirements to align R&D pipelines with compliance thresholds.
Market Dynamics
The FDA's ongoing antiseptic monograph review is forcing reformulation across alcohol-based and essential oil rinse portfolios, compressing development timelines and elevating clinical validation costs for manufacturers competing on therapeutic positioning.
Growth Catalysts
- Professional dental channel expansion:State dental boards in California, Texas, and New York now recommend therapeutic rinses as periodontal protocol adjuncts, tightening clinical endorsement-to-purchase conversion.
- REACH-compliant natural ingredient pipelines:European suppliers are scaling plant-derived antimicrobial extracts that satisfy EU biocidal product regulations while meeting consumer clean-label preferences.
- Alcohol-free formulation R&D:Advances in cetylpyridinium chloride stabilization are enabling zero-alcohol therapeutic efficacy claims that expand pediatric and sensitive-mouth segments.
Market Restraints
- Active ingredient supply concentration:CPC and essential oil feedstocks cluster among three specialty chemical suppliers in Germany and India, creating input vulnerability.
- FDA monograph uncertainty:Pending rulings on triclosan replacements and essential oil concentration thresholds are freezing pipeline investments.
- Water-based production cost inflation:Purified water and effluent treatment requirements for alcohol-free manufacturing are elevating unit economics versus legacy alcohol bases.
Strategic Opportunities
- India's nascent therapeutic segment:CDSCO's streamlined OTC drug registration for fluoride and CPC formulations opens professional-channel penetration in a cosmetic-dominant market.
- Subscription direct-to-consumer models:Refill-pouch and auto-replenishment platforms bypass retail slotting fees while capturing recurring revenue.
- Biomarker-linked personalization:Salivary diagnostic integration enables condition-specific rinse recommendations, creating premium positioning beyond generic therapeutic claims.
Industry Challenges
- Clinical trial talent scarcity:Gingivitis and plaque reduction studies require specialized dental research coordinators, with qualified CRO capacity concentrated among five US and EU providers.
- Legacy manufacturing retrofit costs:Alcohol-to-alcohol-free line conversions demand stainless steel tank replacement and vapor recovery system installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mouthwash Market |
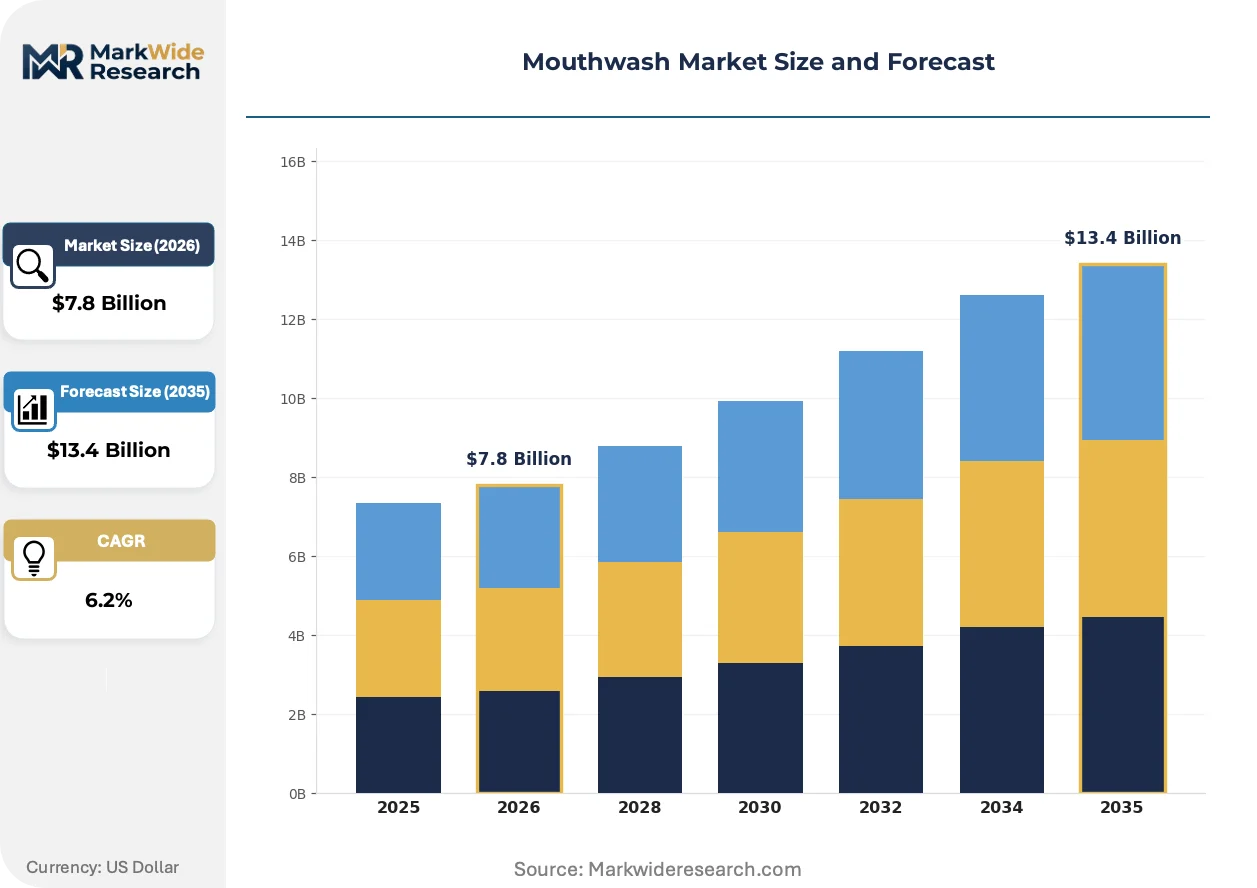
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.4 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic, Therapeutic, Antiseptic, Natural Flavor: Mint, Cinnamon, Citrus, Herbal End User: Adults, Children, Seniors, Professional Use Packaging Type: Bottle, Sachet, Pump, Tube |
| Companies Covered | Haleon plc, Church & Dwight Co., Inc., Colgate-Palmolive Company, Lion Corporation, GlaxoSmithKline plc, Kenvue Inc., Unilever PLC, Kao Corporation, Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mouthwash Market Strategic Shifts & Innovations
Formulation science, regulatory science, and channel economics are converging to compress product development cycles while fragmenting how consumers discover and purchase oral rinses.
Probiotic and postbiotic oral care technologies are consolidating functional positioning in the premium therapeutic tier. Dental professionals in Germany and South Korea are recommending microbiome-balancing rinses ahead of cosmetic alternatives. This adoption pattern is consolidating manufacturer R&D budgets toward live culture stabilization and shelf-life extension rather than traditional antiseptic efficacy benchmarking.
The EPA's revised effluent guidelines for alcohol-based manufacturing facilities are tightening discharge limits for volatile organic compounds. Facilities in Texas and New Jersey face capital expenditure requirements for closed-loop solvent recovery systems. Alcohol-free production lines are gaining preference among contract manufacturers seeking to avoid permitting complexity.
Travel-size and trial-format bundling is restructuring initial purchase behavior in mass retail. Younger adult consumers in the United States are selecting multi-pack assortments over single-unit bottles, compressing per-transaction volume while expanding household penetration. This pattern is most visible in drug and grocery channels where shelf-edge promotional displays drive impulse selection.
Mouthwash Market Segmentation
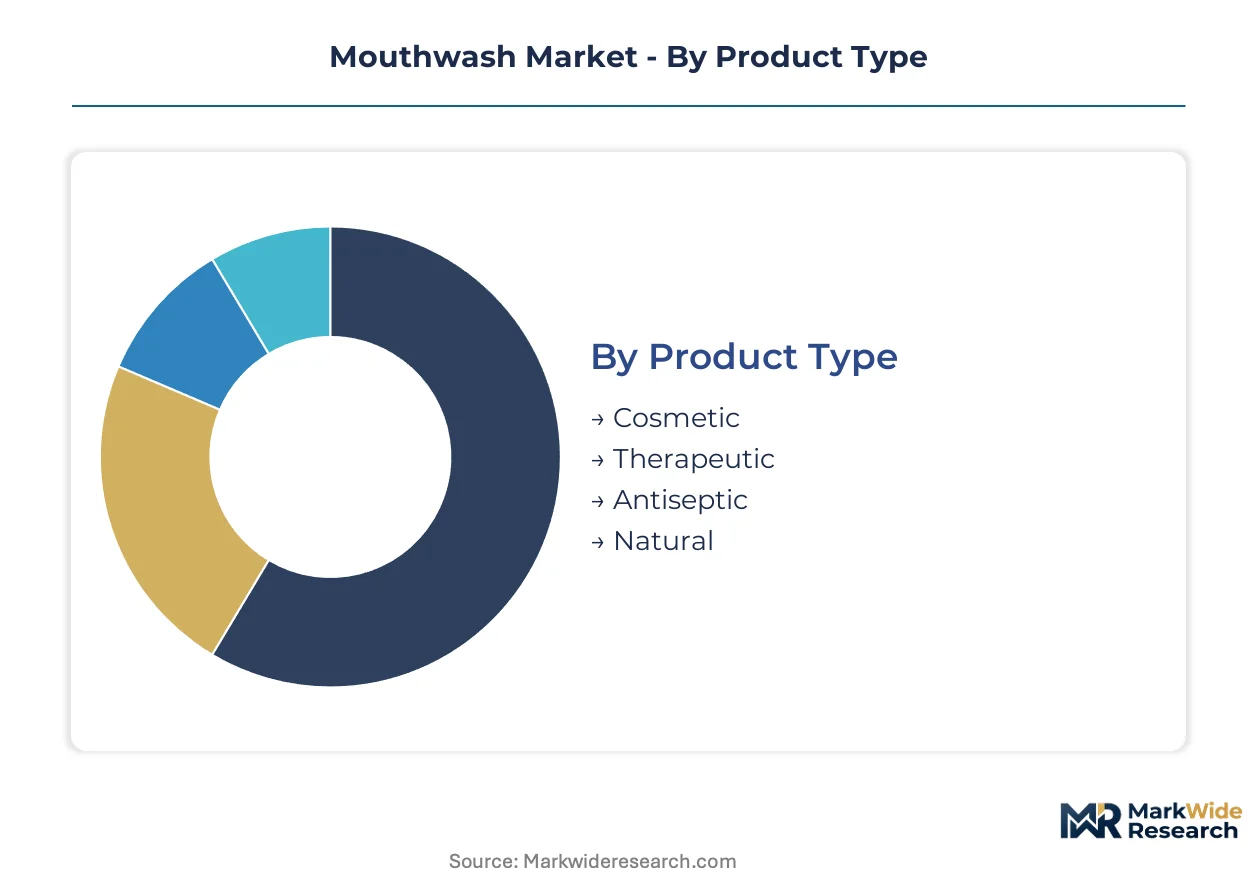
Mouthwash manufacturers calibrate portfolio depth across formulation intensity, sensory preference, and channel access. Each segmentation axis carries distinct margin profiles and regulatory pathways that determine where R&D investment concentrates.
Product Type:
Formulation science distinguishes portfolios along the therapeutic efficacy spectrum, with active ingredient concentration and clinical validation requirements defining manufacturing complexity and price positioning.
- Therapeutic:Fluoride or cetylpyridinium chloride formulations deliver plaque reduction and gingivitis prevention claims requiring FDA monograph compliance. Demand concentrates among professional dental patients in California, Texas, and New York where state board protocols now recommend adjunctive rinse use. Clinical validation costs and pending monograph rulings on concentration thresholds constrain new entrants.
- Natural:Plant-derived antimicrobial extracts and essential oil bases satisfy clean-label preferences while navigating REACH-compliant supply chains from European botanical suppliers. Germany and South Korea dental professionals are recommending microbiome-balancing variants ahead of cosmetic alternatives, consolidating R&D spend toward live culture stabilization.
- Cosmetic:Breath-freshening formulations with minimal active ingredients dominate mass retail volume through lower price points and impulse purchase patterns.
- Antiseptic:High-concentration alcohol or essential oil rinses face EPA effluent scrutiny and reformulation pressure as alcohol-free alternatives gain manufacturing preference.
Mature deployment sits with Cosmetic formulations. Newer deployment is concentrated in Natural and Therapeutic segments.
Flavor:
Sensory differentiation drives trial conversion and repurchase frequency, with generational and regional taste preferences fragmenting SKU proliferation strategies.
- Mint:Dominant volume driver across all channels with established consumer acceptance and professional endorsement. Peppermint and spearmint variants anchor core shelf space allocation.
- Citrus:Lemon, lime, and grapefruit profiles attract younger adult trial segments seeking differentiated sensorial experiences beyond traditional oral care conventions.
- Cinnamon:Seasonal and niche positioning with concentrated demand in North American markets during holiday promotional periods.
- Herbal:Eucalyptus, tea tree, and chamomile formulations align with natural-positioned therapeutic claims and expanding clean-label portfolios.
Volume leadership rests with Mint. Citrus and Herbal variants are climbing the fastest as younger demographics and natural-positioned consumers shift preferences.
End User:
Demographic targeting determines formulation safety profiles, alcohol content thresholds, and channel distribution priorities.
- Adults:Broadest addressable segment spanning cosmetic through therapeutic needs with full flavor and formulation range availability across all retail channels.
- Children:Alcohol-free and low-fluoride formulations with flavor profiles calibrated to pediatric palatability drive specialized SKU development and parental safety certification requirements.
- Seniors:Dry mouth and sensitive gum formulations with reduced alcohol content address age-related oral condition prevalence and medication interaction concerns.
- Professional Use:Pre- and post-procedural rinses with elevated antimicrobial concentration distributed through dental supply channels and clinical endorsement protocols.
Established penetration centers on Adults. Professional Use and Children segments are expanding most quickly through channel specialization and safety-formulation innovation.
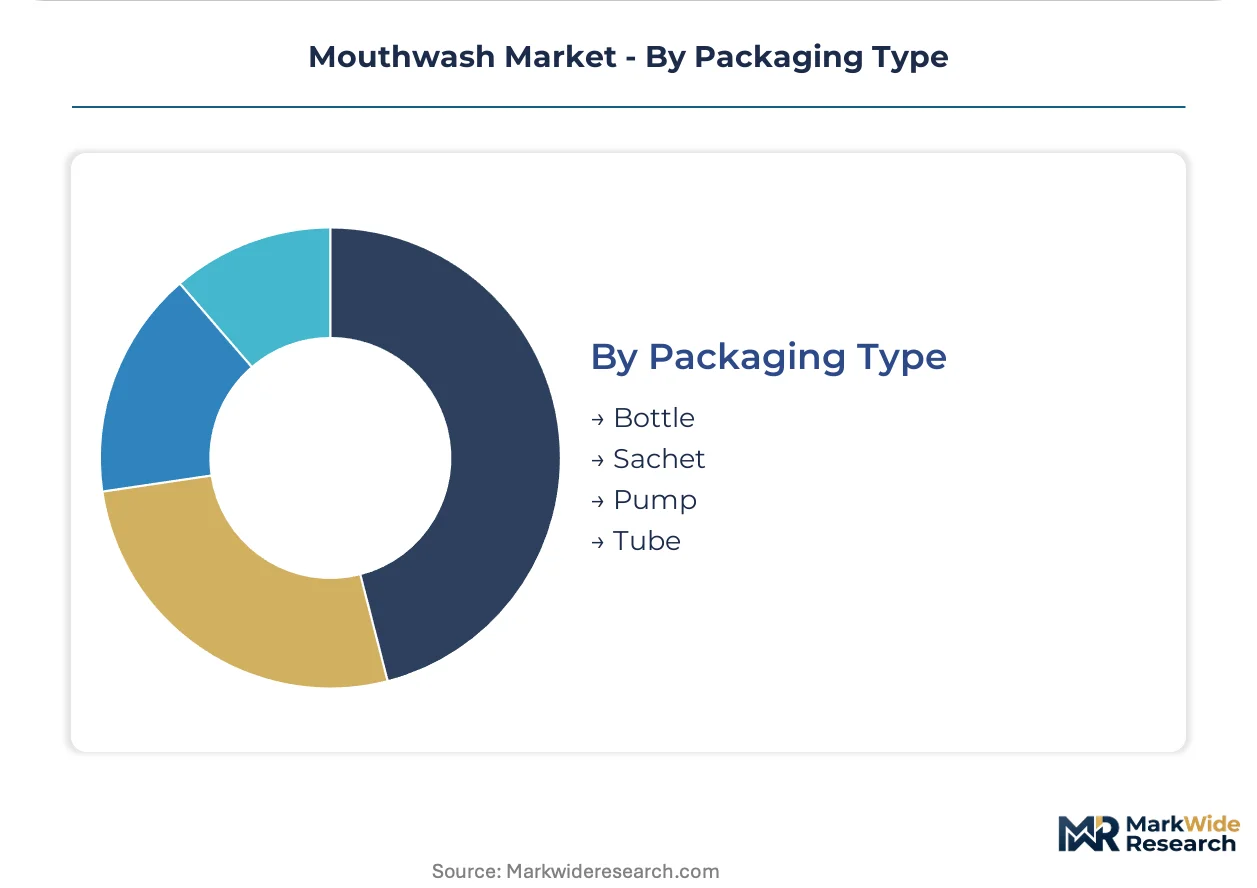
Packaging Type:
Format engineering shapes consumption occasion, retail economics, and sustainability positioning across home, travel, and clinical environments.
- Bottle:Standard 500ml to 1-liter containers dominate household stock-up purchases with pump and screw-cap closure variants optimizing bathroom counter storage and controlled dispensing.
- Sachet:Single-use foil and film packets enable trial sampling, travel convenience, and emerging market unit affordability with minimal packaging material per dose.
- Pump:Metered-dose dispensing systems reduce spillage and support precise usage compliance for therapeutic formulations targeting clinical and senior segments.
- Tube:Collapsible aluminum and laminate structures concentrate in professional and travel formats with compact dimensional efficiency for kit and sampler bundling.
Volume concentration remains with Bottle formats. Sachet and Pump deployments are gaining share fastest through subscription direct-to-consumer models and professional channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of alcohol-based mouthwash concentrates in Texas and New Jersey due to legacy chemical manufacturing infrastructure, while consumption tilts toward coastal states with higher dental professional density and clean-label preference intensity.
United States
State dental boards in California, Texas, and New York now recommend therapeutic rinses as periodontal protocol adjuncts, tightening clinical endorsement-to-purchase conversion. The FDA's ongoing antiseptic monograph review is forcing reformulation across alcohol-based portfolios, compressing development timelines for manufacturers. Manufacturing clusters in New Jersey and Texas face EPA effluent guideline tightening for volatile organic compound discharge limits.
Germany
Dental professionals in Germany are recommending microbiome-balancing rinses ahead of cosmetic alternatives, consolidating manufacturer R&D budgets toward live culture stabilization. REACH-compliant supply chains from European botanical suppliers are scaling plant-derived antimicrobial extracts. The ECHA biocidal product regulations govern essential oil concentration thresholds for natural-positioned therapeutic claims.
India
CDSCO's streamlined OTC drug registration for fluoride and CPC formulations is opening professional-channel penetration in a cosmetic-dominant market. Urban consumers in Mumbai and Delhi are shifting from basic breath-freshening rinses toward therapeutic variants with clinical validation. Domestic contract manufacturers in Gujarat and Maharashtra are retrofitting alcohol-to-alcohol-free production lines to avoid EPA-equivalent permitting complexity.
South Korea
Dental professionals in Seoul and Busan are adopting probiotic oral care technologies ahead of other Asia-Pacific markets, consolidating functional positioning in the premium therapeutic tier. The MFDS regulates antimicrobial active ingredients under pharmaceutical-grade standards that exceed cosmetic rinse requirements. Manufacturing facilities in the Seoul Capital Area are specializing in zero-alcohol cetylpyridinium chloride stabilization for pediatric and sensitive-mouth segments.
Japan
Consumers in Tokyo and Osaka demonstrate high trial frequency for citrus-flavored variants targeting younger adult segments seeking differentiated sensorial profiles. The PMDA's quasi-drug classification system creates distinct regulatory pathways for therapeutic claims versus cosmetic positioning. Lion Corporation and Kao Corporation anchor domestic production capacity in the Kansai and Kanto industrial corridors.
Mouthwash Market Key Industry Players
The competitive structure tilts toward diversified consumer health conglomerates with dental professional channel access. Three to five multinational players control mass retail shelf space through frequency-driving pack sizes and promotional display investments. Strategic archetypes include dental professional channel specialists, mass retail scale operators, and natural-positioned clean-label innovators. Capacity expansion and portfolio diversification toward alcohol-free therapeutic formulations represent the dominant competitive moves as FDA monograph uncertainty persists.
Among UK-based consumer health specialists, Haleon plc and GlaxoSmithKline plc occupy positions anchored around clinical efficacy claims that differentiate from cosmetic-positioned rivals. Colgate-Palmolive Company exemplifies the dental professional channel archetype, leveraging practitioner relationships to sustain trial-to-purchase conversion. Procter & Gamble Company represents mass retail scale dominance through shelf space control and multi-format bundling strategies.
| Leading Market Players |
|---|
| Haleon plc |
| Church & Dwight Co., Inc. |
| Colgate-Palmolive Company |
| Lion Corporation |
| GlaxoSmithKline plc |
| Kenvue Inc. |
| Unilever PLC |
| Kao Corporation |
| Procter & Gamble Company |
| Others |
Cost & Logistics Intelligence
Cetylpyridinium chloride feedstock costs cascade from three specialty chemical suppliers in Germany and India through therapeutic rinse pricing tiers, compressing margins for alcohol-free formulations while elevating premium positioning for REACH-compliant botanical extracts.
Pricing Analysis
Margin tightening in therapeutic tiers reflects FDA monograph uncertainty freezing pipeline investments and concentrating clinical validation spend among established players. Three-tier pricing structure across premium, standard, and economy levels separates fluoride-CPC formulations with professional endorsement from essential oil variants and basic breath-freshening cosmetic rinses. Price differentiation hinges on certification grade and volume scale, with subscription auto-replenishment platforms capturing least price-sensitive households while mass retail sachet formats attract emerging market cost-conscious trial. Cost-down pressure on standard tiers accelerates because contract manufacturers in Gujarat and Maharashtra are retrofitting alcohol-to-alcohol-free lines, elevating unit economics versus legacy alcohol bases.
Supply Chain Analysis
Regional distribution centers in New Jersey and Texas anchor hub-and-spoke patterns for alcohol-based production, while alcohol-free manufacturing gravitates toward contract facilities seeking EPA permitting simplicity. Supply concentrates in Germany for REACH-compliant botanical extracts, India for CPC and essential oil feedstocks, and South Korea for zero-alcohol cetylpyridinium chloride stabilization technologies. Raw material dependencies span purified water systems, stainless steel tank infrastructure, and live culture stabilization inputs for probiotic formulations. Single-source vulnerability sits with the three specialty chemical suppliers controlling antimicrobial active ingredient feedstocks. Distribution runs through dental professional channels, mass retail drug and grocery, and emerging subscription direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents and challengers are racing to secure captive supply of REACH-compliant botanical extracts and clinical trial capacity, with backward integration into European botanical suppliers and dental research coordinator networks determining who captures premium therapeutic positioning.
For Market Incumbents: To counter FDA monograph uncertainty freezing pipeline investments, secure exclusive capacity with the five US and EU clinical research organizations qualified for gingivitis and plaque reduction studies. Deepen backward integration into German and Indian specialty chemical suppliers controlling CPC and essential oil feedstocks to insulate input costs from concentration risk. For New Entrants and Emerging Players: Dental supply distributors represent the most accessible channel partner type for bypassing mass retail slotting fee barriers. Target India's nascent therapeutic segment where CDSCO streamlined OTC registration creates professional-channel penetration opportunity in a cosmetic-dominant market. Lead with biomarker-linked personalization and salivary diagnostic integration to differentiate beyond generic therapeutic claims. For Investors and Strategic Acquirers: CDSCO regulatory filings for fluoride and CPC formulations in India is the leading indicator that professional-channel penetration is accelerating in historically cosmetic-dominant geographies. Over the medium-term horizon, prioritize acquisition targets with live culture stabilization capabilities and REACH-compliant European botanical supply relationships. Watch for EPA effluent guideline enforcement actions against Texas and New Jersey alcohol-based manufacturing facilities as signals of contract manufacturer preference shifts toward alcohol-free production.| Strategic Initiative | Industry Significance |
|---|---|
| Alcohol-Free Formulation Conversion | Retrofitting production lines avoids EPA effluent permitting complexity in Texas and New Jersey. |
| Professional Channel Certification | State dental board protocol alignment in California, Texas, and New York tightens endorsement-to-purchase conversion. |
| Subscription Direct-to-Consumer Launch | Refill-pouch platforms bypass retail slotting fees while capturing recurring revenue from households. |
| Probiotic R&D Investment | Live culture stabilization capabilities differentiate premium therapeutic positioning in Germany and South Korea. |
| REACH-Compliant Supply Integration | European botanical supplier relationships secure clean-label antimicrobial extract pipelines for natural-positioned variants. |
Research Approach
SEC 10-K filings, CDSCO registration databases, and EPA effluent compliance records formed the secondary backbone, cross-referenced with primary interviews involving brand managers at consumer health conglomerates, category buyers at drug and grocery retailers, dental supply channel sales heads, and formulation scientists at contract manufacturers. Bottom-up volume modeling across therapeutic, natural, cosmetic, and antiseptic product types triangulated against top-down market sizing from trade flow analysis.
Historical trendline analysis of professional recommendation patterns and regulatory filing velocities anchored the projection framework across the analysis window. Segmentation dimensions spanned formulation intensity, flavor preference, end-user demographic, and packaging format, with CAGRs derived from elasticity modeling of dental patient adoption curves and channel shift velocities. Forecast inputs incorporated FDA monograph ruling timelines and state dental board protocol evolution patterns.
Several conditions sit outside the modeled scope, including pending EPA effluent guideline finalization, CDSCO regulatory interpretation shifts, and breakthrough microbiome science invalidating current antiseptic efficacy benchmarks. Forecasts reflect documented assumptions around professional endorsement conversion rates and clean-label preference stickiness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Europe Oral Hygiene Market
Oral Care
Oral Mucositis Market
Oral Care
Baby Oral Care Market
Oral Care
Oral Hygiene Products Market
Oral Care
South America Oral Care Market
Oral Care
North America Oral Care Market
Oral Care
Europe Oral Care Market
Oral Care
Toothcare Market
Oral Care
Oral Irrigator Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Oral Thrush Market
Oral Care
Tongue Cleaner Market
Oral Care
Global Halitosis Market
Oral Care
Canker Sores Treatment Market