
 Canker Sores Treatment Market | 2026-2036
Canker Sores Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Canker Sores Treatment Market Insights
CE marking under the EU Medical Device Regulation is restructuring the cost-of-entry calculus for canker sore treatment manufacturers seeking European market access. Pfizer sustains competitive advantage through its established prescription-to-OTC transition capabilities in oral therapeutics. GlaxoSmithKline anchors its position via deep integration with pharmacy and dental professional channels across multiple continents. Colgate-Palmolive leverages its consumer oral care brand equity to dominate shelf space in mass retail environments.
Canker sores treatment encompasses pharmacological and supportive interventions designed to reduce pain, accelerate mucosal healing, and prevent secondary infection in recurrent aphthous stomatitis, typically formulated with active ingredients such as benzocaine, hydrocortisone, or hyaluronic acid in bioadhesive gel matrices. The primary commercial purpose centers on enabling rapid symptomatic relief without clinical intervention, thereby reducing healthcare system burden and supporting patient autonomy in managing minor oral ulcerative conditions. Topical medication occupies the largest revenue share within product type segmentation due to immediate consumer accessibility and established efficacy profiles, while prescription treatment represents the fastest-expanding category as clinicians increasingly adopt corticosteroid-based protocols for severe recurrent cases. Oral gel formulations command superior margin pools compared to mouth rinse alternatives, reflecting higher per-unit pricing and stronger patient compliance metrics in chronic management scenarios.
FDA OTC monograph compliance requirements shape product formulation standards and labeling claims for the US market, while EMA medical device and medicinal product borderline determinations govern European commercialization pathways. India's CDSCO and BIS frameworks impose additional testing protocols on imported oral care therapeutics, creating differentiated regulatory burdens across manufacturing locations. Stakeholders must monitor evolving OTC classification precedents and regional pharmacovigilance reporting obligations to anticipate competitive repositioning and compliance cost shifts.
Market Dynamics
Consumer self-treatment preferences are redirecting prescription-grade formulations toward over-the-counter channels, forcing manufacturers to restructure clinical validation pathways and retail packaging strategies simultaneously.
Growth Catalysts
- EMA Medical Device Regulation:Streamlined borderline determinations between medicinal products and medical devices accelerate European market entry for bioadhesive gel formulations.
- Retail pharmacy chains:Expanded private-label oral care portfolios create shelf-space competition that drives formulation innovation and price accessibility.
- Direct-to-consumer channels:Premium shelf placement in United States health product e-commerce strengthens repeat purchase mechanics for topical analgesic gels.
Market Restraints
- API cost volatility:Benzocaine and hydrocortisone active pharmaceutical ingredients face supply concentration in Indian and Chinese chemical manufacturing clusters.
- FDA OTC monograph compliance:Labeling claim restrictions limit differentiation opportunities for new entrants seeking rapid symptomatic relief positioning.
- Generic substitution pressure:Established corticosteroid protocols commoditize prescription treatment segments, compressing margin pools for branded alternatives.
Strategic Opportunities
- Underpenetrated dental professional channels:Clinician adoption of hyaluronic acid protocols in severe recurrent aphthous stomatitis cases opens prescription-adjacent positioning.
- Convergence of bioadhesive matrices with microbiome research:Next-generation formulations targeting oral microbiome balance create premium tier separation from commodity analgesics.
- Subscription-based replenishment models:Chronic management scenarios for recurrent sufferers enable predictable revenue streams through direct-to-consumer platforms.
Industry Challenges
- CDSCO import testing protocols:India's Bureau of Indian Standards frameworks impose differentiated regulatory burdens that extend time-to-market for foreign manufacturers.
- Pharmacovigilance reporting obligations:Evolving regional adverse event tracking requirements demand specialized compliance infrastructure across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canker Sores Treatment Market |
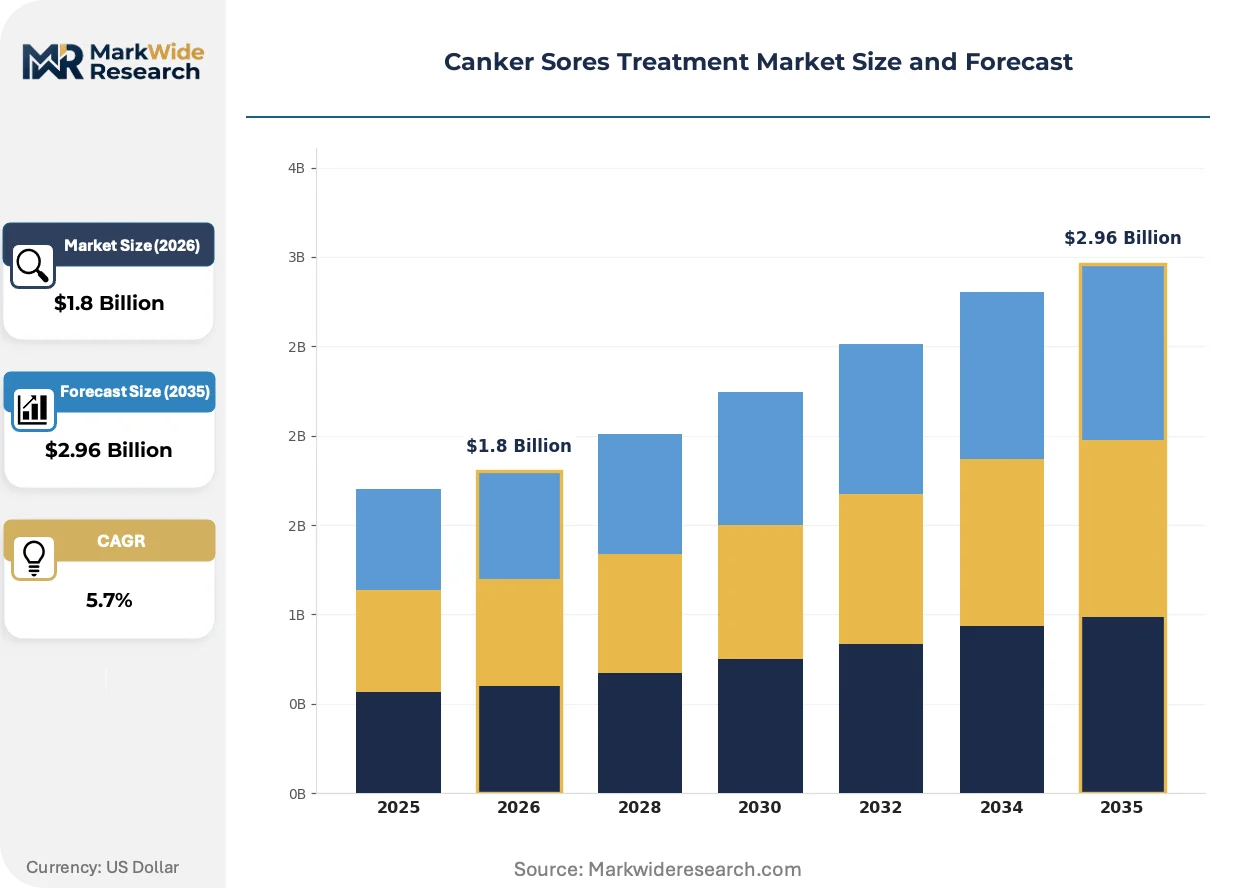
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Medication, Oral Rinse, Oral Gel, Prescription Treatment Delivery Mode: Topical Application, Mouth Rinse, Paste Application, Systemic Treatment End User: Patients, Clinics, Hospitals, Pharmacies Therapy Area: Oral Care, Pain Management, Infection Control, Supportive Care |
| Companies Covered | Colgate-Palmolive, Pfizer, GlaxoSmithKline, 3M Healthcare, Church & Dwight, Blistex, Reckitt Benckiser, Sunstar, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canker Sores Treatment Market Trends and Innovations
Formulation science and channel economics are converging to reshape how mucosal healing products reach end users, with bioadhesive delivery systems and regulatory arbitrage strategies defining competitive advantage.
Hyaluronic acid is integrating into bioadhesive gel matrices as a mucosal repair agent beyond its traditional humectant role. Dental professionals in severe case management protocols are adopting these formulations at accelerating rates. This technology is integrating clinical-grade healing claims into consumer-accessible products, compressing the historical divide between prescription and over-the-counter positioning.
CE marking under the EU Medical Device Regulation is reclassifying previously borderline oral care therapeutics into regulated device categories. Manufacturers must now demonstrate biocompatibility and performance validation under stricter conformity assessment procedures. European market entrants with existing pharmaceutical dossiers face the steepest adaptation costs, while pure-play device specialists capture first-mover positioning.
Self-directed health management is fragmenting traditional pharmacy purchasing patterns into research-intensive online discovery journeys. Mass retail environments are losing traffic to specialized oral health platforms and subscription services that bundle education with product delivery. This behavioral pivot concentrates value capture in the United States, where direct-to-consumer infrastructure and health information accessibility are most developed.
Canker Sores Treatment Market Segmentation
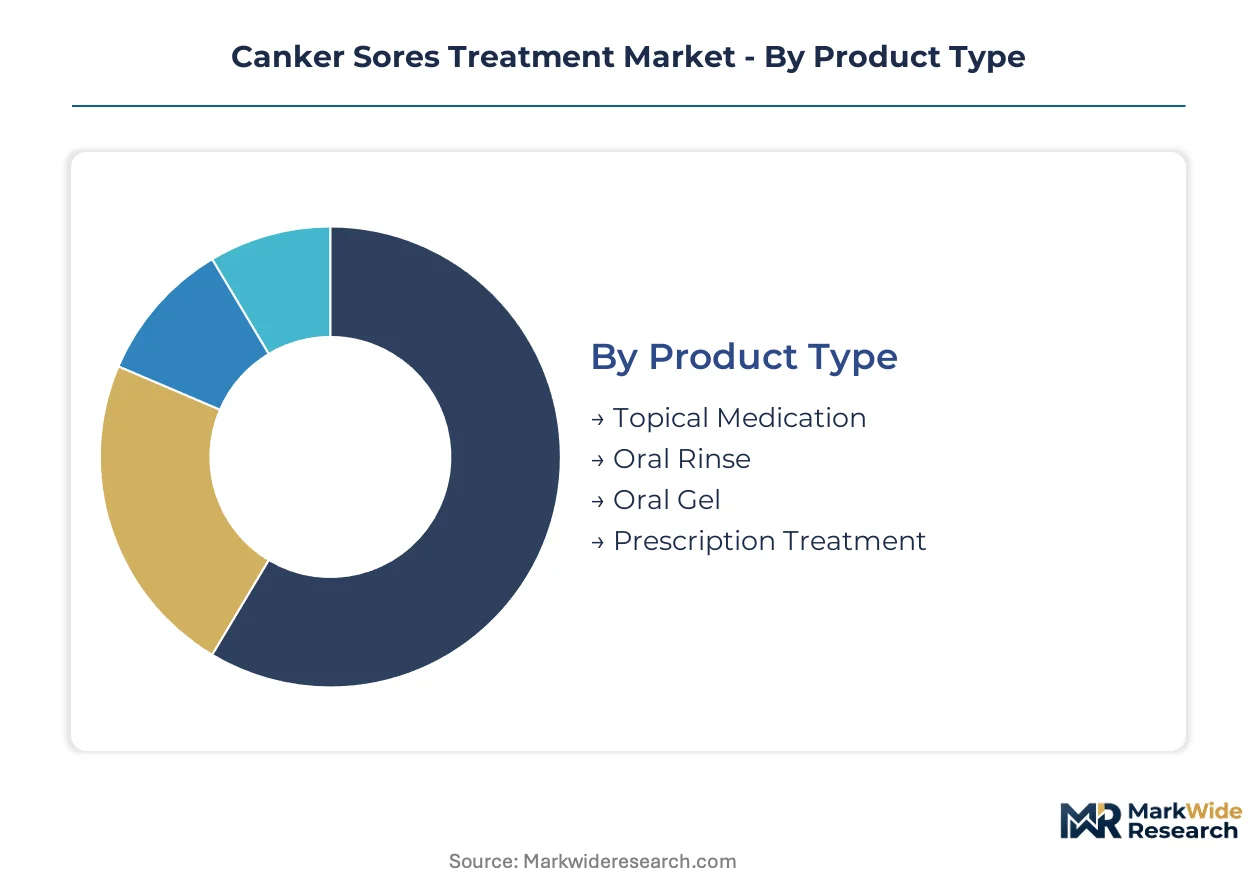
Segmentation in canker sore therapeutics reveals divergent regulatory pathways and margin architectures across formulation types. Each category channels distinct stakeholder economics, from FDA OTC monograph compliance for self-treatment products to prescription-grade corticosteroid protocols requiring clinical oversight.
Product Type:
FDA OTC monograph compliance governs topical analgesics and oral rinses, while prescription treatments face DEA scheduling and clinical trial dossier requirements. CE marking under EU MDR imposes biocompatibility validation on bioadhesive gel formulations regardless of medicinal product status.
- Topical Medication:Benzocaine and hydrocortisone formulations in bioadhesive matrices deliver immediate symptomatic relief through mucosal adhesion. Demand concentrates in United States retail pharmacy chains where private-label expansion compresses branded pricing power. FDA labeling claim restrictions limit differentiation to formulation elegance rather than efficacy positioning.
- Oral Gel:Hyaluronic acid-infused bioadhesive systems command premium tier positioning through mucosal repair claims beyond analgesia. Dental professional channels in Germany and Switzerland drive adoption for severe recurrent aphthous stomatitis protocols. Per-unit pricing exceeds mouth rinse alternatives by substantial margins due to chronic management compliance advantages.
- Oral Rinse:Antiseptic and anesthetic solutions for broad-coverage mucosal contact in acute episode management.
- Prescription Treatment:Corticosteroid-based protocols requiring clinician diagnosis for severe or refractory cases.
Topical medication sits at the top of the volume ranking, with prescription treatment climbing the fastest as clinicians adopt steroid protocols for recurrent sufferers.
Delivery Mode:
Application mechanics determine patient compliance curves and reimbursement eligibility across markets. Direct-to-consumer channels favor low-friction topical formats while systemic treatments require prescription infrastructure.
- Topical Application:Gel and liquid formulations applied directly to ulcerative lesions via swab or fingertip. Mass retail environments in the United States prioritize shelf-stable unit-dose packaging for travel and workplace use. E-commerce subscription models exploit repeat purchase mechanics for chronic sufferers.
- Paste Application:Thick-adherence formulations creating protective barriers over exposed nerve endings. Pharmacy chains in France and Italy promote these for nocturnal pain management where mechanical protection outweighs rapid dissolution.
- Mouth Rinse:Swish-and-spit formats for diffuse mucosal coverage without precise lesion targeting.
- Systemic Treatment:Oral tablets or injections addressing underlying immunological triggers in severe recurrent cases.
Topical application dominates absolute volume, with paste application expanding most quickly through pharmacy professional recommendation programs.
End User:
Purchasing authority and reimbursement access create distinct channel economics across stakeholder types. Self-directed patients command lowest price sensitivity while institutional procurement drives volume contracting.
- Patients:Direct purchasers navigating OTC aisles and digital health platforms without clinical intermediation. United States consumers demonstrate highest willingness-to-pay for rapid relief claims supported by influencer endorsement. Subscription replenishment models capture predictable lifetime value from chronic recurrent sufferers.
- Pharmacies:Retail and institutional dispensaries exercising formulary control over shelf placement and generic substitution. European pharmacy chains leverage private-label portfolios to capture margin from price-sensitive segments.
- Clinics:Dental and primary care settings prescribing protocol-driven therapies for refractory cases.
- Hospitals:Inpatient and emergency departments managing oral ulceration secondary to chemotherapy or immunosuppression.
Patients generate the highest transaction volume, with pharmacies capturing the steepest expansion trajectory through private-label portfolio growth.
Therapy Area:
Clinical positioning determines regulatory classification and pricing architecture across therapeutic claims. Pain management commands broadest accessibility while infection control faces antimicrobial resistance scrutiny.
- Pain Management:Local anesthetic and anti-inflammatory formulations targeting nociceptor modulation at lesion sites. OTC accessibility in the United States, Germany, and Japan supports mass-market volume. Benzocaine concentration limits and methemoglobinemia warnings constrain formulation latitude.
- Oral Care:Preventive and maintenance protocols integrating canker sore management into broader dental hygiene regimens. Colgate-Palmolive and similar consumer oral care giants leverage brand equity for cross-sell mechanics in mass retail.
- Infection Control:Antiseptic adjuncts preventing secondary bacterial colonization of ulcerative lesions.
- Supportive Care:Nutritional and mechanical interventions addressing underlying deficiency or trauma triggers.
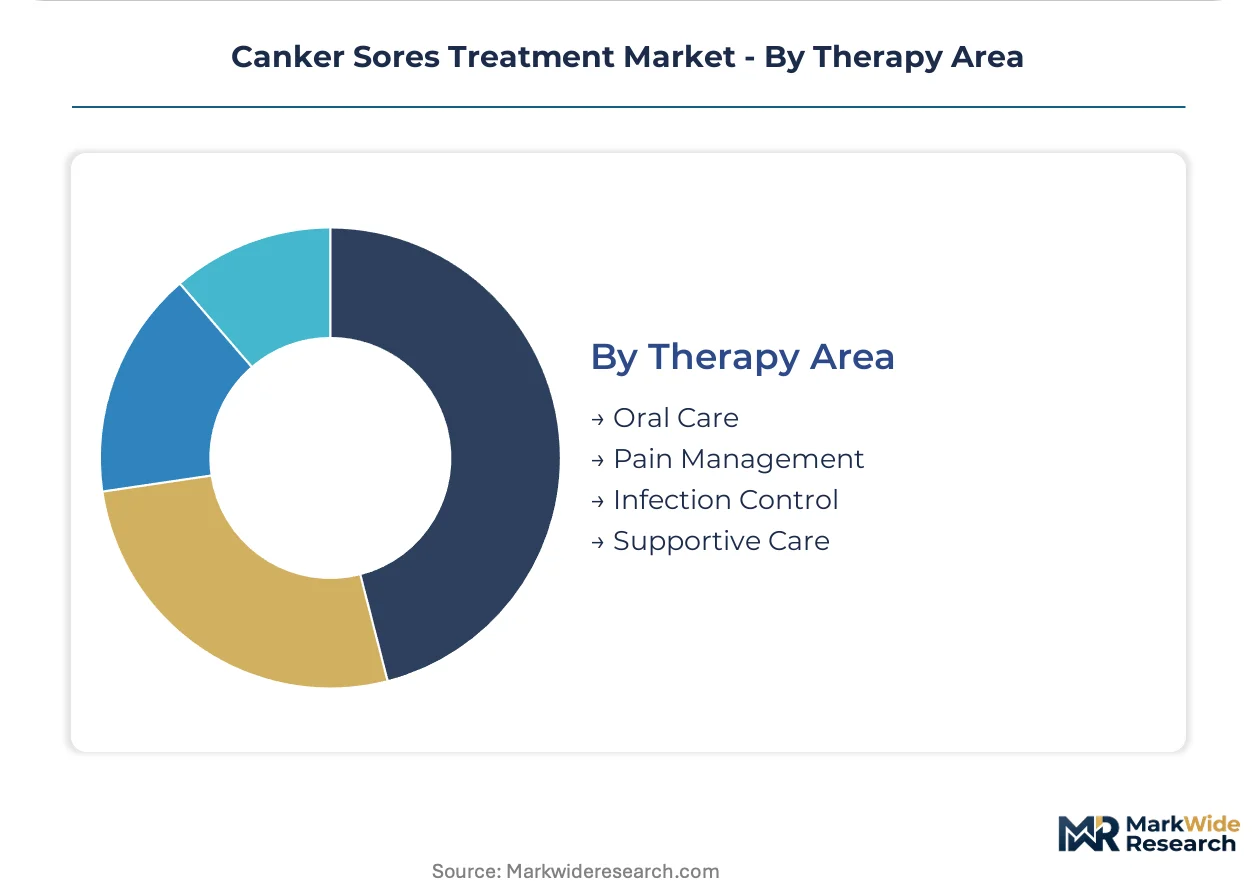
Pain management leads absolute volume, with oral care gaining share fastest through integration with premium toothpaste and rinse portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dental hygienists and pharmaceutical sales specialists concentrate in metropolitan clusters where oral care innovation and retail pharmacy infrastructure intersect most densely.
United States
Direct-to-consumer health platforms and pharmacy chain private-label expansion drive demand concentration. FDA OTC monograph compliance shapes formulation standards for topical analgesics. Boston and Minneapolis anchor clinical trial networks for bioadhesive gel development.
Germany
Dental professional channel adoption of hyaluronic acid protocols accelerates prescription-adjacent positioning. CE marking under EU MDR imposes biocompatibility validation requirements on gel formulations. Stuttgart and Munich host specialized oral care device manufacturers adapting to medical device reclassification.
India
API manufacturing clusters for benzocaine and hydrocortisone supply global formulation networks. CDSCO import testing protocols and BIS standards extend time-to-market for foreign entrants. Hyderabad and Ahmedabad concentrate contract research organizations supporting regulatory dossier preparation.
Japan
Consumer preference for rapid symptomatic relief products supports premium pricing in pharmacy channels. PMDA oversight governs borderline determinations between cosmetics and quasi-drugs. Osaka and Tokyo metropolitan areas dominate domestic distribution infrastructure for oral therapeutics.
Switzerland
Swissmedic regulatory frameworks attract specialty pharmaceutical developers seeking precision positioning. Dental clinics in Zurich and Geneva adopt advanced mucosal repair protocols for severe recurrent cases. Basel anchors cross-border supply coordination for European market access.
Canker Sores Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and channel vectors. The vendor base clusters around three strategic archetypes: consumer oral care giants leveraging brand equity, pharmaceutical manufacturers with prescription-to-OTC transition capabilities, and device specialists capturing medical device reclassification advantages. Competitive maneuvering concentrates on portfolio diversification into adjacent oral health categories and geographic expansion through regulatory pathway optimization.
Among diversified consumer health conglomerates, Colgate-Palmolive and Pfizer exemplify contrasting strategic positions. Colgate-Palmolive represents the brand-equity-driven archetype dominating mass retail shelf space through oral care portfolio integration. Pfizer occupies the pharmaceutical-transition specialist tier, anchoring prescription-grade formulation expertise adapted for consumer accessibility. GlaxoSmithKline sits within the professional channel-integrated category, with dental and pharmacy network penetration across multiple continents.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| Pfizer |
| GlaxoSmithKline |
| 3M Healthcare |
| Church & Dwight |
| Blistex |
| Reckitt Benckiser |
| Sunstar |
| Dr. Reddy's Laboratories |
| Others |
Pricing and Supply Chain Analysis
Benzocaine and hydrocortisone API costs cascade through formulation tiers, with Indian and Chinese chemical manufacturing clusters feeding private-label compression at retail pharmacy chains while hyaluronic acid-infused gels sustain premium positioning through dental professional channels.
Pricing Analysis
Bundled clinician-recommended protocols command substantial premiums over unbundled self-treatment purchases. Three-tier pricing structure across premium, standard, and economy levels separates hyaluronic acid bioadhesive gels from benzocaine analgesics and private-label rinses. Price differentiation rests on FDA OTC monograph compliance tier and dental professional endorsement density. Pricing pressure stems from retail pharmacy chain private-label expansion compressing branded OTC margins. Price-sensitive chronic sufferers gravitate toward subscription replenishment models, while acute episode buyers show lowest sensitivity to per-unit cost.
Supply Chain Analysis
India's Bureau of Indian Standards domestic-content mandates for oral care therapeutics are reshaping sourcing patterns for foreign manufacturers seeking market access. API production concentrates in India, China, and select European specialty chemical hubs. Raw material dependencies span benzocaine precursors, hydrocortisone intermediates, and pharmaceutical-grade hyaluronic acid. Single-source vulnerability runs through concentrated Chinese chemical manufacturing clusters for corticosteroid inputs. Distribution runs through retail pharmacy chains in the United States, pharmacy-led networks in Germany, and direct-to-consumer platforms capturing subscription replenishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as patient self-treatment preferences concentrate value capture in premium hyaluronic acid formulations with mucosal repair claims beyond baseline analgesia.
For Market Incumbents: Deploy prescription-to-OTC transition capabilities to capture clinician-adjacent positioning before generic corticosteroid protocols commoditize severe case management. Defensive consolidation moves center on acquiring bioadhesive gel specialists with EU MDR device classification advantages and deepening dental professional channel control against private-label encroachment. The threat of retail pharmacy chain vertical integration into oral care portfolios demands accelerated formulation differentiation through microbiome-targeting R&D investments. For New Entrants and Emerging Players: Dental professional recommendation networks represent the most penetrable channel archetype for prescription-adjacent positioning without full clinical trial dossier requirements. White-space targets include subscription-based chronic management platforms for recurrent aphthous stomatitis sufferers and CE-marked device-category gels exploiting regulatory arbitrage against pharmaceutical incumbents. Go-to-market execution should prioritize German and Swiss dental clinic adoption before scaling to mass retail. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA OTC monograph compliance costs and EU MDR biocompatibility validation requirements create barriers for sub-scale pure-play device specialists. Long-term viability favors vertically integrated API-to-formulation platforms with captive supply of benzocaine or hydrocortisone inputs. Acquisition target archetypes include bioadhesive matrix specialists with existing dental professional relationships. The signal to watch is pharmacy chain private-label share expansion in topical analgesics, which would accelerate branded margin compression and trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR device reclassification opens premium positioning beyond OTC monograph constraints. |
| Dental Professional Partnership | Clinician adoption of hyaluronic acid protocols creates prescription-adjacent revenue streams. |
| Backward Integration into API | Captive benzocaine supply buffers margin compression from Indian and Chinese chemical volatility. |
| Direct-to-Consumer Launch | Subscription replenishment models capture predictable lifetime value from chronic sufferers. |
| Microbiome Formulation Development | Next-generation bioadhesive matrices targeting oral microbiome balance create tier separation. |
Research Methodology
Coverage spans the United States, Germany, India, Japan, and Switzerland, with primary inputs from each market's stakeholder ecosystem. Primary interviews engaged regulatory affairs leads at topical analgesic manufacturers, pharmacy chain category buyers, dental professional association representatives, and CDSCO compliance consultants. Secondary validation drew from FDA OTC monograph databases, EMA medical device borderline determinations, ClinicalTrials.gov entries for recurrent aphthous stomatitis interventions, and Swissmedic quasi-drug classification precedents. Bottom-up formulation volume estimates triangulated against top-down retail pharmacy audit data.
Rate-of-change decomposition across the analysis window separated volume drivers from pricing dynamics and mix-shift effects. Segmentation dimensions modeled include product type hierarchy, delivery mode friction coefficients, end-user purchasing authority structures, and therapy area regulatory classification tiers. CAGRs were derived from fitted trend extrapolation with scenario-weighted probability distributions. Industry-specific forecast inputs incorporated API cost volatility indices and dental professional protocol adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA OTC monograph reform timing and EU MDR enforcement consistency. Forecasts reflect documented assumptions regarding private-label expansion rates and chronic sufferer subscription conversion elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
United States Oral Hygiene Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
North America Oral Care Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Toothcare Market
Oral Care
Baby Oral Care Market
Oral Care
Halitosis Treatment Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Tongue Cleaner Market
Oral Care
Us Oral Care Market
Oral Care
Oral Thin Films Market
Oral Care
Oral Thrush Market
Oral Care
Mouth Sore Medicine Market