
 Global Halitosis Market | 2026-2036
Global Halitosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Halitosis Market Foresight
Dental hygienist shortages across developed markets is collapsing access to professional halitosis screening and treatment planning. Colgate-Palmolive leverages its therapeutic mouthwash portfolio to sustain shelf presence in pharmacy channels. Procter & Gamble anchors mass-market breath freshener segments through retail distribution density.
Halitosis denotes chronic oral malodor arising from volatile sulfur compound production by anaerobic bacteria colonizing the tongue dorsum and periodontal pockets, with hydrogen sulfide and methyl mercaptan as principal malodorous metabolites. The condition serves both clinical diagnostic value for underlying periodontal or systemic disease and substantial commercial purpose across consumer oral hygiene and professional dental care markets. Mouthwash formulations containing cetylpyridinium chloride or zinc salts dominate value pools due to clinical validation and reimbursement familiarity in dental settings. Breath fresheners and chewing gum segments compete on convenience positioning though margin structures remain thinner than therapeutic rinses.
The FDA regulates antimicrobial oral care claims under over-the-counter drug monographs while the EU MDR governs medical device classifications for diagnostic breath analyzers. REACH compliance in Europe constrains formulation choices for zinc and triclosan alternatives. Japan's PMDA maintains distinct approval pathways for quasi-drug oral rinses. Stakeholders must monitor evolving regulatory divergence between cosmetic and therapeutic claims classifications as ingredient scrutiny intensifies.
Market Dynamics
The halitosis market pivots on tightening antimicrobial ingredient disclosure mandates from FDA and EU MDR regulators, which are compressing formulation flexibility and forcing R&D redeployment toward compliant active compounds.
Growth Catalysts
- EU MDR diagnostic classification:Medical device pathways for breath analyzers in Germany and France are accelerating professional screening infrastructure deployment.
- Employer wellness programs:United States corporations now subsidize preventive oral care, expanding reimbursement-eligible therapeutic rinse volumes.
- Zinc salt formulations:Clinical validation against volatile sulfur compounds is displacing legacy antiseptic rinses in dental clinic procurement.
Market Restraints
- REACH compliance costs:ECHA substance restrictions on triclosan alternatives are elevating European formulation redevelopment expenses.
- Dental hygienist shortages:United States training pipeline gaps are collapsing professional halitosis screening capacity in metropolitan markets.
- Diagnostic device reimbursement:Japan's PMDA quasi-drug approval timelines delay breath analyzer commercialization by 18-24 months versus cosmetic rinse pathways.
Strategic Opportunities
- Tele-dental platforms:Remote oral health assessments in Brazil and Mexico are creating direct-to-consumer therapeutic rinse distribution channels bypassing pharmacy intermediaries.
- AI-powered breath analysis:Machine learning integration with smartphone peripherals is fragmenting diagnostic access beyond clinical settings.
- CSRD sustainability reporting:European corporate oral health benefit expansions are mandating preventive care coverage that includes halitosis management.
Industry Challenges
- Cross-border claim harmonization:Divergent FDA cosmetic-therapeutic boundaries versus EU MDR medical device classifications force parallel marketing material development.
- Anaerobic bacterial assay standardization:Absence of ISO reference methods for volatile sulfur compound quantification complicates product efficacy substantiation across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Halitosis Market |
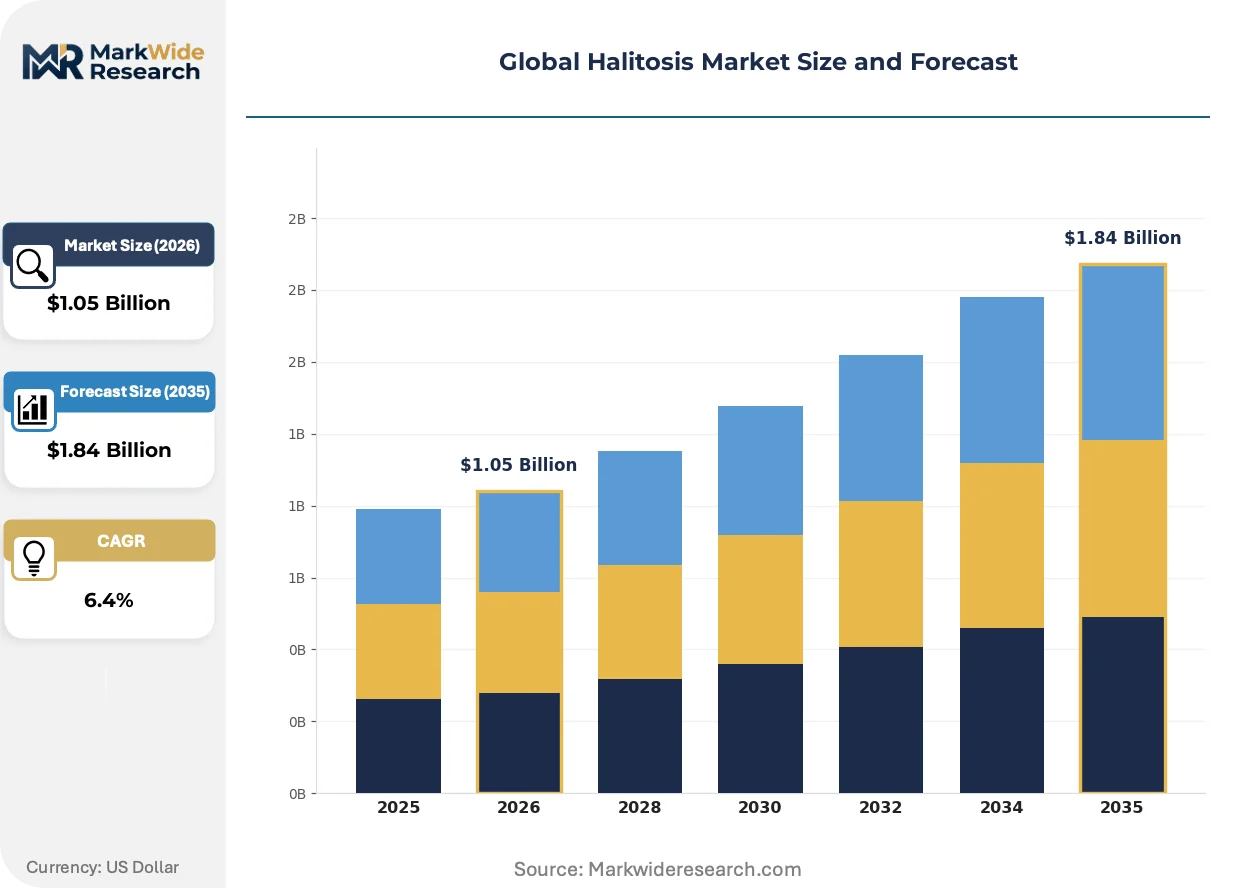
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mouthwash, Breath Fresheners, Chewing Gum, Toothpaste, Oral Sprays Cause Type: Oral Infection, Systemic Disease, Dry Mouth, Food Intake, Poor Oral Hygiene Distribution Channel: Pharmacies, Supermarkets, Online Stores, Specialty Stores, Dental Clinics End User: Adults, Teenagers, Seniors, Corporate Employees, Students |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble, Johnson & Johnson, Church & Dwight, Dabur India, GlaxoSmithKline, Dentsply Sirona, Rowpar Pharmaceuticals, Dr. Harold Katz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Halitosis Market Shifts & Advancements
Active ingredient diversification and diagnostic digitization are restructuring competitive boundaries between consumer breath fresheners and clinically positioned therapeutic rinses.
Portable volatile sulfur compound sensors utilizing metal oxide semiconductor technology are fragmenting the diagnostic landscape. Dental clinics in Japan and South Korea are piloting chairside breath analysis units that deliver quantitative malodor scores within 30 seconds. This capability is compressing the traditional referral pathway from self-perceived halitosis to periodontal specialist consultation.
REACH authorization requirements for zinc pyrithione are forcing European manufacturers toward copper-zinc formulations with equivalent antimicrobial efficacy. German and Dutch formulators are accelerating stability testing for these alternatives ahead of 2026 sunset dates. The transition is elevating R&D intensity for mid-tier private label suppliers lacking captive toxicology resources.
Subscription-based oral care bundles are displacing single-item pharmacy purchases among urban professionals in the United States and United Kingdom. Direct-to-consumer platforms combine therapeutic rinses with tongue scrapers and probiotic lozenges into quarterly replenishment cycles. This model concentrates customer lifetime value capture while eroding traditional retail slotting fee dependencies.
Global Halitosis Market Segmentation
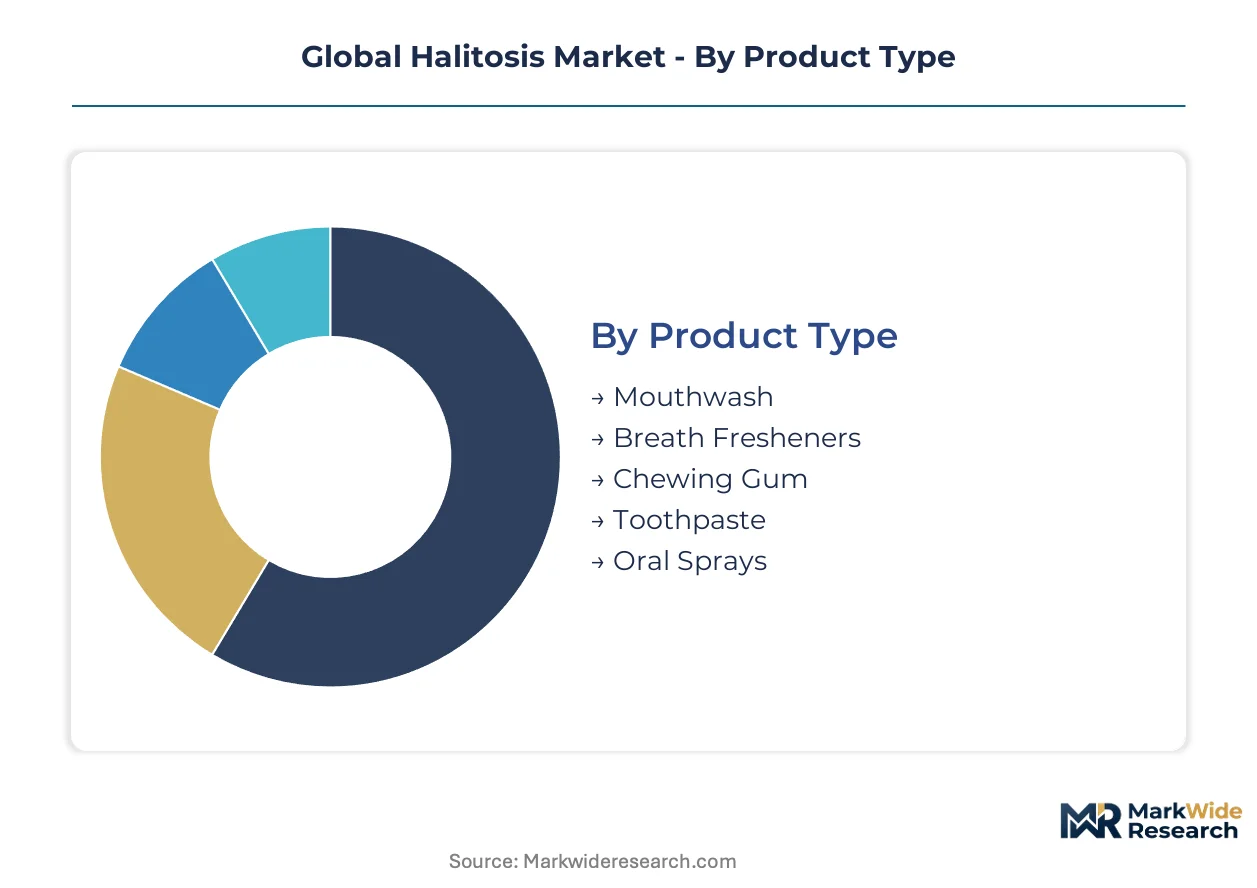
Segmentation in the halitosis market separates cosmetic convenience products from clinically validated therapeutic interventions. Regulatory classification boundaries between drug and device claims reshape competitive positioning across each category.
Product Type:
Mouthwash formulations concentrate manufacturing in the United States and Germany for export to dental clinic networks, while breath fresheners and chewing gum production localizes nearer to mass retail markets.
- Mouthwash:Therapeutic rinses containing cetylpyridinium chloride or zinc salts command premium positioning through FDA over-the-counter drug monograph compliance and dental reimbursement familiarity. Demand concentrates in United States employer wellness programs and German statutory health insurance preventive care coverage, with zinc salt formulations displacing legacy antiseptic rinses in clinic procurement.
- Breath Fresheners:Lozenges and strips deliver rapid malodor masking through flavor encapsulation and essential oil release, competing on convenience portability rather than antimicrobial efficacy. Distribution runs through Japanese convenience store networks and United Kingdom pharmacy impulse displays, where margin compression from private label substitution constrains branded expansion.
- Chewing Gum:Xylitol-sweetened formulations stimulate salivary flow to mechanically cleanse oral surfaces, positioned between cosmetic and functional benefits.
- Toothpaste:Halitosis-specific variants incorporate zinc citrate and stabilized chlorine dioxide for volatile sulfur compound neutralization during brushing.
- Oral Sprays:Pocket-sized delivery systems target immediate post-meal use cases in corporate and travel settings.
Mouthwash holds the largest share; momentum sits with zinc-therapeutic formulations as antimicrobial disclosure mandates intensify.
Cause Type:
Cost tier stratification separates diagnostic-intensive systemic disease management from low-touch poor oral hygiene interventions.
- Oral Infection:Periodontal pocket anaerobiosis and tongue dorsum bacterial biofilms generate hydrogen sulfide and methyl mercaptan as principal malodorous metabolites. Professional diagnosis in Japanese and South Korean dental clinics drives therapeutic rinse prescriptions, with chairside volatile sulfur compound sensors compressing referral pathways to periodontal specialists.
- Systemic Disease:Hepatic, renal, and diabetic metabolic disturbances produce distinctive breath signatures requiring medical rather than dental intervention. Germany and France lead breath analyzer medical device deployment under EU MDR diagnostic classifications, though reimbursement fragmentation limits volume scale.
- Dry Mouth:Xerostomia from medication side effects or autoimmune conditions reduces salivary antimicrobial peptide clearance.
- Food Intake:Volatile organosulfur compounds from garlic and onion consumption create transient malodor addressed through cosmetic masking.
- Poor Oral Hygiene:Inadequate mechanical plaque removal sustains bacterial load without underlying disease pathology.
Oral infection commands the dominant revenue pool; systemic disease segments are climbing the fastest as diagnostic device infrastructure expands.
Distribution Channel:
Volume concentration favors supermarket and pharmacy intermediaries, while margin capture shifts toward direct dental clinic and online subscription channels.
- Pharmacies:Pharmacist counseling drives therapeutic rinse selection in European markets with trained personnel availability, particularly in France and Italy where pharmacy density exceeds United States levels. Shelf space allocation battles between zinc-formulation incumbents and probiotic rinse entrants intensify as antimicrobial disclosure requirements elevate product differentiation needs.
- Supermarkets:Mass-market breath fresheners and chewing gum depend on retail slotting fees and promotional calendar coordination, with Procter & Gamble and Colgate-Palmolive leveraging distribution density for placement dominance.
- Online Stores:Direct-to-consumer platforms in the United States and United Kingdom bundle therapeutic rinses with tongue scrapers and probiotic lozenges into quarterly replenishment cycles, eroding traditional retail dependencies.
- Specialty Stores:Health food retailers stock natural-formulation alternatives with tea tree oil and aloe vera positioning.
- Dental Clinics:Professional screening infrastructure deployment accelerates in Germany and Japan, with EU MDR diagnostic classifications enabling medical device reimbursement pathways for breath analyzers.
Pharmacies retain the largest share; dental clinics are gaining share fastest as hygienist shortages paradoxically concentrate diagnostic value in remaining clinical capacity.
End User:
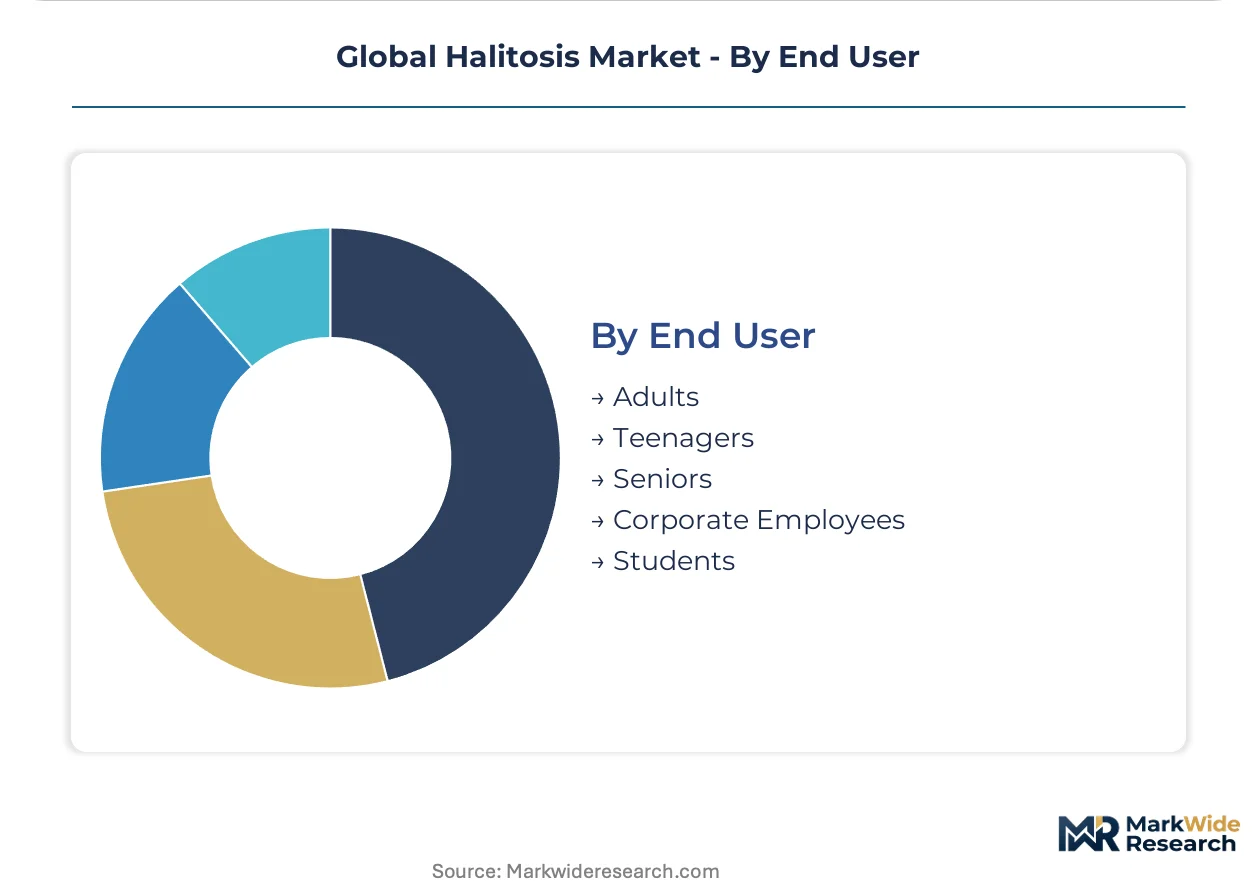
Customer type segmentation maps to distinct purchasing triggers: therapeutic necessity for seniors, social anxiety for teenagers, and employer subsidy for corporate employees.
- Adults:Self-perceived halitosis drives trial of multiple product formats before therapeutic commitment, with United States urban professionals showing highest subscription oral care bundle adoption.
- Teenagers:Social stigma sensitivity and limited disposable income concentrate demand in low-unit-price breath fresheners and chewing gum.
- Seniors:Polypharmacy-induced xerostomia and periodontal disease prevalence elevate therapeutic rinse necessity, with Japanese aging demographics sustaining preventive oral care spending.
- Corporate Employees:United States employer wellness program subsidies expand reimbursement-eligible therapeutic rinse volumes, with CSRD sustainability reporting mandating European corporate oral health benefit expansions.
- Students:Price elasticity and peer influence dynamics concentrate in campus retail and online promotional responsiveness.
Adults represent the largest addressable base; corporate employees show the steepest expansion trajectory as employer wellness program coverage broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between preventive-care markets where therapeutic rinses dominate employer-subsidized spending and cosmetic-heavy regions where breath fresheners anchor retail volume.
United States
Employer wellness program subsidies now cover preventive oral care for over forty million workers, expanding reimbursement-eligible therapeutic rinse volumes through pharmacy benefit managers. FDA over-the-counter drug monographs govern antimicrobial mouthwash claims, tightening ingredient disclosure requirements that favor zinc salt formulations over legacy antiseptics. Metropolitan dental networks in Los Angeles and Dallas-Fort Worth are deploying chairside breath analysis units to compress referral pathways.
Germany
Statutory health insurance preventive care coverage sustains therapeutic rinse procurement through dental clinic networks serving aging demographics. EU MDR diagnostic classifications for breath analyzers enable medical device reimbursement pathways in Bavaria and North Rhine-Westphalia. ECHA REACH substance restrictions on triclosan alternatives are elevating formulation redevelopment costs for mid-tier suppliers.
Japan
PMDA quasi-drug approval timelines delay breath analyzer commercialization by eighteen to twenty-four months versus cosmetic rinse pathways, compressing diagnostic infrastructure deployment. Aging demographics sustain preventive oral care spending among seniors managing polypharmacy-induced xerostomia. Osaka and Nagoya dental clusters are piloting volatile sulfur compound sensors with thirty-second quantitative scoring capability.
United Kingdom
Direct-to-consumer subscription platforms in London and Manchester bundle therapeutic rinses with tongue scrapers into quarterly replenishment cycles, eroding traditional pharmacy dependencies. MHRA oversight of medicinal claims constrains antimicrobial mouthwash marketing versus cosmetic positioning. Pharmacy density exceeds United States levels, enabling trained personnel to drive therapeutic selection through counseling.
Brazil
Tele-dental platforms are creating direct-to-consumer therapeutic rinse distribution channels that bypass pharmacy intermediaries in São Paulo and Rio de Janeiro. ANVISA regulatory pathways for oral care products remain less stringent than FDA or EU MDR frameworks, accelerating product entry. Urban professional demand concentrates in subscription oral care bundles mimicking United States and United Kingdom models.
Global Halitosis Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding pharmacy shelf space through distribution density and the latter competing on clinical validation in dental settings. The market structure reflects dual-channel pressure: mass retail favors scale-driven portfolio breadth while professional channels reward narrow therapeutic credibility. Three archetypes dominate—multinational consumer goods conglomerates with oral care divisions, dental equipment specialists extending into diagnostic consumables, and regional Ayurvedic or natural-formulation players. Competitive moves center on zinc salt formulation transitions ahead of antimicrobial disclosure mandates and subscription platform buildouts to capture recurring revenue.
Within the integrated multinational tier, Colgate-Palmolive Company and Procter & Gamble exemplify scale-driven pharmacy channel dominance, with the former leveraging therapeutic mouthwash portfolios and the latter anchoring mass-market breath freshener segments through retail distribution density. Johnson & Johnson occupies a position bridging consumer and professional domains through its healthcare conglomerate structure. Among dental-focused specialists, Dentsply Sirona represents the equipment-to-consumables extension archetype, while Rowpar Pharmaceuticals and Dr. Harold Katz sit within the narrow therapeutic validation tier targeting clinic procurement.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble |
| Johnson & Johnson |
| Church & Dwight |
| Dabur India |
| GlaxoSmithKline |
| Dentsply Sirona |
| Rowpar Pharmaceuticals |
| Dr. Harold Katz |
| Others |
Supply & Pricing Matrix
Zinc salt formulations displacing legacy antiseptic rinses simultaneously redraw raw material sourcing maps from triclosan-dependent Asian chemical hubs to European zinc oxide processors and restructure procurement economics toward premium therapeutic positioning backed by clinical validation.
Pricing Analysis
Long-term offtake agreements between German dental clinic networks and zinc-formulation manufacturers anchor therapeutic rinse pricing, while spot-market breath freshener transactions through Japanese convenience chains compress margins. Three-tier pricing structure across premium therapeutic, standard cosmetic, and economy private-label tiers separates FDA-validated zinc rinses from essential-oil masking products. Pricing pressure stems from REACH compliance costs elevating European formulation redevelopment expenses. Corporate wellness program buyers show lowest price sensitivity; teenage breath freshener consumers exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate breath freshener and chewing gum production localized to mass retail markets, while strategic stockpiling of zinc oxide and cetylpyridinium chloride concentrates supports mouthwash manufacturing in the United States and Germany. Active pharmaceutical ingredient sourcing draws from Indian chemical processors and Chinese mineral refiners. Single-source vulnerability concentrates in zinc pyrithione alternatives facing 2026 REACH sunset deadlines. Distribution runs through pharmacy benefit managers for therapeutic tiers and retail slotting fee systems for mass-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where FDA over-the-counter drug monographs and EU MDR diagnostic classifications erect multi-year approval barriers that protect validated formulation incumbents from rapid commoditization.
For Market Incumbents: Fortify zinc salt formulation pipelines through backward integration into European zinc oxide supply and preemptive toxicology dossier submission ahead of REACH authorization deadlines. Channel control investments in dental clinic breath analyzer placement lock in diagnostic-driven therapeutic rinse prescriptions against probiotic rinse entrants. Certification investment in ISO breath analysis standardization secures protocol-setting influence. For New Entrants and Emerging Players: Anchor in Brazilian tele-dental platforms where ANVISA regulatory pathways remain less stringent than FDA or EU MDR frameworks, creating direct-to-consumer distribution bypassing pharmacy intermediaries. AI-powered smartphone breath analysis peripherals represent the most penetrable white-space segment. Subscription bundle economics concentrating customer lifetime value capture offer the strongest go-to-market angle against retail slotting fee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward narrow therapeutic validation specialists with established dental clinic procurement relationships and captive toxicology resources, given five-to-ten year viability windows for antimicrobial disclosure compliance. Watch PMDA quasi-drug approval timeline compression as the inflection signal for Japanese diagnostic infrastructure scale-up.| Strategic Initiative | Industry Significance |
|---|---|
| Zinc Formulation Transition | REACH compliance deadlines in Europe force R&D redeployment toward copper-zinc alternatives with equivalent antimicrobial efficacy. |
| Subscription Platform Buildout | Quarterly replenishment cycles in the United States and United Kingdom erode traditional retail slotting fee dependencies. |
| Chairside Diagnostic Deployment | Volatile sulfur compound sensors in Osaka and Los Angeles compress referral pathways to periodontal specialists. |
| Tele-Dental Channel Development | Remote oral health assessments in São Paulo create direct-to-consumer therapeutic rinse distribution bypassing pharmacies. |
| EU MDR Diagnostic Classification | Medical device pathways in Germany and France accelerate professional screening infrastructure reimbursement. |
Research Methodology
A standing panel of dental clinic procurement managers, pharmaceutical formulation scientists, regulatory affairs specialists at oral care manufacturers, and pharmacy benefit manager contract directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through FDA over-the-counter drug monograph filings, ECHA REACH substance restriction updates, PMDA quasi-drug approval databases, and customs trade records for zinc oxide and cetylpyridinium chloride flows. Bottom-up therapeutic rinse volume modeling triangulated against top-down employer wellness program spending estimates.
Consistency checks validated volume and value outputs against external benchmarks including Nielsen retail audit data for mass-market breath freshener segments and dental equipment procurement databases for breath analyzer deployment. The analytical framework segmented across product type, cause type, distribution channel, and end user dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical therapeutic rinse prescription volumes correlated with dental hygienist workforce data and employer wellness program adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained employer wellness program expansion and stable REACH authorization timelines; material deviation would warrant model refresh. Revision becomes warranted when dental hygienist shortage severity crosses thresholds that collapse professional screening capacity or when PMDA quasi-drug approval timelines compress differentially versus cosmetic rinse pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Rinse Market
Oral Care
Kids Toothpaste Market
Oral Care
South America Oral Care Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Toothcare Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Oral Care Market
Oral Care
Oral Thrush Market
Oral Care
Europe Oral Care Market
Oral Care
Global Oral Hygiene Market
Oral Care
Dry Mouth Relief Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Xerostomia Treatment Market
Oral Care
BRICS Oral Care Market