
 Asia-Pacific Oral Care Market | 2026-2036
Asia-Pacific Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oral Care Market Outlook
India's manufacturing corridor is rewriting supply dynamics for oral care across the region. Colgate-Palmolive Company leverages its extensive distribution network to dominate rural penetration, while Lion Corporation anchors premium toothpaste production with specialized fluoride formulations. Unilever Plc competes aggressively through herbal positioning tailored to Ayurveda-influenced consumers.
Asia-Pacific oral care encompasses consumer products formulated for dental hygiene, disease prevention, and aesthetic enhancement, typically containing active ingredients such as sodium fluoride at concentrations between 1000–1500 ppm for anticavity efficacy and manufactured through emulsion-based processes with controlled abrasivity indices. Toothpaste occupies the largest value pool given its daily-use frequency and premiumization potential across whitening and herbal variants, while online retail represents the fastest-growing sales channel as direct-to-consumer platforms bypass traditional pharmacy intermediaries in markets like South Korea and Vietnam. Charcoal formulations attract niche margins despite regulatory scrutiny over abrasiveness claims.
India's BIS standards govern fluoride concentration limits and herbal ingredient disclosures, while Japan's Ministry of Health, Labour and Welfare oversees quasi-drug classifications for medicated toothpastes through PMDA pathways. Australia's TGA regulates therapeutic claims on whitening products, forcing reformulation for cross-border market access. Stakeholders must monitor evolving herbal substantiation requirements and e-commerce labeling mandates as regulatory fragmentation intensifies compliance complexity across the region.
Market Dynamics
India's BIS standards for fluoride content and herbal ingredient disclosures are compressing formulation flexibility while accelerating compliance investments across manufacturing corridors in Mumbai and Ahmedabad.
Growth Catalysts
- Herbal substantiation mandates:India's BIS requirements for Ayurveda-influenced ingredient disclosures create first-mover advantages for domestic laboratories capable of rapid botanical authentication.
- Fluoride concentration standardization:Tier-two Indian cities and Indonesia's Greater Jakarta corridor concentrate demand for 1000–1500 ppm sodium fluoride formulations as oral health literacy spreads.
- Emulsion-based manufacturing:Controlled abrasivity indices and precision mixing technologies enable premium whitening strip production at scale for Southeast Asian urban millennials.
Market Restraints
- Sorbitol supply volatility:Humectant input costs fluctuate with palm oil derivatives pricing, squeezing margin structures for mid-tier toothpaste producers.
- Quasi-drug classification friction:Japan's PMDA pathways for medicated toothpastes extend registration timelines, blocking rapid cross-border product launches.
- Charcoal abrasiveness scrutiny:Australia's TGA therapeutic claims enforcement forces reformulation investments for whitening products seeking market access.
Strategic Opportunities
- Vietnam e-commerce penetration:Direct-to-consumer platforms bypass traditional pharmacy intermediaries, unlocking first-touch customer acquisition in underpenetrated provincial capitals.
- South Korean subscription models:Automated replenishment systems for daily-use oral care products capture lifetime value through predictable consumption tracking.
- PLI scheme manufacturing:India's production-linked incentive framework for personal care goods attracts capacity expansion into Gujarat and Tamil Nadu industrial zones.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in fluoride stability and herbal extraction protocols concentrates with legacy multinationals, constraining local competitor R&D velocity.
- Cross-border label harmonization:Divergent e-commerce labeling mandates between MFDS in South Korea and Vietnam's Ministry of Health fragment packaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oral Care Market |
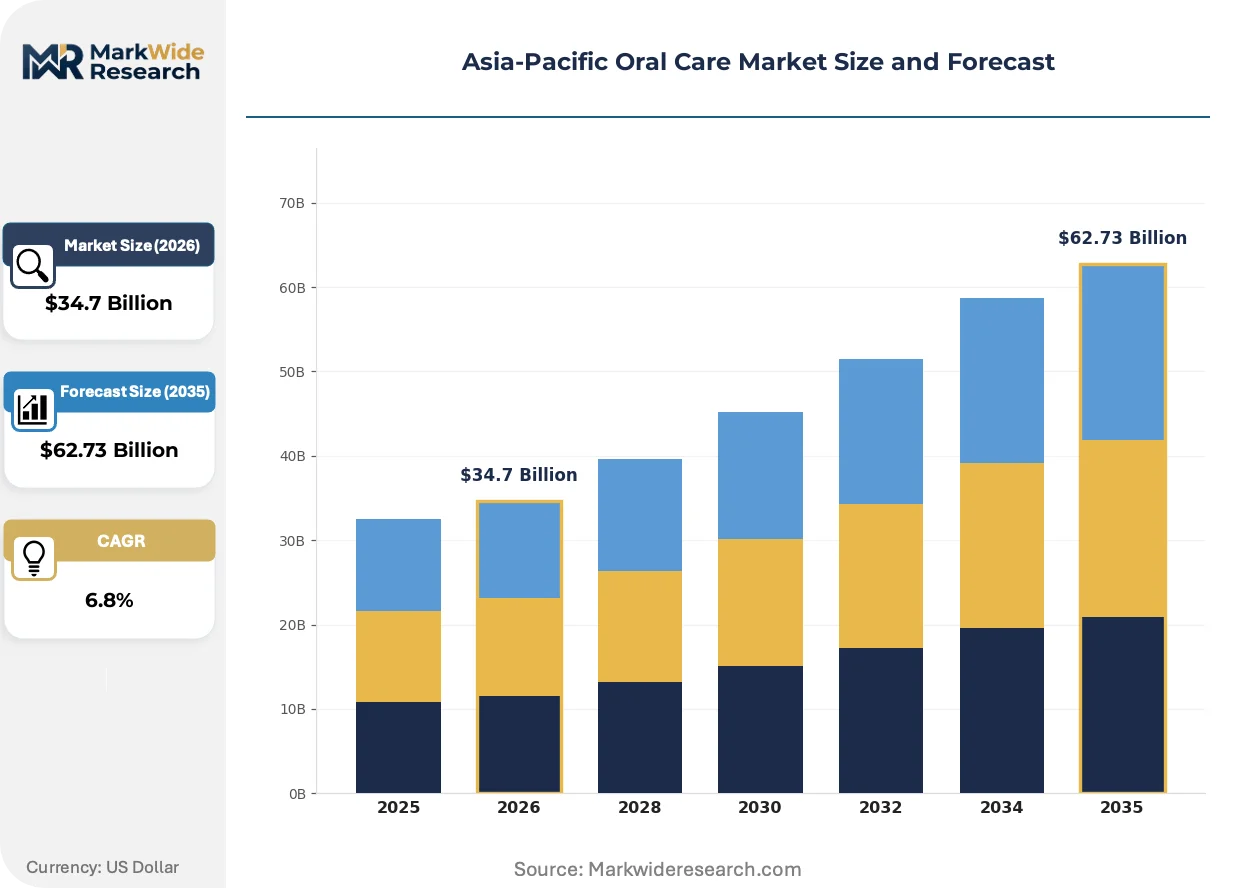
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Strips End User: Adults, Children, Seniors, Orthodontic Patients Sales Channel: Supermarkets, Pharmacies, Online Retail, Convenience Stores Formulation: Fluoride, Herbal, Charcoal, Natural |
| Companies Covered | Colgate-Palmolive Company, Procter and Gamble Company, Unilever Plc, GlaxoSmithKline plc, Lion Corporation, Pigeon Corporation, Kao Corporation, Dabur India Ltd., Hawley and Hazel Asia Investment Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oral Care Market Strategic Shifts
Formulation science and distribution architecture are undergoing simultaneous compression as regional regulators tighten ingredient transparency and digital channels displace traditional retail intermediaries.
Enzymatic whitening systems are collapsing the efficacy gap between professional dental treatments and over-the-counter strips. Urban millennials across Bangkok and Ho Chi Minh City adopt these peroxide-alternative formulations at accelerating velocity. The technology is collapsing premium pricing tiers that previously separated salon-grade procedures from home-use products.
Japan's PMDA quasi-drug classification pathways for medicated toothpastes are tightening evidentiary requirements for gingivitis and hypersensitivity claims. Manufacturers must now submit clinical trial data for active ingredients like potassium nitrate and stannous fluoride. Specialized fluoride toothpaste segments face compressed registration timelines as domestic incumbents leverage existing dossier libraries.
Direct-to-consumer platform penetration is fragmenting pharmacy channel dominance across Southeast Asian capitals. Subscription-based replenishment models capture recurring revenue from whitening strip users in Seoul and Hanoi. South Korea's MFDS-aligned e-commerce labeling standards are spreading as regional template for cross-border oral care sales.
Asia-Pacific Oral Care Market Segmentation
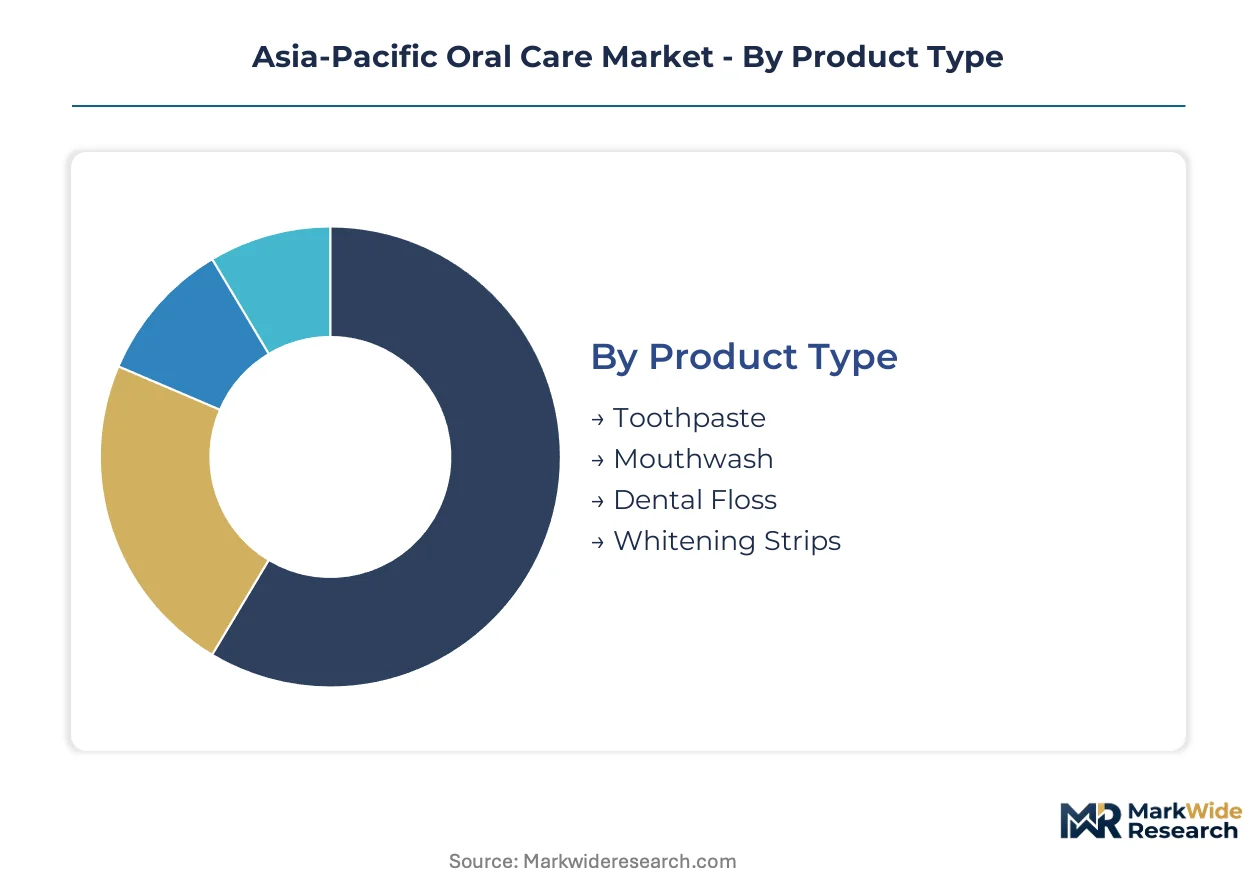
Oral care purchasing patterns in Asia-Pacific diverge sharply by consumption cadence and channel access. Daily-use formats command predictable replenishment cycles while specialty treatments exhibit sporadic, occasion-driven demand spikes.
Product Type:
Toothpaste turns inventory fastest with universal daily application, while whitening strips operate on extended replacement cycles tied to treatment protocols.
- Toothpaste:Emulsion-based formulations with controlled abrasivity indices (RDA 70-150) dominate bathroom shelves across the region. Demand concentrates in India's tier-two cities and Indonesia's Greater Jakarta corridor as oral health literacy spreads through municipal health programs.
- Mouthwash:Antiseptic rinses containing cetylpyridinium chloride or essential oils target periodontal maintenance needs. South Korean consumers drive adoption through pharmacy-led recommendations, though alcohol-free variants gain traction among sensitivity-conscious users.
- Dental Floss:Nylon and PTFE monofilament formats address interdental cleaning gaps left by brushing alone. Urban millennials in Bangkok and Ho Chi Minh City show rising penetration as preventive dentistry awareness climbs.
- Whitening Strips:Hydrogen peroxide or enzymatic bleaching systems deliver professional-grade results through home application. Southeast Asian urban millennials adopt these formats despite premium positioning, compressing the efficacy gap with salon procedures.
Toothpaste anchors the volume base while whitening strips gain share at the steepest rate.
End User:
Pediatric formulations require specialized fluoride dosing and flavor masking, while orthodontic patients need adjunct tools beyond standard brushing.
- Adults:The broadest addressable population spans preventive maintenance through aesthetic enhancement needs. India's working-age demographic in Ahmedabad and Mumbai manufacturing corridors drives bulk purchasing of standard fluoride formulations.
- Children:Low-fluoride (500-1000 ppm) and fruit-flavored variants balance efficacy with safety margins. Parents in Vietnam's provincial capitals increasingly prioritize these formats as dental caries awareness penetrates beyond metro centers.
- Seniors:Dry mouth and gingival recession formulations address age-specific oral conditions. Japan's aging population sustains demand for potassium nitrate sensitivity toothpastes through pharmacy channels.
- Orthodontic Patients:Interdental brushes, floss threaders, and orthodontic wax complement fixed appliance maintenance. South Korean dental clinics bundle these adjuncts with treatment packages, creating captive distribution.
Adult users anchor the volume base while orthodontic patients gain share at the steepest rate.
Sales Channel:
Traditional pharmacy intermediaries face disintermediation as direct-to-consumer platforms capture first-touch relationships and recurring revenue.
- Supermarkets:Mass-market SKUs with prominent shelf positioning drive impulse replenishment. Indonesia's modern trade expansion into Greater Jakarta's satellite cities concentrates volume for family-size toothpaste packs.
- Pharmacies:Pharmacist recommendations influence medicated and sensitivity-focused purchases. Japan's drugstore chains maintain quasi-drug classification expertise, guiding consumers through PMDA-regulated options.
- Online Retail:Direct-to-consumer platforms bypass intermediaries with subscription automation and personalized bundling. South Korean and Vietnamese e-commerce penetration unlocks underexposed provincial markets.
- Convenience Stores:Travel-size and emergency replenishment formats serve immediate-need occasions. Urban density in Seoul and Tokyo sustains 24-hour availability for single-use mouthwash sachets.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
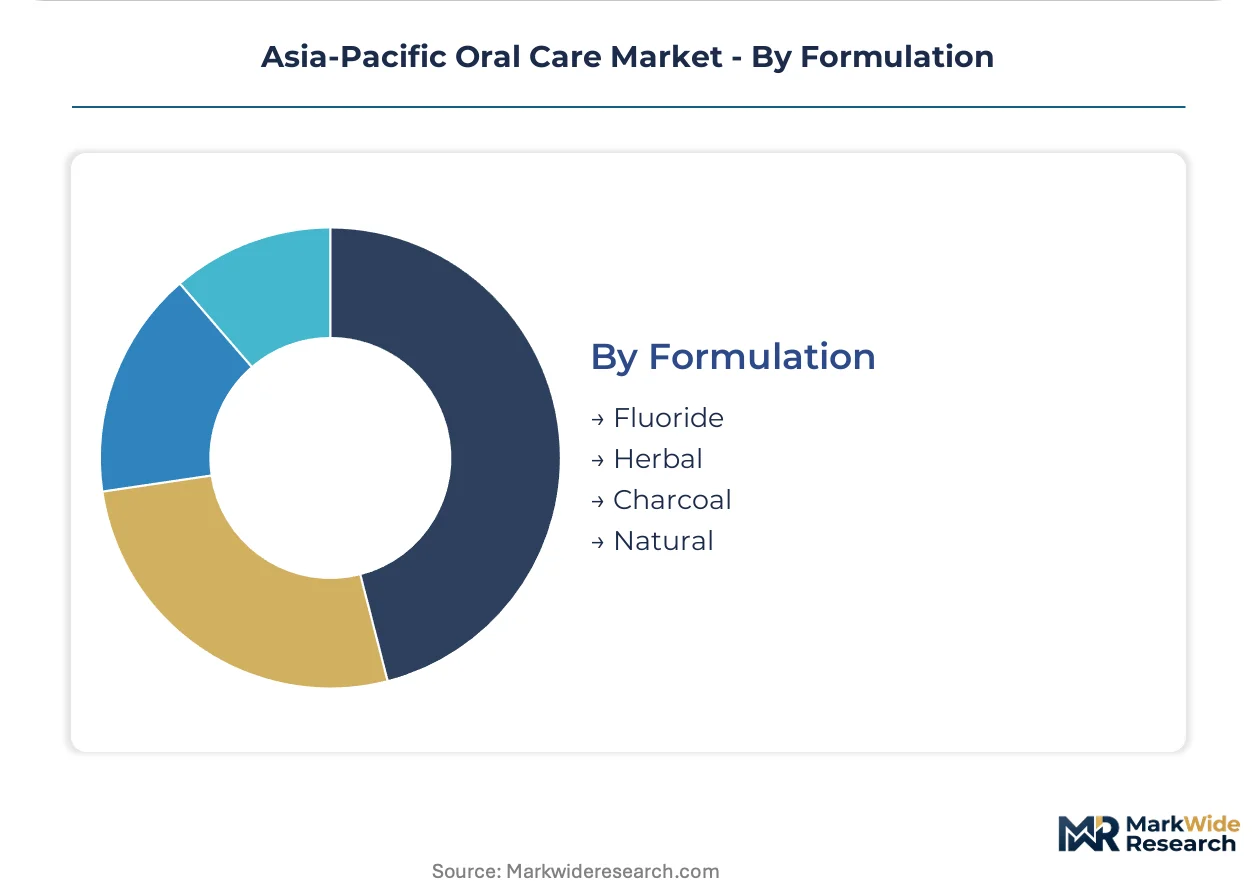
Formulation:
Regulatory pressure on ingredient transparency and herbal substantiation is fragmenting R&D priorities across competing chemistry platforms.
- Fluoride:Sodium fluoride and stannous fluoride at 1000-1500 ppm deliver proven anticavity efficacy through enamel remineralization. India's BIS concentration standards and disclosure mandates compress formulation flexibility while accelerating compliance investments.
- Herbal:Ayurveda-influenced botanicals including neem, clove, and miswak extracts target natural-positioned consumers. Unilever's India operations leverage domestic laboratory authentication capabilities to meet BIS substantiation requirements.
- Charcoal:Activated carbon formulations attract niche margins despite abrasiveness concerns and regulatory scrutiny. Australia's TGA therapeutic claims enforcement forces reformulation for whitening products seeking market access.
- Natural:Fluoride-free and synthetic-additive-free positioning appeals to ingredient-conscious segments. Premium pricing in South Korean subscription channels offsets higher raw material costs.
Fluoride formulations anchor the volume base while herbal variants gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply between fluoride-centric preventive markets and herbal-preference segments, with urban millennials in Seoul and Jakarta driving premium whitening adoption while tier-two Indian cities anchor volume for standard formulations.
India
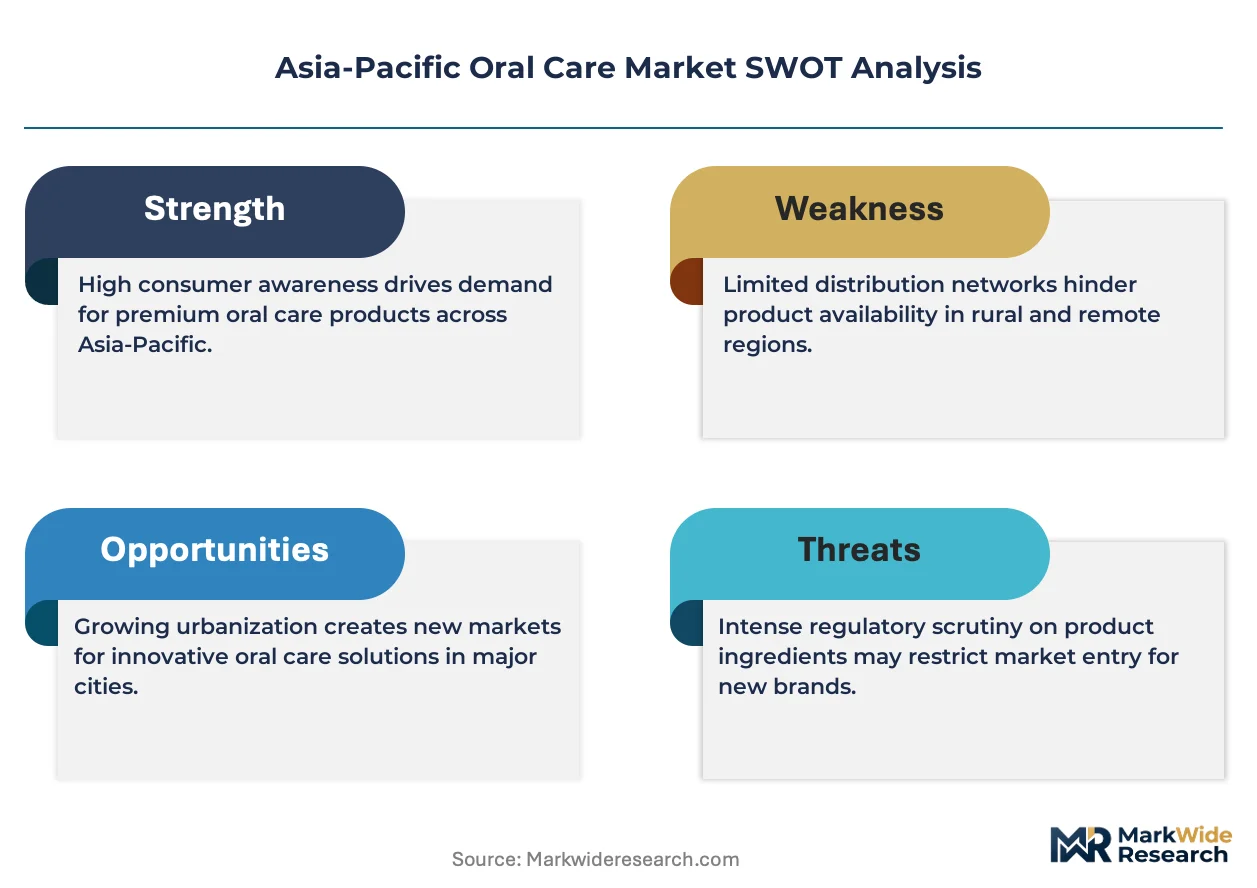
Ahmedabad and Mumbai manufacturing corridors concentrate toothpaste production capacity serving domestic tier-two cities and export markets. BIS standards for fluoride concentration limits and herbal ingredient disclosures compress formulation flexibility while accelerating compliance investments across Gujarat and Tamil Nadu industrial zones. Domestic laboratories capable of rapid botanical authentication capture first-mover advantages as Ayurveda-influenced positioning gains regulatory substantiation requirements.
Japan
Tokyo-Osaka metropolitan corridors sustain demand for potassium nitrate sensitivity toothpastes through pharmacy channels serving aging demographics. PMDA quasi-drug classification pathways for medicated toothpastes tighten evidentiary requirements for gingivitis and hypersensitivity claims, extending registration timelines for active ingredients like stannous fluoride. Domestic incumbents leverage existing dossier libraries to compress registration timelines against cross-border entrants.
South Korea
Seoul Capital Area drives subscription-based replenishment models for whitening strips and daily-use oral care products through automated consumption tracking. MFDS-aligned e-commerce labeling standards spread as regional template for cross-border oral care sales, influencing packaging workflows across neighboring markets. Direct-to-consumer platforms capture recurring revenue from urban millennials through personalized bundling algorithms.
Indonesia
Greater Jakarta corridor concentrates demand for 1000–1500 ppm sodium fluoride formulations as oral health literacy spreads through municipal health programs. Modern trade expansion into satellite cities concentrates volume for family-size toothpaste packs while pharmacy intermediaries face gradual disintermediation. Provincial capitals beyond Java unlock underpenetrated demand as e-commerce penetration deepens.
Australia
Sydney and Melbourne metropolitan markets enforce TGA therapeutic claims standards on whitening products, forcing reformulation investments for charcoal and peroxide-based formulations seeking market access. Sensitivity-conscious users drive alcohol-free mouthwash adoption through pharmacy-led recommendations. Regulatory enforcement creates compliance barriers that favor established players with dedicated regulatory affairs capabilities.
Asia-Pacific Oral Care Market Competitive Environment
Capability concentration sits with legacy multinationals possessing specialized fluoride stability expertise; scale advantage sits with diversified consumer goods conglomerates leveraging cross-category distribution infrastructure. The market structures around three tiers: research-intensive medicated specialists, mass-market volume players, and niche botanical positioning firms. Dominant competitive moves include herbal substantiation investments to meet India's BIS requirements and direct-to-consumer platform builds to bypass traditional pharmacy intermediaries.
Among Asia-Pacific headquartered specialists, Lion Corporation and Kao Corporation exemplify the medicated toothpaste tier with deep quasi-drug registration expertise, while Dabur India Ltd. occupies a distinctive position anchoring Ayurveda-influenced botanical authentication capabilities. These three entities represent the spectrum from fluoride-centric preventive science to herbal substantiation compliance, each sitting within regulatory frameworks that favor accumulated dossier libraries or domestic laboratory infrastructure.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter and Gamble Company |
| Unilever Plc |
| GlaxoSmithKline plc |
| Lion Corporation |
| Pigeon Corporation |
| Kao Corporation |
| Dabur India Ltd. |
| Hawley and Hazel Asia Investment Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Singapore-Jakarta maritime freight corridors transmit palm oil derivative cost volatility directly into sorbitol pricing, compressing margin structures for mid-tier toothpaste producers while enabling premium-tier manufacturers to capture price differentiation through controlled abrasivity indices and herbal authentication capabilities.
Pricing Analysis
Long-term offtake contracts for sodium fluoride and specialty humectants dominate upstream procurement, insulating volume leaders from spot market swings in palm oil derivatives. Three-tier pricing structure across premium, standard, and economy levels separates enzymatic whitening systems from basic fluoride formulations and private-label alternatives. Pricing pressure stems from BIS compliance investments for herbal substantiation, which concentrate cost burdens on domestic challengers lacking legacy dossier libraries. Price-sensitive buyers in India's tier-two cities gravitate toward economy fluoride formulations, while Seoul's subscription-driven millennials absorb premium positioning for automated replenishment models.
Supply Chain Analysis
Upstream feedstock concentration for activated carbon, sodium fluoride, and sorbitum rests on China, Malaysia, and India as primary extraction and processing nodes. Specialty abrasive sourcing draws from Gujarat's bauxite refineries and Tamil Nadu's mineral processing corridors. Single-source vulnerability in enzymatic whitening enzyme supply creates chokepoint exposure for premium strip manufacturers. Distribution runs through pharmacy intermediaries in Japan and Indonesia, though direct-to-consumer platforms in South Korea and Vietnam are accelerating channel disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific oral care sits at a high-growth inflection as India's BIS herbal substantiation mandates and South Korea's MFDS-aligned e-commerce standards simultaneously compress formulation flexibility and unlock subscription-based lifetime value capture.
For Market Incumbents: Insulate margin structures by securing captive sorbitol supply through backward integration into Malaysian palm oil processing, while accelerating dossier compilation for PMDA quasi-drug pathways to block cross-border entrants in Japan's medicated toothpaste segments. For New Entrants and Emerging Players: Provincial capitals in Vietnam and Indonesia's outer islands represent the most penetrable entry points, where pharmacy channel fragmentation and underdeveloped e-commerce penetration create first-mover windows for direct-to-consumer platform builds with localized herbal positioning. For Investors and Strategic Acquirers: Domestic laboratories with rapid botanical authentication capabilities and existing BIS compliance infrastructure offer the strongest acquisition profile, as regulatory substantiation requirements intensify across India's Ayurveda-influenced segments. Watch for MFDS-aligned labeling standards spreading beyond South Korea as the signal for regional e-commerce consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Herbal Substantiation Investment | BIS-compliant botanical authentication creates defensible positioning in India's tier-two cities. |
| Direct-to-Consumer Platform Build | Subscription automation in Seoul and Hanoi captures lifetime value through consumption tracking. |
| Backward Integration into Humectants | Captive sorbitol supply from Malaysian palm oil derivatives insulates margin from input volatility. |
| PMDA Dossier Compilation | Quasi-drug registration libraries compress timelines for medicated toothpaste entrants in Japan. |
| Provincial E-Commerce Penetration | First-touch acquisition in Vietnam's satellite cities bypasses entrenched pharmacy intermediaries. |
Study Parameters
A standing panel of brand managers at multinational oral care manufacturers, category buyers at Indonesian modern trade retailers, BIS compliance officers at domestic laboratories, and supply planners at Gujarat-based production facilities provided ongoing calibration. Primary interview findings were cross-referenced with secondary sources including CDSCO registration databases, MFDS quasi-drug filings, customs records for sorbitum and abrasive imports, and Nielsen retail audit data across Southeast Asian pharmacy channels. Bottom-up volume builds for whitening strips and toothpaste SKUs were triangulated against top-down category spend estimates.
Scenario-bracketing around BIS enforcement intensity and e-commerce penetration velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user demographic, sales channel architecture, and formulation chemistry platform. CAGRs were derived from normalized historical growth patterns adjusted for regulatory inflection points and channel shift trajectories. Forecast inputs incorporated municipal health program expansion timelines in Greater Jakarta and subscription adoption curves in Seoul Capital Area.
Stress conditions across palm oil derivative pricing, PMDA registration timeline extensions, and provincial logistics infrastructure development were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding BIS herbal substantiation rollout pace and MFDS labeling standard regional adoption. Cross-checking against CDSCO quarterly registration statistics and Vietnam e-commerce gross merchandise value benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Mouth Sore Medicine Market
Oral Care
BRICS Oral Care Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Us Oral Care Market
Oral Care
LED Oral Care Kits Market
Oral Care
Toothcare Market
Oral Care
Kids Oral Care Products Market
Oral Care
Dry Mouth Relief Market
Oral Care
Tongue Cleaner Market
Oral Care
United States Oral Hygiene Market
Oral Care
China Oral Care Market
Oral Care
Oral Antiseptics Market
Oral Care
Baby Oral Care Market
Oral Care
Global Oral Care Products Market
Oral Care
Mouthwash Market
Oral Care
Herbal Toothcare Market