
 Global Oral Care/Oral Hygiene Market | 2026-2036
Global Oral Care/Oral Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oral Care/Oral Hygiene Market Foresight
Modular refill systems and unbundled subscription kits is decoupling the traditional all-in-one tube-and-brush purchase pattern. Colgate-Palmolive leverages its manufacturing scale to dominate refill pod distribution in North America. Procter & Gamble differentiates through enzymatic technology leadership in premium whitening strips. Haleon plc anchors its position in pharmacy channels with specialized gum care portfolios.
Oral care and oral hygiene encompasses the maintenance of dental and gingival health through mechanical and chemotherapeutic interventions, typically involving abrasives below 20% by weight, surfactants such as sodium lauryl sulfate, and active agents including stannous fluoride or potassium nitrate delivered via paste, rinse, or device formats to prevent caries, periodontal disease, and enamel erosion. Toothpaste remains the volume anchor across mass retail channels, while teeth whitening products capture disproportionate margin pools in specialty and direct-to-consumer routes. Activated charcoal formulations have plateaued in mature markets, whereas enzymatic technology is gaining shelf space in European pharmacies and Asian e-commerce platforms.
FDA monograph rules govern over-the-counter fluoride and antibacterial claims in the United States, while the EU Green Deal and REACH frameworks are restricting certain synthetic preservatives and mandating packaging recyclability across member states. Japan's PMDA and METI enforce distinct efficacy labeling standards that shape product registration timelines for imported formulations. Stakeholders must monitor evolving chemical restriction lists and packaging compliance costs as these determine which formulation portfolios can cross borders profitably.
Market Dynamics
Modular refill systems are decoupling the traditional tube-and-brush purchase pattern, forcing incumbents to reconfigure manufacturing assets and distribution economics around pod-based replenishment rather than unit-based restocking.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability requirements are accelerating format innovation toward aluminum-free tubes and water-soluble films, creating first-mover advantages for compliant suppliers.
- Enzymatic whitening chemistry:Peroxide-free systems using glucose oxidase and lactoperoxidase are capturing pharmacy shelf space in Germany and Japan as sensitivity-conscious consumers reject traditional bleaching agents.
- Middle-class oral care systematization:Brazilian and Indian households are shifting from single-item fluoride paste purchases toward bundled preventive regimens including mouth rinse, interdental cleaning, and tongue scrapers.
Market Restraints
- Sodium lauryl sulfate substitution costs:Reformulating around sulfate-free surfactants increases raw material expenses and requires stability testing that extends development timelines.
- Titanium dioxide pigment restrictions:EFSA's 2021 reclassification as a food additive of concern has forced European manufacturers to source alternative opacifiers with inferior optical performance.
- Fluoride source concentration:Three suppliers control global stannous fluoride supply, creating vulnerability for brands dependent on this antibacterial active versus sodium fluoride alternatives.
Strategic Opportunities
- Direct-to-consumer subscription bundling:Unbranded refill pods paired with smart dispensing hardware offer margin expansion beyond mass retail slotting fees.
- Pharmacy-channel gum care specialization:Periodontal maintenance portfolios targeting post-surgical patients remain underdeveloped outside Haleon's established presence.
- BIS cosmetic safety compliance:India's 2022 mandatory registration requirement creates barriers for unorganized sector competitors, consolidating share for documented manufacturers.
Industry Challenges
- Clinical substantiation timelines:FDA monograph compliance for new fluoride delivery mechanisms requires multi-year caries reduction studies that delay market entry.
- Legacy filling line retrofit costs:Transitioning from extruded tubes to thermoformed pod systems demands capital expenditure that mid-tier brands cannot absorb.
- Cross-border formulation harmonization:Divergent permissible active concentrations between PMDA, FDA, and EMA standards fragment SKU strategies and inflate inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oral Care/Oral Hygiene Market |
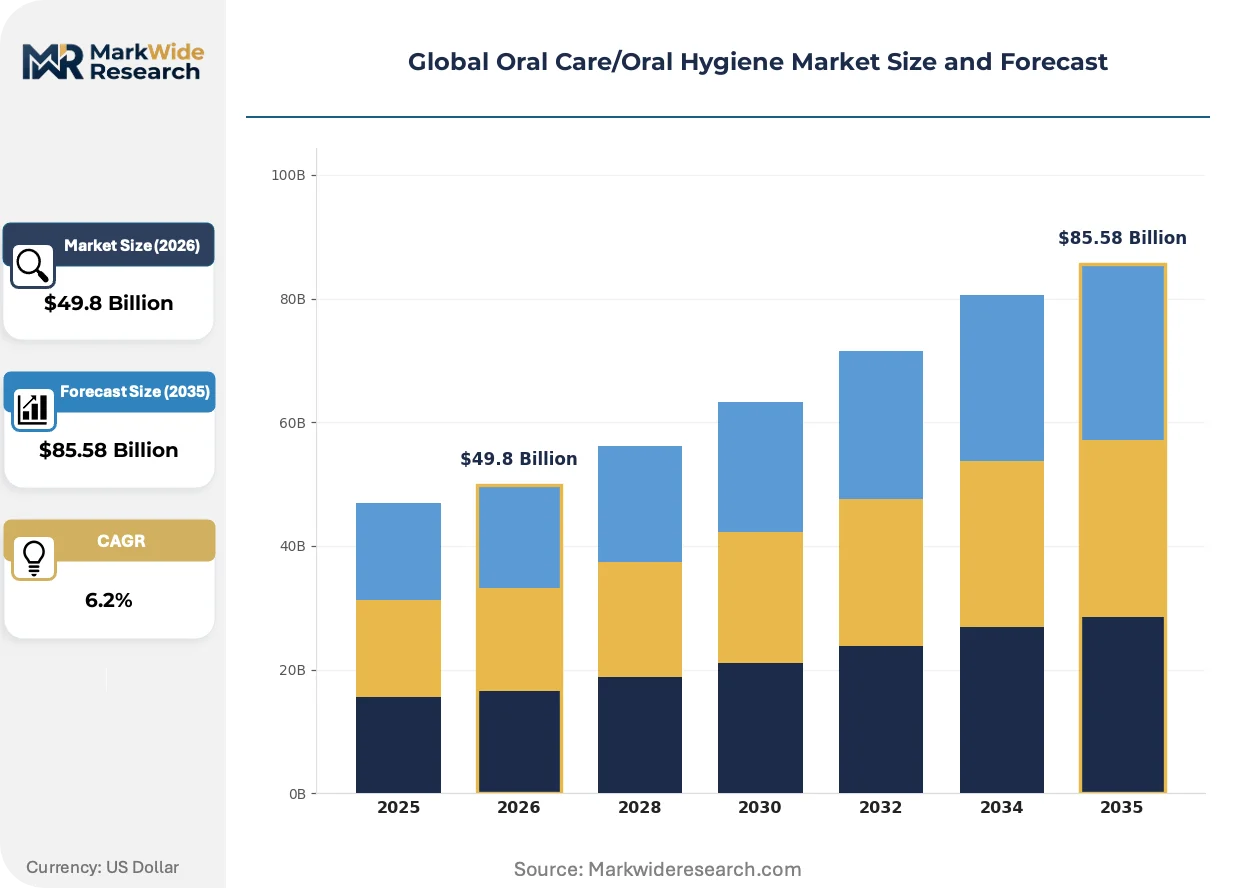
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $85.58 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Teeth Whitening Products, Breath Fresheners Technology: Activated Charcoal, Fluoride, Herbal Extracts, Enzymatic, Baking Soda, Antibacterial Application: Cavity Prevention, Gum Care, Whitening, Plaque Removal, Sensitive Teeth, Fresh Breath End User: Pharmacies, Supermarkets, Dental Clinics, Specialty Stores, E-commerce Platforms |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble, Unilever, Haleon plc, Johnson & Johnson, Church & Dwight Co., Inc., Koninklijke Philips N.V., Lion Corporation, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oral Care/Oral Hygiene Market Shifts & Advancements
Oral care is fragmenting into condition-specific solutions delivered through novel formats that bypass traditional retail gatekeepers, with technology convergence enabling personalization at previously impossible scale.
Enzymatic biofilm disruption using targeted proteases and carbohydrate-active enzymes is expanding into preventive home care from its professional dental clinic origins. Early adopters in South Korean and Dutch markets demonstrate willingness to pay premium prices for peroxide-free whitening efficacy. This expansion is compressing the addressable market for traditional bleaching strips while opening adjacent spaces for sensitivity-management positioning.
REACH framework restrictions on synthetic preservatives including parabens and formaldehyde releasers are forcing European manufacturers toward novel preservation systems using organic acids and hurdle technology. The industrial consequence is accelerated reformulation cycles and shortened product shelf lives. Natural-positioned brands in France and Germany are responding by emphasizing cold-process manufacturing and refrigerated distribution as quality differentiators.
Subscription-based replenishment with AI-driven usage tracking is replacing episodic retail purchasing among urban professionals in the United States and United Kingdom. Smart brush heads with embedded sensors transmit wear data to mobile applications that trigger automatic pod shipments. This behavioral shift is most visible in millennial and Generation Z demographics, where brand loyalty now attaches to convenience architecture rather than advertising equity.
Global Oral Care/Oral Hygiene Market Segmentation
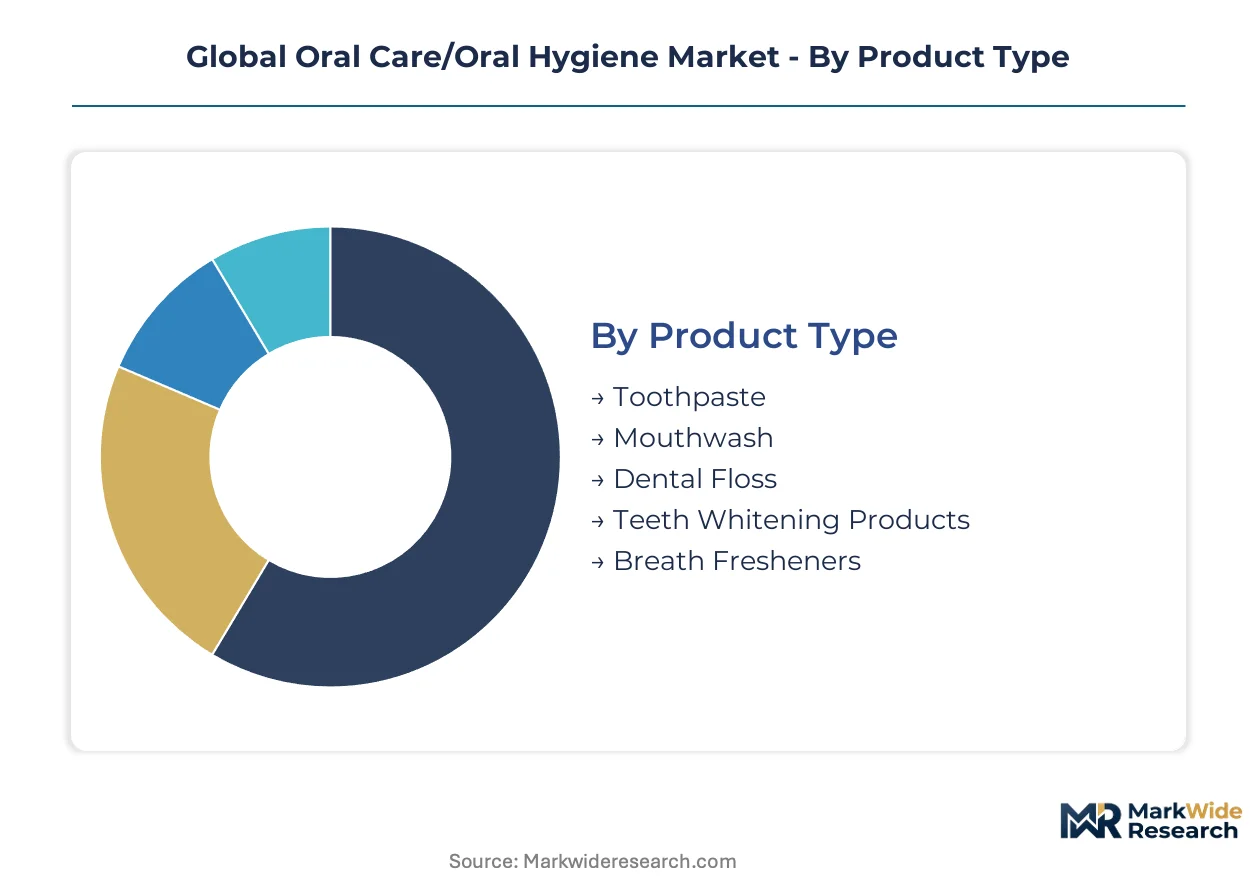
Oral care manufacturers configure production assets around distinct formulation chemistries and channel economics. Segmentation choices determine regulatory compliance pathways, margin capture, and the feasibility of direct-to-consumer pivots.
Product Type:
Supply concentration varies sharply by format, with tube-filling infrastructure dominating capital deployment decisions across manufacturing networks.
- Toothpaste:Abrasive pastes containing hydrated silica or calcium carbonate below 20% by weight, delivered via laminated tubes or pump dispensers. Volume concentrates in Indian and Brazilian mass retail as households systematize preventive routines beyond basic fluoride. Supply chains favor incumbent filling line operators with scale advantages in pod-compatible formats.
- Mouthwash:Aqueous solutions with cetylpyridinium chloride or essential oil actives, requiring alcohol-free reformulation for Middle Eastern markets. Pharmacy channels in Germany and Japan prioritize enzymatic variants over traditional antiseptic formulations.
- Dental Floss:Waxed or unwaxed nylon filaments, expanding into biodegradable silk and corn-fiber alternatives under EU Green Deal packaging mandates.
- Teeth Whitening Products:Peroxide gels and enzymatic strips capturing disproportionate margin pools in specialty retail and subscription channels.
- Breath Fresheners:Spray, strip, and lozenge formats concentrated in impulse-purchase retail and travel retail environments.
Today's leader: Toothpaste. Tomorrow's challenger: Teeth Whitening Products.
Technology:
Cost tier stratification separates premium enzymatic positioning from mass-market fluoride standardization.
- Activated Charcoal:Carbon-based abrasives with high surface area for adsorptive cleaning, plateauing in mature markets as clinical substantiation gaps persist.
- Fluoride:Sodium fluoride and stannous fluoride systems governed by FDA monograph compliance, with supply concentration among three global active suppliers creating vulnerability.
- Herbal Extracts:Neem, clove, and tea tree oil formulations dominant in Indian Ayurvedic-positioned brands seeking BIS cosmetic safety registration.
- Enzymatic:Glucose oxidase and lactoperoxidase systems gaining pharmacy shelf space in Germany and Japan as sensitivity-conscious consumers reject peroxide bleaching. Premium positioning commands 2-3x mass-market pricing.
- Baking Soda:Sodium bicarbonate abrasives with pH-neutralizing properties, concentrated in value-tier North American retail.
- Antibacterial:Triclosan-restricted formulations pivoting to stannous fluoride and CPC alternatives under REACH framework constraints.
Enzymatic technology is climbing the fastest; fluoride remains the volume anchor.
Application:
Customer type fragmentation drives condition-specific SKU proliferation beyond all-in-one positioning.
- Cavity Prevention:Fluoride-based chemotherapeutic intervention targeting pediatric and geriatric demographics with elevated caries risk.
- Gum Care:Periodontal maintenance formulations with stannous fluoride or essential oils, underdeveloped outside established pharmacy-channel portfolios.
- Whitening:Peroxide and enzymatic systems capturing professional-treatment-adjacent demand in direct-to-consumer channels.
- Plaque Removal:Mechanical and chemical biofilm disruption combining abrasives with surfactant systems.
- Sensitive Teeth:Potassium nitrate and arginine formulations addressing dentin hypersensitivity in aging populations.
- Fresh Breath:Zinc ion and essential oil systems targeting volatile sulfur compound neutralization.
Gum Care represents the most underdeveloped specialist opportunity.
End User:
Geography determines channel viability, with regulatory divergence fragmenting distribution strategies.
- Pharmacies:Professional-adjacent positioning requiring clinical substantiation, dominant in German and Japanese markets with stringent efficacy labeling standards.
- Supermarkets:Mass retail slotting-fee economics favoring incumbent scale and multi-format bundling.
- Dental Clinics:Professional dispensing of premium preventive products expanding as chairside retail captures margin from procedure adjacencies.
- Specialty Stores:Curated natural and premium positioning with refrigerated distribution for cold-process formulations.
- E-commerce Platforms:Subscription-based replenishment with AI-driven usage tracking, concentrated in US and UK urban professional demographics.
E-commerce Platforms are expanding most quickly; Pharmacies retain the premium margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern oral care manufacturing traces its industrial lineage to 19th-century American soap-making operations that diversified into dentifrice production, with subsequent scaling in German chemical engineering hubs and Japanese precision manufacturing clusters.
United States
Subscription-based replenishment with AI-driven usage tracking concentrates in urban professional demographics across New York and Los Angeles. FDA monograph rules govern over-the-counter fluoride claims, requiring multi-year caries reduction studies for new delivery mechanisms. Greater Boston anchors enzymatic technology development with proximity to MIT and Harvard dental research centers.
Germany
Pharmacy-channel dominance drives demand for peroxide-free enzymatic whitening systems in Berlin and Munich metropolitan areas. REACH framework restrictions on synthetic preservatives force accelerated reformulation cycles toward organic acid preservation. The Rhine-Ruhr industrial corridor hosts specialized filling line manufacturers serving pod-based format transitions.
Japan
Sensitivity-conscious consumers in Tokyo and Osaka reject traditional bleaching agents in favor of glucose oxidase formulations. METI and PMDA enforce distinct efficacy labeling standards that extend product registration timelines for imported formulations. The Kansai region concentrates precision molding capacity for smart brush head sensor integration.
India
Middle-class households in Mumbai and Bangalore shift from single-item fluoride paste toward bundled preventive regimens including mouth rinse and interdental cleaning. BIS cosmetic safety compliance mandates 2022 registration requirements that consolidate share for documented manufacturers. Gujarat hosts the largest tube-filling infrastructure serving domestic and export markets.
Brazil
Systematized oral care adoption accelerates in São Paulo and Rio de Janeiro as households upgrade from basic fluoride pastes to complete care systems. ANVISA registration pathways shape which formulation portfolios enter profitably. The São Paulo state industrial belt concentrates laminated tube manufacturing for Latin American distribution.
Global Oral Care/Oral Hygiene Market Competitive Landscape
Premium-margin players sit above commodity-margin players across enzymatic technology and pharmacy-channel positioning versus mass retail fluoride standardization. The market structure consolidates around three global conglomerates with manufacturing scale advantages in refill pod distribution, while mid-tier brands struggle to absorb legacy filling line retrofit costs for thermoformed pod transitions. Strategic archetypes include enzymatic technology specialists, pharmacy-channel gum care anchors, and direct-to-consumer subscription architects. Dominant competitive moves encompass strategic partnerships with smart hardware manufacturers and portfolio diversification into condition-specific solutions.
Within the manufacturing conglomerate tier, Colgate-Palmolive Company and Procter & Gamble exemplify scale-driven positioning across North American mass retail and subscription channels. Haleon plc occupies a specialized position in pharmacy-channel periodontal maintenance portfolios. Among Asia-Pacific-based operators, Lion Corporation represents regional enzymatic technology adaptation for sensitivity-conscious demographics.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble |
| Unilever |
| Haleon plc |
| Johnson & Johnson |
| Church & Dwight Co., Inc. |
| Koninklijke Philips N.V. |
| Lion Corporation |
| Henkel AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Gujarat and São Paulo state anchor tube-filling capacity while exercising pricing discipline against private-equity-rolled-up refill pod competitors. Their retained earnings finance incremental capacity without debt-service pressure, insulating mass-market fluoride tiers from subscription-channel price erosion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enzymatic pharmacy-positioned SKUs from mass retail fluoride tubes and unbranded refill pods. Price differentiation rests on certification tier—FDA monograph compliance versus BIS cosmetic safety registration versus unregulated gray-market imports. Pricing pressure stems from EU Green Deal packaging mandates forcing aluminum-free tube conversions. Price-sensitive Brazilian and Indian households gravitate toward economy fluoride tiers, while German pharmacy channels absorb premium enzymatic markups without volume elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for laminated tube stock, while dental clinic dispensing captures premium preventive margins. Geographic supply concentrates in India, Brazil, and Germany, with Gujarat hosting dominant tube-filling infrastructure and the Rhine-Ruhr corridor supplying specialized pod thermoforming equipment. Raw material dependencies include stannous fluoride from three concentrated suppliers, hydrated silica abrasives, and water-soluble film substrates. Single-source vulnerability in antibacterial actives threatens formulation continuity. Distribution runs through supermarket slotting-fee networks, pharmacy wholesale cooperatives, and AI-driven subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Oral Care/Oral Hygiene Market functions as a regulatory compounder where EU Green Deal chemical disclosure rules and BIS cosmetic safety mandates continuously consolidate share toward documented manufacturers.
For Market Incumbents: Deepen enzymatic technology R&D partnerships with MIT and Harvard dental research centers to defend pharmacy-channel positioning against peroxide-free whitening substitutes. Expand captive stannous fluoride supply agreements to mitigate three-supplier concentration risk. Accelerate thermoformed pod line retrofits in North American facilities before mid-tier competitors achieve scale. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription bundling with smart dispensing hardware, targeting underdeveloped periodontal maintenance portfolios outside Haleon's established pharmacy presence. India's BIS registration requirements create consolidation tailwinds for documented manufacturers willing to absorb compliance timelines. White-space concentrates in post-surgical gum care regimens and sensitivity-conscious enzymatic formulations for Japanese and German demographics. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier brands stranded with legacy extruded tube infrastructure and insufficient capital for pod-system transitions. Long-term viability favors operators with backward-integrated active ingredient supply or exclusive pharmacy-channel access. The signal to watch is ANVISA registration acceleration in Brazil as a proxy for Latin American portfolio profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Technology Licensing | Glucose oxidase formulations capture German pharmacy shelf space from peroxide competitors. |
| Direct-to-Consumer Subscription Launch | AI-driven replenishment with smart brush heads builds millennial brand loyalty beyond advertising equity. |
| Aluminum-Free Tube Conversion | EU Green Deal recyclability mandates create first-mover advantages for compliant European suppliers. |
| Pharmacy-Channel Gum Care Expansion | Periodontal maintenance portfolios target post-surgical patients with professional-adjacent positioning. |
| Backward Integration into Active Supply | Captive stannous fluoride production mitigates three-supplier concentration vulnerability for antibacterial formulations. |
Research Methodology
Direct dialogue with brand managers, category buyers at mass retailers, pharmacy procurement leads, and supply planners at tube-filling operators grounded qualitative findings. Secondary validation drew from FDA monograph filings, ECHA REACH restriction updates, BIS cosmetic safety registrations, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates from national statistical offices.
Bottom-up modeling segmented the market by product type, technology platform, application indication, and end-user channel across the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by base-year revenue contributions. Forecast inputs incorporated EU Green Deal implementation timelines, BIS registration completion rates, and enzymatic technology adoption curves in German and Japanese pharmacy channels.
Inputs from regulatory filing databases and retail audit panels were available through the study window; gaps in private-label subscription channel volume introduce uncertainty bands around direct-to-consumer growth trajectories. Forecasts reflect documented assumptions regarding REACH framework enforcement consistency and ANVISA pathway stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Europe Oral Hygiene Market
Oral Care
Global Oral Care Products Market
Oral Care
China Oral Care Market
Oral Care
South America Oral Care Market
Oral Care
BRICS Oral Care Market
Oral Care
Adult Oral Care Products Market
Oral Care
United States Oral Hygiene Market
Oral Care
Oral Thin Films Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Oral Rinse Market
Oral Care
Oral Care Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Us Oral Care Market
Oral Care
Oral Health Ingredient Market
Oral Care
Herbal Toothpaste Market