
 Toothcare Market | 2026-2036
Toothcare Market Size, Share, and Industry Trends Forecast 2026-2036
Toothcare Market Analytics
Pharmacy retail is rewriting competitive access rules for oral care brands. Colgate-Palmolive Company leverages its shelf-space dominance to sustain volume leadership in mass-market toothpaste. Procter & Gamble Company anchors premium positioning through its whitening portfolio across drugstore and supermarket chains. Unilever PLC differentiates via specialized gum-health formulations that command higher margins in pharmacy channels.
Toothcare encompasses formulations and devices designed to clean, protect, and maintain oral structures, including dentifrices containing abrasives such as hydrated silica at 15-20% concentration, fluoride compounds for enamel remineralization, and mechanical tools with specified bristle stiffness ratings. Toothpaste remains the largest revenue pool, though whitening applications within the segment attract disproportionate margin investment. Mouthwash competes on clinical endorsement frequency, while sensitivity relief products target an aging customer base with higher willingness to pay for functional claims.
The FDA regulates fluoride concentration limits and therapeutic claim substantiation for oral care products sold in the United States. ECHA enforces REACH compliance on surfactant and preservative chemistries entering European markets, raising reformulation costs for exporters. ISO 11609 governs toothpaste abrasivity testing methods that manufacturers must satisfy for market access across multiple jurisdictions. Stakeholders must monitor evolving state-level packaging mandates and ingredient disclosure rules that will determine which product architectures survive channel compliance audits.
Market Dynamics
The EU Green Deal is forcing mass-market toothpaste manufacturers to abandon sodium lauryl sulfate and synthetic microplastics ahead of 2030 deadlines, triggering a reformulation race that favors suppliers with biodegradable surfactant pipelines.
Growth Catalysts
- REACH compliance deadlines:European manufacturers accelerating biodegradable ingredient R&D to meet ECHA-mandated surfactant phase-outs by 2030.
- Pediatric oral care specialization:Family demand for preventive fluoride varnishes and child-formulated dentifrices expanding prescription-channel volumes.
- Sensitivity relief formulations:Aging populations in Japan and Germany driving potassium nitrate and stannous fluoride adoption in pharmacy retail.
Market Restraints
- Fluoride supply concentration:Chinese and Moroccan phosphate rock deposits dominate active ingredient sourcing, exposing formulators to export quota volatility.
- Abrasivity testing costs:ISO 11609 compliance requires specialized profilometry equipment that small manufacturers cannot amortize across limited SKU counts.
- Biodegradable packaging premiums:Sugarcane-derived tubes and aluminum jars carry 40-60% cost premiums over conventional multilayer plastics.
Strategic Opportunities
- Indian pharmacy modernization:Organized retail chains in Mumbai and Bangalore creating dedicated oral care aisles for premium sensitivity and whitening portfolios.
- Subscription direct-to-consumer models:Refillable glass jar systems with concentrated tablet dentifrices bypassing traditional supermarket slotting fees.
- AI-driven personalization:Smartphone-connected brushing apps generating custom fluoride and abrasive recommendations based on enamel thickness scans.
Industry Challenges
- Green chemistry talent scarcity:Formulators with expertise in plant-derived surfactants and natural preservatives command premium compensation in Basel and Rotterdam clusters.
- Dual regulatory filing timelines:Separate FDA therapeutic claim substantiation and ECHA REACH dossier preparation extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toothcare Market |
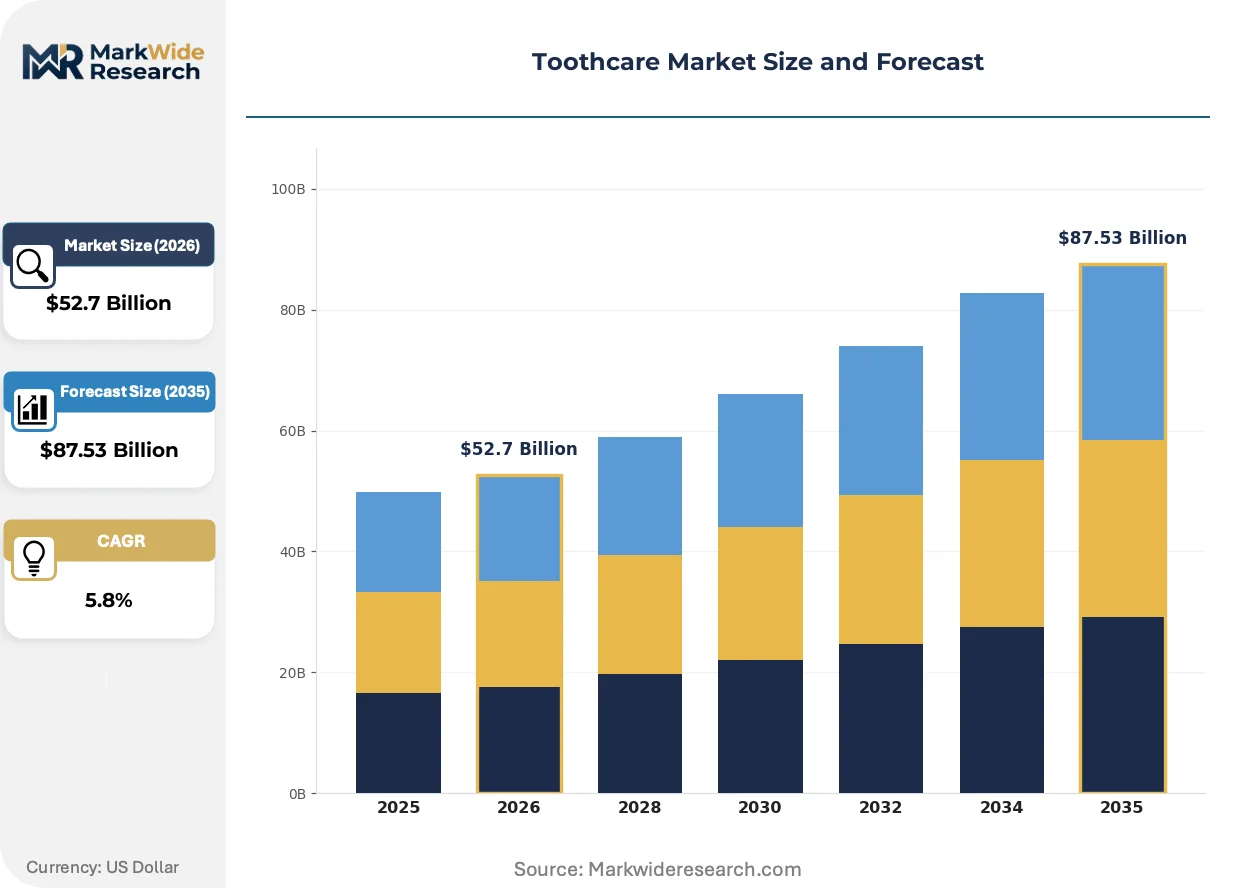
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $87.53 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Toothbrushes, Mouthwash, Floss Application: Daily Care, Whitening, Sensitivity Relief, Gum Health Customer Type: Families, Adults, Children, Seniors Distribution Channel: Online Retail, Drugstores, Supermarkets, Specialty Stores |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble Company, Johnson & Johnson Services Inc., Haleon PLC, Unilever PLC, Church & Dwight Co., Inc., Lion Corporation, GlaxoSmithKline Plc., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toothcare Market Evolving Landscape
Formulation chemistry and distribution architecture are diverging sharply as sustainability mandates collide with pharmacy-channel consolidation. Three developments are compressing legacy operating models.
Hydroxyapatite remineralization systems are replacing conventional fluoride in premium European and Japanese dentifrices. Boutique oral care brands in Paris and Tokyo are adopting the biomimetic mineral at 10-15% concentrations for enamel repair claims. Synthetic fluoride dominance is rendering obsolete in segments where biomimetic marketing commands shelf-space premiums.
ECHA's 2024 update to REACH Annex XVII restricted microplastic additives in rinse-off cosmetics, capturing polyethylene beads and certain film-forming polymers used in whitening toothpastes. German and Dutch manufacturers are reformulating with cellulose-based abrasives and natural waxes to maintain market access. Pharmacy buyers in Hamburg and Amsterdam are now screening supplier portfolios for pre-registered biodegradable alternatives ahead of enforcement.
Consumers are unbundling professional cleaning from daily maintenance, purchasing ultrasonic scalers and interdental cameras for home plaque monitoring. Dental e-commerce platforms in Seoul and São Paulo are aggregating these devices with subscription paste refills, compressing traditional six-month recall cycles. This behavioral shift is most pronounced in urban South Korean households where tele-dentistry consultations validate home hygiene metrics.
Toothcare Market Segmentation
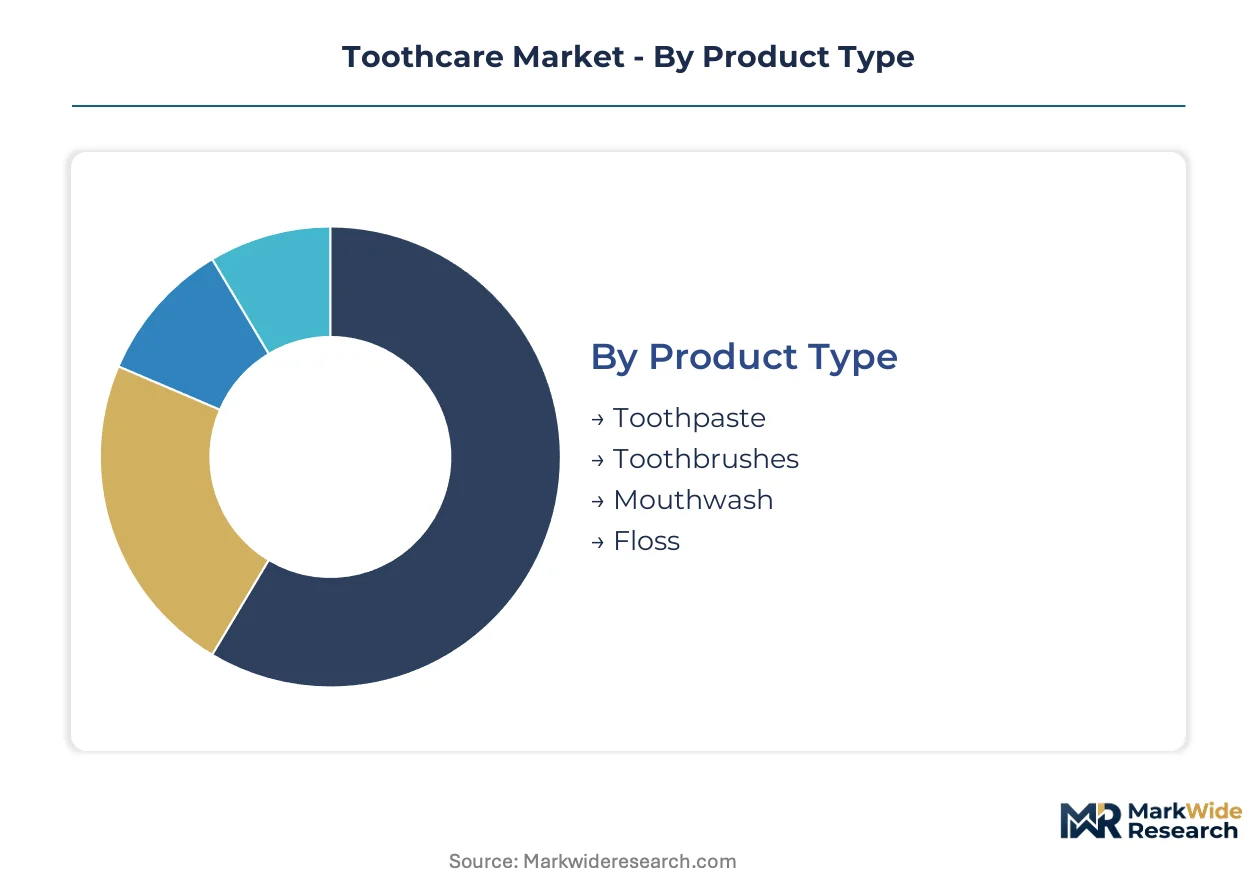
Toothcare manufacturers architect product portfolios around distinct usage occasions and buyer economics. Segmentation discipline determines which formulations justify premium pricing versus mass-market volume plays.
Product Type:
Cost tier separates commodity staples from margin-accretive innovations across oral care portfolios.
- Toothpaste:Formulations incorporate hydrated silica abrasives at 15-20% concentration alongside fluoride compounds for enamel remineralization. Pharmacy retail in the United States concentrates demand for premium whitening and sensitivity-relief variants that command higher margins than standard daily care.
- Toothbrushes:Mechanical tools specify bristle stiffness ratings and ergonomic handle geometries for differentiated positioning. Japanese and German consumers drive replacement cycle compression through subscription models and smart-connected brushing systems.
- Mouthwash:Clinical endorsement frequency determines competitive positioning in pharmacy channels. ECHA REACH compliance on surfactant chemistries is forcing reformulation toward biodegradable alternatives ahead of enforcement deadlines.
- Floss:Waxed and unwaxed nylon or PTFE filaments target interdental cleaning precision. Urban households in South Korea and Brazil are adopting water flosser substitutes that bundle with tele-dentistry platforms.
Toothpaste holds installed capacity. Mouthwash is rotating up the share rankings.
Application:
Functional claims reshape procurement patterns as consumers trade up from basic hygiene to therapeutic outcomes.
- Daily Care:Standard fluoride dentifrices and manual brushes address baseline plaque removal and cavity prevention. Supermarket chains in India and the United States anchor volume through promotional bundling and private-label substitution.
- Whitening:Peroxide-based gels and abrasive polishing systems target extrinsic stain removal. ECHA's microplastic restrictions are capturing polyethylene beads used in legacy formulations, forcing German and Dutch manufacturers toward cellulose-based alternatives.
- Sensitivity Relief:Potassium nitrate and stannous fluoride formulations block dentinal tubule transmission. Aging populations in Japan and Germany are expanding pharmacy-channel prescriptions for these therapeutic-positioned products.
- Gum Health:Antiseptic rinses and specialized toothpastes target gingivitis reduction with clinical substantiation requirements. Unilever PLC commands margin premiums through formulations that satisfy FDA therapeutic claim standards.
Sensitivity Relief is gaining share fastest. Daily Care retains volume dominance.
Customer Type:
Life-stage targeting aligns fluoride concentration, flavor profiles, and packaging safety with distinct household needs.
- Families:Multi-unit packs and flavor variety bundles optimize household economics. Organized retail chains in Mumbai and Bangalore are creating dedicated oral care aisles for family-oriented preventive portfolios.
- Adults:Individual purchasers prioritize convenience formats and professional-grade efficacy claims. Subscription direct-to-consumer models with refillable glass jar systems are bypassing traditional supermarket slotting fees.
- Children:Lower fluoride concentrations and novelty flavors address safety and compliance concerns. Pediatric oral care adoption is expanding among families seeking preventive fluoride varnishes and child-formulated dentifrices.
- Seniors:Dry-mouth formulations and grip-adapted tools address age-related oral health degradation. Pharmacy retail in Germany and Japan concentrates demand for specialized sensitivity and gum-health solutions.
Adults hold installed capacity. Seniors are climbing the fastest.
Distribution Channel:
Channel economics determine whether brands pursue shelf-space dominance or bypass retail intermediaries entirely.
- Online Retail:Dental e-commerce platforms in Seoul and São Paulo aggregate devices with subscription paste refills. AI-driven personalization through smartphone-connected brushing apps is generating custom fluoride recommendations.
- Drugstores:Pharmacy retail rewrites competitive access rules through clinical endorsement requirements and pharmacist recommendation protocols. Colgate-Palmolive Company leverages shelf-space dominance to sustain volume leadership.
- Supermarkets:Mass-market toothpaste moves through promotional cycles and end-cap placement. Procter & Gamble Company anchors premium positioning through whitening portfolios across drugstore and supermarket chains.
- Specialty Stores:Boutique oral care brands in Paris and Tokyo adopt hydroxyapatite remineralization systems at 10-15% concentrations. Biomimetic marketing commands shelf-space premiums in segments where synthetic fluoride dominance is rendering obsolete.
Drugstores hold installed capacity. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium whitening and sensitivity-relief formulations command 40-60% price premiums in United States pharmacy retail versus mass-market daily care in Indian supermarket chains. This pricing-power asymmetry reflects divergent regulatory pathways and channel consolidation patterns across developed and emerging markets.
United States
FDA therapeutic claim substantiation requirements concentrate premium whitening and sensitivity-relief portfolios in pharmacy retail channels. The agency's fluoride concentration limits and clinical endorsement standards elevate compliance costs for new entrants. Colgate-Palmolive and Procter & Gamble leverage shelf-space dominance across drugstore and supermarket chains in metropolitan corridors from New York to Los Angeles.
Germany
Aging demographics in Hamburg and Munich drive pharmacy-channel demand for potassium nitrate and stannous fluoride formulations. ECHA's REACH Annex XVII microplastic restrictions force reformulation of legacy whitening products containing polyethylene beads. Manufacturers in the Rhine-Ruhr cluster accelerate biodegradable surfactant R&D to meet 2030 compliance deadlines.
Japan
Senior households in Tokyo and Osaka expand prescription-channel volumes for dry-mouth and gum-health solutions. METI standards govern connected brushing device interoperability and data privacy for AI-driven personalization platforms. Lion Corporation anchors domestic production of specialized sensitivity formulations targeting aging consumers.
India
Organized retail chains in Mumbai and Bangalore create dedicated oral care aisles for family-oriented preventive portfolios. BIS standards on fluoride concentration and packaging safety govern domestic manufacturing compliance. Multi-unit packs and flavor variety bundles optimize household economics in emerging middle-class segments.
Brazil
Dental e-commerce platforms in São Paulo aggregate ultrasonic scalers and interdental cameras with subscription paste refills. ANVISA regulates therapeutic claims and active ingredient concentrations for products entering pharmacy channels. Tele-dentistry consultations validate home hygiene metrics in urban households compressing traditional recall cycles.
Toothcare Market Competitive Landscape
Multinational consumer goods conglomerates and specialized oral care manufacturers split the market between mass-market volume plays and premium therapeutic positioning. Pharmacy retail consolidation favors incumbents with established shelf-space relationships and clinical endorsement frequencies. Three archetypes dominate: diversified personal care conglomerates with oral care divisions, pure-play dental specialists with prescription-channel focus, and emerging direct-to-consumer brands bypassing traditional retail intermediaries. Competitive moves concentrate on biodegradable ingredient reformulation and subscription model deployment.
Within the diversified conglomerate tier, Colgate-Palmolive Company and Procter & Gamble Company exemplify mass-market and premium positioning strategies respectively. Unilever PLC occupies a position emphasizing specialized gum-health formulations that command margin premiums in pharmacy channels. Haleon PLC represents the pharmaceutical-origin archetype with clinical substantiation capabilities for therapeutic claims.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble Company |
| Johnson & Johnson Services Inc. |
| Haleon PLC |
| Unilever PLC |
| Church & Dwight Co., Inc. |
| Lion Corporation |
| GlaxoSmithKline Plc. |
| Koninklijke Philips N.V. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese phosphate rock processing is squeezing margins across fluoride active ingredient supply, forcing formulators to absorb cost volatility while pharmacy retail chains extract slotting fee concessions. This utilization imbalance rewards incumbents with backward integration into Moroccan mineral deposits while pressuring mid-tier brands toward private-label erosion.
Pricing Analysis
The customization-premium spread between standard daily-care toothpaste and configured therapeutic formulations spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on clinical endorsement frequency and ECHA REACH pre-registration status for biodegradable surfactants. Cost compression in mass-market tiers is intensifying because supermarket private-label substitution accelerates during promotional cycles. Family households in India exhibit highest price sensitivity, while aging consumers in Germany and Japan demonstrate lowest sensitivity for potassium nitrate sensitivity-relief variants.
Supply Chain Analysis
Extended payment terms from European pharmacy retail chains are forcing Chinese and Moroccan fluoride suppliers to absorb working capital strain through supply-chain finance facilities. Raw material dependencies center on phosphate rock concentrates, hydrated silica abrasives, and biodegradable surfactant feedstocks. Single-source vulnerability concentrates in Chinese export quota administration for fluoride compounds. Distribution runs through pharmacy retail consolidation in developed markets and organized retail chain expansion in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
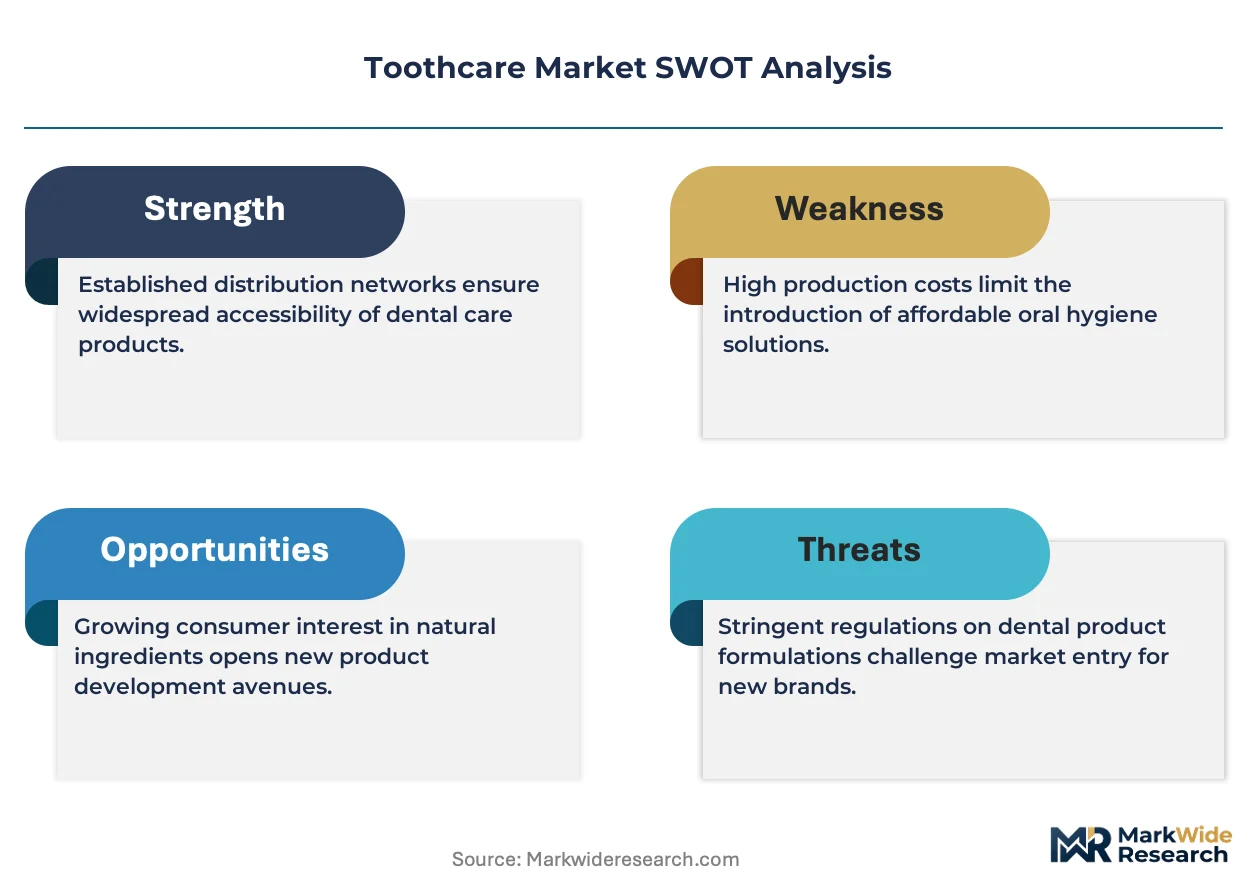
The toothcare market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA therapeutic claim substantiation and ECHA REACH dossier requirements create 18-24 month barriers to competitive entry.
For Market Incumbents: Insulate market position by accelerating captive supply of biodegradable surfactants ahead of 2030 ECHA deadlines, while securing exclusive pharmacist recommendation protocols in German and Japanese pharmacy chains against direct-to-consumer subscription entrants. Capacity addition in Moroccan fluoride processing hedges Chinese export quota volatility. For New Entrants and Emerging Players: Pursue white-space opportunity in Indian organized retail pharmacy modernization, where dedicated oral care aisles in Mumbai and Bangalore lack premium sensitivity and whitening portfolios. Tele-dentistry bundled device-and-consumable models in Brazilian urban households offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward boutique oral care specialists with hydroxyapatite formulation expertise and pre-registered REACH biodegradable ingredient pipelines. Long-term viability across the projection horizon favors assets with clinical endorsement frequency and pharmacist channel relationships. The signal to monitor is ECHA enforcement acceleration on microplastic restrictions, which would compress legacy formulation valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Transition | ECHA REACH compliance secures European pharmacy channel access against 2030 enforcement deadlines. |
| Pharmacy Retail Consolidation | Exclusive shelf-space agreements with German and Japanese chains lock out subscription competitors. |
| Direct-to-Consumer Subscription Launch | Refillable glass jar systems bypass supermarket slotting fees and capture adult convenience demand. |
| Tele-dentistry Platform Partnership | Brazilian and South Korean dental e-commerce integration validates home hygiene metrics and compresses recall cycles. |
| Hydroxyapatite Formulation Investment | Biomimetic mineral adoption at 10-15% concentrations commands shelf-space premiums in Paris and Tokyo specialty retail. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at multinational consumer goods conglomerates, pharmacy retail category buyers, regulatory affairs specialists navigating FDA and ECHA filing pathways, and procurement leads at fluoride active ingredient suppliers, then refined against secondary validation from FDA 510(k) filings, ECHA REACH registration databases, customs trade records for phosphate rock concentrates, and Nielsen retail audit data for oral care shelf-space allocation. Bottom-up SKU-level volume builds were triangulated with top-down category spend estimates across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation modeled across product type, application, customer life-stage, and distribution channel dimensions. CAGRs were derived from elasticity-adjusted growth trajectories incorporating pharmacy retail consolidation rates, biodegradable ingredient adoption curves, and tele-dentistry platform penetration in South Korean and Brazilian urban households.
Sensitivities concentrate around ECHA enforcement acceleration on microplastic restrictions, Chinese fluoride export quota volatility, and Indian organized retail expansion timing. Forecasts incorporate documented assumptions on regulatory pathway durations and channel migration patterns. Macroeconomic contraction, regulatory deviation, or technological disruption in AI-driven personalization platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Canker Sores Treatment Market
Oral Care
South America Oral Care Market
Oral Care
Dry Mouth Relief Market
Oral Care
Adult Oral Care Products Market
Oral Care
North America Oral Care Market
Oral Care
Baby Oral Care Market
Oral Care
Oral Irrigator Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Oral Rinse Market
Oral Care
Mouthwash Market
Oral Care
Global Halitosis Market
Oral Care
Baby Teeth Care Products Market
Oral Care
China Oral Care Market
Oral Care
Mouth Sore Medicine Market