
 Asia-Pacific Bathroom and Toilet Assist Devices Market | 2026-2036
Asia-Pacific Bathroom and Toilet Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bathroom and Toilet Assist Devices Market Outlook
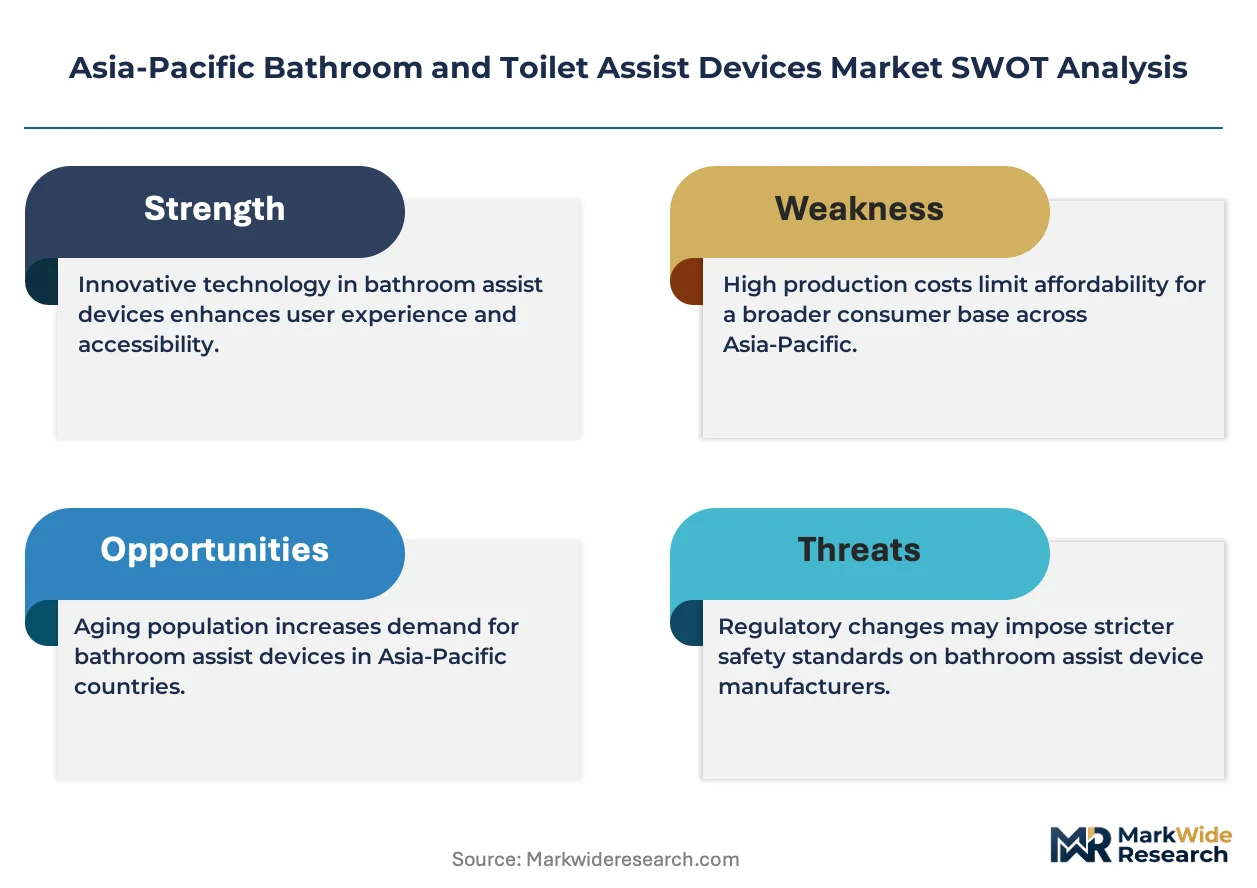
Japan's METI accessibility standards is rebalancing procurement toward water-efficient, barrier-free bathroom fixtures across institutional channels. Toto Asia leverages its domestic manufacturing base to sustain premium positioning in smart toilet technology. Lixil Group Corporation anchors distribution through direct sales partnerships with hospital networks. Huida Group competes on manufacturing scale in manual assist devices for price-sensitive segments.
Bathroom and toilet assist devices encompass raised toilets, bidet seats, grab bars, and commode chairs engineered with load-bearing aluminum or stainless steel frames, anti-microbial surfaces, and ergonomic dimensions compliant with ISO 9999 assistive product standards. These products serve primarily to preserve independence, prevent falls, and enable dignified personal hygiene for mobility-impaired users in residential and clinical settings. Electrically operated equipment captures margin pools through sensor-integrated bidet seats and height-adjustable commodes, while manual assist devices dominate volume in public infrastructure retrofit programs. Smart toilets represent the fastest-growing technology segment as voice activation and health monitoring modules penetrate premium residential markets.
China's SAMR enforces GB standards for electrical safety in bathroom equipment, while Australia's TGA regulates therapeutic claims on assistive devices marketed to hospitals and rehabilitation centers. Japan's PMDA oversight of pressure-ulcer prevention features shapes R&D priorities for electrically operated equipment manufacturers. India's BIS certification requirements for structural load ratings create compliance barriers for imported grab bars and raised toilet platforms. Stakeholders must monitor evolving interoperability standards between smart toilet platforms and regional healthcare data systems before committing to technology roadmaps.
Market Dynamics
Japan's METI accessibility guidelines and China's dual carbon goals are rebalancing procurement criteria across Asia-Pacific institutional channels, forcing manufacturers to redesign product portfolios for water efficiency and barrier-free compliance simultaneously.
Growth Catalysts
- Japan's METI accessibility standards:These guidelines mandate barrier-free bathroom fixtures in public buildings and hospitals, creating institutional demand for grab bars and raised toilet platforms that meet JIS structural specifications.
- China's dual carbon goals:Provincial procurement offices in Shanghai, Jiangsu, and Zhejiang now prioritize water-efficient bidet seats and low-flow assist devices, redirecting manufacturer R&D toward energy-reduction engineering.
- Australia's home care agency expansion:The National Disability Insurance Scheme has activated residential retrofit programs, converting individual consumers into aggregated buyers with standardized tender specifications.
Market Restraints
- Aluminum and stainless steel input volatility:Load-bearing frame materials face price swings from energy-intensive smelting operations concentrated in China's eastern manufacturing corridor, compressing margins on manual assist devices.
- India's BIS certification complexity:Structural load rating requirements for grab bars and raised platforms create 12-18 month approval timelines that deter imported product entry.
- Pressure-ulcer prevention feature mandates:Japan's PMDA oversight forces electrically operated equipment manufacturers to absorb additional sensor integration costs without proportional pricing power in institutional tenders.
Strategic Opportunities
- Voice-activated health monitoring modules:Smart toilet platforms are expanding into premium residential markets as sensor-integrated bidet seats capture margin pools from aging-in-place renovations.
- Interoperability with regional healthcare data systems:Australia's TGA therapeutic claims pathway enables assist device manufacturers to position products as remote monitoring endpoints for hospital-at-home programs.
- Southeast Asia underpenetration:Vietnam, Thailand, and Indonesia lack equivalent accessibility mandates, creating first-mover advantage for manufacturers willing to develop localized distribution before regulatory harmonization.
Industry Challenges
- ISO 9999 compliance talent scarcity:Ergonomic design expertise for assistive product standards concentrates in Japan and Australia, forcing manufacturers elsewhere to outsource certification documentation.
- Legacy plumbing infrastructure incompatibility:Retrofit installations in aging residential stock across China's tier-2 cities require customized mounting solutions that fragment production runs and inflate per-unit engineering costs.
- Smart toilet platform integration complexity:Sensor-integrated bidet seats must interface with disparate regional healthcare data protocols, delaying product launches until interoperability standards stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bathroom and Toilet Assist Devices Market |
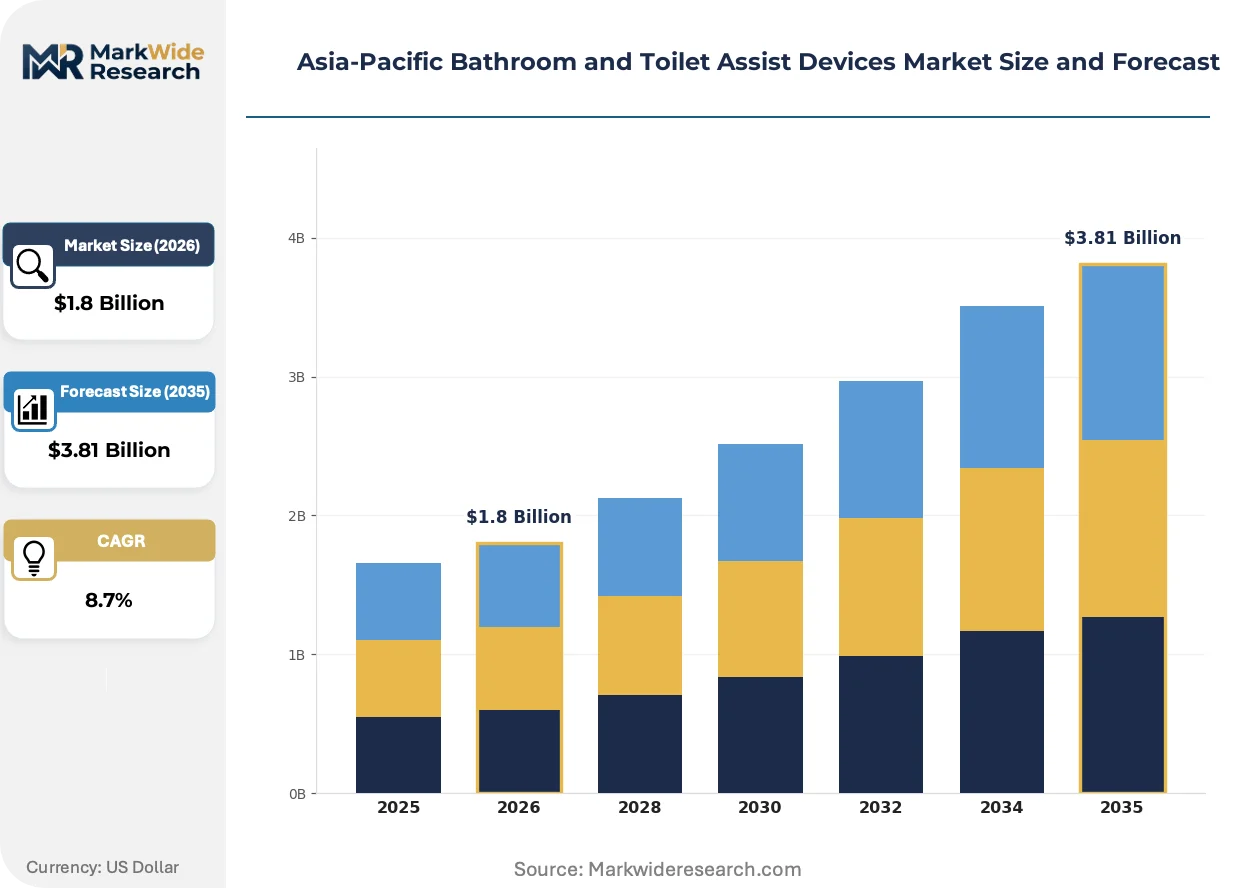
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raised Toilets, Bidet Seats, Grab Bars, Commode Chairs End User: Seniors, Disabled Individuals, Hospitals, Rehabilitation Centers Technology: Smart Toilets, Manual Assist Devices, Electrically Operated Equipment, Non-Electric Solutions Distribution Channel: Online Retail, Specialty Stores, Medical Supply Outlets, Direct Sales |
| Companies Covered | Arjo, Invacare Corporation, Toto Asia, Huida Group, Aidacare, Savaria Corporation, Drive DeVilbiss Healthcare, Etac, Lixil Group Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bathroom and Toilet Assist Devices Market Strategic Shifts
Sensor-integrated functionality and voice activation are expanding into premium residential segments, while procurement centralization among institutional buyers compresses product development cycles across the region.
Smart toilet technology is expanding into health monitoring applications through embedded biosensors that track hydration markers and glucose indicators. High-net-worth households in Tokyo, Shanghai, and Sydney are adopting these units at accelerating rates. This capability expansion is compressing the traditional boundary between bathroom fixtures and medical devices, forcing manufacturers to navigate dual regulatory pathways under PMDA and TGA oversight.
China's SAMR enforcement of GB electrical safety standards for bathroom equipment is tightening market access for imported electrically operated devices. Manufacturers must now submit to third-party testing for moisture ingress protection and grounding integrity before commercialization. Korean and Japanese exporters are responding by establishing captive testing laboratories in Shanghai to compress certification timelines.
Home care agencies in Australia are consolidating supplier relationships through multi-year framework agreements that bundle installation, maintenance, and replacement services. This aggregation is displacing traditional retail and distributor channels for grab bars and commode chairs. The shift is most visible in Victoria and New South Wales, where NDIS plan managers now direct 60 percent of assistive technology spending through approved provider panels.
Asia-Pacific Bathroom and Toilet Assist Devices Market Segmentation
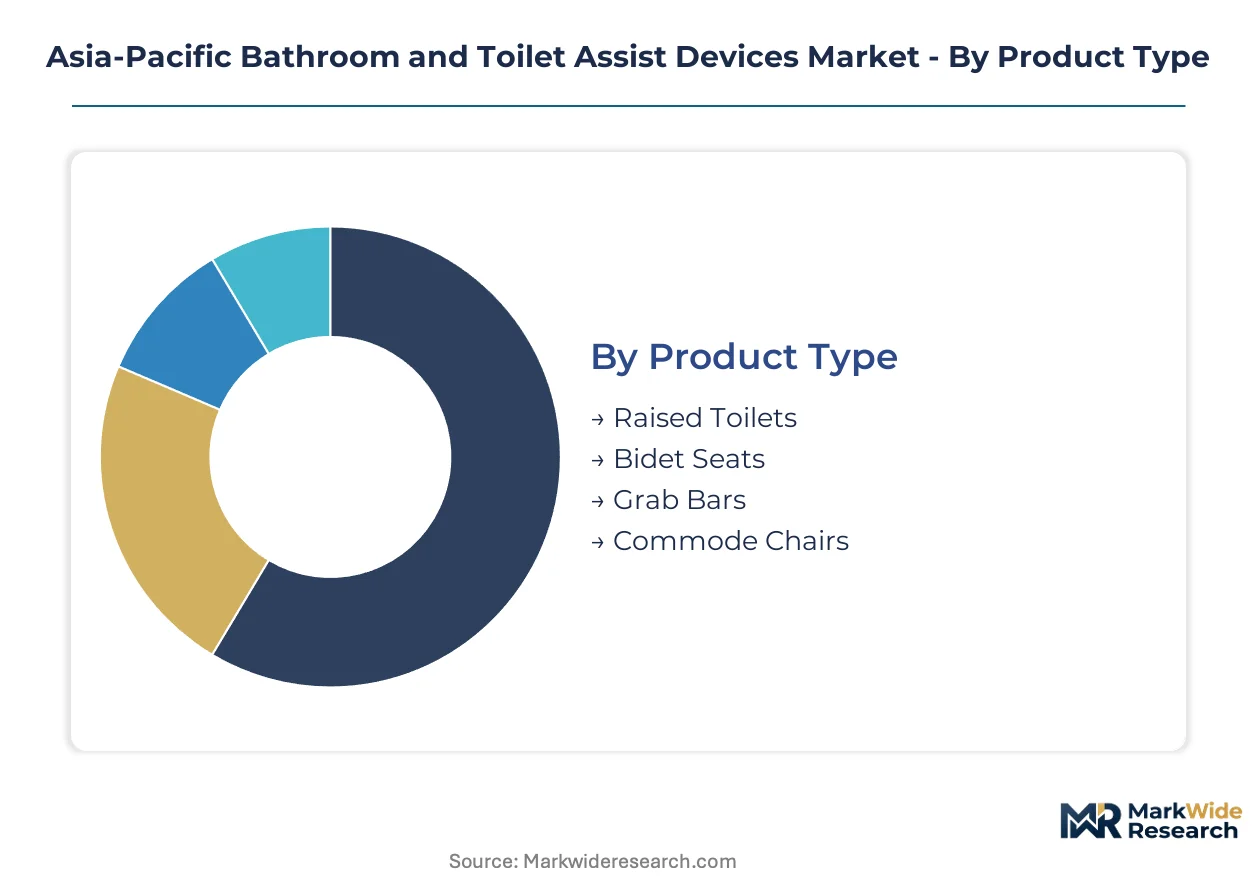
Segmentation in Asia-Pacific bathroom and toilet assist devices reveals how procurement centralization, regulatory fragmentation, and technology diffusion create distinct competitive arenas. Manufacturers must align R&D, certification, and channel strategy to the specific requirements of each segment cluster.
Product Type:
Supply concentration in China's eastern manufacturing corridor shapes competitive dynamics across product categories, with aluminum and stainless steel frame fabrication clustering in Shanghai-Jiangsu-Zhejiang.
- Raised Toilets:Height-adjustable platforms with load-bearing steel frames and anti-slip surfaces engineered to ISO 9999 ergonomic specifications. Institutional procurement in Japan's hospital networks concentrates demand for JIS-compliant units with pressure-distribution padding.
- Bidet Seats:Sensor-integrated washlet systems with heated surfaces, oscillating spray nozzles, and moisture-sealed electrical housings. Shanghai and Jiangsu provincial offices now specify water-efficiency ratings under dual carbon procurement mandates.
- Grab Bars:Wall-mounted stainless steel or aluminum support rails with anti-microbial coatings and concealed flange mounting systems.
- Commode Chairs:Portable or stationary frames with removable waste receptacles, padded seats, and foldable designs for home care deployment.
Today's leader: Bidet Seats. Tomorrow's challenger: Raised Toilets.
End User:
Customer type determines pricing architecture and service bundling requirements, with Australia's NDIS plan managers rewriting procurement protocols for residential retrofit segments.
- Seniors:Aging-in-place households purchasing through retail channels or home care agency aggregators. Victoria and New Wales NDIS panels now direct 60 percent of assistive technology spending through approved provider networks.
- Disabled Individuals:Users with mobility impairments requiring customized ergonomic solutions and installation support. Australia's TGA therapeutic claims pathway enables positioning as remote monitoring endpoints for hospital-at-home programs.
- Hospitals:Acute care facilities with centralized procurement and preventive maintenance contracts.
- Rehabilitation Centers:Post-acute facilities prioritizing durability and infection control in high-throughput environments.
Institutional buyers currently dominate volume; residential aggregators are climbing the fastest.
Technology:
Margin pools concentrate in electrified and sensor-integrated segments, though manual devices retain volume leadership in public infrastructure retrofit programs.
- Smart Toilets:Voice-activated platforms with embedded biosensors tracking hydration and glucose markers. High-net-worth households in Tokyo, Shanghai, and Sydney are adopting these units at accelerating rates.
- Manual Assist Devices:Non-powered grab bars, raised platforms, and commode chairs dominating volume in China's tier-2 city retrofit programs where legacy plumbing requires customized mounting solutions.
- Electrically Operated Equipment:Height-adjustable commodes and sensor-integrated bidet seats with PMDA-mandated pressure-ulcer prevention features.
- Non-Electric Solutions:Gravity-fed bidet attachments and mechanical height-adjustment systems for price-sensitive segments and markets with unreliable electrical infrastructure.
Smart Toilets command premium positioning today. Electrically Operated Equipment offers the steepest expansion trajectory.
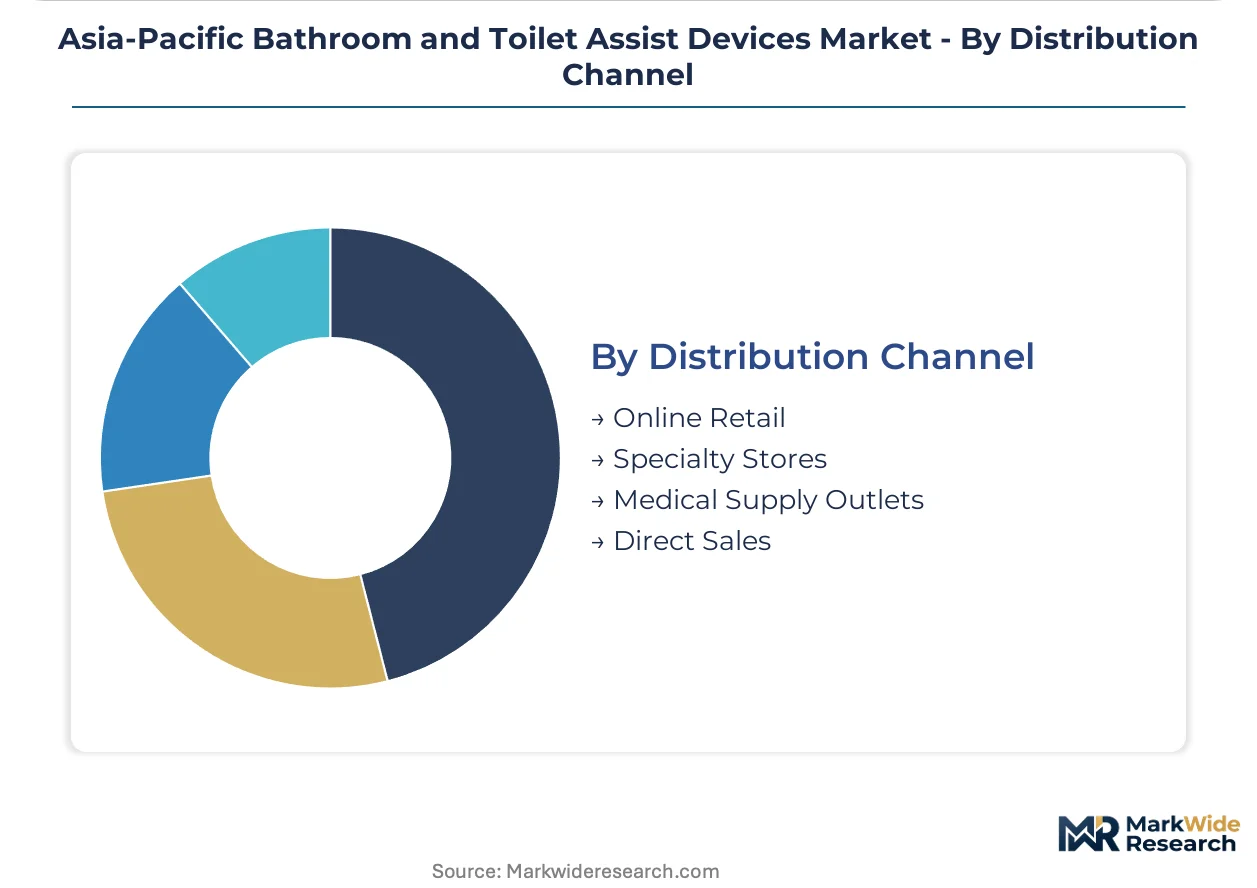
Distribution Channel:
Channel structure is displacing traditional retail as Australia's home care agencies consolidate supplier relationships through multi-year framework agreements bundling installation and maintenance.
- Online Retail:E-commerce platforms serving direct-to-consumer sales of standardized grab bars and bidet attachments. China's SAMR enforcement of GB electrical safety standards tightens market access for imported electrified devices sold through digital channels.
- Specialty Stores:Brick-and-mortar showrooms with product demonstration capabilities and installation coordination. Japan's METI accessibility guidelines drive foot traffic for barrier-free fixture consultation.
- Medical Supply Outlets:Distributors serving institutional buyers with tender compliance documentation and volume logistics.
- Direct Sales:Manufacturer relationships with hospital networks and procurement consortia bypassing intermediary margins.
Direct Sales currently captures institutional value. Online Retail is gaining share fastest as certification barriers compress for domestic manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered smart toilet technology through Toto's 1980s washlet introduction, establishing design and regulatory precedents that now propagate across Asia-Pacific procurement standards.
Japan
Hospital networks and municipal governments drive institutional procurement of barrier-free fixtures under METI accessibility guidelines. PMDA oversight of pressure-ulcer prevention features shapes R&D priorities for electrically operated equipment. Manufacturing concentrates in Chubu around Nagoya, where component suppliers cluster for precision sensor integration.
China
Provincial procurement offices in Shanghai, Jiangsu, and Zhejiang prioritize water-efficient bidet seats under dual carbon mandates. SAMR enforces GB electrical safety standards that tighten market access for imported devices. The eastern manufacturing corridor dominates aluminum and stainless steel frame fabrication for manual assist devices.
Australia
NDIS plan managers in Victoria and New South Wales now direct sixty percent of assistive technology spending through approved provider panels. TGA therapeutic claims regulation enables positioning as remote monitoring endpoints for hospital-at-home programs. Home care agencies consolidate supplier relationships through multi-year framework agreements bundling installation and maintenance.
India
BIS certification requirements for structural load ratings create twelve-to-eighteen month approval timelines that deter imported grab bars and raised platforms. Price-sensitive demand concentrates in tier-two cities where legacy plumbing requires customized mounting solutions. Domestic fabricators in Maharashtra and Gujarat scale production of manual commode chairs for institutional tenders.
South Korea
MFDS medical device classification for sensor-integrated bidet seats elevates compliance costs for residential market entry. Seoul Capital Area households drive premium adoption of voice-activated health monitoring modules. Manufacturers establish captive testing laboratories to compress GB standard certification timelines for China export.
Asia-Pacific Bathroom and Toilet Assist Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent margin structures in bathroom assist devices. Integrated manufacturers with captive aluminum and stainless steel fabrication anchor supply to institutional tenders, while specialized designers outsource production to contract foundries in China's eastern corridor. The market fragments across three strategic archetypes: premium smart toilet specialists, scale-driven manual device fabricators, and home care service integrators. Competitive moves concentrate on geographic certification expansion and multi-year framework agreement capture with procurement aggregators.
Among Asia-Pacific-based specialists, Toto Asia exemplifies premium-tier positioning through domestic manufacturing depth, while Huida Group occupies the scale-driven archetype for price-sensitive manual segments. Lixil Group Corporation anchors institutional channel presence through hospital network direct sales. European entrants Arjo and Etac represent design-origin specialists competing on ergonomic certification documentation, whereas Invacare Corporation and Drive DeVilbiss Healthcare exemplify diversified healthcare equipment conglomerates leveraging cross-category procurement relationships.
| Leading Market Players |
|---|
| Arjo |
| Invacare Corporation |
| Toto Asia |
| Huida Group |
| Aidacare |
| Savaria Corporation |
| Drive DeVilbiss Healthcare |
| Etac |
| Lixil Group Corporation |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals gate qualified supply and premium-tier pricing access by forcing manufacturers to redesign water-efficient bidet seats and low-flow assist devices for provincial procurement offices in Shanghai, Jiangsu, and Zhejiang. This environmental mandate simultaneously compresses margins on non-compliant manual devices while elevating pricing power for certified electrified equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the Asia-Pacific bathroom and toilet assist devices market, with ISO 9999 certification grade and after-sales service bundling as primary price differentiation drivers. Cost compression in economy-tier manual assist devices is intensifying because aluminum and stainless steel input volatility from energy-intensive smelting operations compresses fabricator margins. Hospital networks and Australia's NDIS plan managers exhibit the least price sensitivity due to centralized procurement and therapeutic claims pathways, while price-sensitive segments concentrate in China's tier-2 city retrofit programs.
Supply Chain Analysis
Regional distribution centers in Shanghai and Singapore anchor hub-and-spoke patterns serving hospital networks and home care agencies across the Asia-Pacific region. Manufacturing concentrates in China's eastern corridor spanning Shanghai, Jiangsu, and Zhejiang, with aluminum extrusion and stainless steel stamping as core fabrication inputs. Single-source vulnerability in precision sensor modules for smart toilet platforms creates supply chain risk, as Japanese and South Korean component suppliers dominate voice-activation and biosensor integration. Distribution runs through direct sales partnerships with institutional buyers and multi-year framework agreements with Australia's home care agency aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific bathroom and toilet assist devices market functions as a regulatory compounder, with Japan's METI accessibility guidelines mandating barrier-free fixtures in public buildings and hospitals to drive sustained institutional demand.
For Market Incumbents: Extend certification coverage across Japan's PMDA pressure-ulcer prevention mandates and Australia's TGA therapeutic claims pathways to defend against emerging smart toilet specialists. Backward integration into aluminum and stainless steel frame fabrication in China's eastern manufacturing corridor secures margin control against raw material volatility. Channel control through direct sales partnerships with hospital networks preserves pricing power as procurement centralization accelerates. For New Entrants and Emerging Players: The price-point gap between premium smart toilets and economy manual assist devices creates white-space opportunity for mid-tier electrically operated equipment with modular sensor integration. Southeast Asia's underpenetrated markets in Vietnam, Thailand, and Indonesia offer the most penetrable geography before regulatory harmonization. A go-to-market angle bundling installation and maintenance services through local home care agency partnerships bypasses established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for home care service integrators because Australia's NDIS plan managers now direct sixty percent of assistive technology spending through approved provider panels, creating scalable contract aggregation. Long-term viability over a multi-year horizon hinges on capturing multi-year framework agreements with procurement aggregators. The signal to watch is interoperability standard stabilization between smart toilet platforms and regional healthcare data systems.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Investment | Pressure-ulcer prevention feature compliance unlocks Japan's hospital network procurement channels. |
| Captive Testing Laboratory Establishment | Shanghai-based GB standards testing compresses SAMR certification timelines for electrified devices. |
| NDIS Provider Panel Inclusion | Victoria and New South Wales plan manager relationships aggregate residential retrofit demand. |
| Sensor Integration Partnership | Voice-activation and biosensor modules differentiate premium positioning in Tokyo and Sydney. |
| Provincial Procurement Tender Capture | Shanghai-Jiangsu-Zhejiang dual carbon compliance secures water-efficient bidet seat volume. |
Study Parameters
Multiple input streams — primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts managers; secondary validation through SAMR GB standards filings, TGA therapeutic claims databases, and METI accessibility guideline documentation; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Hospital purchasing committees and home care agency operations directors provided demand-side validation, while manufacturer R&D leads and certification specialists supplied supply-side perspectives. This multi-source approach ensures cross-verification of market sizing assumptions.
Data-stream reconciliation across product type, end user, technology, and distribution channel segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from modeled adoption curves for smart toilet penetration in premium residential segments and manual assist device retrofit cycles in institutional channels. Forecast inputs incorporated Japan's PMDA regulatory timeline assumptions and Australia's NDIS spending aggregation patterns.
Caveats apply where BIS certification timeline extensions in India or aluminum price volatility from energy policy shifts could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Bone Cement Mixers Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Oral Appliance Market
Medical Devices
Spinal Osteosynthesis Units Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
United States Organ Preservation Market