
 Chemotherapy-Induced Oral Mucositis Market | 2026-2036
Chemotherapy-Induced Oral Mucositis Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy-Induced Oral Mucositis Market Outlook
Oncology service networks is recalibrating procurement patterns as hospital systems consolidate cancer care into centralized infusion centers. Pfizer Inc. leverages its institutional distribution scale to secure formulary placement across these consolidating buyers. Amgen Inc. sustains competitive presence through its established biologics infrastructure in supportive care. GSK anchors market position with specialized oncology portfolios aligned to hospital pharmacy protocols.
Chemotherapy-induced oral mucositis denotes inflammatory ulcerative damage to oral mucosal epithelium triggered by cytotoxic agents, characterized by erythema, pseudomembranous lesions, and functional impairment graded by WHO or NCI-CTCAE scales. The condition necessitates prophylactic and therapeutic intervention to maintain chemotherapy dosing intensity and patient nutritional status. Topical agents command the largest revenue pool given immediate accessibility and favorable reimbursement in outpatient settings, while biomaterials represent the fastest-expanding segment as bioactive dressings and regenerative matrices advance through clinical validation. Systemic agents retain entrenched positions in severe-grade protocols where mucosal integrity cannot be managed locally.
FDA oncology supportive care guidance, EMA MDR requirements for device-drug combinations, and WHO cancer pain relief standards collectively elevate evidentiary thresholds for market entry. These frameworks compel manufacturers to generate robust mucositis-specific endpoints rather than extrapolating from general anti-inflammatory data. Stakeholders must track evolving regulatory expectations for real-world evidence generation as payers tighten coverage criteria for premium-priced interventions.
Market Dynamics
Hospital consolidation into centralized oncology networks is compressing formulary access points, forcing manufacturers to secure multi-site procurement contracts rather than individual clinic relationships. This structural concentration elevates the importance of institutional distribution scale and evidence packages that satisfy pharmacy and therapeutics committees simultaneously.
Growth Catalysts
- FDA oncology supportive care guidance:Evidentiary requirements for mucositis-specific endpoints compel manufacturers to generate robust clinical data, raising barriers for marginal competitors and rewarding sponsors with differentiated trial designs.
- Japan's aging chemotherapy population:METI-supported cancer care infrastructure expansion in prefectural medical centers generates sustained demand for prophylactic mucositis protocols in high-volume infusion settings.
- Bioactive regenerative matrices:Advanced biomaterials integrating growth factors and extracellular matrix scaffolds are advancing through Phase III validation, promising to reduce treatment interruption rates in high-dose regimens.
Market Restraints
- Reimbursement compression in US outpatient settings:Medicare Part B payment limits on supportive care agents constrain pricing flexibility for novel topical formulations entering competitive therapeutic classes.
- EMA MDR device-drug combination requirements:Enhanced clinical evidence standards for bioactive dressings extend regulatory timelines and inflate development costs for European market entry.
- Generic sodium bicarbonate and chlorhexidine rinses:Low-cost prophylactic substitutes capture substantial volume in mild-grade mucositis prevention, limiting premium product penetration at the disease onset stage.
Strategic Opportunities
- Germany's outpatient chemotherapy expansion:Federal cancer plan investments in community-based infusion centers create addressable sites for portable mucositis management systems outside hospital pharmacy control.
- Real-world evidence generation mandates:Payer tightening of coverage criteria for premium interventions rewards manufacturers with established post-market surveillance infrastructure and health economics capabilities.
- Digital therapeutics convergence:Smartphone-based symptom tracking applications integrated with provider workflow systems enable remote monitoring of mucositis progression and intervention timing optimization.
Industry Challenges
- WHO and NCI-CTCAE scale harmonization:Inconsistent grading terminology across clinical trial protocols complicates cross-study evidence synthesis and regulatory submission preparation for multi-regional approvals.
- Specialized wound care nursing shortage:Limited availability of trained personnel for biomaterial dressing application in community oncology settings restricts adoption of advanced topical interventions outside academic centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy-Induced Oral Mucositis Market |
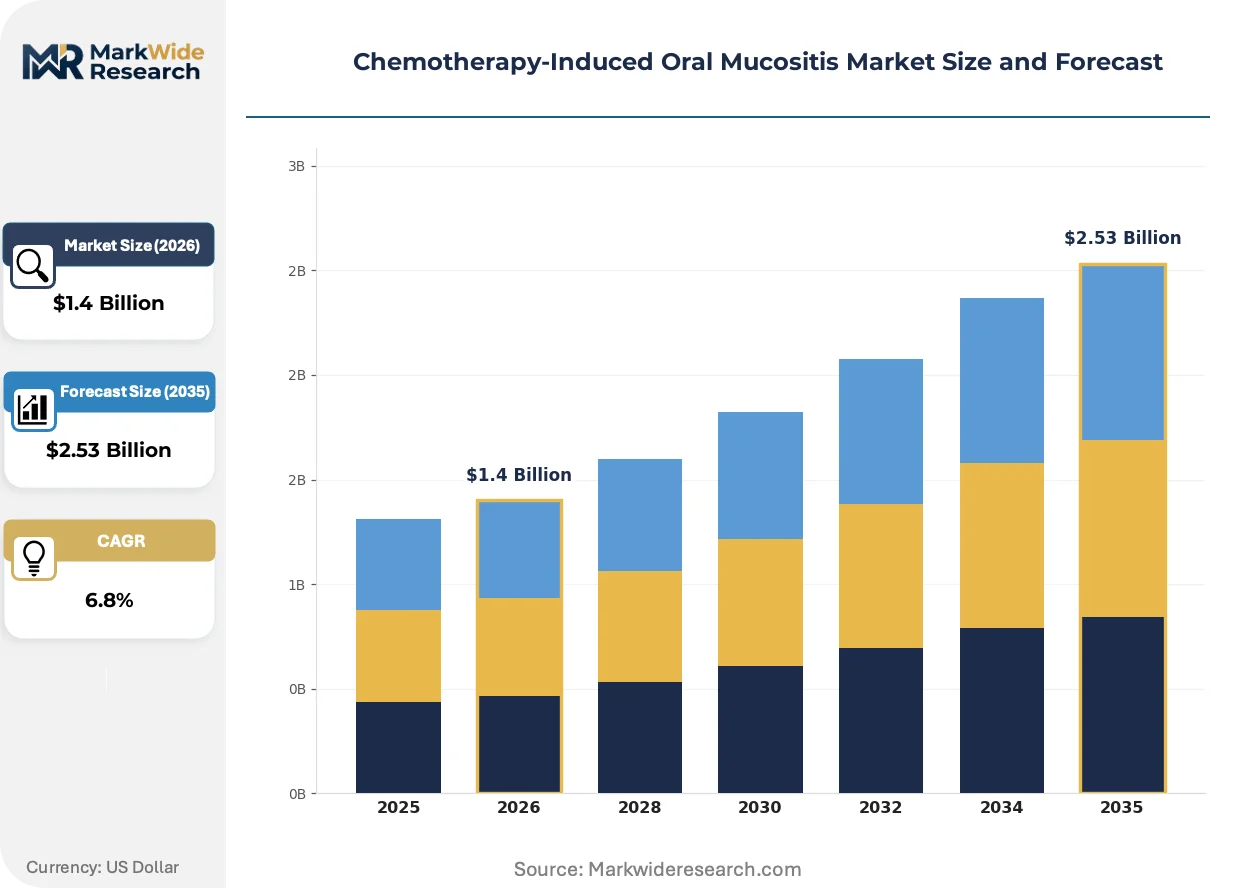
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Oral Rinses, Systemic Agents, Biomaterials Application: Supportive Care, Cancer Treatment, Palliative Care, Research Studies Delivery Mode: Oral, Injectable, Intravenous, Transmucosal End User: Hospitals, Clinics, Homecare, Long-term Care Facilities |
| Companies Covered | Amgen Inc., Galera Therapeutics Inc., Soligenix Inc., Helsinn Healthcare SA, Innovation Pharmaceuticals Inc., Pfizer Inc., GSK, Jaguar Health Inc., EpicentRx Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy-Induced Oral Mucositis Market Strategic Shifts
Clinical validation priorities are pivoting toward preservation of chemotherapy dosing intensity rather than symptom palliation alone, reshaping endpoint selection and commercial messaging across the therapeutic landscape. This therapeutic goal reframing elevates interventions demonstrating prophylactic efficacy in preventing dose reductions or treatment delays.
Platelet-rich fibrin and autologous blood-derived biologics are converging with standardized chemotherapy protocols in European academic centers, where pharmacy compounding capabilities support patient-specific preparation. German and French oncology departments are piloting these autologous approaches in head and neck cancer populations receiving concomitant chemoradiation. The technology is converging with existing supportive care infrastructure to create premium service lines that differentiate comprehensive cancer centers from community competitors.
EMA MDR requirements for device-drug combinations are forcing sponsors to generate mucositis-specific clinical data rather than extrapolating from general anti-inflammatory or wound healing studies. Manufacturers must now conduct dedicated trials with validated oral assessment instruments to support CE marking of bioactive dressings and regenerative matrices. European notified bodies are applying these standards most stringently to products containing active pharmaceutical ingredients, compressing development timelines for device-centric alternatives.
Hospital system procurement centralization is consolidating purchasing authority into regional oncology networks and group purchasing organizations, displacing individual clinic autonomy in formulary decisions. Community infusion centers in the United States are losing direct supplier relationships as contracts migrate to system-wide agreements negotiated by centralized pharmacy directors. This concentration is most visible in consolidated health systems across Texas, Florida, and California, where three to five hospital networks control the majority of chemotherapy delivery sites.
Chemotherapy-Induced Oral Mucositis Market Segmentation
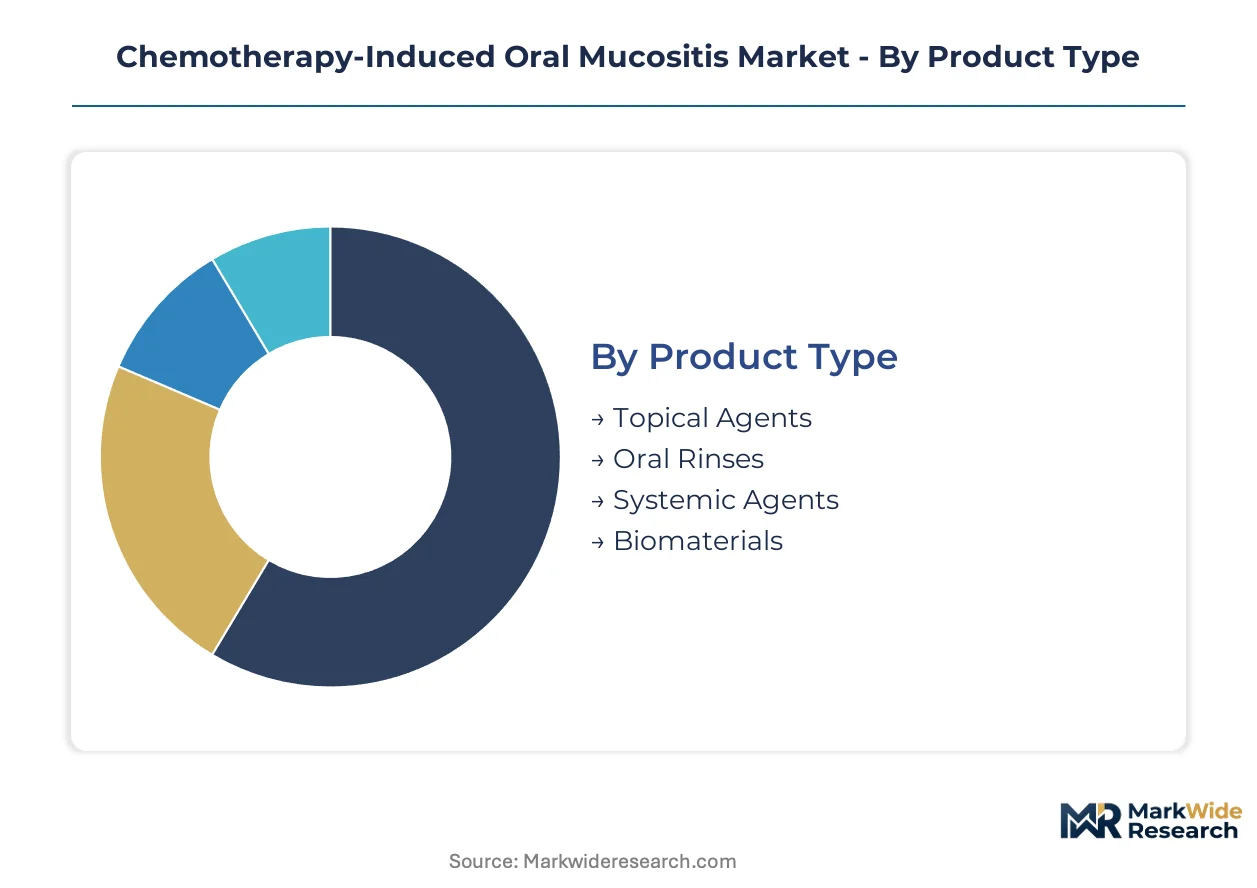
Segmentation in the chemotherapy-induced oral mucositis market reveals distinct procurement pathways and clinical utility patterns. Treatment setting, delivery complexity, and reimbursement tier determine product selection across institutional and ambulatory environments.
Product Type:
Formulation chemistry and reimbursement classification separate buyers into distinct procurement tiers with varying evidentiary requirements.
- Topical Agents:Creams, gels, and mucoadhesive patches deliver localized anti-inflammatory or cytoprotective action directly to ulcerated mucosa. Outpatient oncology clinics in the United States favor these for immediate accessibility and favorable Medicare Part B reimbursement pathways.
- Biomaterials:Bioactive dressings and regenerative matrices incorporate extracellular matrix scaffolds or growth factors to accelerate epithelial repair. German academic medical centers are piloting these in high-dose chemotherapy protocols where treatment interruption carries substantial survival implications.
- Oral Rinses:Chlorhexidine, sodium bicarbonate, and prescription formulations provide prophylactic coverage across mild-grade presentations. Generic substitutes dominate volume in community infusion settings with constrained pharmacy budgets.
- Systemic Agents:Intravenous or oral medications modulate inflammatory cascades systemically for severe-grade mucositis unresponsive to local intervention. Hospital inpatient protocols retain these for grade 3-4 presentations requiring opioid escalation or parenteral nutrition.
Topical agents lead volumes today; biomaterials are gaining share fastest.
Application:
Clinical intent shapes regulatory pathway and endpoint selection for sponsors developing mucositis interventions.
- Supportive Care:Prophylactic and therapeutic protocols integrated into standard chemotherapy regimens to preserve dosing intensity. FDA oncology supportive care guidance mandates mucositis-specific endpoints for this indication, elevating trial design complexity.
- Cancer Treatment:Mucositis management as a component of curative-intent protocols where dose reductions compromise survival outcomes. Japan's METI-supported cancer care infrastructure expansion is driving protocol standardization across prefectural medical centers.
- Palliative Care:Symptom-focused interventions prioritizing oral intake maintenance and analgesic reduction in advanced disease. Hospice and long-term care facilities in Germany's federal cancer plan network represent emerging demand pockets.
- Research Studies:Investigational agents and biomaterials undergoing clinical validation with WHO or NCI-CTCAE grading instruments. Academic consortia in France and the United Kingdom are coordinating multi-center trials for novel regenerative approaches.
Supportive care commands the largest addressable base; cancer treatment applications are climbing the fastest.
Delivery Mode:
Route of administration determines site-of-care requirements and nursing competency needs across treatment settings.
- Oral:Self-administered rinses, gels, and tablets requiring minimal clinical supervision. Homecare and ambulatory settings favor this route for patient convenience and reduced infusion center burden.
- Intravenous:Systemic agents delivered in supervised infusion environments with cardiac monitoring capabilities. Hospital outpatient departments retain control over this delivery tier through pharmacy and therapeutics committee oversight.
- Injectable:Subcutaneous or intramuscular formulations bridging outpatient convenience with systemic exposure. Community oncology networks in Texas and Florida are standardizing these protocols across consolidated infusion centers.
- Transmucosal:Buccal or sublingual absorption bypassing gastrointestinal degradation for rapid onset. Specialized compounding pharmacies in academic medical centers support patient-specific preparation of autologous blood-derived biologics.
Oral delivery dominates prescription volume; transmucosal formulations show the steepest expansion trajectory.
End User:
Facility type dictates formulary autonomy, procurement scale, and patient acuity mix for mucositis product vendors.
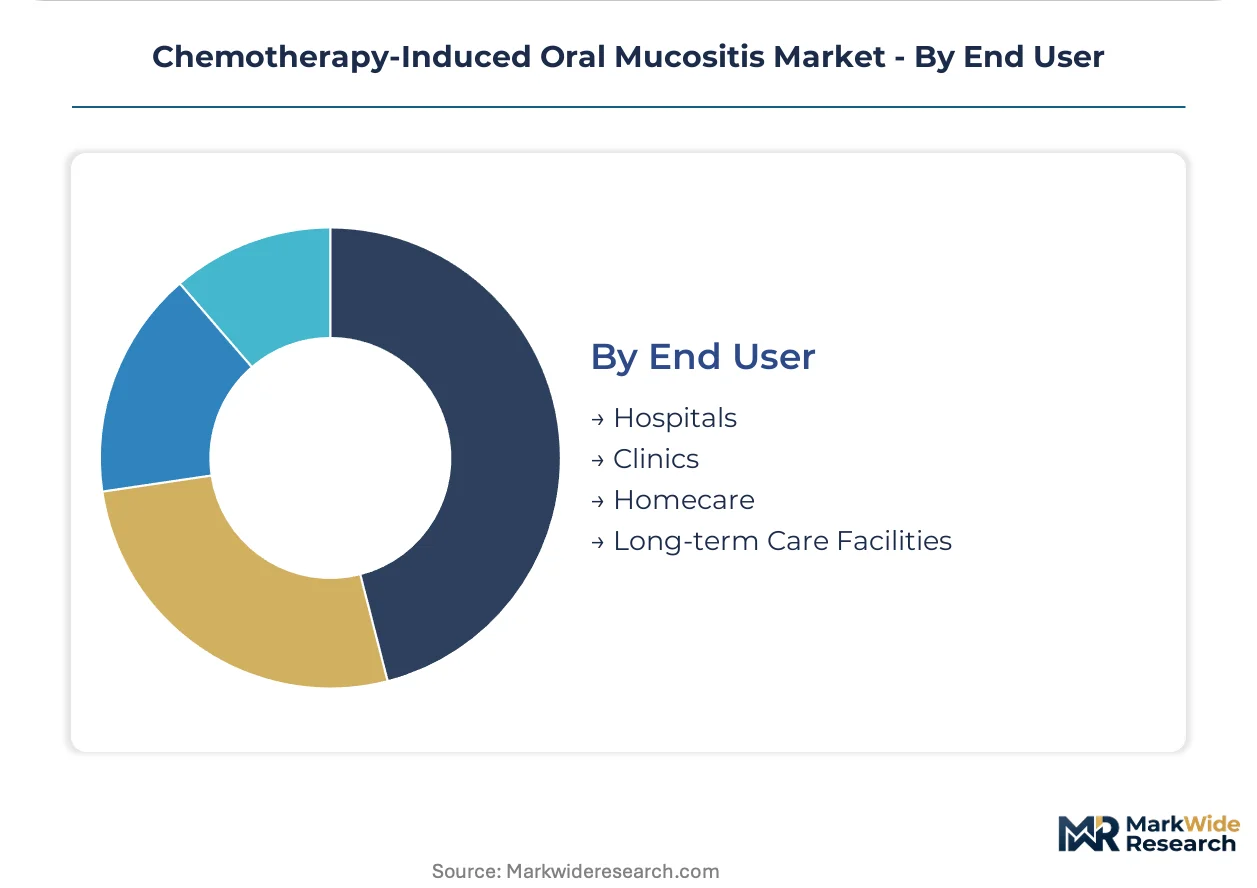
- Hospitals:Comprehensive cancer centers with centralized pharmacy authority and multi-site procurement contracts. Consolidated health systems across California are displacing individual clinic relationships through system-wide agreements.
- Clinics:Community infusion centers losing direct supplier access as purchasing migrates to regional oncology networks. Germany's outpatient chemotherapy expansion is creating addressable sites outside hospital pharmacy control.
- Homecare:Home infusion and nursing services managing mild-grade mucositis with patient-administered rinses and topical agents. Reimbursement compression in US outpatient settings is constraining premium product penetration here.
- Long-term Care Facilities:Skilled nursing and hospice environments prioritizing palliative symptom management. Specialized wound care nursing shortages restrict adoption of advanced biomaterial dressings outside academic referral patterns.
Hospitals anchor procurement volume today; homecare channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology nursing specialists concentrate in metropolitan hospital systems across the United States, Germany, and Japan, anchoring clinical protocol development and biomaterial adoption decisions in these high-volume chemotherapy markets.
United States
Consolidated health systems in Texas, Florida, and California control the majority of chemotherapy delivery sites through centralized pharmacy authority. FDA oncology supportive care guidance mandates mucositis-specific endpoints, elevating evidentiary requirements for market entry. The Southeast region witnesses procurement migration from individual clinics to regional oncology networks.
Germany
Federal cancer plan investments expand community-based infusion centers outside hospital pharmacy control, creating addressable sites for portable mucositis management. EMA MDR requirements for device-drug combinations extend regulatory timelines for bioactive dressings. Bavarian academic medical centers pilot autologous blood-derived biologics in head and neck cancer protocols.
Japan
METI-supported cancer care infrastructure expansion across prefectural medical centers generates sustained demand for prophylactic protocols. The country's aging chemotherapy population drives protocol standardization in high-volume infusion settings. Kanto region medical centers anchor clinical validation for novel regenerative matrices.
United Kingdom
NHS England cancer program centralization compresses formulary access points into regional procurement frameworks. NICE technology appraisals tighten coverage criteria for premium-priced interventions. London and Southeast oncology consortia coordinate multi-center trials for novel supportive care agents.
France
ANSM oversight of hospital pharmacy compounding supports patient-specific preparation of autologous biologics in academic centers. Regional health agencies standardize mucositis grading protocols across public hospital networks. Paris and Lyon comprehensive cancer centers differentiate through premium supportive care service lines.
Chemotherapy-Induced Oral Mucositis Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers defined by institutional scale and therapeutic complexity. Hospital consolidation into centralized oncology networks compresses formulary access points, forcing manufacturers to secure multi-site contracts rather than individual clinic relationships. Three archetypes dominate: large pharmaceutical firms with institutional distribution infrastructure, mid-cap biotech specialists with targeted supportive care portfolios, and emerging developers of bioactive regenerative matrices. Competitive moves concentrate on evidence generation for mucositis-specific endpoints and strategic partnerships with consolidated health systems.
Within the diversified pharmaceutical tier, Pfizer Inc. and Amgen Inc. occupy anchor positions shaped by their established institutional presence. GSK sits within the specialized oncology portfolio segment, aligned to hospital pharmacy protocols. Among emerging developers, Galera Therapeutics Inc. and Soligenix Inc. exemplify the pure-play specialist archetype focused on supportive care innovation. EpicentRx Inc. and Jaguar Health Inc. represent the biotechnology-driven segment advancing novel mechanistic approaches. Helsinn Healthcare SA and Innovation Pharmaceuticals Inc. anchor the mid-cap tier with concentrated therapeutic focus.
| Leading Market Players |
|---|
| Amgen Inc. |
| Galera Therapeutics Inc. |
| Soligenix Inc. |
| Helsinn Healthcare SA |
| Innovation Pharmaceuticals Inc. |
| Pfizer Inc. |
| GSK |
| Jaguar Health Inc. |
| EpicentRx Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive distribution infrastructure anchors both supply positioning and pricing power for mucositis management products, as Pfizer and Amgen leverage institutional pharmacy networks to defend premium positioning against generic rinse substitutes. Hospital consolidation into regional oncology networks compresses formulary access points, forcing manufacturers to secure multi-site procurement contracts that embed volume-based pricing tiers.
Pricing Analysis
Capacity additions in Germany's outpatient chemotherapy expansion are reshaping price floors for portable mucositis management systems outside hospital pharmacy control. Three-tier pricing structure across premium, standard, and economy levels separates bioactive regenerative matrices from compounded topical agents and generic sodium bicarbonate rinses. Price differentiation rests on FDA oncology supportive care guidance compliance and Medicare Part B reimbursement tier placement. Cost compression in the generic rinse segment is intensifying because low-cost chlorhexidine substitutes capture substantial mild-grade prevention volume, while hospital systems exhibit lowest price sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Single-source vulnerability sits with specialized wound care nursing capacity for biomaterial dressing application in community oncology settings. Manufacturing concentration spans the United States, Germany, and Japan where METI-supported cancer care infrastructure and federal cancer plan investments anchor production. Raw material dependencies include extracellular matrix scaffolds, growth factor formulations, and mucoadhesive polymer bases. Tariff exposure on European device-drug combinations under EMA MDR requirements extends regulatory timelines and inflates development costs. Distribution runs through consolidated health system pharmacy directors in Texas, Florida, and California rather than individual clinic procurement officers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in chemotherapy-induced oral mucositis management hinges on biomaterial premium-tier adoption outpacing generic rinse substitution, as bioactive regenerative matrices command reimbursement premiums for prophylactic efficacy in high-dose protocols.
For Market Incumbents: Anticipate formulary displacement from emerging bioactive dressing developers by securing exclusive multi-site contracts with consolidating regional oncology networks. Invest in real-world evidence generation infrastructure to satisfy payer tightening of coverage criteria for premium-priced interventions. Deepen backward integration into growth factor sourcing to control input costs for regenerative matrix production. For New Entrants and Emerging Players: The price-point gap between premium biomaterials and economy generic rinses creates white-space opportunity for mid-tier compounded topical agents with differentiated mucoadhesive delivery. Target Germany's outpatient chemotherapy expansion where federal cancer plan investments bypass hospital pharmacy gatekeepers. Pursue hospital system partnerships in the Southeast United States where procurement migration from individual clinics to regional networks remains incomplete. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap supportive care specialists because hospital consolidation demands scalable institutional distribution infrastructure that fragmented players cannot replicate independently. Five-to-ten year viability favors developers with established post-market surveillance capabilities and health economics teams. Watch for inflection when EMA MDR device-drug combination approvals accelerate for bioactive dressings with mucositis-specific endpoints.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Mucositis-specific endpoints per FDA oncology supportive care guidance elevate evidentiary barriers for competitors. |
| Hospital System Partnership | Multi-site procurement contracts with Texas and Florida consolidated networks displace individual clinic relationships. |
| Reimbursement Strategy | Medicare Part B pathway optimization determines pricing flexibility for novel topical formulations. |
| Manufacturing Scale-Up | Bioactive regenerative matrix production scaling supports Phase III validation and commercial supply security. |
| Regulatory Approval Pathway | EMA MDR compliance for device-drug combinations compresses timelines for device-centric alternatives. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulated volume estimates across treatment settings.
Historical reference periods anchored the forecast window to observed chemotherapy administration volumes and mucositis incidence rates across the projection horizon. Segmentation dimensions modeled include product type, application intent, delivery mode, and end-user facility tier alongside regional regulatory cluster differentiation. CAGRs derived from trend extrapolation of prophylactic protocol adoption and biomaterial clinical validation progress, with inputs from WHO and NCI-CTCAE grading instrument standardization timelines.
Caveats apply where EMA MDR enforcement intensity, Medicare Part B reimbursement revisions, or bioactive dressing Phase III outcomes could materially shift the outlook. Forecasts reflect documented assumptions about hospital consolidation pace and generic substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Kids Oral Care Products Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Mouthwash Market
Oral Care
Oral Thrush Treatment Market
Oral Care
BRICS Oral Care Market
Oral Care
Manual Toothbrush Market
Oral Care
South America Oral Care Market
Oral Care
Adult Oral Care Products Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Oral Rinse Market
Oral Care
Xerostomia Treatment Market
Oral Care
Canker Sores Treatment Market
Oral Care
Global Halitosis Market
Oral Care
Herbal Toothpaste Market
Oral Care
Oral Mucositis Market