
 Antiseptic Mouthwash Market | 2026-2036
Antiseptic Mouthwash Market Size, Share, and Industry Trends Forecast 2026-2036
Antiseptic Mouthwash Market Outlook
Subscription-based replenishment programs is repositioning how antiseptic mouthwash reaches households, converting one-time buyers into recurring revenue streams. Procter & Gamble leverages its direct-to-consumer infrastructure to lock in repeat purchases. Colgate-Palmolive anchors pharmacy shelf presence through clinician endorsement programs. Johnson & Johnson Services, Inc. competes on therapeutic credibility with healthcare channel specialization.
Antiseptic mouthwash denotes a liquid formulation containing antimicrobial agents—typically chlorhexidine gluconate, essential oils, or cetylpyridinium chloride—designed to reduce oral bacterial load below pathogenic thresholds when used as a rinse. Manufacturers compound active ingredients with flavoring agents, humectants, and pH stabilizers in aqueous or hydroalcoholic bases to achieve substantivity against plaque-forming biofilms. Alcohol-based formulations dominate volume in emerging markets where cost sensitivity shapes purchasing, while non-alcoholic variants command premium positioning in North American and European retail channels. Essential oil segments sustain growth through natural-positioned branding that resonates with ingredient-conscious consumers.
The US FDA governs antiseptic mouthwash claims under OTC drug monographs, requiring substantiation of antimicrobial efficacy against specified oral pathogens. The EU REACH framework restricts certain preservative chemistries, pushing reformulation toward bio-derived actives. China's NMPA mandates registration for therapeutic-grade rinses, creating compliance barriers for imported brands. Stakeholders must monitor evolving classification thresholds that distinguish cosmetic rinses from regulated drug products across major jurisdictions.
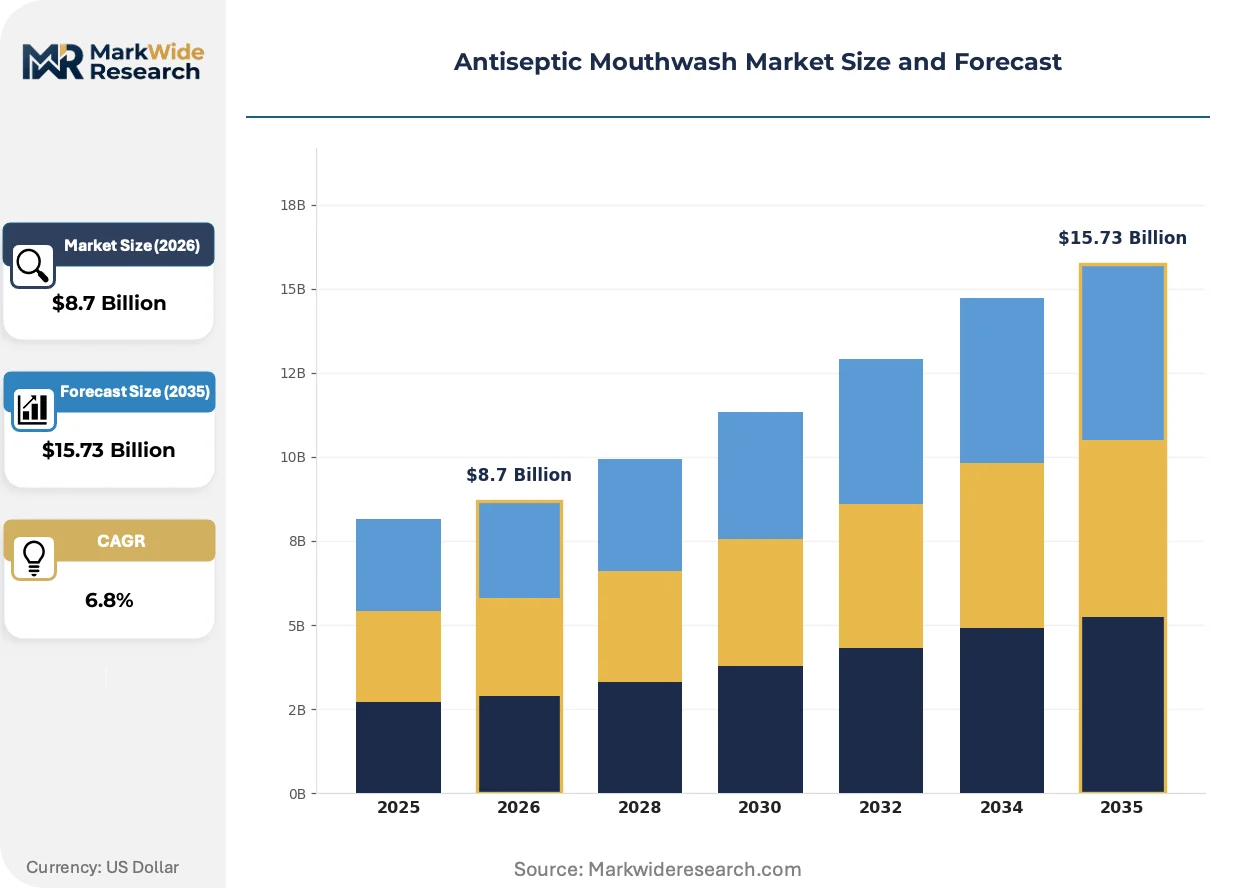
Market Dynamics
Dental clinics are hardwiring antiseptic mouthwash into pre-procedural protocols, converting discretionary retail purchases into institutional procurement mandates. This shift from consumer choice to clinical directive is restructuring volume flows toward healthcare channels.
Growth Catalysts
- Pre-procedural rinsing protocols:Dental associations in the United States and Germany now mandate chlorhexidine rinsing before invasive procedures, institutionalizing demand through infection-control guidelines.
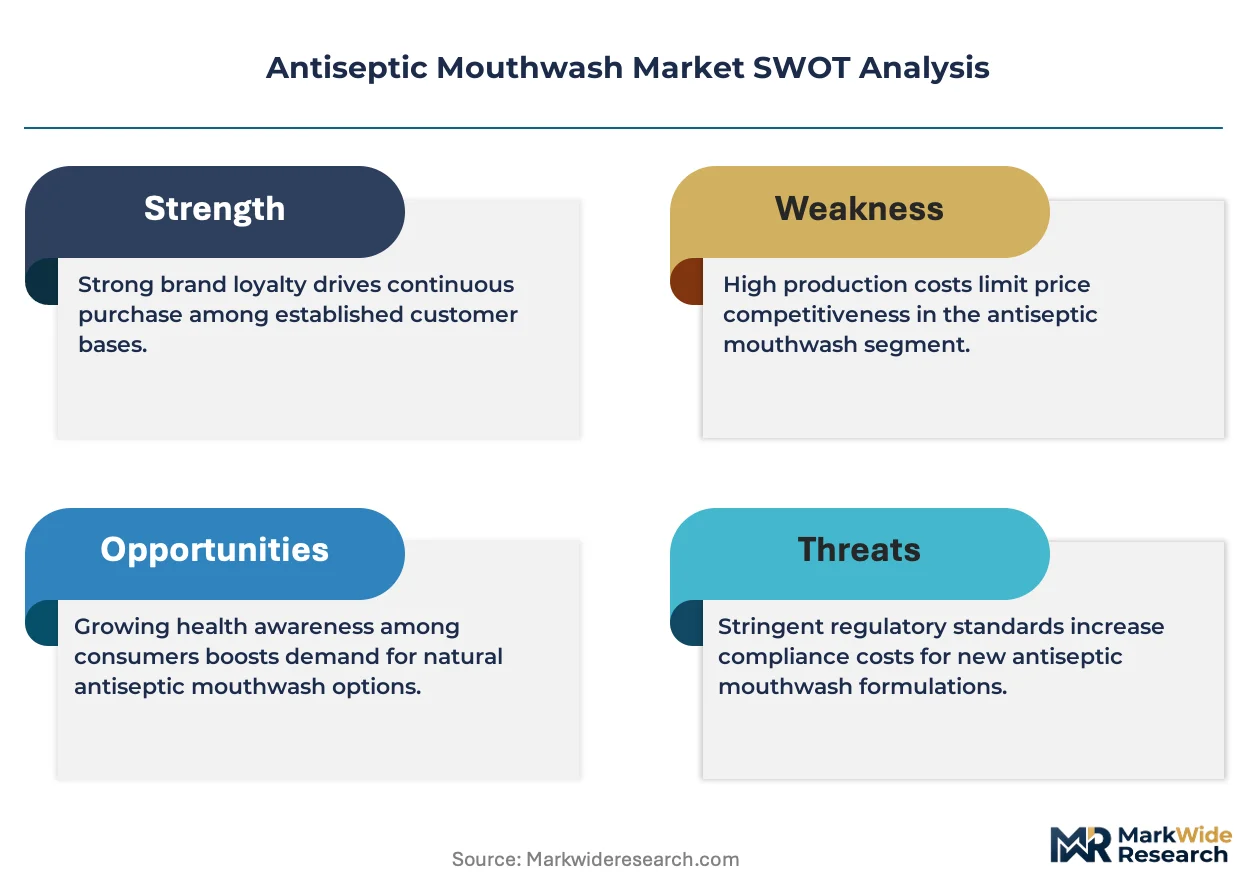
- REACH framework reformulation:EU restrictions on synthetic preservatives are accelerating bio-derived active development, opening premium positioning for essential oil formulations.
- China pharmacy network expansion:Domestic oral care brands are building registered pharmacy distribution, capturing consumers migrating from unregulated e-commerce to licensed retail channels.
Market Restraints
- Alcohol excise volatility:Hydroalcoholic formulation costs fluctuate with ethanol feedstock prices, compressing margins for volume producers in emerging markets.
- NMPA registration barriers:China's therapeutic-grade rinse classification creates multi-year approval timelines, freezing market access for imported therapeutic claims.
- Cosmetic rinse substitution:Unregulated flavor rinses without antimicrobial substantivity compete on price at retail, eroding clinical-grade volume in price-sensitive segments.
Strategic Opportunities
- Rural India pharmacy penetration:Underregistered districts present whitespace for chlorhexidine distribution through government health sub-centers and accredited drug shops.
- Subscription direct-to-consumer channels:Replenishment programs lock in recurring revenue, bypassing retail slotting fees and capturing lifetime value through automated reordering.
- CE-marked medical device reclassification:EU MDR pathway for post-surgical rinses enables reimbursement access, shifting competitive arena from retail shelf to hospital formulary.
Industry Challenges
- Substantivity testing capacity:FDA OTC monograph compliance requires specialized biofilm assay laboratories, creating bottlenecks for new active ingredient submissions.
- Legacy formulation integration:Reformulating established SKUs for alcohol-free positioning while maintaining antimicrobial efficacy demands capital-intensive stability testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiseptic Mouthwash Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-Based, Chlorhexidine, Essential Oil, Non-Alcoholic Target Audience: General Consumers, Dental Patients, Healthcare Professionals, Athletes Functionality: Antimicrobial, Whitening, Breath Freshening, Fluoride-Infused Distribution Channel: Retail Stores, Online Platforms, Pharmacies, Supermarkets |
| Companies Covered | Procter & Gamble, Colgate-Palmolive, Johnson & Johnson Services, Inc., Church & Dwight Co, Inc., Unilever, GlaxoSmithKline plc, Reckitt Benckiser Group plc, Hawley & Hazel (BVI) Co. Ltd., Lion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiseptic Mouthwash Market Strategic Shifts
Antiseptic mouthwash is transitioning from commodity rinse to precision oral therapeutics, with formulation science and channel architecture evolving in parallel. Three developments are compressing competitive timelines and reallocating value capture.
Essential oil microemulsion technology is consolidating antimicrobial delivery systems. These nano-scale dispersions of thymol and eucalyptol achieve deeper periodontal penetration than conventional solutions. Dental clinics in Germany and the Netherlands are adopting microemulsion protocols for peri-implantitis management. The technology is consolidating high-efficacy positioning previously fragmented across prescription chlorhexidine and over-the-counter alternatives.
EU REACH Annex XVII restrictions on quaternary ammonium compounds are forcing preservative system redesigns. ECHA evaluations of cetylpyridinium chloride environmental persistence have triggered downstream notification obligations. Manufacturers serving European markets are accelerating bio-preservative validation, with essential oil and organic acid systems displacing legacy chemistries in new product development pipelines.
Clinician endorsement programs are displacing traditional advertising as the primary demand generation mechanism. Dental school continuing education partnerships now determine formulary placement more effectively than retail promotional spend. This channel pivot is most visible in North American and Japanese markets, where practitioner recommendation carries higher conversion weight than shelf visibility or price promotion.
Antiseptic Mouthwash Market Segmentation
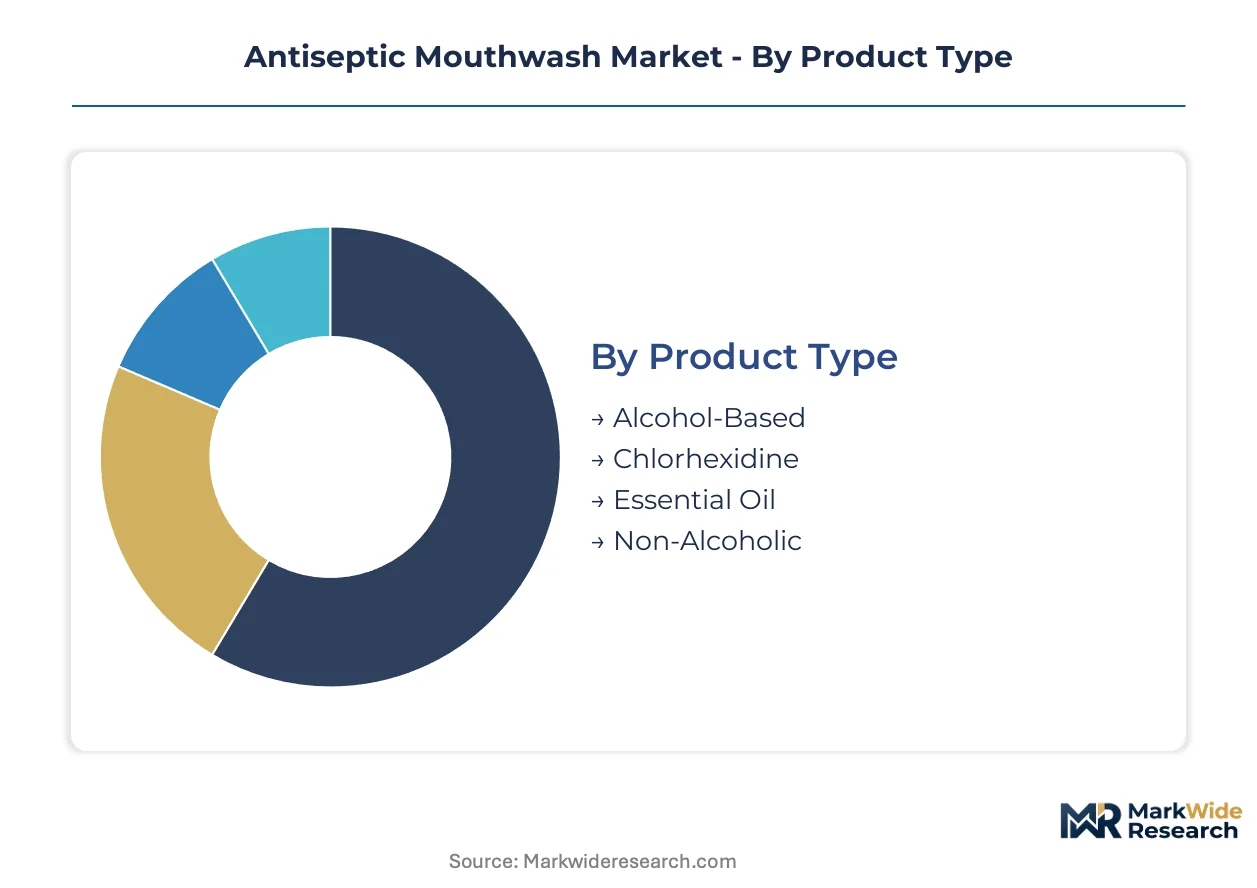
Antiseptic mouthwash segmentation determines regulatory pathways, margin structures, and channel access. Product chemistry dictates whether formulations fall under OTC drug monographs or cosmetic classifications. Audience targeting shapes whether brands invest in clinical substantiation or consumer advertising.
Product Type:
Alcohol-Based formulations require the lightest regulatory burden among therapeutic rinses in most jurisdictions, while Chlorhexidine faces prescription-grade controls. Essential Oil and Non-Alcoholic variants occupy intermediate positions with varying substantivity claims.
- Alcohol-Based:Hydroalcoholic solutions typically containing ethanol at 10-26% concentration achieve rapid bacterial kill through protein denaturation. Demand concentrates in emerging markets including Brazil and India where cost sensitivity dominates purchasing decisions, though alcohol excise volatility compresses margins for volume producers.
- Chlorhexidine:Bisbiguanide antimicrobial at 0.12-0.2% concentration delivers sustained substantivity against plaque biofilms through cationic binding to oral surfaces. Dental clinics in Germany and the United States mandate pre-procedural rinsing, institutionalizing procurement through infection-control guidelines rather than consumer choice.
- Essential Oil:Thymol-eucalyptol-menthol combinations in hydroalcoholic or aqueous bases leverage natural-positioned branding. EU REACH restrictions on synthetic preservatives accelerate bio-derived active development.
- Non-Alcoholic:Cetylpyridinium chloride or stabilized chlorine dioxide systems target pediatric and recovering alcoholic populations. North American retail channels command premium positioning for alcohol-free variants.
Alcohol-Based sits at the top of the volume ranking, with Essential Oil climbing the fastest.
Target Audience:
Audience segmentation drives whether brands pursue pharmacy formulary placement, direct-to-consumer subscription models, or institutional procurement contracts. Cost-to-serve varies dramatically across these pathways.
- General Consumers:Mass-market purchasers selecting primarily on price, flavor, and shelf visibility. Retail slotting fees dominate go-to-market economics.
- Dental Patients:Individuals with diagnosed periodontal conditions or post-surgical recovery needs. Clinician recommendation carries higher conversion weight than advertising in Japan and North America.
- Healthcare Professionals:Institutional buyers including dental clinics and hospital systems mandating pre-procedural protocols. Procurement shifts from discretionary retail to infection-control mandates.
- Athletes:Sports-focused consumers seeking breath management and oral hydration. Team sponsorships and locker room sampling drive trial.
General Consumers generate the largest revenue base, while Healthcare Professionals deliver the steepest expansion trajectory as clinical protocols hardwire rinsing requirements.
Functionality:
Functional claims determine whether products require antimicrobial substantiation or compete as cosmetic rinses. Regulatory investment correlates directly with therapeutic positioning.
- Antimicrobial:Formulations with validated bacterial load reduction against specified oral pathogens. FDA OTC monograph compliance demands specialized biofilm assay capacity.
- Whitening:Peroxide-based or optical brightening systems targeting extrinsic stain removal. Cosmetic classification avoids drug-level registration in most jurisdictions.
- Breath Freshening:Masking agents without antimicrobial substantivity. Unregulated flavor rinses compete on price, eroding clinical-grade volume in price-sensitive retail segments.
- Fluoride-Infused:Sodium fluoride or stannous fluoride additions for caries prevention. Dental association endorsement programs determine formulary placement effectiveness.
Antimicrobial commands the highest per-unit margins, with Fluoride-Infused gaining share fastest through pediatric and geriatric positioning.
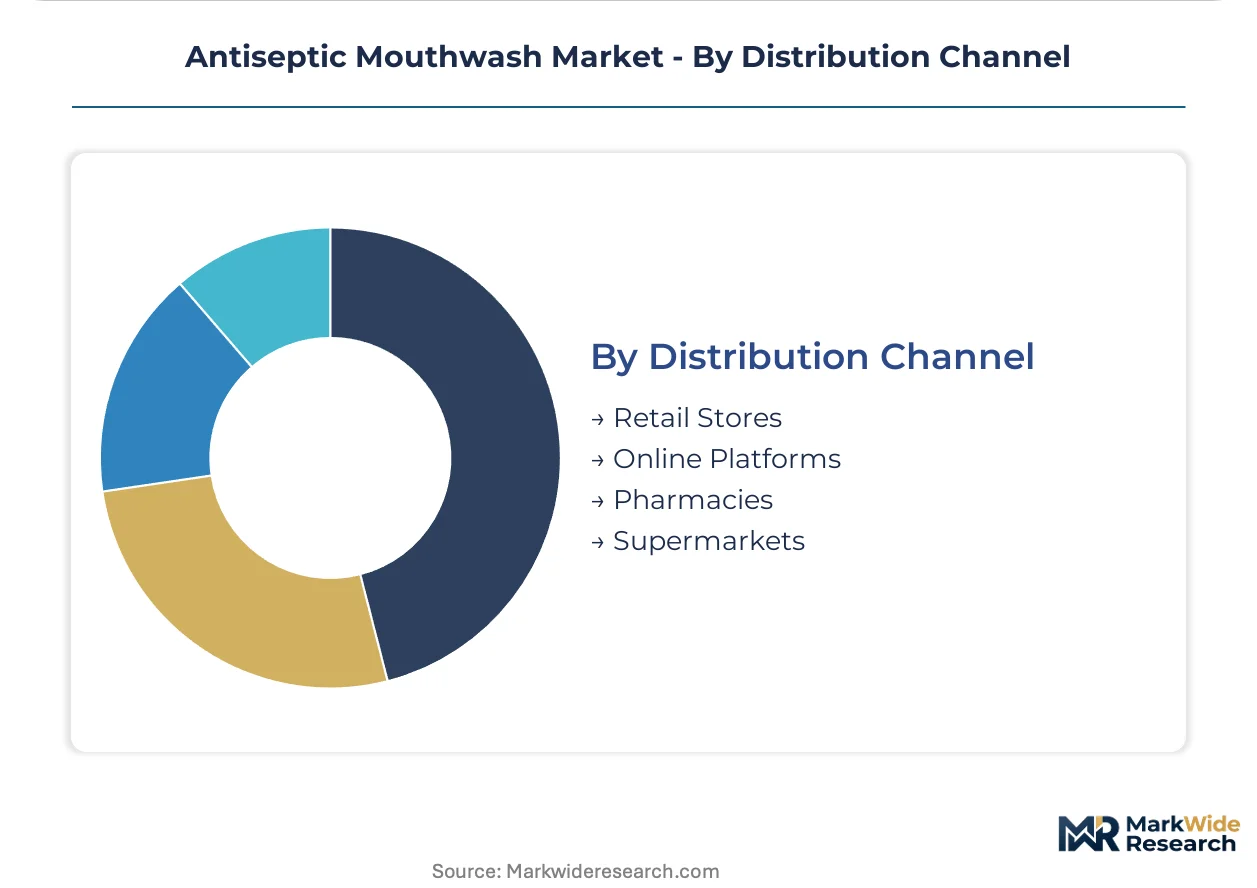
Distribution Channel:
Channel selection determines working capital requirements, margin capture, and customer relationship depth. Direct-to-consumer infrastructure investment separates subscription-capable players from traditional retail-dependent competitors.
- Retail Stores:Mass merchandisers and drug chains requiring slotting fees and promotional support. Shelf visibility drives trial in undifferentiated segments.
- Online Platforms:E-commerce and direct-to-consumer subscription programs. Automated replenishment locks in recurring revenue and captures lifetime value.
- Pharmacies:Licensed retail with pharmacist consultation. China's NMPA mandates registration for therapeutic-grade rinses, creating compliance barriers for imported brands.
- Supermarkets:High-velocity grocery channels emphasizing price promotion and multi-pack formats. Volume scale compensates for compressed margins.
Retail Stores retain the largest volume footprint, with Online Platforms expanding most quickly as replenishment programs convert one-time buyers into recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate formulation capacity toward jurisdictions with streamlined OTC drug pathways. Cost-of-compliance gaps between the FDA's biofilm assay requirements and China's NMPA registration timelines are driving facility investment decisions.
United States
Dental clinic procurement mandates and subscription direct-to-consumer channels concentrate demand in California and New York Metro. The FDA's OTC drug monograph for antiseptic rinses requires specialized substantivity testing that bottlenecks new active ingredient submissions. Manufacturing clusters in New Jersey and North Carolina host GMP-certified facilities serving institutional and retail channels.
China
Domestic oral care brands are capturing pharmacy network expansion as consumers migrate from unregulated e-commerce to licensed retail. NMPA registration for therapeutic-grade rinses creates multi-year approval timelines that freeze market access for imported therapeutic claims. Production concentrates in Guangdong and Jiangsu provinces where contract manufacturers serve both local and export markets.
Germany
Dental association pre-procedural rinsing protocols institutionalize chlorhexidine demand through infection-control guidelines. ECHA evaluations under REACH Annex XVII accelerate bio-preservative validation and essential oil formulation development. The Rhine-Ruhr corridor hosts formulation science clusters serving peri-implantitis management protocols adopted in Dutch and German clinics.
India
Alcohol-based volume demand concentrates in price-sensitive segments while government health sub-centers present whitespace for chlorhexidine distribution. CDSCO regulates therapeutic claims under the Drugs and Cosmetics Act, with state-level pharmacy councils enforcing retail licensing. Manufacturing clusters in Maharashtra and Gujarat supply hydroalcoholic formulations across South Asian markets.
Brazil
Cost-driven purchasing decisions favor alcohol-based formulations despite excise volatility compressing producer margins. ANVISA registration requirements for antimicrobial claims create compliance differentiation between cosmetic and therapeutic rinse categories. São Paulo anchors both domestic production and import distribution for multinational brands.
Antiseptic Mouthwash Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing portfolios commanding shelf access premiums while B2B formulators capture institutional procurement contracts. The market structures around three tiers: multinational FMCG conglomerates with direct-to-consumer infrastructure, regional pharmacy brands with clinician endorsement networks, and private-label manufacturers serving price-elastic retail segments. Dominant competitive moves include vertical integration into flavor chemistry and active ingredient sourcing, plus geographic licensing partnerships that bypass NMPA registration barriers.
Among the FMCG conglomerates, Procter & Gamble and Colgate-Palmolive exemplify divergent channel strategies. Procter & Gamble anchors subscription replenishment programs that convert one-time buyers into recurring revenue streams. Colgate-Palmolive occupies a position tied to pharmacy shelf presence and dental school continuing education partnerships. Johnson & Johnson Services, Inc. represents the healthcare channel specialization archetype, with positioning built on therapeutic credibility rather than retail promotional spend.
| Leading Market Players |
|---|
| Procter & Gamble |
| Colgate-Palmolive |
| Johnson & Johnson Services, Inc. |
| Church & Dwight Co, Inc. |
| Unilever |
| GlaxoSmithKline plc |
| Reckitt Benckiser Group plc |
| Hawley & Hazel (BVI) Co. Ltd. |
| Lion Corporation |
| Others |
Value Chain & Pricing Dynamics
EU REACH Annex XVII restrictions on quaternary ammonium compounds gate qualified supply for preservative systems and reserve premium-tier pricing access for manufacturers with validated bio-derived active pipelines. Compliance differentiation separates essential oil microemulsion suppliers commanding formulation premiums from legacy producers facing reformulation cost compression.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for alcohol-based formulations, intensifying cost competition in emerging market segments. Three-tier pricing structure across premium, standard, and economy levels stratifies by antimicrobial substantivity certification and clinician endorsement density. Pricing pressure stems from ethanol feedstock volatility squeezing hydroalcoholic producer margins. General consumers in Brazil and India exhibit highest price sensitivity, while dental clinic procurement mandates in Germany and the United States show lowest elasticity due to infection-control protocol requirements.
Supply Chain Analysis
Ocean freight rate fluctuations from Asia-Pacific manufacturing hubs to North American and European distribution centers directly impact landed cost structures for bulk active ingredient shipments. Supply concentrates in China for chlorhexidine gluconate synthesis, India for hydroalcoholic compounding, and Germany for essential oil extraction and microemulsion processing. Raw material dependencies include ethanol feedstocks, thymol-eucalyptol botanicals, and cetylpyridinium chloride precursors. Single-source vulnerability runs through concentrated chlorhexidine API manufacturing in Guangdong province. Distribution runs through pharmacy wholesale networks in regulated markets and direct-to-consumer subscription infrastructure in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antiseptic mouthwash functions as a stable compounder anchored by dental association pre-procedural protocol mandates that institutionalize recurring procurement volumes irrespective of consumer discretionary cycles.
For Market Incumbents: Acquire bio-preservative validation capabilities and essential oil microemulsion formulation expertise to preempt REACH-driven competitive displacement. Consolidate infection-control guideline relationships with dental associations in Germany and the United States before emerging essential oil specialists capture peri-implantitis protocol adoption. Channel control through subscription infrastructure locks in lifetime value against retail price erosion. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier entry path for challenger brands lacking pharmacy formulary relationships. Target underpenetrated rural India pharmacy networks through government health sub-center accreditation, bypassing established urban distribution dominated by FMCG conglomerates. Whitening and fluoride-infused cosmetic rinse segments present white-space with lighter regulatory burden than antimicrobial therapeutic classifications. For Investors and Strategic Acquirers: Roll-up economics work for regional pharmacy brands with clinician endorsement networks because dental school continuing education partnerships create durable formulary placement moats less susceptible to advertising spend competition. Five-to-ten year viability rests on consolidation of essential oil microemulation technology platforms and NMPA-registered manufacturing assets. Monitor EU MDR medical device reclassification pathways for post-surgical rinse reimbursement access as inflection signal shifting value capture from retail to hospital formulary channels.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Preservative Validation Investment | REACH Annex XVII compliance secures European market access against quaternary ammonium displacement. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures lifetime value and bypasses retail slotting fee structures. |
| Dental School Continuing Education Partnership | Clinician endorsement programs convert shelf visibility dependence into protocol-driven procurement mandates. |
| Essential Oil Microemulsion Scale-Up | Nano-scale thymol-eucalyptol delivery achieves peri-implantitis management positioning against prescription chlorhexidine. |
| NMPA Registration Pathway Execution | Therapeutic-grade rinse classification unlocks pharmacy network expansion in China's licensed retail channels. |
Study Parameters
Multiple input streams — regulatory filing analysis, trade flow databases, and channel inventory audits — were reconciled against primary fieldwork with dental clinic procurement officers, pharmacy chain category managers, oral care brand marketing directors, and contract manufacturing executives. Secondary validation drew from FDA OTC drug monograph submissions, ECHA REACH registration dossiers, NMPA therapeutic product listings, and customs export records. Bottom-up volume modeling across formulation types and top-down market sizing triangulated to constrain estimate variance.
Historical consumption patterns were cross-referenced against panel input from institutional buyers and retail distributors to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product chemistry, target audience archetype, functional claim substantiation level, and distribution channel type. CAGRs were derived from elasticity-adjusted demand curves incorporating dental protocol adoption rates and pharmacy network penetration trajectories. Forecast inputs weighted ethanol excise volatility, NMPA registration timeline uncertainty, and essential oil raw material supply concentration.
Regulatory reclassification, feedstock price shocks, and antimicrobial resistance guideline revisions are the dominant revision risks that could compress or expand addressable market boundaries. Stakeholders should weight assumptions against their own operating context and sensitivity to compliance timeline variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Thin Films Market
Oral Care
Adult Oral Care Products Market
Oral Care
Us Oral Care Market
Oral Care
Baby Oral Care Market
Oral Care
Herbal Toothpaste Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Canker Sores Treatment Market
Oral Care
Global Halitosis Market
Oral Care
China Oral Care Market
Oral Care
North America Oral Care Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Tongue Cleaner Market
Oral Care
Oral Thrush Market
Oral Care
Oral Hygiene Products Market
Oral Care
Oral Irrigator Market
Oral Care
Global Oral Care/Oral Hygiene Market