
 Herbal Drugs Market | 2026-2036
Herbal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Drugs Market Analytics
A capital-intensity divergence between fully integrated extract manufacturers and contract-reliant formulators is bifurcating competitive returns in herbal drugs. Dr. Willmar Schwabe GmbH & Co. KG leverages captive cultivation networks across multiple continents to secure raw material consistency. Bionorica SE specializes in clinically validated phytotherapeutics with documented pharmacokinetic profiles. Dabur India Limited anchors its position through Ayurvedic heritage brands distributed across South Asian pharmacy channels.
Herbal drugs comprise plant-derived preparations containing defined bioactive constituents standardized for potency, purity, and batch consistency, manufactured through extraction, concentration, and stabilization processes for therapeutic or preventive health applications. Extract formulations command premium positioning due to higher active-molecule concentrations and reproducible dosing profiles compared to whole-herb alternatives. The phytotherapy application segment leads clinical adoption where prescribers require evidence-backed monographs, while cosmeceuticals represent the fastest-expanding margin pool as dermatology brands incorporate adaptogenic botanicals. Online retail channels are displacing traditional herbal stores in volume growth, though pharmacies retain regulatory credibility for reimbursed prescriptions.
FDA botanical drug guidance, EMA herbal monograph requirements, and India's CDSCO AYUSH licensing framework collectively determine market access thresholds and clinical validation burdens for herbal drug developers. These regulatory architectures reward manufacturers investing in randomized trial data while marginalizing undocumented traditional preparations in formal healthcare procurement. Stakeholders must monitor evolving pharmacovigilance mandates and botanical identification technologies to sustain compliance and consumer trust.
Market Dynamics
Regulatory bifurcation between evidence-based phytomedicine frameworks and traditional herbal practice is fragmenting competitive returns and forcing manufacturers to choose between clinical trial investment and heritage positioning.
Growth Catalysts
- EMA Herbal Monograph Pathway:The European Medicines Agency's well-established monograph system creates reimbursement access for standardized extracts in Germany, France, and Poland, anchoring prescriber confidence.
- Adaptogenic Cosmeceuticals:Dermatology brands are incorporating ashwagandha, rhodiola, and holy basil into topical formulations, expanding addressable demand beyond traditional ingestible formats.
- CDSCO AYUSH Licensing:India's streamlined regulatory pathway for Ayurvedic, Unani, and Siddha products accelerates domestic manufacturing scale and export certification to diaspora markets.
Market Restraints
- Wild-Harvest Supply Concentration:Premium botanicals including ginseng, goldenseal, and hoodia face sourcing constraints from limited geographic ranges in Appalachia, Manchuria, and southern Africa.
- FDA Botanical Drug Development Costs:The agency's requirement for two adequate and well-controlled clinical trials imposes validation burdens that exclude small-scale traditional manufacturers from US prescription channels.
- Synthetic Phytochemical Substitution:Laboratory-produced resveratrol, curcumin analogs, and berberine derivatives threaten pricing power for plant-derived equivalents in supplement markets.
Strategic Opportunities
- Brazilian Regulatory Convergence:ANVISA's evolving herbal product framework presents first-mover advantage for manufacturers establishing local pharmacovigilance infrastructure ahead of formal monograph adoption.
- Direct-to-Consumer Genomic Personalization:Pharmacogenomic testing integration with herbal protocol selection creates subscription revenue models for metabolically tailored phytotherapy regimens.
- Blockchain Provenance Verification:Distributed ledger technologies enabling field-to-finished-product traceability address adulteration concerns in premium extract supply chains.
Industry Challenges
- Botanical Identification Expertise Scarcity:Qualified taxonomists and phytochemists capable of validating raw material identity through DNA barcoding and chromatographic fingerprinting command premium compensation.
- Extract Standardization Equipment Lead Times:High-performance liquid chromatography systems and supercritical CO2 extraction vessels face 12-18 month procurement delays from specialized European and Japanese suppliers.
- Legacy ERP Integration with Batch Tracking:Traditional manufacturers upgrading from paper-based production records to electronic systems encounter workflow disruption and validation documentation gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Drugs Market |
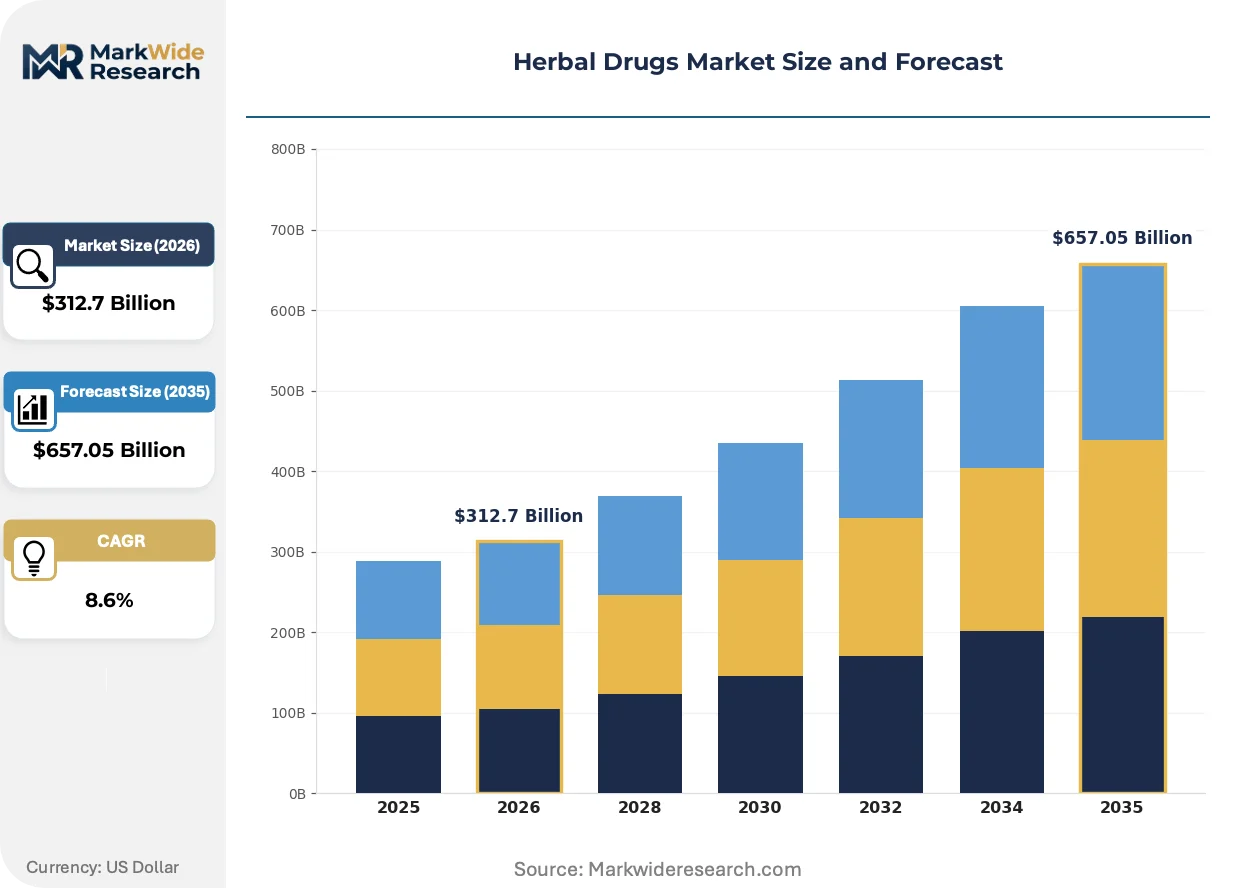
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Oils, Capsules, Teas Application: Phytotherapy, Nutraceuticals, Cosmeceuticals, Functional Foods End User: Pharmacies, Herbal Stores, Online Retail, Clinics Formulation Type: Solid, Liquid, Semi-Solid, Powder |
| Companies Covered | Dr. Willmar Schwabe GmbH & Co. KG, Baidyanath Group, Himalaya Drug Company, Gaia Herbs, Nature’s Way Products LLC, Dabur India Limited, Blackmores Limited, Bionorica SE, Tsumura & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Drugs Market Evolving Landscape
Digitalization of quality assurance and the convergence of traditional knowledge systems with molecular validation techniques are redefining competitive differentiation in botanical therapeutics.
DNA barcoding coupled with metabolomic profiling is supplanting morphological identification and simple chromatography for raw material authentication. Large extract manufacturers in Germany and Switzerland are adopting these molecular verification protocols to satisfy EMA pharmacovigilance requirements. The technology is compressing batch rejection rates while extending documentation burdens to upstream suppliers.
REACH regulation amendments addressing botanical substance registration are forcing European formulators to reassess supply chain exposure for exotic raw materials. Manufacturers are responding by regionalizing cultivation partnerships and substituting European-grown equivalents for imported species. The policy shift most acutely affects adaptogen and nootropic categories reliant on Asian and South American sourcing.
Subscription-based phytotherapy protocols are displacing single-product retail purchases in wellness-oriented consumer segments. Direct-to-consumer brands bundle personalized herbal regimens with telehealth consultations, capturing recurring revenue. This model concentrates in urban Australia and coastal US markets where digital health adoption outpaces traditional pharmacy loyalty.
Herbal Drugs Market Segmentation
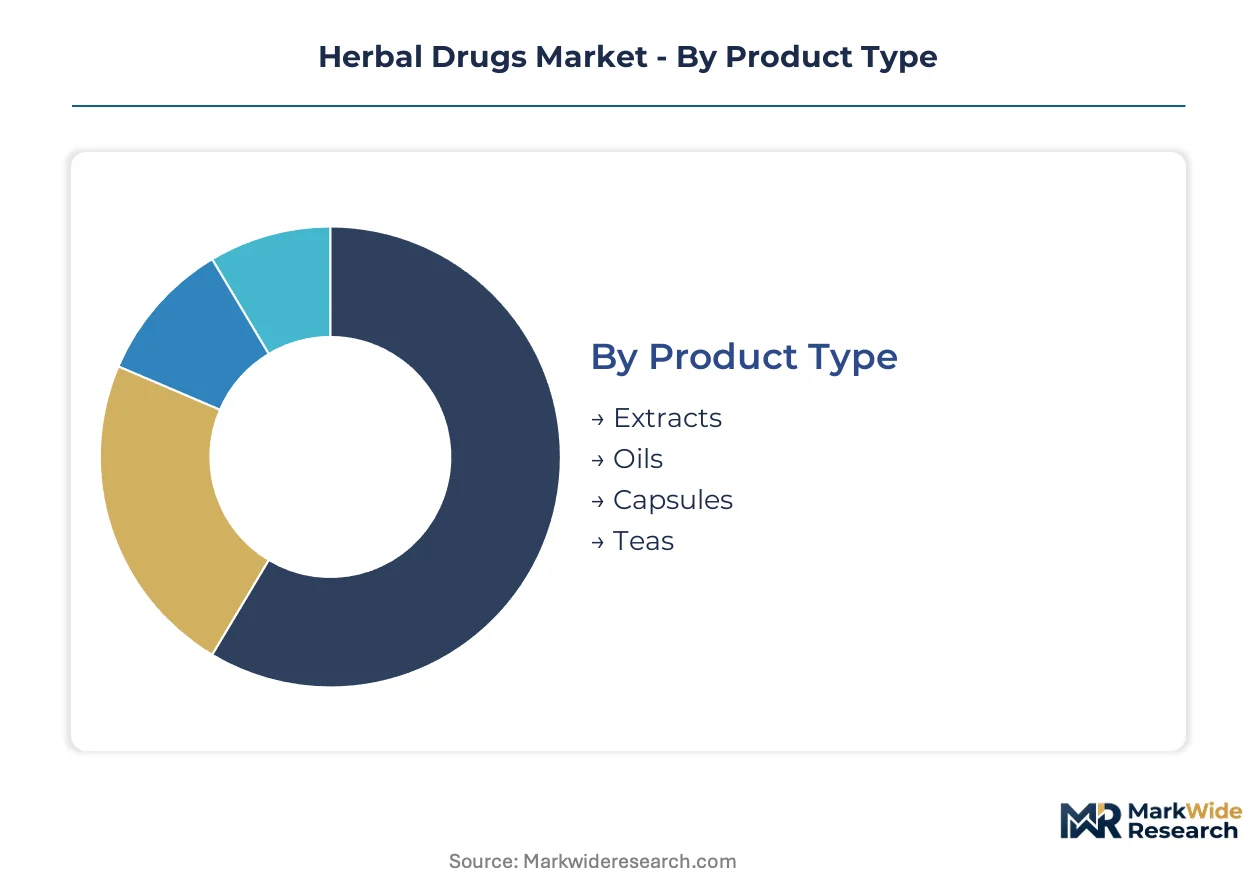
Segmentation in herbal drugs determines regulatory pathway eligibility and margin capture. Manufacturers align product architecture with reimbursement frameworks and distribution channel requirements.
Product Type:
Extract formulations face intensifying substitution pressure from synthetic phytochemical analogs, while whole-herb formats retain cost-sensitive consumer loyalty.
- Extracts:Concentrated preparations standardized to defined marker compound percentages through solvent or supercritical extraction. German pharmacy reimbursement under Commission E monographs concentrates demand for validated extracts, though laboratory-synthesized resveratrol and curcumin analogs erode pricing power in supplement channels.
- Oils:Lipid-soluble active fractions obtained through cold-pressing or steam distillation, requiring oxidative stability testing. Demand clusters in topical cosmeceutical applications across French and Italian dermatology brands seeking adaptogenic botanical positioning.
- Capsules:Encapsulated powders or standardized extracts in gelatin or vegetable shells. Ayurvedic heritage brands in India dominate volume through pharmacy distribution to diaspora markets.
- Teas:Whole or cut dried botanicals for aqueous infusion. Traditional herbal stores in Central Europe sustain volume despite online retail displacement.
Extracts anchor the volume base while cosmeceutical oil applications gain share at the steepest rate.
Application:
Cost tier stratification separates clinical-grade phytotherapy from mass-market nutraceutical positioning, with regulatory validation burden as the primary divider.
- Phytotherapy:Clinically validated botanical preparations prescribed within formal healthcare systems. EMA herbal monograph compliance enables reimbursement in Germany, Poland, and France, though FDA botanical drug development costs exclude traditional manufacturers from US prescription channels.
- Nutraceuticals:Dietary supplements positioned for wellness and preventive health. India's CDSCO AYUSH licensing framework accelerates domestic manufacturing scale and export certification.
- Cosmeceuticals:Topical formulations bridging cosmetic and therapeutic claims. Dermatology brands incorporate ashwagandha and rhodiola for adaptogenic positioning, expanding fastest among application segments.
- Functional Foods:Botanical-infused beverages and fortified food matrices. FSSAI regulatory clarity in India supports chai and herbal infusion commercialization.
Phytotherapy commands premium pricing while cosmeceuticals expand most quickly through dermatology channel penetration.
End User:
Channel maturity determines trust architecture and regulatory credibility for herbal drug procurement.
- Pharmacies:Licensed dispensaries with pharmacist oversight and reimbursement processing. German statutory health insurance coverage for Commission E-listed products sustains volume concentration.
- Herbal Stores:Traditional retail specializing in whole-herb and loose botanical sales. Urban concentration in Central European cities faces online displacement.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators. Subscription-based phytotherapy protocols concentrate in Australian and US coastal markets.
- Clinics:Integrative medicine practices combining herbal protocols with conventional care. Practitioner confidence depends on pharmacokinetic documentation and batch consistency.
Pharmacies retain regulatory credibility while online retail climbs the fastest in volume growth.
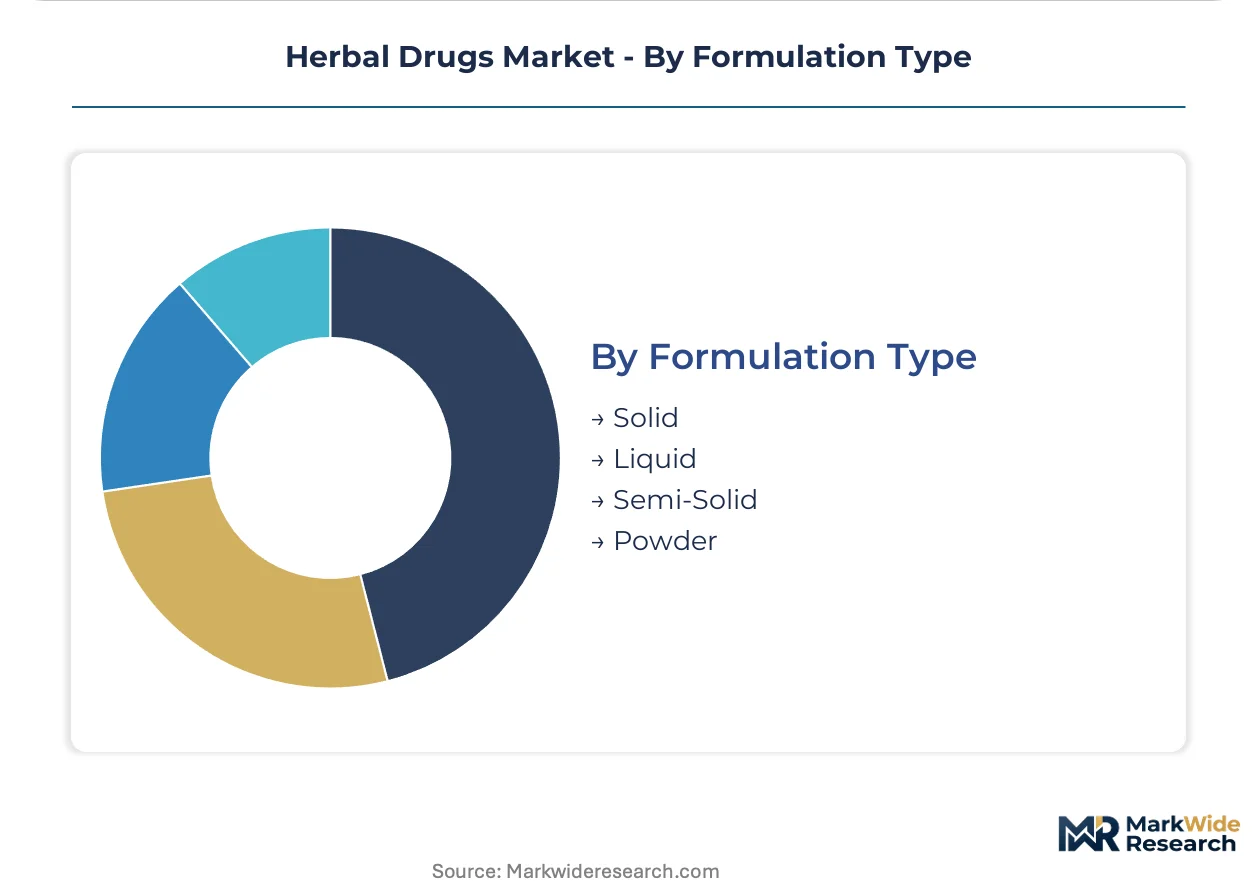
Formulation Type:
Manufacturing equipment specialization and stability requirements create supply-side segmentation.
- Solid:Tablets, capsules, and compressed dosage forms requiring dissolution testing. Standardized extract incorporation enables reproducible dosing profiles.
- Liquid:Tinctures, syrups, and aqueous extracts with defined concentration ratios. Alcohol-based preservation systems face formulation restrictions in Middle Eastern markets.
- Semi-Solid:Ointments, creams, and gels for topical delivery. Cosmeceutical demand drives semi-solid formulation investment.
- Powder:Bulk extracts and whole-herb preparations for compounding or encapsulation. Ayurvedic manufacturing in India concentrates powder production for domestic and export markets.
Solid formulations dominate prescription volume while semi-solid formats gain share fastest through dermatology expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor net exporters with captive cultivation networks, while import-dependent markets concentrate procurement through pharmacy reimbursement frameworks. Germany and India maintain structural trade surpluses in standardized extracts, whereas the United States and Japan rely on external sourcing for premium botanicals.
Germany
Commission E monographs sustain pharmacy reimbursement for prescribed phytomedicines, anchoring prescriber confidence in clinical-grade extracts. The country's national pharmaceutical regulator enforces batch consistency documentation through pharmacovigilance mandates. Karlsruhe and the Baden-Württemberg cluster host extraction facilities serving statutory health insurance channels across Central Europe.
India
CDSCO AYUSH licensing accelerates domestic manufacturing scale for Ayurvedic heritage formulations targeting diaspora markets. The streamlined regulatory pathway reduces export certification burdens for traditional medicine producers. Manufacturing concentrates in Maharashtra and Gujarat, where contract extractors serve European and North American importers seeking GMP-compliant botanicals.
United States
FDA botanical drug guidance imposes two-trial validation requirements that exclude traditional manufacturers from prescription channels, concentrating demand in dietary supplement formats. The agency's evolving framework rewards randomized trial investment while marginalizing undocumented preparations. Asheville and the Pacific Northwest host integrative medicine clinics driving practitioner-protocol demand for pharmacokinetically documented extracts.
Japan
Kampo medicine integration within national health insurance sustains demand for standardized herbal prescriptions requiring documented equivalence to reference extracts. The country's national pharmaceutical regulator enforces strict heavy metal and pesticide residue limits on imported raw materials. Manufacturing clusters in the Kanto region around Tokyo coordinate with domestic cultivation cooperatives to reduce wild-harvest dependence.
Australia
TGA complementary medicine regulations create tiered market access distinguishing listed from registered herbal products based on indication claims. The regulator's pharmacovigilance reporting system captures adverse event data informing monograph updates. Sydney and Melbourne anchor direct-to-consumer subscription phytotherapy brands targeting wellness-oriented urban demographics with personalized protocol bundles.
Herbal Drugs Market Competitive Landscape
Concentration sits with heritage Ayurvedic houses and German phytopharmaceutical specialists commanding pharmacy reimbursement access. The competitive terrain splits between clinical-grade extract manufacturers investing in randomized trial data and traditional formulators leveraging cultural brand equity. Three archetypes dominate: vertically integrated cultivator-extractors, clinically validated phytotherapeutic developers, and heritage wellness brands with diaspora distribution networks. Dominant competitive moves include backward integration into captive cultivation and strategic partnerships with genomic testing platforms for personalized protocol development.
Among German-based phytopharmaceutical developers, Dr. Willmar Schwabe GmbH & Co. KG and Bionorica SE exemplify the clinical-validation archetype through Commission E-aligned manufacturing and pharmacokinetic documentation. Dabur India Limited occupies a position representing heritage Ayurvedic formulators with pharmacy channel penetration across South Asian and diaspora markets. These three entities anchor distinct competitive vectors: standardized clinical extracts, evidence-based monograph compliance, and traditional knowledge brand extension.
| Leading Market Players |
|---|
| Dr. Willmar Schwabe GmbH & Co. KG |
| Baidyanath Group |
| Himalaya Drug Company |
| Gaia Herbs |
| Nature's Way Products LLC |
| Dabur India Limited |
| Blackmores Limited |
| Bionorica SE |
| Tsumura & Co. |
| Others |
Value Network & Pricing Analysis
Commission E monograph compliance gates both German pharmacy reimbursement eligibility and the premium pricing tier for standardized extracts, compressing undocumented traditional preparations into commodity positioning while rewarding manufacturers with pharmacovigilance documentation. This dual-gate mechanism concentrates pricing power among EMA-aligned producers and forces supply chain investments in batch-traceable cultivation networks.
Pricing Analysis
The customization-premium spread separates configured-to-order clinical extracts from standard dietary supplement formats, with pharmacokinetic documentation commanding substantial premia in German prescription channels. Price differentiation hinges on EMA herbal monograph alignment and DNA barcoding certification grade, while synthetic phytochemical substitution in wellness markets drives cost compression in non-reimbursed tiers. Institutional buyers in statutory health insurance systems exhibit lowest price sensitivity; direct-to-consumer segments face acute pressure from laboratory-produced curcumin and resveratrol analogs.
Supply Chain Analysis
Wild-harvest dependence in the Appalachian range, Manchurian ginseng belts, and southern African hoodia territories creates sourcing chokepoints that constrain premium extract availability. Raw material flows draw from cultivated networks in Germany, India, and Japan alongside concentrated wild zones, with botanical identification expertise scarcity amplifying single-source vulnerability for DNA-validated inputs. Distribution runs through pharmacy reimbursement channels in Germany and CDSCO-certified export corridors from Maharashtra and Gujarat, though online retail displacement is fragmenting traditional herbal store procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified taxonomists capable of chromatographic fingerprinting and DNA barcoding validation command compensation premia that outstrip production labor costs, constraining expansion for manufacturers lacking captive expertise pipelines. This capability bottleneck favors incumbents with established phytochemistry training programs and disadvantages contract-reliant formulators.
For Market Incumbents: Secure backward integration into captive cultivation networks across multiple continents to insulate against wild-harvest supply shocks and adulteration risks. Invest in pharmacogenomic testing partnerships to capture subscription protocol revenue before digital health platforms commoditize personalization. Defend Commission E-aligned positioning against synthetic phytochemical substitution through expanded pharmacokinetic documentation and practitioner education programs. For New Entrants and Emerging Players: Differentiate on blockchain-enabled provenance verification to address premium extract adulteration concerns in North American and Australian direct-to-consumer channels. Target Brazilian ANVISA regulatory convergence ahead of formal monograph adoption, establishing local pharmacovigilance infrastructure before heritage manufacturers consolidate first-mover advantage. Pursue white-space positioning in adaptogenic cosmeceuticals through dermatology brand partnerships rather than competing on clinical trial investment with German phytopharmaceutical specialists. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across extract standardization equipment and supercritical CO2 extraction vessel procurement, favoring scaled manufacturers with existing chromatography infrastructure over greenfield entrants. Long-term viability across the analysis window rests on acquisition of vertically integrated cultivator-extractors with EMA-aligned documentation capabilities rather than heritage brand portfolios lacking pharmacokinetic validation. Monitor FDA botanical drug guidance evolution as the critical signal for whether clinical trial investment thresholds will exclude additional traditional manufacturers from US prescription channels.| Strategic Initiative | Industry Significance |
|---|---|
| DNA Barcoding Infrastructure Deployment | EMA pharmacovigilance mandates in Germany and Poland now require molecular authentication protocols for reimbursed extracts. |
| Captive Cultivation Network Expansion | Dr. Willmar Schwabe and Bionorica have secured multi-continent raw material consistency through controlled agricultural partnerships. |
| Pharmacogenomic Testing Integration | Sydney and Melbourne subscription brands bundle personalized herbal regimens with telehealth consultations for recurring revenue capture. |
| Blockchain Provenance Verification | Distributed ledger technologies address premium extract adulteration concerns in Australian and US coastal direct-to-consumer markets. |
| CDSCO AYUSH Export Certification | Maharashtra and Gujarat contract extractors leverage streamlined regulatory pathways to serve European and North American GMP-compliant demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with herbal drug manufacturing executives, regulatory affairs specialists at EMA and CDSCO, pharmacy procurement managers in German statutory health insurance channels, and integrative medicine practitioners; alongside secondary validation through FDA botanical drug guidance documents, EMA herbal monograph databases, CDSCO AYUSH licensing records, and customs trade data for standardized extract flows. Bottom-up volume modeling triangulated against top-down expenditure estimates across the analysis window.
Across the projection horizon, the analytical framework segmented by product type, application, end-user channel, and formulation complexity, with regional regulatory cluster effects modeled separately. CAGRs derived from historical volume trajectories adjusted for reimbursement policy shifts and synthetic substitution elasticities. Key inputs included Commission E monograph update schedules, supercritical extraction equipment lead times, and practitioner protocol adoption curves in integrative medicine clinics.
The analysis sits within stated boundaries; outcomes outside sustained EMA herbal monograph enforcement and CDSCO AYUSH licensing stability would require recalibration. Forecasts reflect documented assumptions regarding wild-harvest supply continuity and synthetic phytochemical substitution rates. Practitioners should keep alternative scenarios live as FDA botanical drug guidance evolution and REACH regulation amendments for botanical substance registration reshape market access thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Global 3D Printed Drugs Market