
 Antimicrobial Resistance Diagnostics Market | 2026-2036
Antimicrobial Resistance Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Resistance Diagnostics Market Intelligence
China is tilting toward domestic molecular diagnostic manufacturing for resistance gene detection. bioMérieux leverages its European reference laboratory network to sustain assay validation depth. Danaher anchors North American hospital contracts through integrated microbiology workflows. Abbott competes in point-of-care resistance testing with simplified cartridge-based platforms.
Antimicrobial resistance diagnostics encompass laboratory and near-patient systems that detect bacterial, fungal, or viral pathogen susceptibility to therapeutic agents, typically reporting minimum inhibitory concentrations or genetic resistance markers within 2–48 hours to guide treatment decisions. Molecular diagnostic tests lead segment value due to multiplexed gene detection capability, while next generation sequencing occupies the fastest-expanding technology tier as whole-genome epidemiology gains hospital pharmacy adoption. Culture tests retain substantial volume in resource-limited settings where infrastructure constraints favor conventional phenotypic methods.
FDA antimicrobial susceptibility device requirements and EMA in vitro diagnostic regulations shape product development timelines and clinical evidence thresholds for market authorization. The EU AI Act and IVDR convergence will force algorithm-dependent susceptibility prediction tools through enhanced conformity assessment pathways. Stakeholders must monitor reimbursement coding evolution for rapid resistance panels versus conventional culture-based methods.
Market Dynamics
Hospital pharmacy and infectious disease departments are consolidating procurement around integrated resistance testing workflows that compress time-to-therapeutic-decision from days to hours, reshaping vendor contracting structures and assay validation requirements.
Growth Catalysts
- IVDR Conformity Assessment:The EU In Vitro Diagnostic Regulation mandates clinical evidence thresholds for susceptibility prediction algorithms, accelerating hospital laboratory investment in validated molecular platforms.
- Integrated Delivery Networks:US hospital systems are standardizing resistance panel procurement across affiliated laboratories, creating volume commitments that justify automated susceptibility testing infrastructure.
- Multiplexed Gene Detection:Resistance gene panels covering carbapenemases, ESBLs, and methicillin resistance markers enable simultaneous pathogen identification and susceptibility profiling from positive blood cultures.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction chemistries and resistance gene probe libraries concentrate among specialized biochemical suppliers in Germany and the United States.
- Phenotypic Method Persistence:Culture-based susceptibility testing retains dominance in resource-limited settings where cold-chain-dependent molecular platforms face infrastructure barriers.
- FDA Enforcement Lag:Antimicrobial susceptibility testing device clearances require extensive clinical correlation studies, extending product development timelines for novel resistance mechanisms.
Strategic Opportunities
- Community Hospital Penetration:Mid-sized US hospitals outside academic medical centers represent underpenetrated demand for rapid resistance panels with simplified workflow integration.
- Whole-Genome Epidemiology:Next-generation sequencing convergence with clinical microbiology enables resistance gene surveillance and outbreak tracing within hospital pharmacy stewardship programs.
- Point-of-Care Expansion:Simplified cartridge-based platforms targeting emergency departments and intensive care units bypass centralized laboratory bottlenecks for critical therapeutic decisions.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories face recruitment gaps for specialists capable of interpreting next-generation sequencing resistance profiles and validating algorithmic susceptibility predictions.
- Legacy System Integration:Hospital laboratory information systems require extensive middleware development to incorporate molecular susceptibility results into existing antimicrobial stewardship dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Resistance Diagnostics Market |
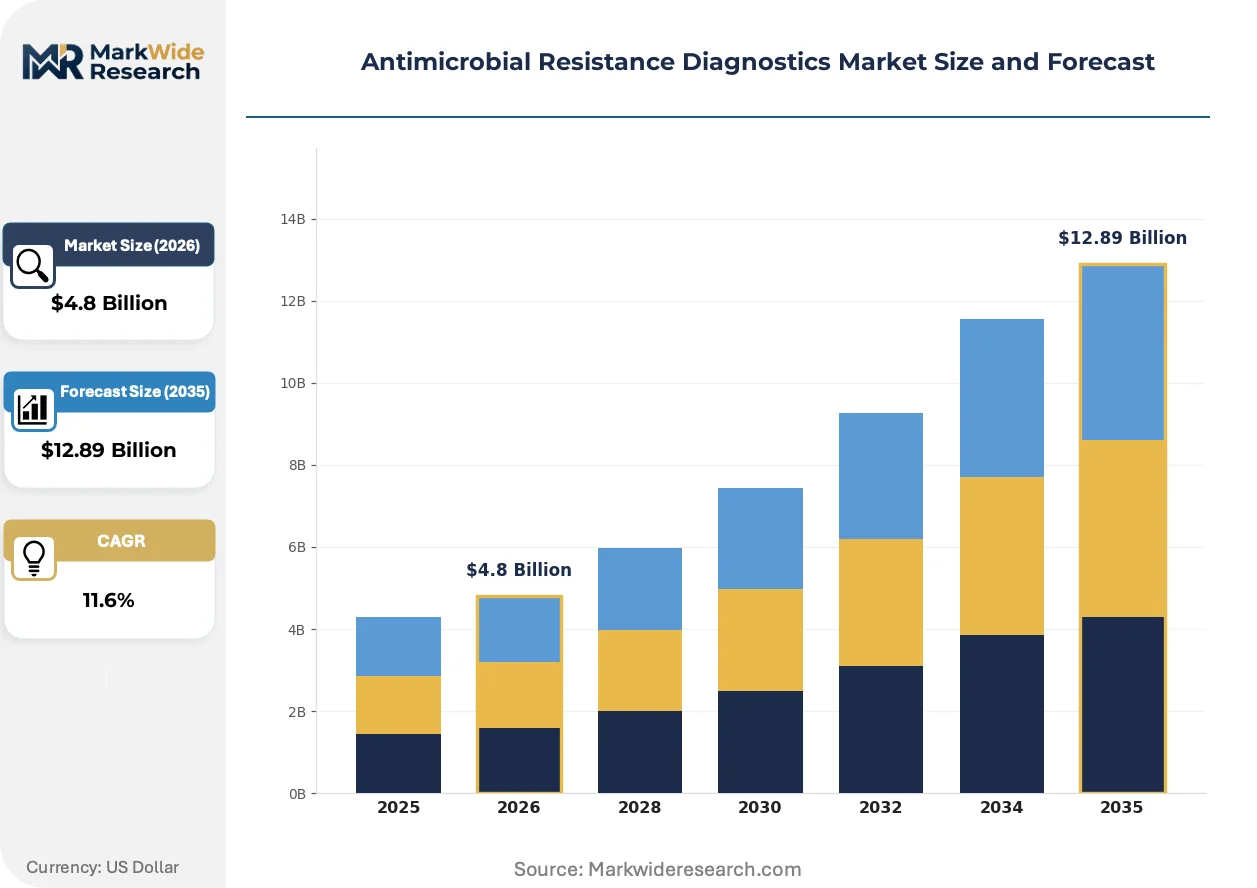
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Culture Tests, Molecular Diagnostic Tests, Immunoassays, Rapid Tests Technology: Polymerase Chain Reaction, Next Generation Sequencing, Microarray Technology, Mass Spectrometry End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Sample Type: Blood, Urine, Sputum, Stool |
| Companies Covered | bioMérieux, Abbott, Danaher, F. Hoffmann-La Roche Ltd., BD, Thermo Fisher Scientific, Hologic Inc., Accelerate Diagnostics, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Resistance Diagnostics Market Strategic Shifts & Innovations
Resistance diagnostics is pivoting from centralized reference laboratory models toward distributed testing architectures that embed rapid susceptibility determination at the point of therapeutic decision.
Next-generation sequencing platforms are virtualizing the reference laboratory function for resistance surveillance. Academic medical centers in the United States and Western Europe are adopting benchtop sequencers for real-time outbreak investigation and resistance gene epidemiology. This technology is virtualizing the traditional send-out model for complex susceptibility profiling, compressing turnaround times from weeks to same-day results while enabling hospital-specific resistance atlases.
The EU AI Act intersects with IVDR implementation to impose enhanced conformity assessment on machine-learning susceptibility prediction tools. Algorithm-dependent resistance forecasting now requires documented training dataset provenance and clinical validation across diverse pathogen populations. European manufacturers are restructuring product development pipelines to segregate rule-based from adaptive algorithmic components, with the latter facing extended notified body review timelines.
Pharmacy-driven procurement is consolidating resistance testing contracts under antimicrobial stewardship program budgets rather than laboratory capital allocations. Hospital systems in the United States are bundling rapid susceptibility panel access with therapeutic guidance software subscriptions, displacing standalone instrument purchasing models. This shift is most pronounced among integrated delivery networks managing pharmacy spend across fifty or more affiliated facilities.
Antimicrobial Resistance Diagnostics Market Segmentation
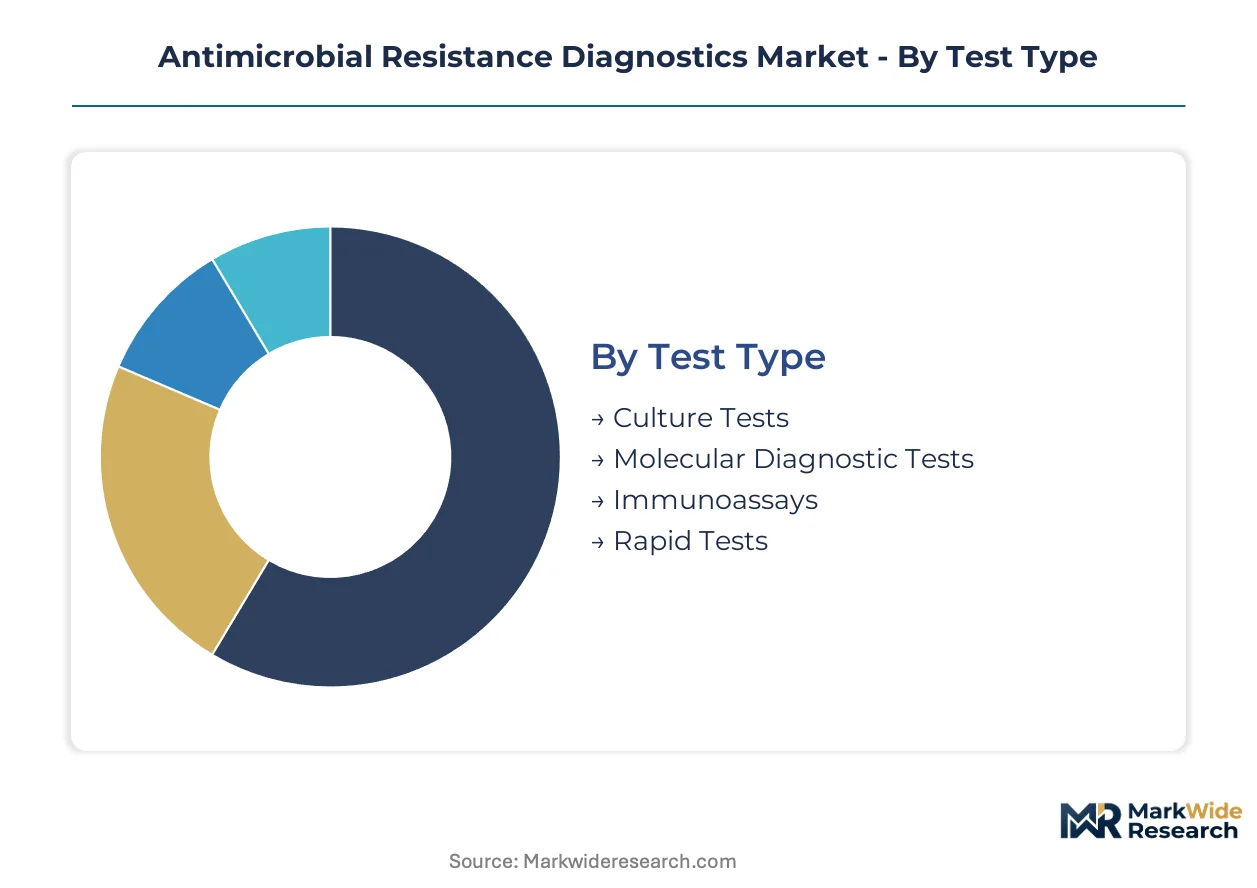
Antimicrobial resistance diagnostics fragment across test methodologies, detection technologies, care settings, and specimen sources. Each dimension shapes procurement patterns, regulatory pathways, and reimbursement structures differently.
Test Type:
Resistance detection spans phenotypic culture methods to nucleic acid amplification, with adoption curves diverging by infrastructure maturity and turnaround requirements.
- Molecular Diagnostic Tests:Multiplexed PCR and nucleic acid amplification platforms detect resistance genes directly from clinical specimens within 2–6 hours. Hospital laboratories in the United States prioritize these for bloodstream infection panels where delayed appropriate therapy elevates mortality.
- Culture Tests:Conventional phenotypic susceptibility testing remains the reference standard, requiring 24–48 hours for bacterial isolation and minimum inhibitory concentration determination. Resource-limited settings depend on these methods where cold-chain logistics and capital equipment constraints exclude molecular alternatives.
- Rapid Tests:Lateral flow and immunochromatographic devices deliver resistance marker detection at the point of care without laboratory infrastructure.
- Immunoassays:Enzyme-linked and chemiluminescent methods quantify resistance-related biomarkers or pathogen antigens in centralized laboratory workflows.
The dominant share belongs to Culture Tests, while Molecular Diagnostic Tests is closing the gap fastest.
Technology:
Detection modalities concentrate around amplification chemistry, with emerging platforms compressing turnaround and expanding resistance gene coverage.
- Polymerase Chain Reaction:Real-time and digital PCR chemistries dominate commercial resistance panels, targeting carbapenemase, ESBL, and methicillin resistance genes with established clinical validation libraries.
- Next Generation Sequencing:Benchtop sequencers enable whole-genome resistance profiling and outbreak tracing through single-nucleotide polymorphism analysis. Academic medical centers deploy these for hospital-specific resistance atlases and real-time epidemiology.
- Mass Spectrometry:MALDI-TOF platforms identify pathogens through protein fingerprinting, with emerging resistance detection through antibiotic hydrolysis assays.
- Microarray Technology:Solid-phase hybridization arrays simultaneously probe thousands of resistance gene variants, applied primarily in reference laboratory surveillance applications.
Polymerase Chain Reaction commands installed base leadership, though Next Generation Sequencing exhibits the steepest expansion trajectory among hospital pharmacy stewardship programs.
End User:
Procurement authority is migrating from laboratory capital budgets toward pharmacy and antimicrobial stewardship program control.
- Hospitals:Integrated delivery networks consolidate resistance testing contracts across affiliated laboratories, bundling rapid panel access with therapeutic guidance software subscriptions.
- Diagnostic Laboratories:Independent and hospital-affiliated reference laboratories process send-out susceptibility testing for community hospitals lacking in-house molecular infrastructure.
- Research Institutions:Academic centers drive next-generation sequencing adoption for resistance surveillance and novel mechanism discovery.
- Home Care:Limited penetration reflects specimen collection complexity and regulatory barriers to decentralized resistance testing outside clinical settings.
Hospitals retain procurement volume leadership, while Diagnostic Laboratories are gaining share fastest through regional reference network consolidation.
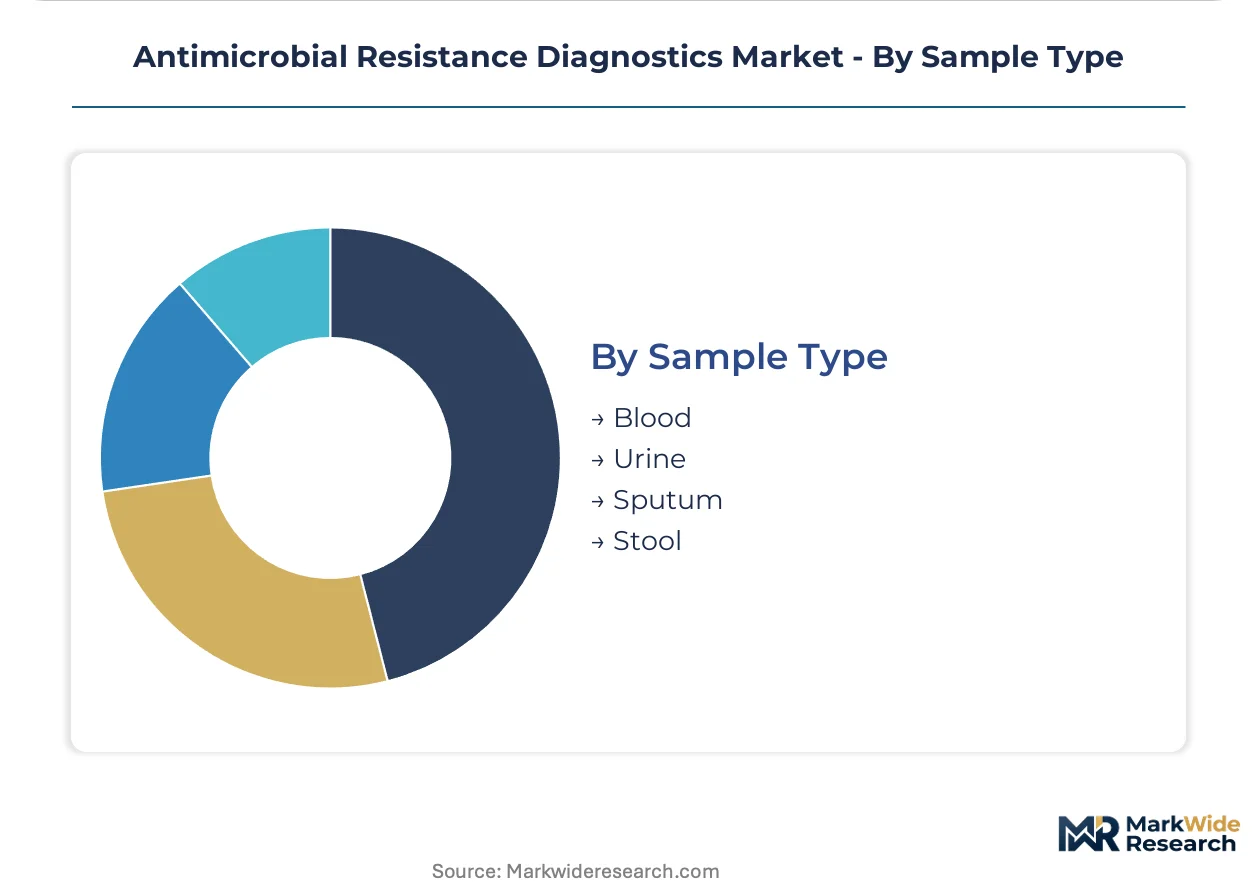
Sample Type:
Specimen source determines assay design complexity, with bloodstream and respiratory matrices commanding development priority.
- Blood:Bloodstream infections drive mortality urgency, making positive blood culture panels the highest-value resistance diagnostic application.
- Sputum:Respiratory specimens require pathogen-specific lysis protocols and contamination controls for reliable resistance gene detection.
- Urine:Urinary tract infection panels target uropathogen resistance markers with simplified extraction workflows.
- Stool:Gastrointestinal resistance surveillance focuses on enteric pathogen carriage and colonization screening for multidrug-resistant organisms.
Blood specimen testing dominates revenue concentration, while Sputum-based applications are expanding most quickly through respiratory pathogen panel integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic reagent manufacturing clusters in Germany and the United States concentrate polymerase chain reaction chemistry supply, while hospital procurement consolidation across integrated delivery networks reshapes regional demand patterns. Regulatory divergence between FDA antimicrobial susceptibility enforcement and EMA IVDR implementation creates divergent product development timelines. Market authorization pathways now require clinical correlation studies spanning multiple pathogen populations.
United States
Integrated delivery networks managing fifty or more affiliated facilities are bundling rapid resistance panel access with therapeutic guidance software subscriptions. FDA enforcement of antimicrobial susceptibility testing standards tightens quality requirements for commercial assays seeking 510(k) clearance. The Boston-Cambridge corridor anchors molecular diagnostic R&D concentration, with academic medical centers driving next-generation sequencing adoption for hospital-specific resistance atlases.
Germany
Specialized biochemical suppliers in Baden-Württemberg and Bavaria concentrate polymerase chain reaction chemistries and resistance gene probe libraries. EMA in vitro diagnostic regulations and the EU AI Act impose enhanced conformity assessment on machine-learning susceptibility prediction tools. The Rhine-Main biotech cluster hosts reference laboratory networks sustaining assay validation depth for European market access.
China
Domestic molecular diagnostic manufacturing for resistance gene detection receives policy support through national health security initiatives. NMPA regulatory pathways for innovative diagnostic devices accelerate review timelines for locally developed carbapenemase detection platforms. The Yangtze River Delta biopharma corridor concentrates contract manufacturing organizations scaling multiplexed gene panel production.
United Kingdom
NHS antimicrobial stewardship programs drive procurement standardization across hospital trust networks, consolidating resistance testing contracts under pharmacy budgets. MHRA post-Brexit regulatory autonomy enables tailored pathways for rapid diagnostic devices targeting bloodstream infections. The Oxford-Cambridge-London golden triangle anchors next-generation sequencing research translation into clinical microbiology workflows.
Japan
PMDA regulatory frameworks for infectious disease diagnostics emphasize clinical evidence from domestic patient populations for resistance gene panel approval. METI industrial policy supports diagnostic platform development through public-private partnerships targeting carbapenem-resistant enterobacteriaceae surveillance. The Kansai region's medical device manufacturing base supplies automated susceptibility testing instrumentation across Asia-Pacific markets.
Antimicrobial Resistance Diagnostics Market Key Industry Players
Full-system integrators and specialized molecular diagnostic developers split the market into distinct capability tiers. Consolidation pressure intensifies as hospital laboratories demand validated end-to-end workflows rather than discrete instrument purchases. Three archetypes dominate: European reference laboratory network operators, North American integrated microbiology workflow providers, and point-of-care cartridge platform specialists. Competitive moves center on strategic partnerships for algorithm validation and geographic expansion through distribution agreements in Asia-Pacific markets.
Within the European reference laboratory tier, bioMérieux exemplifies network-dependent validation depth. Among North American integrated workflow providers, Danaher occupies a position anchoring hospital contracts through automated microbiology platforms. Abbott represents the point-of-care archetype with simplified cartridge-based systems targeting emergency department deployment. These three companies illustrate how regulatory compliance capabilities and workflow integration depth determine procurement outcomes in consolidated health systems.
| Leading Market Players |
|---|
| bioMérieux |
| Abbott |
| Danaher |
| F. Hoffmann-La Roche Ltd. |
| BD |
| Thermo Fisher Scientific |
| Hologic Inc. |
| Accelerate Diagnostics |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
Rhine-Main freight corridors linking German biochemical suppliers to European hospital networks impose cold-chain logistics premiums that concentrate pricing power among integrated platform vendors while fragmenting procurement costs for standalone assay purchasers.
Pricing Analysis
FDA antimicrobial susceptibility testing enforcement dictates the pricing tier structure for commercial assays seeking 510(k) clearance. Three-tier pricing structure across premium, standard, and economy levels separates validated molecular platforms from conventional culture methods and rapid lateral flow devices. Cost compression in economy-tier phenotypic testing is intensifying because of reagent commoditization and emerging domestic manufacturing in China. Community hospital laboratories exhibit highest price sensitivity, while integrated delivery networks leverage volume commitments for subscription-based rapid panel access.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk assessment for polymerase chain reaction chemistries and resistance gene probe libraries. Manufacturing concentrates in Baden-Württemberg, the Yangtze River Delta, and Massachusetts for specialized biochemical inputs. Raw material dependencies include fluorophore-conjugated primers, magnetic bead extraction matrices, and synthetic oligonucleotide libraries. Single-source vulnerability persists for carbapenemase gene probe synthesis. Distribution runs through regional reference laboratory networks that validate assay batches before hospital deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial resistance diagnostics is approaching a platform-economics inflection where hospital pharmacy stewardship programs function as orchestration layers, with interoperability between rapid susceptibility results and therapeutic guidance software determining vendor lock-in depth.
For Market Incumbents: Build data network effects by embedding resistance atlases into hospital pharmacy stewardship dashboards, preempting middleware competitors. Deepen backward integration into resistance gene probe synthesis to secure supply continuity against German-Chinese tariff friction. Anchor contracts through automated microbiology workflow integration rather than standalone instrument placement, as emerging point-of-care cartridge platforms threaten centralized laboratory volume. For New Entrants and Emerging Players: Build out simplified cartridge-based platforms targeting emergency departments and intensive care units where time-to-therapeutic-decision compression justifies premium positioning. Mid-sized US community hospitals outside academic medical centers represent the most penetrable segment, lacking in-house molecular infrastructure but facing identical mortality pressure from delayed appropriate therapy. Pursue GPO contract access through antimicrobial stewardship program budget channels rather than laboratory capital allocation routes. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underoptimized diagnostic divisions lacking hospital system integration depth. Long-term viability hinges on algorithmic susceptibility prediction capabilities validated across diverse pathogen populations, with regulatory compliance timelines extending competitive moats. Watch FDA enforcement acceleration on antimicrobial susceptibility device clearances as the inflection signal for consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Assessment Investment | Accelerates European market access for algorithm-dependent susceptibility prediction tools facing EU AI Act intersection. |
| Hospital System Partnership Consolidation | Bundles rapid resistance panel access with therapeutic guidance software across fifty-plus affiliated facilities. |
| Next-Generation Sequencing Platform Integration | Virtualizes reference laboratory function for whole-genome epidemiology and real-time outbreak investigation. |
| Point-of-Care Cartridge Development | Bypasses centralized laboratory bottlenecks for critical bloodstream infection therapeutic decisions. |
| Reimbursement Strategy Alignment | Secures favorable coding for rapid resistance panels versus conventional culture-based methods in CMS frameworks. |
Research Approach
Initial hypotheses were tested against primary input from hospital pharmacy directors, clinical microbiology laboratory managers, infectious disease specialists, GPO contracts managers, and diagnostic platform engineers and refined through secondary validation against FDA 510(k) filings, EMA IVDR submission databases, hospital procurement records, CMS reimbursement coding updates, and antimicrobial stewardship program budget disclosures. Bottom-up assay volume modeling triangulated with top-down health system expenditure tracking.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling test type, technology platform, end user procurement authority, and specimen source segmentation dimensions. CAGRs were derived from installed base expansion rates and replacement cycle compression. Forecast inputs incorporated IVDR implementation timelines and FDA enforcement acceleration patterns for susceptibility testing standards.
Stress conditions across regulatory approval delays, reagent supply disruptions, and hospital capital budget freezes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on molecular platform adoption curves and stewardship program budget migration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
H. Pylori Breath Test Kit Market