
 Oral Mucositis Market | 2026-2036
Oral Mucositis Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Mucositis Market Outlook
Oncology clinic protocols are rebalancing toward preventive management as intensity-modulated radiation therapy expands. Amgen Inc. leverages biologic manufacturing scale to sustain supply of palifermin-derived therapies across major cancer centers. Soligenix Inc. specializes in synthetic hypericin formulations for photodynamic intervention. Helsinn Healthcare SA anchors European distribution through its oncology-focused commercial infrastructure.
Oral mucositis denotes inflammatory ulceration of the oral mucosa triggered by cytotoxic cancer therapies, characterized by epithelial stem cell depletion and neutrophil-mediated tissue breakdown that disrupts nutrition intake and treatment adherence. The condition demands barrier-forming gels, antimicrobial mouth rinses, and keratinocyte growth factor formulations to preserve mucosal integrity during chemotherapy cycles. Growth factors command premium positioning due to biological manufacturing complexity and targeted severe-stage applications, while mouth rinses occupy high-volume preventive protocols across hospital infusion centers. Gel formulations lead in patient compliance metrics for moderate-grade cases, whereas spray delivery is gaining traction in home care settings for ease of administration during active treatment.
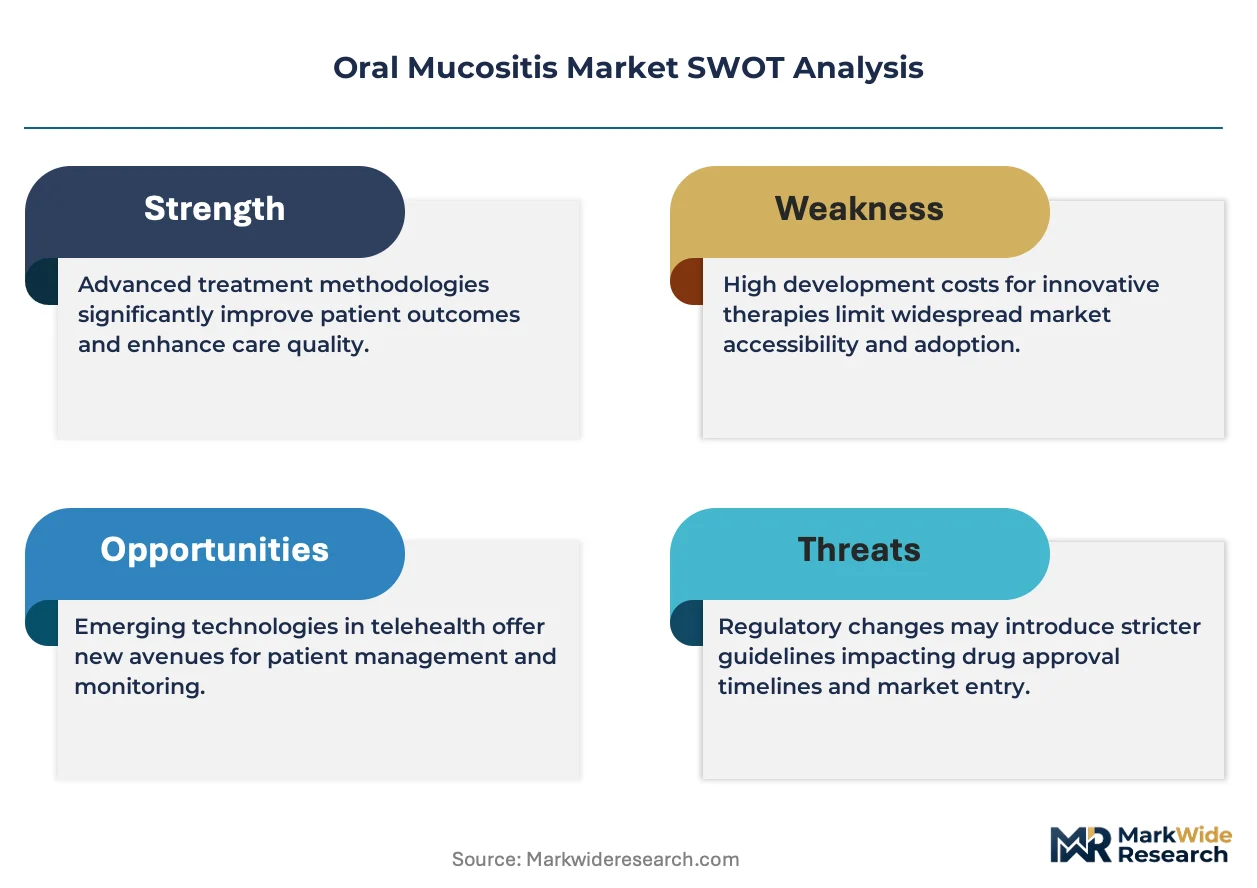
FDA orphan drug designations shape development economics for severe-grade biologics, while EMA's pediatric investigation plans extend regulatory requirements into adolescent oncology protocols. The EU MDR recertification timeline pressures smaller device-format manufacturers to consolidate quality management systems. Stakeholders must monitor reimbursement coding shifts for prophylactic versus therapeutic administration as value-based oncology contracts expand.
Market Dynamics
Intensity-modulated radiation therapy expansion is rebalancing oncology clinic protocols toward preventive mucosal management, compressing the window between diagnosis and prophylactic intervention while elevating demand for barrier-forming and growth factor formulations.
Growth Catalysts
- FDA Orphan Drug Incentives:Accelerated development timelines and tax credits for severe-grade biologics reduce capital barriers for novel keratinocyte growth factor therapies targeting grade 3-4 mucositis.
- Head-and-Neck Cancer Treatment Volumes:Rising radiation oncology caseloads in the United States drive prescription rates for prophylactic mouth rinses and gel formulations across hospital infusion centers.
- Photodynamic Intervention Platforms:Synthetic hypericin formulations enable targeted mucosal repair protocols that integrate with existing chemotherapy cycles, expanding therapeutic options beyond traditional barrier methods.
Market Restraints
- Biological Manufacturing Complexity:Growth factor production requires specialized recombinant DNA facilities with extended validation timelines, constraining supply elasticity for severe-stage therapies.
- EU MDR Recertification Pressure:Smaller device-format manufacturers face quality management system consolidation costs that compress margins on antimicrobial mouth rinse portfolios.
- Reimbursement Coding Fragmentation:Divergent prophylactic versus therapeutic administration classifications across Medicare and commercial payers create prior authorization friction for preventive protocols.
Strategic Opportunities
- Home Care Spray Delivery:Aerosolized formulations for moderate-grade cases address patient compliance gaps outside hospital settings, capturing value from treatment cycle decentralization.
- Pediatric Investigation Plans:EMA-mandated adolescent oncology protocols extend addressable populations for existing severe-grade biologics with modified dosing regimens.
- Value-Based Oncology Contracts:Outcome-linked reimbursement models reward mucositis prevention metrics, aligning provider incentives with prophylactic gel and rinse adoption.
Industry Challenges
- Stem Cell Biology Expertise Scarcity:Epithelial regeneration research talent concentrates in academic medical centers, limiting commercial R&D bandwidth for next-generation barrier technologies.
- Legacy Quality System Integration:Device-format manufacturers merging with biologic developers face ISO 13485 and GMP harmonization timelines that delay portfolio unification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Mucositis Market |
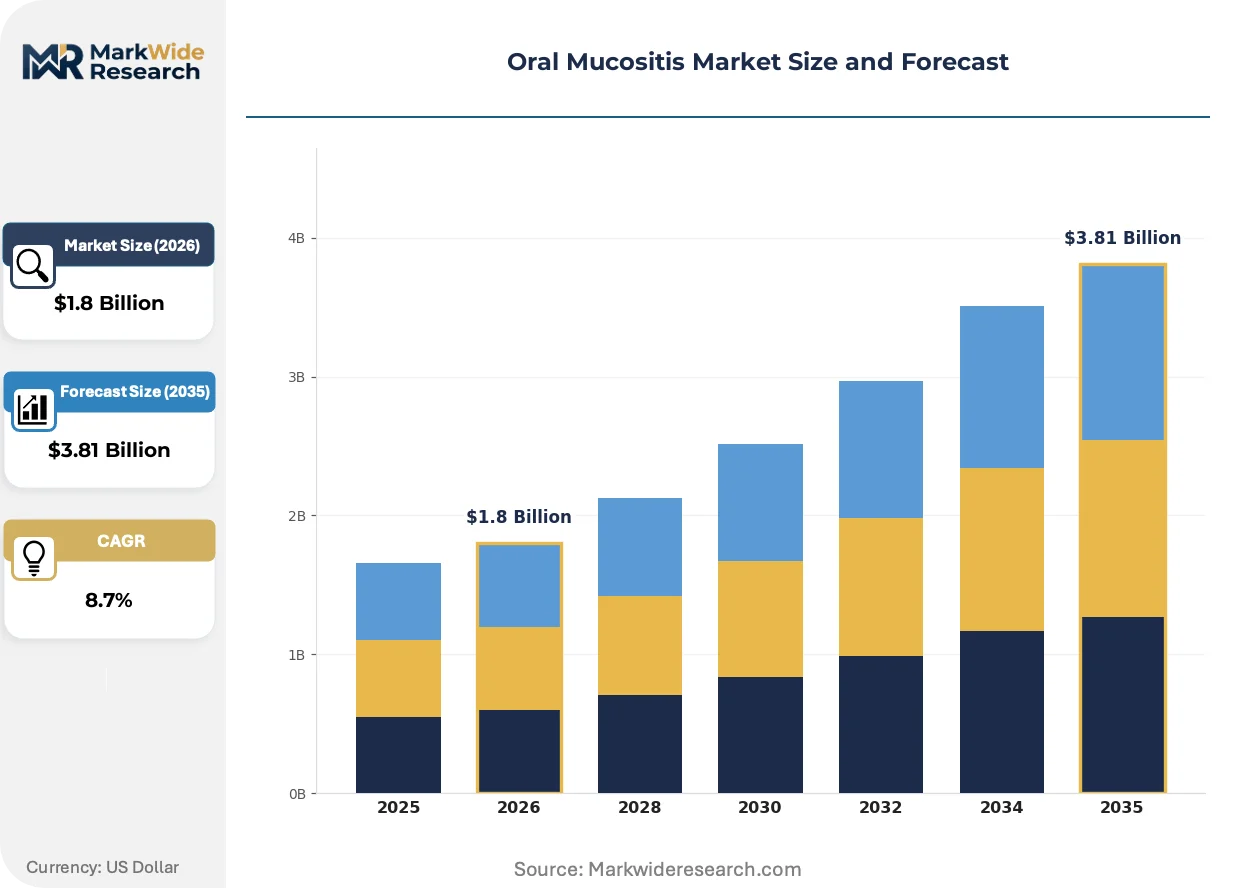
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Topical Analgesics, Antimicrobial Agents, Mouth Rinses, Growth Factors Stage of Disease: Preventive, Mild, Moderate, Severe Formulation: Gel, Spray, Mouthwash, Lozenges End User: Hospitals, Clinics, Home Care, Research Institutes |
| Companies Covered | Amgen Inc., Galera Therapeutics Inc., Soligenix Inc., Helsinn Healthcare SA, Innovation Pharmaceuticals Inc., Pfizer Inc., Bausch Health Companies Inc., Merck & Co., EpicentRx Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Mucositis Market Strategic Shifts
Photodynamic and biomaterial platforms are converging with digital patient monitoring to transform mucosal injury management from reactive treatment to predictive prevention, compressing intervention timelines and reshaping competitive positioning across formulation categories.
Light-activated synthetic hypericin formulations are integrating with standard chemotherapy protocols to enable selective epithelial stem cell protection. Major cancer centers in Germany and the United States are piloting these platforms for head-and-neck radiation patients. The technology is integrating photobiomodulation principles with existing clinical workflows, creating new protocol layers that supplement rather than displace growth factor therapies.
EMA's pediatric investigation plan mandates now extend into adolescent oncology, requiring sponsors to generate age-stratified mucositis efficacy data for severe-grade biologics. This regulatory expansion forces protocol redesign for keratinocyte growth factor trials and delays adult-label exclusivity periods. European oncology networks are responding by establishing dedicated adolescent mucositis assessment units to streamline compliance.
Hospital purchasing coalitions are consolidating oral care product procurement under single-source agreements that bundle barrier gels, antimicrobial rinses, and growth factors. This concentration displaces fragmented supplier relationships and shifts negotiation leverage toward integrated portfolio vendors. The pattern is most visible in United States academic medical centers where value-based contracts tie reimbursement to mucositis incidence reduction metrics.
Oral Mucositis Market Segmentation
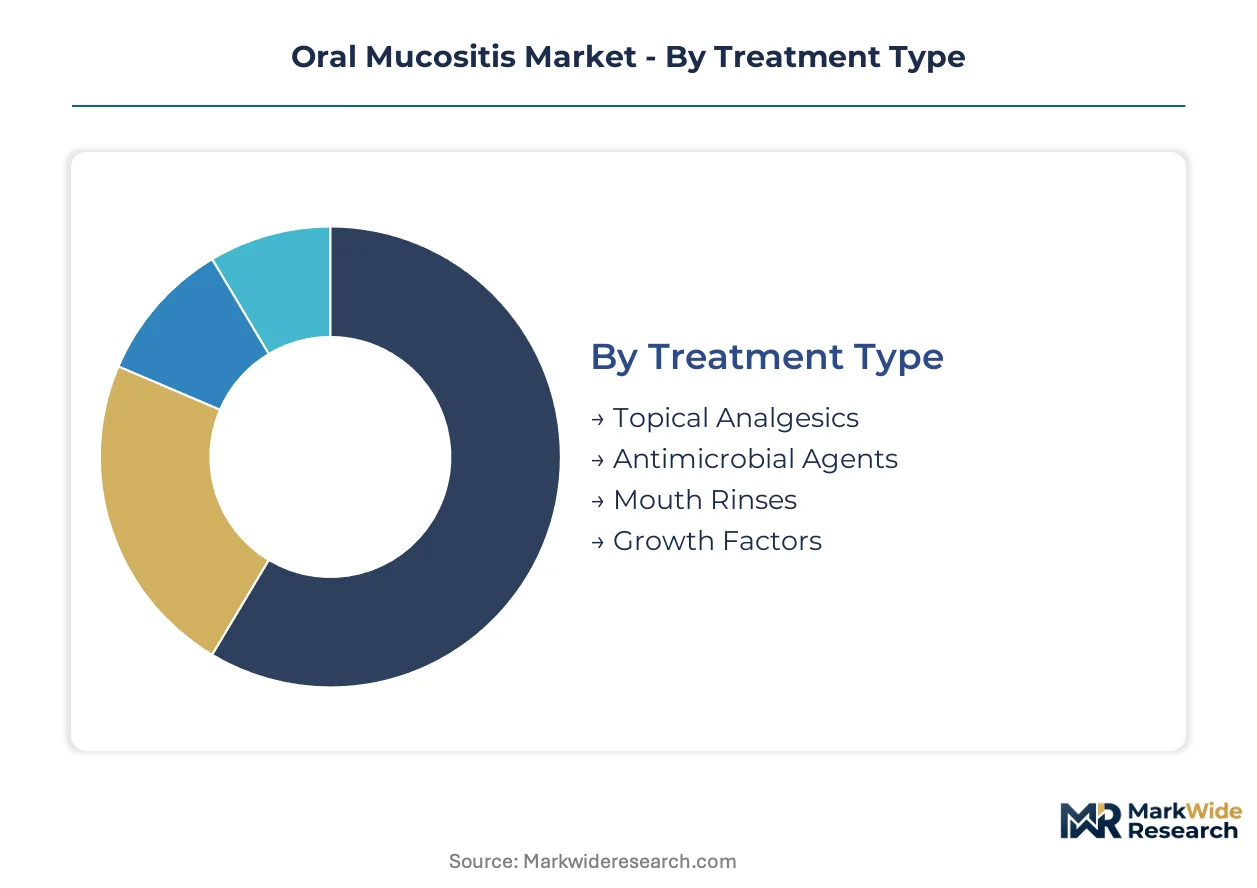
Oral mucositis therapies serve distinct clinical moments across the cancer treatment cycle, from prophylactic protocols through acute intervention. Segmentation reveals how formulation choices and administration settings determine competitive positioning and reimbursement pathways.
Treatment Type:
Growth factors operate as embedded biologics requiring infusion coordination, while barrier and antimicrobial formats function as standalone patient-administered products.
- Growth Factors:Recombinant keratinocyte growth factor formulations manufactured via mammalian cell culture. Severe-grade mucositis in United States academic medical centers drives demand, constrained by cold-chain distribution requirements and biological manufacturing complexity.
- Mouth Rinses:Polymer-based barrier solutions and saline-bicarbonate formulations for preventive protocols. Hospital infusion centers in Germany and the United States standardize these across head-and-neck radiation cohorts, capturing high-volume placement through oncology nursing protocols.
- Topical Analgesics:Lidocaine and benzocaine suspensions for pain palliation in active ulceration.
- Antimicrobial Agents:Chlorhexidine and nystatin formulations targeting fungal and bacterial superinfection in neutropenic patients.
Volume placements concentrate in Mouth Rinses; the faster expansion belongs to Growth Factors.
Stage of Disease:
Cost tier stratification separates premium biologics for severe presentation from commodity prevention products, with reimbursement coding diverging sharply across these thresholds.
- Severe:Grade 3-4 ulceration requiring opioid analgesia and nutritional support. FDA orphan drug incentives accelerate development timelines for targeted biologics, with United States Medicare creating distinct reimbursement codes for inpatient management.
- Preventive:Prophylactic protocols initiated before radiation or chemotherapy cycles. EMA pediatric investigation plans now mandate adolescent data for severe-grade biologics, expanding addressable populations through modified dosing.
- Mild:Grade 1 erythema and sensitivity managed with over-the-counter barrier products.
- Moderate:Grade 2 ulceration affecting solid food intake but not requiring hospitalization.
Procurement concentrates in Preventive protocols; Severe-stage therapies command the steepest expansion trajectory.
Formulation:
Patient compliance patterns favor viscosity and residence time in hospital settings, while portability determines home care selection.
- Gel:High-viscosity polymer matrices forming protective coatings over ulcerated mucosa. Moderate-grade cases in United States oncology clinics show strongest compliance metrics, driven by extended residence time and nursing preference for visible application confirmation.
- Spray:Aerosolized delivery systems for posterior oral cavity and oropharyngeal coverage. Home care settings in Germany and the United States are gaining fastest adoption, addressing patient mobility constraints during active treatment cycles.
- Mouthwash:Liquid rinse formats for preventive and mild-stage protocols requiring frequent application.
- Lozenges:Slow-dissolve matrices for salivary stimulation and topical drug release in ambulatory patients.
Hospital purchasing concentrates in Gel formulations; Spray delivery is gaining share fastest in decentralized care models.
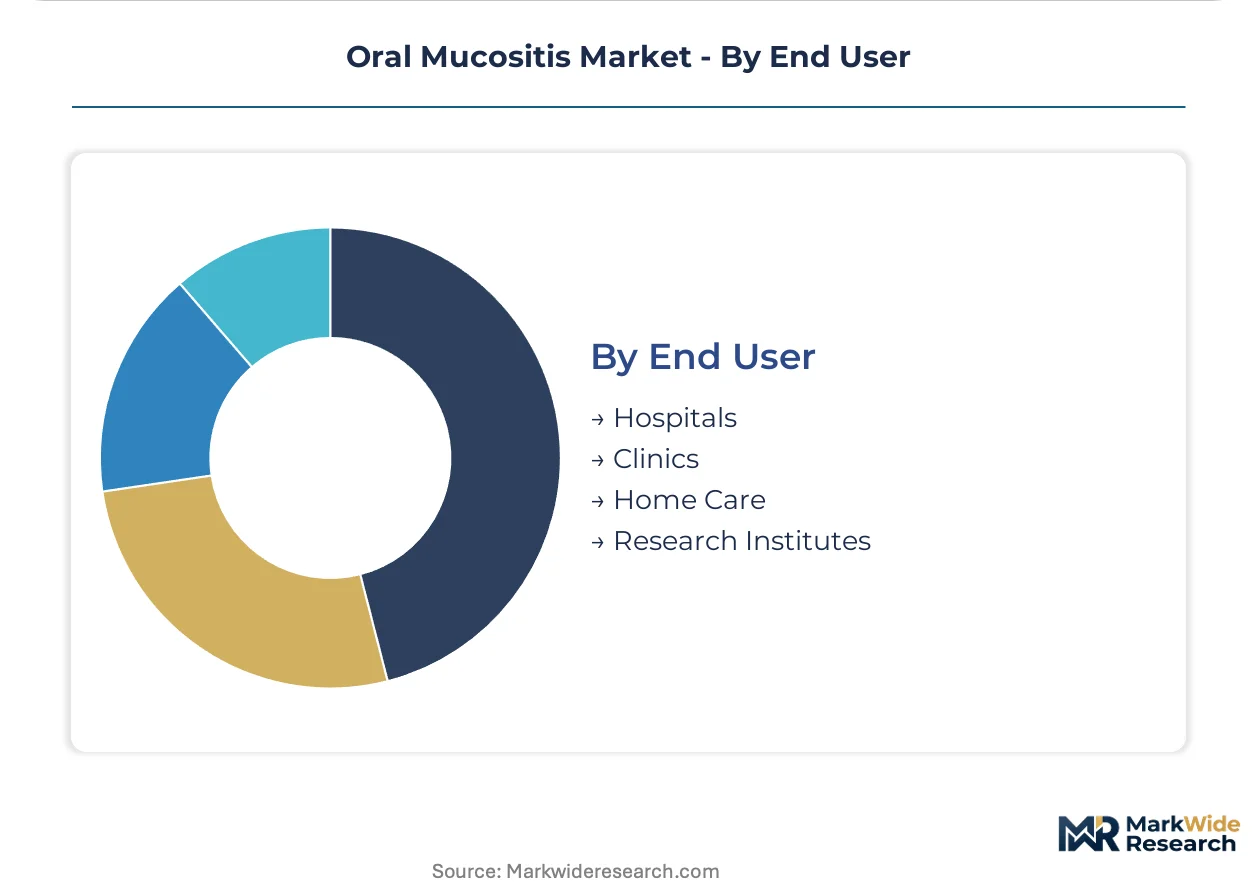
End User:
Customer type determines protocol standardization depth, with institutional purchasers bundling across formulation categories while home care fragments to individual prescription.
- Hospitals:Integrated cancer centers with radiation oncology and medical oncology co-location. United States academic medical centers are consolidating procurement under single-source agreements that bundle barrier gels, antimicrobial rinses, and growth factors, tying reimbursement to mucositis incidence reduction metrics.
- Home Care:Patient-directed administration outside clinical settings. Spray and gel formats are expanding fastest in Germany and the United States, supported by oral telehealth monitoring and direct-to-patient pharmacy distribution.
- Clinics:Community oncology practices without inpatient radiation capacity.
- Research Institutes:Clinical trial sites generating pediatric and adolescent efficacy data for EMA compliance.
Contract value concentrates in Hospitals; Home Care represents the fastest-climbing channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biotech tax zones concentrate growth factor manufacturing, drawing recombinant protein producers to Massachusetts and California corridors. FDA orphan drug credits accelerate development timelines for severe-grade therapies in these designated zones.
United States
Head-and-neck cancer radiation volumes drive prescription rates for prophylactic mouth rinses across academic medical centers. FDA orphan drug incentives compress development timelines for grade 3-4 biologics. Boston and Houston oncology clusters anchor photodynamic therapy pilot programs integrating synthetic hypericin protocols.
Germany
EMA pediatric investigation plans mandate adolescent efficacy data for keratinocyte growth factor trials. EU MDR recertification pressures device-format manufacturers to consolidate quality systems. Munich and Heidelberg cancer networks establish dedicated adolescent mucositis assessment units for streamlined compliance.
Japan
PMDA accelerated review pathways for severe-grade biologics align with METI innovation incentives for regenerative medicine. Aging demographics expand radiation oncology caseloads requiring mucosal protection protocols. Osaka and Tokyo medical districts concentrate photobiomodulation research for head-and-neck cancer patients.
United Kingdom
NHS England value-based contracts tie reimbursement to mucositis incidence reduction metrics in integrated cancer centers. MHRA post-Brexit regulatory autonomy enables faster biologic approval timelines for severe-stage therapies. London and Manchester hospital purchasing coalitions consolidate oral care procurement under single-source agreements.
Switzerland
Swissmedic streamlined pathways for orphan biologics attract European headquarters for severe-grade therapy developers. Precision oncology infrastructure supports biomarker-driven patient stratification for growth factor interventions. Basel and Zurich biotech corridors concentrate barrier formulation R&D for moderate-grade cases.
Oral Mucositis Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with biological producers commanding premium positioning and device-format suppliers competing on volume placement. The structure concentrates around three archetypes: large-cap biologics manufacturers with recombinant protein platforms, mid-cap synthetic formulation specialists, and regional device distributors with hospital contracting relationships. Consolidation pressures favor portfolio bundling across growth factors, barrier gels, and antimicrobial rinses. Technology licensing agreements proliferate as synthetic hypericin developers seek photodynamic platform integration.
Within the biologics tier, Amgen Inc. and Pfizer Inc. exemplify scale-driven manufacturing archetypes with recombinant protein capabilities. Soligenix Inc. occupies a position among synthetic formulation specialists developing photodynamic interventions. These three represent divergent strategic paths: mammalian cell culture scale, small-molecule synthetic platforms, and light-activated therapeutic modalities.
| Leading Market Players |
|---|
| Amgen Inc. |
| Galera Therapeutics Inc. |
| Soligenix Inc. |
| Helsinn Healthcare SA |
| Innovation Pharmaceuticals Inc. |
| Pfizer Inc. |
| Bausch Health Companies Inc. |
| Merck & Co. |
| EpicentRx Inc. |
| Others |
Value Chain & Pricing Dynamics
Recombinant protein manufacturing expertise concentrates in Massachusetts and California biotech corridors, where specialized cell-culture technicians command wage premiums that widen spreads between originator biologics and biosimilar alternatives. These labor-cost differentials cascade through cold-chain distribution requirements, amplifying price stratification across growth factor, barrier gel, and antimicrobial rinse tiers.
Pricing Analysis
Short-lead-time premiums attach to growth factor formulations requiring just-in-time cold-chain coordination with chemotherapy infusion schedules, while spot inventory of standard mouth rinses trades at contracted discounts. Three-tier pricing structure across premium biologics, standard barrier products, and economy antimicrobial rinses reflects FDA orphan drug exclusivity periods and manufacturing complexity differentials. Pricing pressure stems from EU MDR recertification costs compressing margins on device-format portfolios. Hospital purchasing coalitions exhibit lowest price sensitivity given bundled contract structures, whereas home care channels demonstrate acute responsiveness to out-of-pocket cost exposure.
Supply Chain Analysis
Workforce availability for mammalian cell culture operations concentrates in United States biotech corridors, Switzerland precision manufacturing zones, and Japanese regenerative medicine clusters. Raw material dependencies span recombinant DNA vectors, pharmaceutical-grade polymers for barrier matrices, and synthetic hypericin precursors for photodynamic platforms. Single-source vulnerability characterizes specialized growth factor production facilities with extended GMP validation timelines. Distribution runs through hospital purchasing coalitions and oncology GPO networks that consolidate procurement across formulation categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug designation requirements erect substantial compliance cost barriers that protect incumbent positions while constraining capital-efficient entry paths. This regulatory moat rewards players with established biologics manufacturing infrastructure and pediatric investigation plan execution capabilities.
For Market Incumbents: Lock in hospital purchasing coalition relationships through bundled contracts spanning growth factors, barrier gels, and antimicrobial rinses. Extend manufacturing capacity in United States biotech corridors to capture orphan drug tax credit incentives. Counter photodynamic platform substitution threats by integrating synthetic hypericin licensing into existing portfolio architectures.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in home care spray delivery creates white-space opportunity for aerosolized formulations with simplified cold-chain requirements. Target decentralized oncology settings in Germany and United States metropolitan areas where patient mobility constraints drive compliance gaps. Pursue direct-to-patient pharmacy distribution partnerships to bypass hospital purchasing coalition concentration.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap synthetic formulation specialists given EMA pediatric investigation plan mandates expanding addressable populations. Long-term viability hinges on regulatory compliance infrastructure rather than single-product positioning. Monitor reimbursement coding consolidation for prophylactic versus therapeutic administration as inflection signal for portfolio valuation trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Execution | EMA-mandated adolescent oncology protocols extend exclusivity periods for compliant sponsors. |
| Photodynamic Platform Licensing | Synthetic hypericin integration with chemotherapy cycles creates protocol differentiation. |
| Hospital System Partnership | Single-source agreements bundle growth factors, gels, and rinses under value-based contracts. |
| Cold-Chain Distribution Expansion | Specialized logistics capabilities capture premium positioning for biologic formulations. |
| Reimbursement Strategy Development | Medicare coding alignment for prophylactic administration reduces prior authorization friction. |
Study Parameters
Independent corroboration across oncology clinic directors, hospital procurement managers, regulatory affairs specialists, and formulary access leads underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA orphan drug designations, EMA pediatric investigation plans, ClinicalTrials.gov mucositis protocols, and hospital GPO contract databases. Bottom-up prescription volume modeling and top-down market sizing triangulate across treatment type, disease stage, formulation, and end-user segments.
Rate-of-change decomposition separates volume expansion in head-and-neck cancer radiation cohorts from value-per-patient escalation in severe-grade biologic adoption across the analysis window. Segmentation dimensions span treatment type, disease severity, formulation viscosity, and administration setting. CAGRs derive from patient flow modeling through chemotherapy cycles and radiation oncology protocols. Forecast inputs incorporate intensity-modulated radiation therapy adoption curves and orphan drug incentive utilization rates.
Underlying measurement precision varies by segment; growth factor biologics carry tighter precision than device-format portfolios given structured regulatory pathways. Forecasts reflect assumptions around reimbursement coding stability and EU MDR recertification timelines. Material deviation in FDA orphan drug policy or pediatric investigation plan enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Thrush Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Dry Mouth Relief Market
Oral Care
Canker Sores Treatment Market
Oral Care
Oral Irrigator Market
Oral Care
Baby Teeth Care Products Market
Oral Care
LED Oral Care Kits Market
Oral Care
Mouthwash Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Herbal Toothcare Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Oral Thin Films Market