
 North America Oral Care Market | 2026-2036
North America Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oral Care Market Analytics
Modular bundling of toothpaste with whitening strips and specialty mouthwash is broadening consumer choice architecture in retail aisles. Procter & Gamble Company leverages its manufacturing scale to dominate bundled oral care sets across mass-market channels. Colgate-Palmolive Company sustains brand loyalty through specialized toothpaste formulations targeting sensitivity and gum health. Church & Dwight Co. Inc. competes aggressively in the whitening segment with peroxide-based systems that anchor its premium positioning.
Oral care encompasses products and devices designed to maintain dental hygiene, prevent caries, and treat periodontal conditions, with formulations typically containing fluoride concentrations between 1,000 and 1,500 ppm for anticavity efficacy and abrasives such as hydrated silica or calcium carbonate for mechanical cleaning. The category serves consumer health maintenance, professional dental adjunct therapy, and cosmetic enhancement purposes across household and clinical settings. Toothpaste occupies the largest revenue pool as a mature daily-use staple with stable replenishment cycles, while whitening products capture disproportionate margin contribution despite smaller volume bases. Online distribution channels represent the fastest-growing access point, though supermarkets retain dominant foot traffic for impulse and replenishment purchases.
The FDA regulates anticavity and antigingivitis claims through its OTC monograph system, while Health Canada and PMRA enforce parallel standards for product safety and label claims north of the border. EPA guidelines on peroxide concentrations constrain whitening product potency, indirectly steering R&D toward enzymatic and LED-activated alternatives. Stakeholders must monitor how state-level environmental packaging mandates in California and New York reshape material specifications and compliance costs.
Market Dynamics
The FDA's OTC monograph system is compressing formulation timelines for anticavity and antigingivitis claims, while California's packaging mandates force material transitions that ripple through North American supply chains. These dual regulatory pressures are restructuring how manufacturers balance efficacy, compliance, and cost.
Growth Catalysts
- Professional-grade home solutions:Dental patients seeking clinical-equivalent whitening and periodontal maintenance are expanding the premium segment beyond traditional retail boundaries.
- EPA peroxide guidelines:Concentration caps on whitening agents are accelerating R&D investment into enzymatic and LED-activated alternatives with comparable efficacy profiles.
- California urban corridors:Premium oral care penetration in Los Angeles and San Francisco metro areas exceeds national benchmarks, creating template markets for tiered product rollouts.
Market Restraints
- Fluoride sourcing concentration:Hydrated silica and calcium carbonate supply chains concentrate among limited North American chemical processors, exposing margins to input volatility.
- Health Canada/PMRA parallel compliance:Dual-track regulatory filing requirements for US-Canada bundled launches extend time-to-market by 8-14 months for reformulated products.
- Substitution threat from natural alternatives:Charcoal and baking soda formulations without fluoride are capturing shelf space in mass channels despite inferior caries prevention data.
Strategic Opportunities
- Mexico underpenetration:Professional dental adjunct therapy products remain underdistributed in Mexican urban centers relative to US and Canadian coverage density.
- Online subscription bundling:Direct-to-consumer platforms enable modular toothpaste-whitening-mouthwash combinations with replenishment automation that supermarkets cannot replicate.
- New York state packaging mandates:Pending extended producer responsibility legislation creates first-mover advantage for manufacturers with recyclable mono-material tube capabilities.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in fluoride stability and abrasive rheology is concentrating among aging cohorts with limited pipeline replacement.
- OTC monograph reform delays:FDA's pending updates to anticavity standards are freezing label claim investments as manufacturers await final concentration thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oral Care Market |
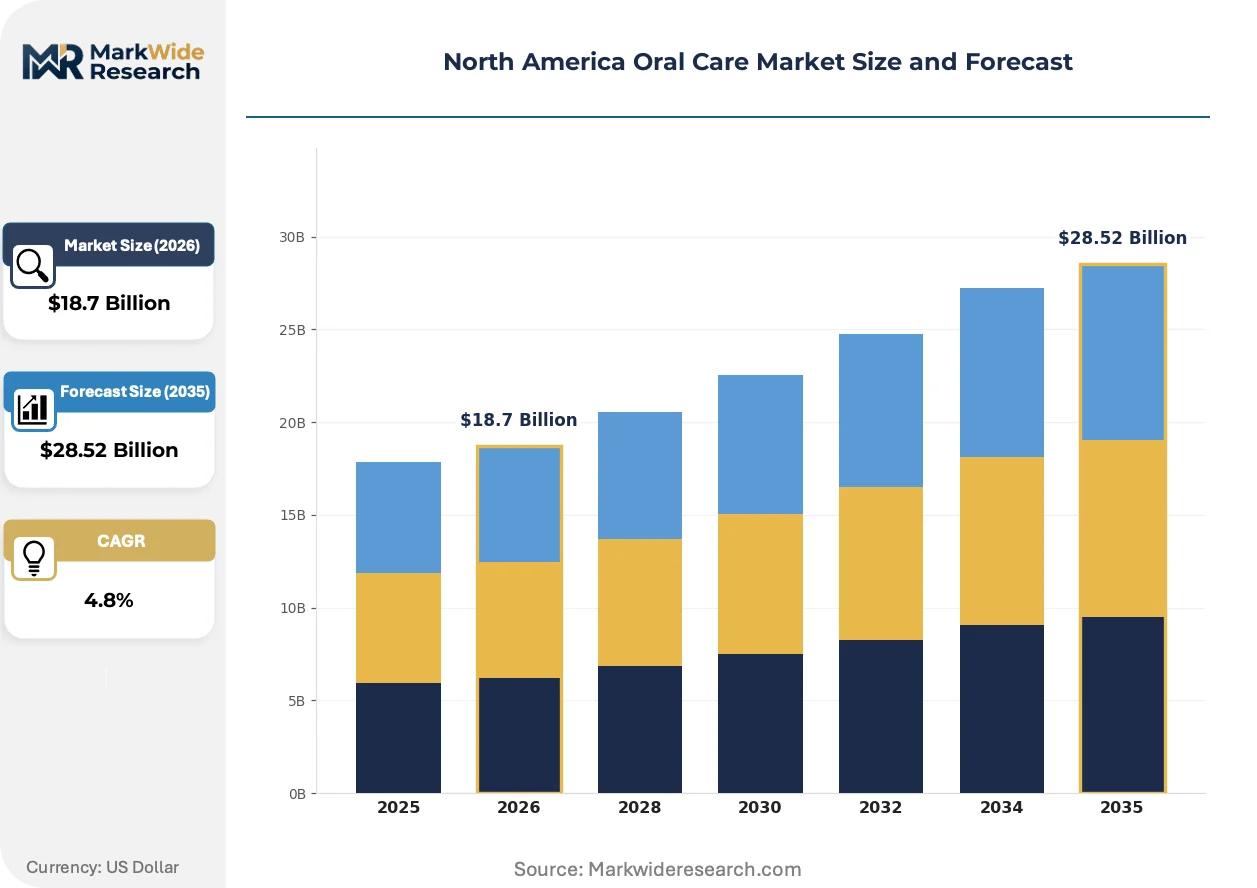
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Products End User: Adults, Children, Seniors, Dental Patients Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores Price Tier: Premium, Mid-range, Economy, Budget |
| Companies Covered | Church & Dwight Co. Inc., Johnson & Johnson Services Inc., Colgate-Palmolive Company, Koninklijke Philips N.V., GSK PLC, Procter & Gamble Company, Haleon PLC, Henkel AG & Co. KGaA, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oral Care Market Evolving Landscape
Digital connectivity and biomaterial science are converging to transform oral care from reactive hygiene into predictive health maintenance, with implications for device-design, data architecture, and channel economics across North America.
Smart toothbrush platforms integrating pressure sensors and AI-driven brushing feedback are unifying hardware, software, and consumable replenishment into single-ecosystem relationships. Dental practices are prescribing these systems to periodontal patients at accelerating rates. This convergence is compressing standalone device margins while expanding recurring revenue pools for integrated solution providers.
California's extended producer responsibility framework for plastic packaging is mandating post-consumer recycled content minimums that exceed EPA baseline guidelines. Manufacturers are reformulating tube laminates and cap assemblies to meet these specifications ahead of 2027 enforcement windows. The whitening segment faces disproportionate compliance costs given multi-layer barrier requirements for peroxide stability.
Subscription-based replenishment is displacing impulse-driven supermarket purchasing among millennial and Gen Z households. Direct-to-consumer platforms capture preference data that enables personalized formulation matching, while traditional retail loses foot traffic for core toothpaste restocking. This behavioral shift concentrates in Canadian metropolitan markets where e-commerce penetration in personal care exceeds US averages.
North America Oral Care Market Segmentation
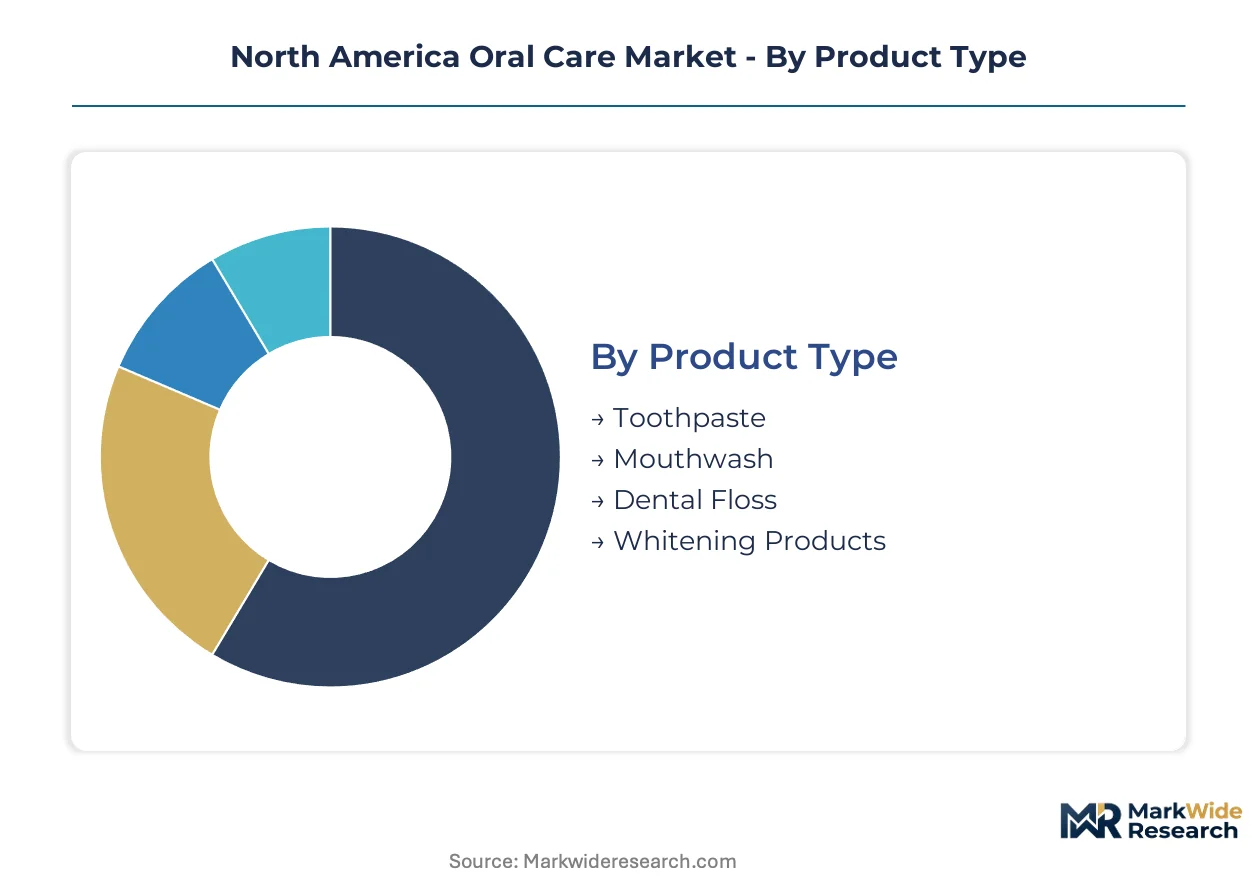
Segmentation in oral care reveals how formulation chemistry, patient demographics, and channel economics fragment what appears as a homogeneous daily-use category. Supply-side specialization in fluoride stability and peroxide delivery systems creates divergent margin profiles across product tiers.
Product Type:
Manufacturing assets for abrasive rheology and active ingredient stabilization concentrate among North American chemical processors serving multiple product formats.
- Toothpaste:Formulations containing 1,000-1,500 ppm fluoride as sodium monofluorophosphate or stannous fluoride dominate household replenishment cycles. California urban corridors absorb disproportionate volumes of sensitivity and gum-health variants as dental practices prescribe adjunct therapy regimens.
- Whitening Products:Peroxide-based systems and emerging enzymatic alternatives command premium shelf positioning despite EPA concentration caps that constrain maximum potency. LED-activated devices are gaining traction in Canadian metropolitan markets where e-commerce penetration exceeds US benchmarks.
- Mouthwash:Antiseptic and cosmetic variants serve distinct use cases with alcohol-free formulations capturing preference shifts in professional dental settings.
- Dental Floss:Waxed, unwaxed, and tape formats maintain stable demand profiles with limited formulation innovation compared to adjacent categories.
Toothpaste absorbs the bulk of installed capacity; whitening products are expanding most quickly.
End User:
Patient segmentation tracks dental disease prevalence, insurance coverage patterns, and professional recommendation intensity across age cohorts.
- Adults:Working-age consumers drive volume through daily-use replenishment with escalating interest in cosmetic enhancement and periodontal maintenance.
- Dental Patients:Individuals under active clinical management represent the fastest-expanding buyer segment as practices prescribe professional-grade home solutions for whitening and gum disease management.
- Children:Pediatric formulations with controlled fluoride dosing and flavor profiles serve caries prevention protocols established by dental professionals.
- Seniors:Dry mouth and recession-sensitive product demand concentrates where aging demographics intersect with Medicare Advantage dental coverage expansion.
Adult households generate the majority of baseline revenue; dental patients climb the fastest as clinical-adjacent positioning reshapes premium tier development.
Distribution Channel:
Channel economics fragment between impulse-driven physical retail and data-rich subscription platforms with divergent replenishment automation capabilities.
- Supermarkets:Dominant foot traffic for unplanned purchases and emergency replenishment maintains volume throughput despite declining trip frequency.
- Online:Direct-to-consumer platforms enable modular bundling of toothpaste, whitening strips, and specialty mouthwash with automated replenishment cycles that physical channels cannot replicate.
- Pharmacies:Professional recommendation proximity positions these outlets for sensitivity and therapeutic variant distribution.
- Specialty Stores:Premium and natural-positioned products capture shelf space where consumer willingness to pay for differentiated formulations peaks.
Supermarkets retain the largest share of transaction volume; online channels gain share fastest as millennial and Gen Z households displace impulse purchasing with planned subscription behavior.
Price Tier:
Raw material grade and clinical validation intensity stratify manufacturing cost structures across four distinct positioning levels.
- Premium:Peroxide-based whitening systems and dentist-dispensed formulations carry clinical-equivalent positioning with concentrated active ingredients and specialized delivery mechanisms.
- Mid-range:Differentiated variants for sensitivity, enamel repair, and gum health occupy the competitive center with trade promotion dependence.
- Economy:Basic anticavity formulations with standard fluoride concentrations serve price-sensitive households through high-volume retail placement.
- Budget:Private-label and deep-discount offerings compete on shelf price with minimal marketing investment and commodity ingredient sourcing.
Mid-range SKUs absorb the majority of production planning attention; premium tier development accelerates fastest as professional-grade home solutions expand addressable market boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing assets for fluoride stabilization and peroxide delivery systems concentrate in the United States, while consumption patterns fragment across income tiers and urban density gradients throughout the three-country trade bloc.
United States
Dental practices in Los Angeles and San Francisco metro areas prescribe professional-grade home whitening systems at rates exceeding national benchmarks. The FDA's OTC monograph system governs anticavity and antigingivitis claims, compressing formulation timelines for compliant products. New Jersey and Ohio host specialized chemical processors supplying hydrated silica and calcium carbonate to toothpaste manufacturers across the eastern seaboard.
Canada
Millennial households in Toronto and Vancouver drive e-commerce penetration for oral care subscriptions above US averages. Health Canada and PMRA enforce parallel compliance requirements that extend time-to-market for reformulated products by 8-14 months. Montreal's packaging converters are retooling for post-consumer recycled content mandates ahead of 2027 enforcement windows.
Mexico
Mexico City and Monterrey absorb rising volumes of mid-range sensitivity and gum-health variants as dental insurance coverage expands. COFEPRIS, the national health regulator, maintains distinct filing pathways for therapeutic versus cosmetic oral care claims. Guadalajara's retail distribution networks remain underpenetrated for professional dental adjunct therapy products relative to US coverage density.
California
Premium oral care penetration in the state's urban corridors outpaces national norms, creating template markets for tiered product rollouts. The state's extended producer responsibility framework mandates post-consumer recycled content minimums exceeding EPA baseline guidelines. Silicon Valley hardware startups are integrating pressure sensors and AI-driven feedback into smart toothbrush platforms prescribed by periodontal practices.
New York Metro
Pending extended producer responsibility legislation in New York state creates first-mover advantage for manufacturers with recyclable mono-material tube capabilities. The metropolitan area's pharmacy density positions these outlets for sensitivity and therapeutic variant distribution. Brooklyn and Queens manufacturing cooperatives are piloting enzymatic whitening alternatives to navigate EPA peroxide concentration caps.
North America Oral Care Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North America Oral Care Market, creating a tiered structure where scale advantages clash with formulation agility. Three archetypes dominate: multinational consumer goods conglomerates with manufacturing scale, dental-care pure-plays with clinical credibility, and technology-integrated device manufacturers with recurring revenue ecosystems. Competitive moves concentrate on portfolio diversification into professional-grade home solutions and strategic partnerships with dental practices for prescription-channel placement.
Among diversified conglomerates, Procter & Gamble Company and Colgate-Palmolive Company exemplify scale-driven archetypes with mass-market channel dominance, while Church & Dwight Co. Inc. occupies a specialized position in peroxide-based whitening systems. These three entities represent contrasting strategic postures: the first two leverage manufacturing scale and bundled oral care sets, while the third competes aggressively in premium positioning through concentrated active ingredient formulations.
| Leading Market Players |
|---|
| Church & Dwight Co. Inc. |
| Johnson & Johnson Services Inc. |
| Colgate-Palmolive Company |
| Koninklijke Philips N.V. |
| GSK PLC |
| Procter & Gamble Company |
| Haleon PLC |
| Henkel AG & Co. KGaA |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
Calcium carbonate and hydrated silica price indices cascade through North American oral care manufacturing into three distinct pricing tiers, with California's extended producer responsibility mandates layering compliance premiums atop base material costs for tube and cap assemblies.
Pricing Analysis
Margin tightening in economy-tier toothpaste reflects private-label expansion at mass retailers and deep-discount channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by fluoride concentration, clinical validation intensity, and delivery mechanism sophistication. Pricing pressure stems from charcoal and baking soda natural alternatives capturing shelf space despite inferior caries prevention. Dental patients seeking professional-grade home solutions exhibit lowest price sensitivity; budget-tier households in rural distribution zones show highest elasticity.
Supply Chain Analysis
Fluoride stabilization chemistry rests on specialized North American chemical processors concentrated in New Jersey and Ohio. Hydrated silica, calcium carbonate, and sodium monofluorophosphate constitute critical input dependencies. Single-source vulnerability concentrates in peroxide supply for whitening formulations facing EPA concentration caps. Distribution runs through supermarket replenishment networks for impulse purchases, with direct-to-consumer platforms capturing subscription-automated volume in Canadian metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Oral Care Market functions as a cost-of-compliance story where FDA's OTC monograph system erects formulation barriers that freeze out subscale competitors lacking regulatory affairs infrastructure.
For Market Incumbents: To counter enzymatic whitening alternatives and LED-activated device entrants, accelerate backward integration into post-consumer recycled tube manufacturing ahead of California and New York packaging mandates. Deepen channel control through dental practice prescription partnerships that lock in periodontal patient replenishment cycles. For New Entrants and Emerging Players: Mexican urban centers outside Mexico City and Monterrey represent an underserved buyer archetype with expanding dental insurance coverage and limited professional dental adjunct therapy distribution. Capture this white-space through pharmacy-centric go-to-market positioning for sensitivity and gum-health variants. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized chemical processors with fluoride stability expertise in the US Northeast and Great Lakes regions. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch FDA OTC monograph reform timing as the critical inflection signal for label claim investment resumption.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Captures millennial and Gen Z replenishment automation that supermarkets cannot replicate in Canadian metros. |
| Post-Consumer Recycled Tube Manufacturing Scale-Up | Addresses California's extended producer responsibility mandates exceeding EPA baseline guidelines. |
| Dental Practice Prescription Partnership | Locks in professional-grade home solution distribution for whitening and periodontal maintenance segments. |
| Enzymatic Whitening R&D Investment | Navigates EPA peroxide concentration caps while maintaining efficacy profiles for premium positioning. |
| Mexico Distribution Network Expansion | Penetrates underdistributed urban centers as COFEPRIS therapeutic claim pathways mature. |
Research Methodology
Independent corroboration across formulation chemists at North American chemical processors, dental practice procurement managers, and retail category buyers underwrites the qualitative findings. Primary interviews with supply planners at mass-market retailers, regulatory affairs leads at OTC manufacturers, and GPO contracts managers at dental service organizations combined with secondary validation from FDA OTC monograph filings, Health Canada PMRA submissions, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation anchored the market sizing.
Historical reference periods spanning pre-pandemic baseline through recent normalization established trajectory anchors across the projection horizon. Segmentation dimensions modeled include product type, end user demographic, distribution channel, and price tier stratification. CAGRs derived from regression analysis of volume and value trends, with forecast inputs incorporating EPA peroxide guideline evolution and state-level packaging mandate enforcement calendars.
Revisions become necessary when FDA OTC monograph reform finalizes concentration thresholds, California EPR enforcement windows accelerate, or fluoride raw material supply disruptions materialize. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Herbal Toothcare Market
Oral Care
LED Oral Care Kits Market
Oral Care
BRICS Oral Care Market
Oral Care
Canker Sores Treatment Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Mouthwash Market
Oral Care
Oral Hygiene Products Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Oral Irrigator Market
Oral Care
Herbal Toothpaste Market
Oral Care
Oral Thrush Market
Oral Care
Global Oral Care Products Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Tongue Cleaner Market
Oral Care
Global Toothbrush and Toothpaste Market