
 Europe Oral Care Market | 2026-2036
Europe Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oral Care Market Analysis
Asset-light contract manufacturing and third-party formulation partnerships are reshaping competitive entry in European oral care. GlaxoSmithKline plc leverages its pharmaceutical heritage to sustain clinical credibility in therapeutic toothpaste formulations. Colgate-Palmolive Company anchors shelf presence across European supermarkets through decades of brand investment. Unilever competes via sustainability-led positioning that differentiates its oral care portfolio in environmentally conscious markets.
Oral care encompasses products and devices designed to maintain dental hygiene, prevent oral diseases, and treat conditions affecting teeth, gums, and mucosal tissues, with formulations typically containing fluoride concentrations between 1000-1500 ppm for caries prevention and antimicrobial agents such as chlorhexidine or cetylpyridinium chloride for plaque control. These products serve consumer self-care routines, professional dental prophylaxis, and post-surgical maintenance across institutional and retail channels. Toothpaste occupies the largest value share within product type segmentation, though mouthwash demonstrates faster growth as consumers integrate multi-step regimens. Pharmacy distribution channels capture premium price tiers, while online retail expands fastest among distribution channels as subscription models reduce customer acquisition costs for repeat-purchase categories.
The EU Medical Device Regulation (MDR) and REACH framework administered by ECHA govern oral care device classification and chemical ingredient safety across member states, with CE marking requirements determining market access timelines for powered toothbrushes and interdental cleaners. The F-Gas Regulation constrains propellant choices for aerosolized oral sprays, pushing reformulation toward mechanical pump systems. Stakeholders must monitor evolving MDR guidance documents and national dental association reimbursement lists to anticipate which product categories will face accelerated compliance costs or expanded professional channel opportunities.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing market access timelines for powered oral care devices while simultaneously elevating compliance costs across the value chain. This regulatory tightening coincides with rising patient volumes at European dental clinics, which are expanding procurement of professional-grade formulations and instruments.
Growth Catalysts
- MDR compliance acceleration:The EU Medical Device Regulation is mandating stricter clinical documentation for interdental cleaners and powered toothbrushes, creating competitive moats for established manufacturers with regulatory infrastructure already in place.
- German dental reimbursement expansion:Preventive oral care coverage under statutory health insurance frameworks supports higher per-capita spending on therapeutic toothpastes and prophylaxis products.
- Fluoride concentration optimization:Formulation advances enabling 1450 ppm fluoride delivery without stability degradation are improving caries prevention efficacy in mass-market segments.
Market Restraints
- REACH chemical registration costs:ECHA's extended registration deadlines for antimicrobial agents like chlorhexidine are elevating formulation compliance expenditures for mid-tier suppliers.
- F-Gas propellant constraints:The EU F-Gas Regulation is eliminating hydrofluorocarbon options for aerosolized breath sprays, forcing mechanical pump system redesigns with extended validation cycles.
- Professional channel concentration:Dental clinic procurement in France, Germany, and Italy aggregates through three major group purchasing organizations, compressing margin structures for device manufacturers.
Strategic Opportunities
- Poland and Romania pharmacy channel expansion:Underpenetrated Eastern European markets present whitespace for premium fluoride formulations distributed through pharmacy networks with trained consultation staff.
- Subscription oral care models:Direct-to-consumer replenishment platforms for interdental brushes and therapeutic mouthwash are reducing customer acquisition costs in Nordic markets with high digital payment penetration.
- CE marking mutual recognition:MDR compliance documentation is transferable across EU member states, enabling accelerated multi-country launches for Swiss and UK manufacturers seeking continental market access.
Industry Challenges
- Biocompatibility testing bottlenecks:Notified body capacity constraints for ISO 10993 biological evaluation are extending powered toothbrush certification timelines by eight to fourteen months.
- Legacy ERP integration with EUDAMED:Dental device manufacturers face system reconfiguration costs to automate unique device identifier submissions to the EU's medical device database.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oral Care Market |
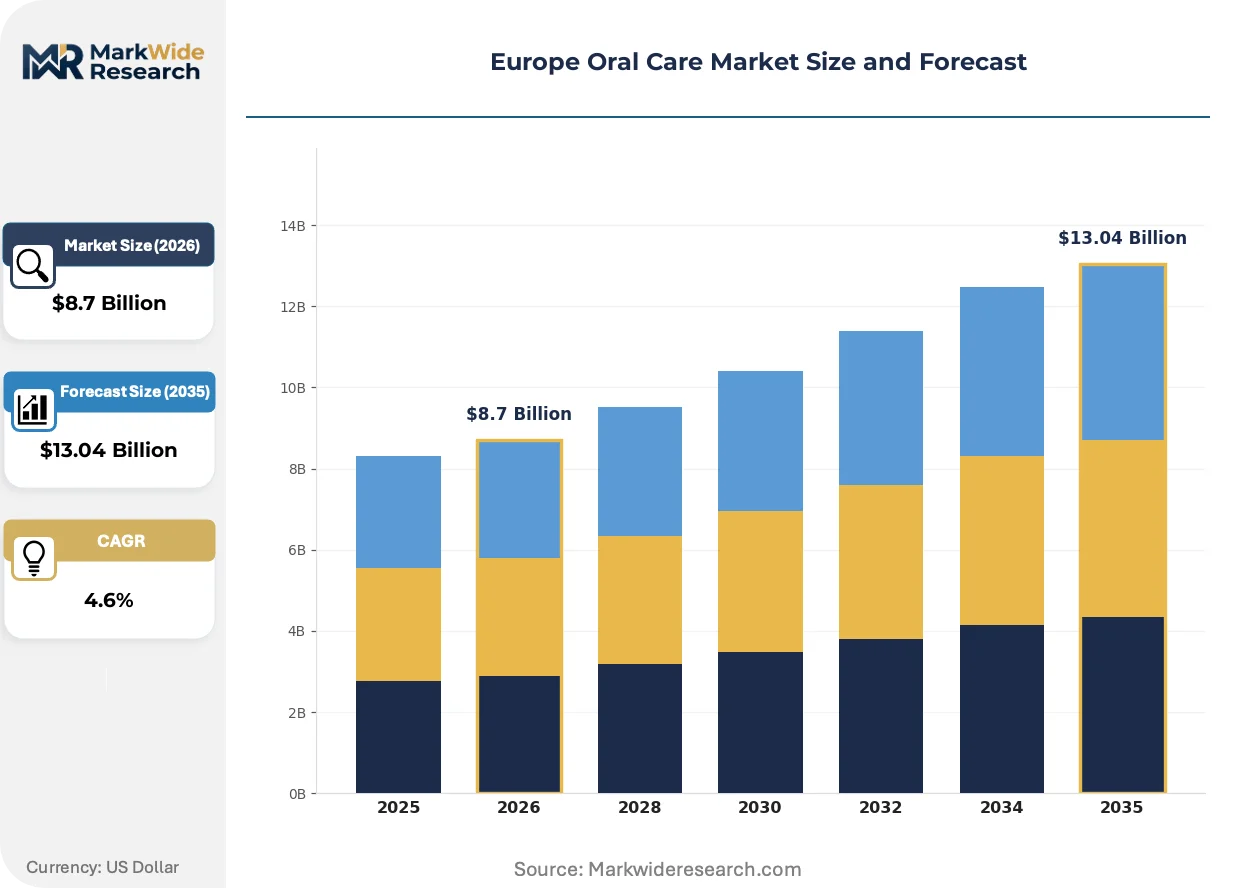
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Toothbrushes, Dental Floss End User: Adults, Children, Seniors, Dentists Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | GlaxoSmithKline plc, Sunstar Suisse S.A., Colgate-Palmolive Company, Church & Dwight Co. Inc., Henkel AG & Co. KGaA, Procter & Gamble, Johnson & Johnson Consumer Inc, Straumann Group, Unilever, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oral Care Market Emerging Trajectories
Formulation chemistry and connected device architectures are converging to reshape competitive positioning across European oral care. These developments are compressing traditional product lifecycles while opening new premium tiers anchored to measurable efficacy claims.
Sonic pressure-mapping sensors embedded in brush handles are rendering obsolete unpowered manual toothbrushes in German and Dutch professional recommendation channels. Dental hygienists in Amsterdam and Munich clinics now prioritize real-time feedback devices for patient home-care compliance. The technology is rendering obsolete single-function mechanical brushes by bundling plaque detection with brushing technique coaching.
REACH authorization requirements for cetylpyridinium chloride are forcing antimicrobial mouthwash reformulations across EU manufacturing facilities. ECHA's 2024 substance evaluation timeline is compressing R&D pipelines for plaque-control formulations. French and Spanish manufacturers are accelerating natural extract alternatives to maintain antimicrobial claims without pending authorization uncertainties.
Pharmacy-led consultation models for therapeutic toothpaste selection are displacing unassisted supermarket purchases in Belgium and Austria. Trained pharmacists in Brussels and Vienna now guide fluoride concentration choices based on individual caries risk profiles. This channel evolution is most visible in markets with reimbursement codes linking professional recommendation to product subsidy eligibility.
Europe Oral Care Market Segmentation
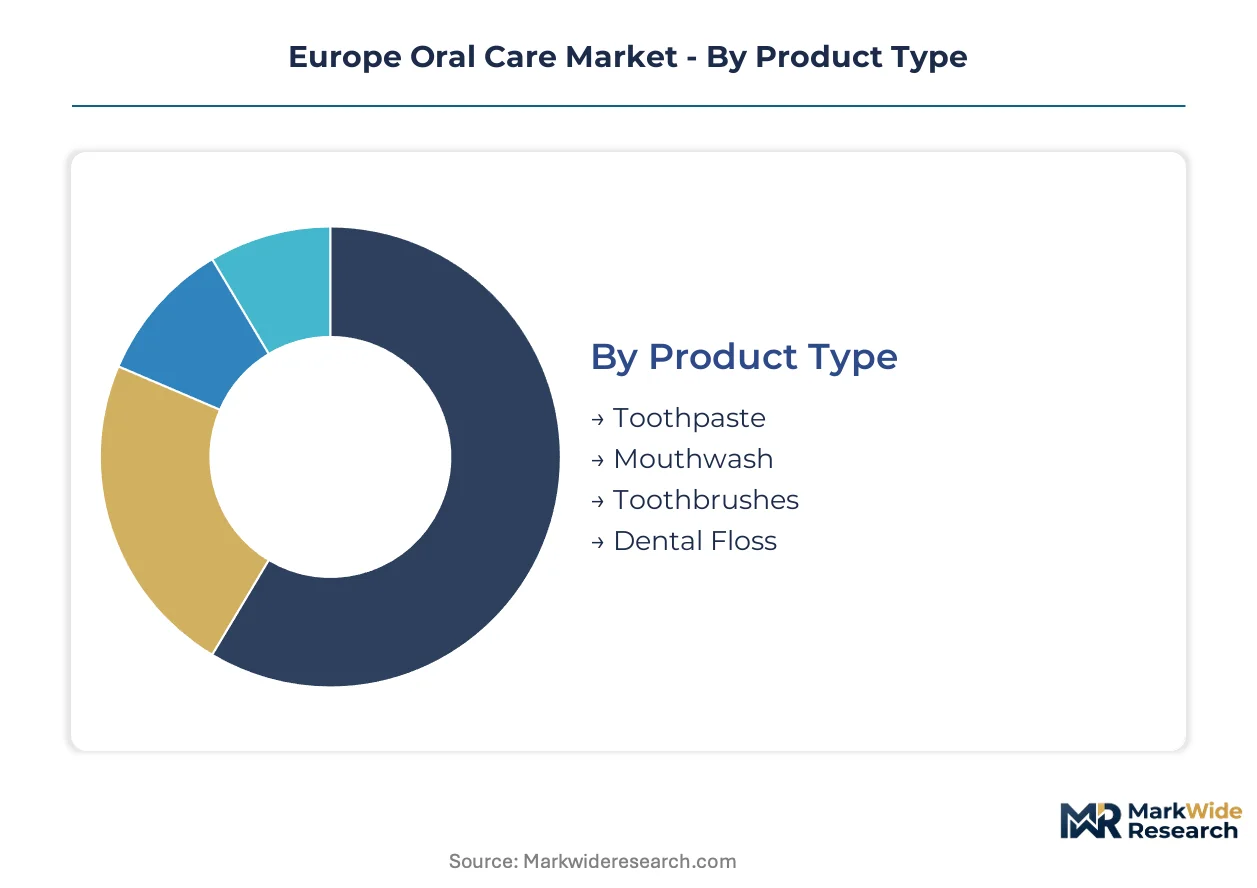
European oral care segmentation reveals distinct demand profiles across product formulations, professional versus consumer channels, and reimbursement-linked price tiers. Manufacturers must align portfolio depth with Germany's therapeutic reimbursement codes, France's pharmacy consultation models, and the Nordic direct-to-consumer acceleration.
Product Type:
Formulations span preventive maintenance, therapeutic intervention, and mechanical cleaning functions with varying fluoride concentrations and antimicrobial agent profiles.
- Toothpaste:Formulations delivering 1000-1500 ppm fluoride dominate mass-market caries prevention, with 1450 ppm variants gaining professional endorsement in German statutory insurance reimbursement frameworks. Concentration optimization without stability degradation remains the primary technical battleground.
- Mouthwash:Antimicrobial rinses containing chlorhexidine or cetylpyridinium chloride face REACH authorization pressures, forcing reformulation toward natural extracts in French and Spanish manufacturing facilities. Pharmacy consultation channels in Belgium and Austria now drive therapeutic selection.
- Toothbrushes:Powered variants with sonic pressure-mapping sensors are displacing manual alternatives in Dutch and German professional recommendation channels.
- Dental Floss:Interdental cleaners face tightened MDR clinical documentation requirements, elevating compliance moats for established CE-marked manufacturers.
The dominant share belongs to Toothpaste, while Mouthwash is closing the gap fastest.
End User:
Customer archetypes range from self-directed consumers to clinically supervised patients with varying risk profiles and reimbursement access.
- Adults:The core volume base purchasing across supermarket and online channels, with German adults accessing therapeutic formulations through statutory insurance subsidies.
- Children:Pediatric formulations with adjusted fluoride concentrations and flavor profiles concentrate in pharmacy and parent subscription channels.
- Seniors:Dry mouth and periodontal maintenance needs drive pharmacy-led consultation in Vienna and Brussels, where reimbursement codes link professional recommendation to product subsidy.
- Dentists:Professional procurement through French, German, and Italian group purchasing organizations aggregates demand for clinical-grade prophylaxis products and powered devices.
Adults command the volume base, yet Dentists are expanding their share fastest through clinic procurement consolidation.
Distribution Channel:
Channel economics diverge sharply between assisted consultation models capturing premium tiers and self-service formats driving volume scale.
- Online Retail:Subscription replenishment platforms for interdental brushes and therapeutic mouthwash reduce customer acquisition costs in Nordic markets with high digital payment penetration.
- Supermarkets:Mass-market toothpaste and manual toothbrush volume concentrates here, with Colgate-Palmolive and Unilever anchoring shelf presence through decades of brand investment.
- Pharmacies:Trained consultation staff in Poland and Romania present whitespace for premium fluoride formulations, while Belgian and Austrian pharmacists guide therapeutic selection based on individual caries risk.
- Convenience Stores:Emergency and travel-size oral care purchases concentrate in urban transit corridors with limited assortment depth.
Supermarkets retain the volume leadership, though Online Retail is climbing the fastest on subscription model economics.
Price Tier:
Pricing stratification reflects formulation complexity, professional endorsement, and reimbursement eligibility rather than manufacturing cost alone.
- Premium:Therapeutic toothpastes with optimized fluoride delivery and connected powered toothbrushes with real-time feedback sensors command professional channel placement.
- Mid-Range:Standard fluoride formulations and established powered brush brands balance efficacy claims with mass-market accessibility.
- Budget:Basic fluoride toothpaste and manual brushes compete on shelf price in supermarket and convenience channels with thin margin structures.
- Discount:Private-label alternatives and promotional pack sizes concentrate in German and Eastern European hard discounters.
Premium tier captures margin concentration, while Mid-Range is gaining share fastest through efficacy-versus-price positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance framework subsidizes therapeutic toothpaste, creating the region's highest per-capita oral care expenditure. France and Italy channel professional procurement through consolidated group purchasing organizations. Eastern European markets present pharmacy-led expansion opportunities as reimbursement codes extend preventive coverage.
Germany
Therapeutic toothpaste with 1450 ppm fluoride dominates pharmacy shelves as statutory insurers reimburse preventive formulations. The Federal Institute for Drugs and Medical Devices enforces MDR compliance timelines for powered interdental devices. Manufacturing clusters in North Rhine-Westphalia supply clinical-grade prophylaxis products to dental clinic chains across Bavaria and Baden-Württemberg.
France
Pharmacy consultation models displace unassisted supermarket purchases as ANSM tightens antimicrobial mouthwash oversight. ECHA's REACH authorization deadlines for cetylpyridinium chloride force reformulation toward natural extract alternatives. Production facilities in the Île-de-France region export fluoride-optimized formulations to Belgian and Luxembourg markets.
Italy
Dental clinic procurement consolidation drives demand for professional-grade prophylaxis instruments and therapeutic pastes. The Ministry of Health aligns national device registration with EU MDR CE marking requirements. Industrial concentration in Lombardy and Emilia-Romagna supports contract manufacturing for Swiss and German brands seeking Mediterranean market access.
Poland
Underpenetrated pharmacy networks present whitespace for premium fluoride formulations with trained consultation staff. The Office for Registration of Medicinal Products oversees therapeutic toothpaste classification distinct from cosmetic oral care. Warsaw and Kraków distribution hubs channel imported professional products to expanding private dental clinic chains.
Netherlands
Sonic pressure-mapping toothbrushes displace manual alternatives as dental hygienists prioritize real-time feedback devices. The Healthcare and Youth Inspectorate enforces biocompatibility documentation for ISO 10993 evaluation. Amsterdam and Rotterdam clinics anchor professional recommendation networks influencing Belgian and Nordic purchasing patterns.
Europe Oral Care Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent distribution economics. Supermarket shelf dominance by heritage consumer goods conglomerates contrasts with pharmacy-dependent therapeutic specialists navigating reimbursement complexity. Three archetypes define competitive positioning: pharmaceutical-origin formulators leveraging clinical credibility, sustainability-led challengers capturing environmentally conscious segments, and contract-manufacturing enablers lowering entry barriers for private-label entrants. M&A activity concentrates on formulation technology acquisitions, while strategic partnerships with dental clinic chains secure professional channel access.
Among pharmaceutical-origin players, GlaxoSmithKline plc and Johnson & Johnson Consumer Inc exemplify clinical-credibility archetypes rooted in therapeutic development heritage. Colgate-Palmolive Company and Unilever occupy positions as shelf-presence anchors across European mass retail, with the latter representing sustainability-led differentiation. Sunstar Suisse S.A. and Straumann Group sit within professional-channel specialists focused on dental clinic procurement and clinical-grade device supply. Henkel AG & Co. KGaA and Church & Dwight Co. Inc. represent mid-tier diversified challengers balancing consumer and professional segments.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Sunstar Suisse S.A. |
| Colgate-Palmolive Company |
| Church & Dwight Co. Inc. |
| Henkel AG & Co. KGaA |
| Procter & Gamble |
| Johnson & Johnson Consumer Inc |
| Straumann Group |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Eastern European contract manufacturing facilities is compressing margin structures for mid-tier oral care suppliers while simultaneously enabling aggressive pricing postures from established CE-marked device manufacturers seeking volume scale.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with MDR-compliant CE marking and ISO 10993 biocompatibility documentation commanding pharmacy channel placement at substantially higher price points than non-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by fluoride concentration optimization and connected device functionality. Pricing pressure stems from group purchasing organization consolidation in France, Germany, and Italy, where dental clinic procurement aggregates through three major buying consortiums. Budget-tier buyers in Eastern European hard discounters exhibit highest price sensitivity, while German statutory insurance reimbursement frameworks insulate premium therapeutic formulations from direct cost competition.
Supply Chain Analysis
Extended payment terms from major retail pharmacy chains are forcing working capital restructuring among formulation specialists, with supply-chain finance facilities increasingly bridging production-to-collection gaps. Manufacturing concentration centers on Germany, France, and Italy, with North Rhine-Westphalia and Lombardy clusters supplying clinical-grade prophylaxis products across the region. Raw material dependencies draw from sodium fluoride suppliers in Spain, antimicrobial active ingredient producers in Switzerland, and polymer brush head manufacturers in the Netherlands. Single-source vulnerability runs through Swiss specialty chemical providers for stabilized fluoride formulations. Distribution runs through pharmacy networks in Belgium and Austria for therapeutic segments, while supermarket and online channels dominate mass-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected device ecosystems and subscription replenishment platforms are restructuring European oral care toward platform economics, with interoperability between powered brushes and dental practice management software emerging as the decisive ecosystem battleground.
For Market Incumbents: Entrench professional channel control by securing exclusive procurement contracts with expanding dental clinic chains in Poland and Romania, while accelerating MDR compliance documentation to extend certification moats against mid-tier challengers facing notified body bottlenecks. Backward integration into fluoride stabilization chemistry reduces exposure to Swiss specialty supplier concentration. For New Entrants and Emerging Players: Pharmacy networks in Warsaw and Kraków with trained consultation staff represent the most penetrable entry point for premium therapeutic formulations, given underpenetrated reimbursement code expansion and limited incumbent shelf presence. Direct-to-consumer subscription models for interdental brushes in Nordic markets offer a second white-space target, leveraging high digital payment penetration to bypass established retail gatekeepers. Go-to-market execution should anchor on pharmacist education programs linking caries risk assessment to product selection. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because MDR documentation transferability and REACH authorization timelines create durable competitive moats for compliant manufacturers. Acquisition targets should prioritize formulation technology specialists with existing CE-marked device portfolios and established EUDAMED database integration. The signal to watch is notified body capacity expansion announcements, which would compress certification timelines and erode incumbent documentation advantages.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Documentation Investment | CE marking transferability across EU member states accelerates multi-country launches for Swiss and UK manufacturers. |
| Pharmacy Channel Expansion | Trained consultation staff in Belgian and Austrian networks drive therapeutic toothpaste selection based on individual caries risk profiles. |
| Subscription Model Deployment | Direct-to-consumer replenishment platforms reduce customer acquisition costs in Nordic markets with high digital payment penetration. |
| Formulation Technology Acquisition | Fluoride concentration optimization capabilities without stability degradation secure professional endorsement in German reimbursement frameworks. |
| Dental Clinic Chain Partnership | Exclusive procurement contracts with expanding Polish and Romanian private clinic networks secure professional channel volume. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dental clinic procurement managers, pharmacy category buyers, formulation R&D directors, and regulatory affairs specialists; and secondary validation against ECHA REACH substance databases, EU MDR guidance documents, national dental association reimbursement lists, and customs trade records. Bottom-up product-level volume estimates triangulated against top-down market sizing from macro expenditure indicators.
Forecast inputs incorporated product type segmentation by formulation chemistry and device architecture, end-user archetypes spanning self-directed consumers to clinically supervised patients, distribution channel economics, and price tier stratification by reimbursement eligibility. CAGRs derived from trend extrapolation of patient volume growth, regulatory compliance cost trajectories, and channel shift velocities across the projection horizon. Industry-specific inputs included notified body capacity constraints for ISO 10993 evaluation and statutory insurance coverage expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in eurozone inflation trajectories, dental reimbursement policy shifts, or REACH authorization timelines would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and patient volume growth. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Baby Oral Care Market
Oral Care
Kids Toothpaste Market
Oral Care
South America Oral Care Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
China Oral Care Market
Oral Care
Tongue Cleaner Market
Oral Care
Herbal Toothcare Market
Oral Care
Mouthwash Market
Oral Care
Adult Oral Care Products Market
Oral Care
Oral Rinse Market
Oral Care
Oral Hygiene Products Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
GCC Oral Hygiene Market