
 Oral Irrigator Market | 2026-2036
Oral Irrigator Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Irrigator Market Intelligence
Premium specification tiers above 1,200 pulses per minute is bifurcating the Oral Irrigator landscape into clinical-grade and consumer-grade camps. Waterpik leverages its American dental professional channel to sustain institutional loyalty. Philips competes through sonic-pulsation integration that anchors its ecosystem strategy across oral care devices.
An oral irrigator is a pressurized water-flossing device delivering pulsated or continuous aqueous streams at 10–100 psi to dislodge interdental plaque and food debris, primarily serving preventive dentistry and periodontal maintenance. Countertop units with reservoir capacities exceeding 600 milliliters dominate margin pools in North American households, while cordless lithium-ion designs lead growth trajectories in European and Asian travel segments. Online retail channels now capture the fastest-growing share of volume, though pharmacies retain structural importance for first-time buyers seeking clinician validation.
FDA 510(k) clearance requirements govern device marketing claims in the United States, while CE marking under the EU MDR framework imposes clinical evidence standards for European market access. Japan's PMDA oversees electrical safety and efficacy labeling for imported units. Stakeholders must monitor evolving reimbursement codes for preventive periodontal devices and anticipate stricter water-efficiency mandates from environmental regulators.
Market Dynamics
The oral irrigator market is bifurcating along pulse-frequency specifications, with clinical-grade thresholds above 1,200 pulses per minute separating professional reimbursement pathways from consumer retail channels.
Growth Catalysts
- Japan's PMDA electrical safety framework:Clear efficacy labeling standards for imported units reduce market entry friction for compliant manufacturers targeting aging demographic clusters in Tokyo and Osaka prefectures.
- Periodontal maintenance protocols:Dental clinics in Germany are integrating pressurized water-flossing into standard preventive care workflows, expanding institutional procurement volumes for reservoir-capacity units exceeding 600 milliliters.
- Lithium-ion battery chemistry advances:Energy density improvements enable cordless designs with sustained pressure output, unlocking travel-segment adoption across European urban corridors.
Market Restraints
- CE marking clinical evidence burdens:EU MDR framework requirements for European market access extend registration timelines and elevate documentation costs for smaller device manufacturers.
- Resin supply concentration:Medical-grade polymer feedstocks for reservoir housings cluster with specialized compounders in Bavaria and Guangdong, creating input cost volatility during logistics disruptions.
- Manual floss substitution:Low-cost string floss retains preference among price-sensitive household segments in rural United States counties, compressing addressable market penetration rates.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing create tariff-advantaged export platforms targeting Middle East and Southeast Asian distribution networks.
- Sonic-pulsation convergence:Integration of acoustic vibration with pressurized water streams enables multi-modal plaque removal, opening premium positioning above standalone mechanical categories.
- Pharmacy validation channels:First-time buyers seeking clinician endorsement represent an underexploited retail pathway distinct from e-commerce price competition.
Industry Challenges
- FDA 510(k) clearance timelines:Marketing claim substantiation for therapeutic indications requires extensive predicate device analysis, delaying revenue recognition for novel pressure-delivery architectures.
- Water-efficiency compliance:Anticipated environmental mandates from state-level regulators in California and Massachusetts will necessitate flow-rate redesigns for countertop units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Irrigator Market |
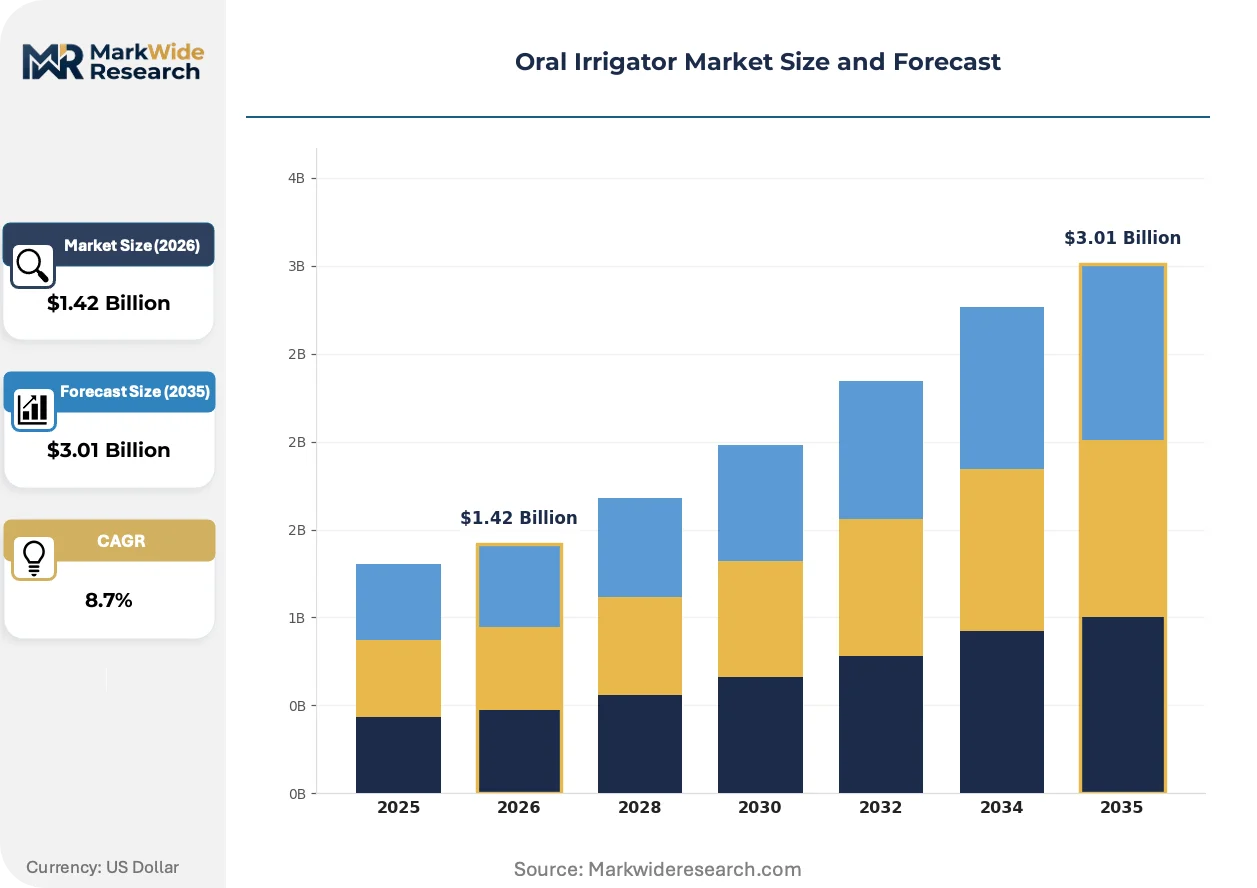
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Cordless, Portable, Specialty End User: Households, Dental Clinics, Hospitals, Orthodontic Practices Technology: Pulsating, Continuous Flow, Battery Operated, Plug-in Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Procter & Gamble, Johnson & Johnson, Waterpik, Hydro Floss, Aquapick, Philips, Colgate-Palmolive, Jetpik, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Irrigator Market Strategic Shifts & Innovations
Pressurized oral care devices are undergoing functional specialization, with engineering priorities diverging between clinical reimbursement optimization and consumer convenience maximization.
Micro-pump actuator technology is decomposing the traditional separation between fixed-reservoir countertop performance and portable cordless convenience. German dental equipment distributors are piloting hybrid units with detachable pressure modules for chairside-to-home continuity. This convergence is compressing the historical trade-off between pulse consistency and travel portability that segmented the category.
EU MDR clinical evidence standards are elevating barrier-to-entry thresholds for European market access. Manufacturers must now submit prospective efficacy data for plaque-reduction claims previously supported by predicate equivalence. German and French notified bodies are prioritizing review queues for devices with documented periodontal maintenance outcomes, advantaging established clinical-grade portfolios.
Subscription-based consumable replenishment is displacing transactional replacement purchases for jet-tip cartridges. United States direct-to-consumer platforms are bundling quarterly tip deliveries with pressure-calibration services, locking in recurring revenue streams. This model concentrates customer lifetime value capture among digitally native entrants rather than legacy pharmacy-dependent brands.
Oral Irrigator Market Segmentation
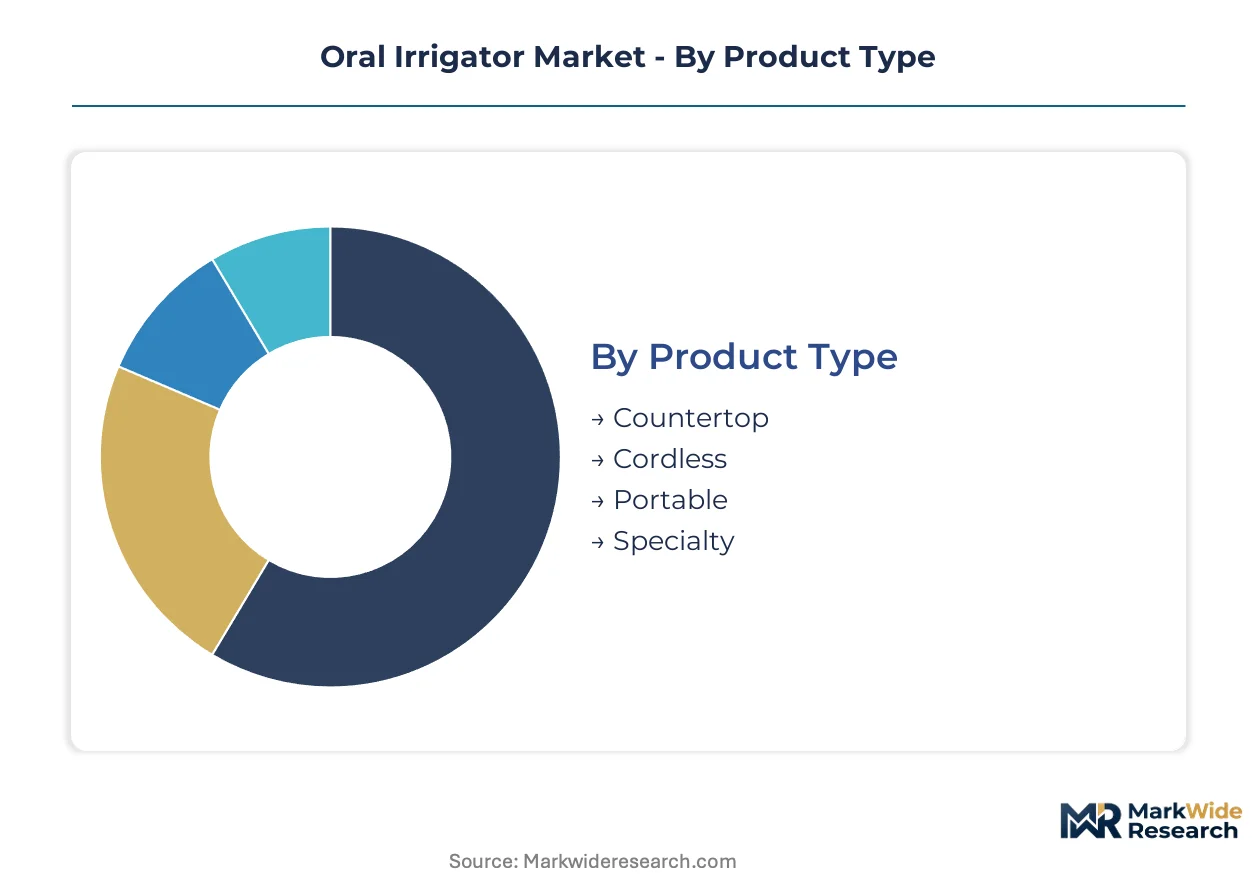
Oral irrigator segmentation reflects divergent engineering priorities between clinical reimbursement pathways and consumer convenience maximization. Regulatory frameworks in the United States, Germany, and Japan create distinct specification thresholds that reshape competitive positioning across each category.
Product Type:
FDA 510(k) clearance requirements and CE marking under EU MDR impose differentiated pressure-output documentation standards that favor established manufacturers with predicate device portfolios.
- Countertop:Fixed-reservoir designs exceeding 600 milliliters deliver sustained pulse consistency above 1,200 pulses per minute. Demand concentrates in suburban United States households where dental insurance reimbursement for preventive periodontal maintenance reduces out-of-pocket acquisition costs.
- Cordless:Lithium-ion battery architectures achieve pressure parity with countertop units through advanced micro-pump actuators. German and Japanese urban professionals drive adoption in travel segments where TSA-compliant portability intersects with clinical-grade efficacy requirements.
- Portable:Collapsible reservoir designs sacrifice pressure consistency for packability. Compact dimensions target Southeast Asian business travelers and European weekend commuters.
- Specialty:Orthodontic-specific tip configurations address bracket-adjacent plaque accumulation. Narrow nozzle geometries serve post-surgical irrigation protocols in Japanese oral surgery clinics.
Established volume favors countertop; emerging adoption favors cordless.
End User:
Procurement authority and reimbursement eligibility create divergent margin structures across institutional and household segments.
- Households:Direct-to-consumer channels dominate with subscription-based tip replenishment models. United States pharmacy validation remains critical for first-time purchasers seeking clinician endorsement before online migration.
- Dental Clinics:Chairside-to-home continuity protocols in Germany integrate pressurized water-flossing into standard preventive care workflows. Institutional procurement volumes favor reservoir-capacity units with documented periodontal maintenance outcomes.
- Hospitals:Inpatient oral care protocols require infection-control-rated housing materials. Japanese acute care facilities specify PMDA-cleared electrical safety standards for imported units.
- Orthodontic Practices:Specialized tip configurations for bracket-adjacent irrigation command premium positioning. California and Texas orthodontic chains drive North American demand for multi-patient tip sterilization systems.
Reimbursement access favors dental clinics; price elasticity favors households.
Technology:
Energy density improvements in battery chemistry are compressing the historical performance gap between fixed and portable architectures.
- Pulsating:Intermittent pressure delivery at 10–100 psi optimizes plaque dislodgement with minimal gingival trauma. Clinical-grade thresholds above 1,200 pulses per minute separate professional reimbursement pathways from consumer retail channels in the United States and Germany.
- Continuous Flow:Steady aqueous streams suit post-surgical irrigation and implant maintenance protocols. Steady output demands higher reservoir turnover, constraining portable applications.
- Battery Operated:Lithium-ion cell chemistry enables cordless designs with sustained pressure output. Energy density gains unlock travel-segment expansion across European urban corridors.
- Plug-in:AC-powered consistency eliminates charge-cycle anxiety for daily home use. Japanese aging demographics favor simplicity over portability in Tokyo and Osaka prefectures.
Clinical validation favors pulsating; convenience expansion favors battery operated.
Distribution Channel:
Channel selection determines customer acquisition cost structures and lifetime value capture mechanisms.
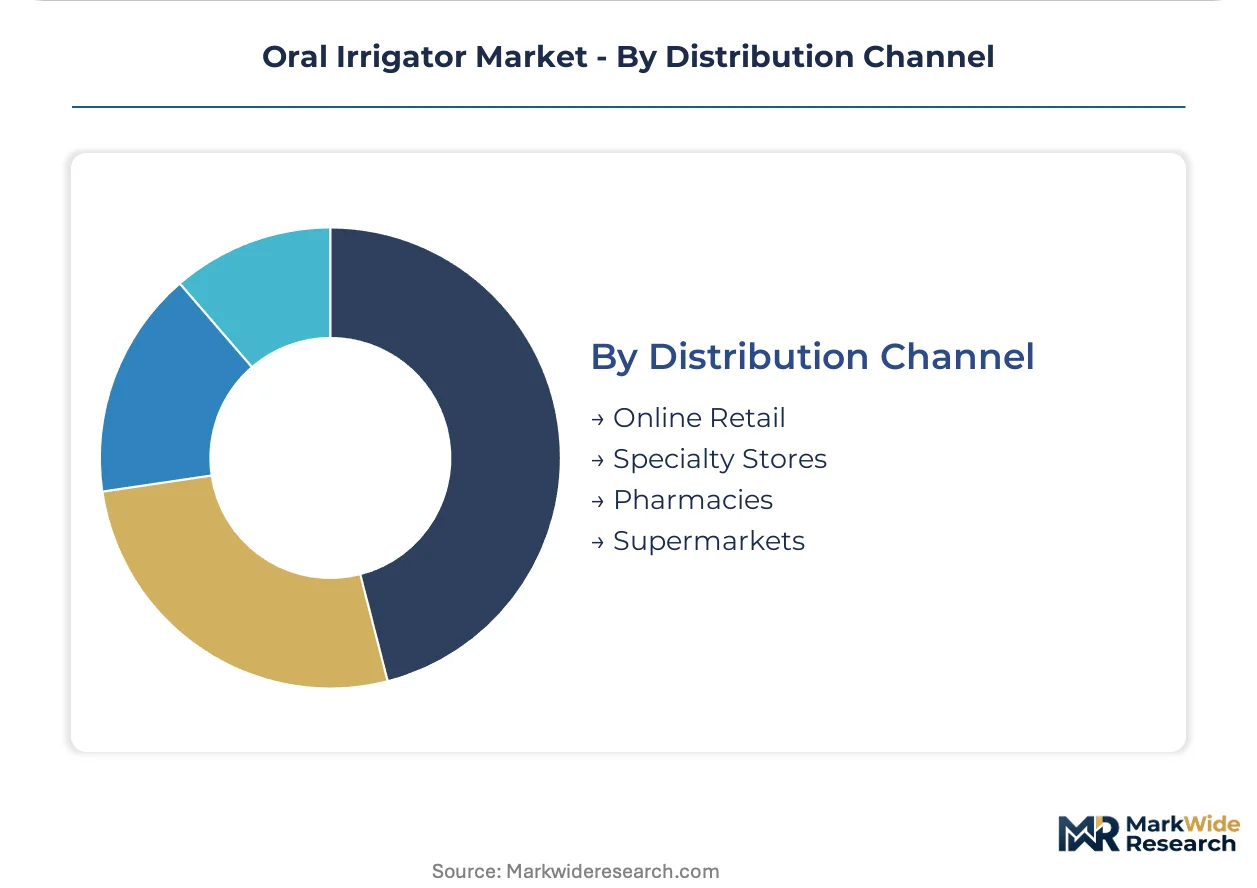
- Online Retail:Direct-to-consumer platforms bundle quarterly tip deliveries with pressure-calibration services. Digital native entrants concentrate recurring revenue capture away from legacy pharmacy-dependent brands.
- Specialty Stores:Dental equipment distributors in Germany pilot hybrid units with detachable pressure modules. Staff expertise supports clinical-grade specification navigation for institutional buyers.
- Pharmacies:First-time buyer validation remains structurally important for clinician-seeking segments. Rural United States counties retain pharmacy preference over e-commerce price competition.
- Supermarkets:Mass-market placement drives impulse trial among manual floss substitution segments. Low-margin positioning compresses feature sets to basic pressure-output specifications.
Customer lifetime value favors online retail; trust transfer favors pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing in China and Germany supplies countertop and cordless units to deficit markets in the United States and Japan, where domestic production concentrates on premium clinical-grade specifications and regulatory compliance services.
United States
FDA 510(k) clearance requirements shape device marketing claims for therapeutic indications, with suburban households in Texas and Florida driving countertop adoption through dental insurance reimbursement for preventive periodontal maintenance. The EPA anticipates state-level water-efficiency mandates from California and Massachusetts regulators.
Germany
Dental clinics in Bavaria and North Rhine-Westphalia integrate pressurized water-flossing into standard preventive care workflows, expanding institutional procurement for reservoir-capacity units exceeding 600 milliliters. CE marking under the EU MDR framework imposes clinical evidence standards that extend registration timelines for novel pressure-delivery architectures.
Japan
PMDA electrical safety and efficacy labeling standards reduce market entry friction for compliant manufacturers targeting aging demographic clusters in Tokyo and Osaka prefectures. Japanese acute care facilities specify PMDA-cleared standards for imported units used in inpatient oral care protocols.
China
Production-linked incentive schemes for medical devices create tariff-advantaged export platforms targeting Middle East and Southeast Asian distribution networks. Guangdong province hosts specialized compounders supplying medical-grade polymer feedstocks for reservoir housings.
India
Domestic manufacturing incentives under the PLI scheme position Indian producers to serve price-sensitive household segments across South Asia. Maharashtra and Gujarat industrial corridors attract contract manufacturers seeking cost-competitive bases for cordless lithium-ion designs.
Oral Irrigator Market Key Industry Players
Listed leaders compete with private specialists across regulatory compliance capabilities, with publicly traded conglomerates leveraging predicate device portfolios for faster FDA and CE marking approvals while private specialists concentrate on niche tip configurations and regional distribution partnerships. The market structure tiers into multinational oral care conglomerates, dedicated irrigator specialists, and electronics manufacturers extending into pressurized devices. M&A activity targets tip sterilization system providers, while capacity expansion concentrates in lithium-ion battery integration for cordless portability.
Within the multinational conglomerate tier, Procter & Gamble and Johnson & Johnson occupy positions anchored by pharmacy channel relationships and subscription-based consumable replenishment models. Philips exemplifies the electronics crossover archetype, leveraging sonic-pulsation integration across oral care device ecosystems. Waterpik represents the dedicated specialist position, with institutional loyalty sustained through American dental professional channel penetration.
| Leading Market Players |
|---|
| Procter & Gamble |
| Johnson & Johnson |
| Waterpik |
| Hydro Floss |
| Aquapick |
| Philips |
| Colgate-Palmolive |
| Jetpik |
| Panasonic |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery chemistry replacing nickel-metal hydride in cordless designs simultaneously relocates component sourcing toward South Korean and Chinese cell manufacturers while compressing per-unit power costs and enabling premium pricing for travel-grade portability.
Pricing Analysis
Household buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on pulse-frequency certification tier and pharmacy channel validation. Pricing pressure stems from direct-to-consumer subscription models undercutting legacy retail markups. Rural United States households exhibit highest price sensitivity; German dental clinics demonstrate lowest.
Supply Chain Analysis
China and Germany anchor reservoir housing production through specialized medical-grade polymer compounders in Guangdong and Bavaria. Feedstocks draw from petroleum-derived ABS and polycarbonate resins. Single-source vulnerability concentrates with Bavarian specialty compounders serving CE-marking documentation requirements. Distribution runs through dental equipment distributors for institutional procurement and direct-to-consumer platforms for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral irrigator market functions as a regulatory-moat industry where FDA 510(k) predicate portfolios and CE marking dossiers create switching costs that institutional buyers cannot easily circumvent.
For Market Incumbents: Shield reimbursement pathway entrenchment by deepening predicate device libraries for faster FDA clearances on novel pressure-delivery architectures. Expand captive production of lithium-ion battery modules to offset South Korean cell supplier concentration. Counter emerging direct-to-native subscription entrants through pharmacy channel exclusivity agreements. For New Entrants and Emerging Players: Post-surgical irrigation protocols in Japanese oral surgery clinics represent underserved white space where narrow-nozzle specialty configurations command premium positioning. India's PLI scheme offers tariff-advantaged manufacturing for Middle East export platforms. Pursue GPO contracts with California orthodontic chains as beachhead entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clinical-grade specialists with documented periodontal maintenance outcomes. Long-term viability rests on tip sterilization system providers capturing recurring revenue streams. Monitor FDA 510(k) clearance queue lengths as inflection signal for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Expedited marketing claims for therapeutic indications compress revenue recognition timelines for novel architectures. |
| CE Marking Dossier Expansion | EU MDR clinical evidence standards elevate barrier-to-entry thresholds advantaging established portfolios. |
| Pharmacy Channel Partnership | Clinician validation transfer captures first-time buyer trust before online migration. |
| Subscription Tip Replenishment | Quarterly delivery bundling locks recurring revenue away from transactional replacement purchases. |
| Lithium-Ion Battery Integration | Energy density gains unlock travel-segment adoption across TSA-compliant portable designs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body decisions, PMDA electrical safety registrations, and dental equipment distributor procurement databases. Primary inputs span dental clinic procurement managers, biomedical engineers at Japanese acute care facilities, GPO contracts specialists, and oral care brand managers. Bottom-up unit shipment estimates triangulate against top-down reimbursement code analysis.
Segmentation dimensions modeled include product architecture, end-user procurement authority, pressure-delivery technology, and distribution channel structure across the projection horizon. CAGRs derive from regression analysis of historical predicate device approval timelines and reimbursement code expansion patterns. Forecast inputs incorporate lithium-ion cell chemistry cost curves and state-level water-efficiency mandate probability.
Forecasts assume regulatory continuity in FDA, EU MDR, and PMDA regimes; material policy shifts would require re-modeling. Specific risks include CE marking timeline extensions, resin feedstock logistics disruptions, and manual floss substitution preference persistence. Recalibration cycles align with material shifts in reimbursement code coverage and battery chemistry cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Antiseptics Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Dry Mouth Relief Market
Oral Care
Halitosis Treatment Market
Oral Care
Manual Toothbrush Market
Oral Care
LED Oral Care Kits Market
Oral Care
Herbal Toothcare Market
Oral Care
Oral Rinse Market
Oral Care
Global Oral Care Products Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Toothcare Market
Oral Care
North America Oral Care Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Herbal Toothpaste Market
Oral Care
Kids Toothpaste Market