
 South America Oral Care Market | 2026-2036
South America Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
South America Oral Care Market Analytics
Supermarket buyer concentration is expanding across Brazil and Argentina as modern trade chains consolidate oral care shelf space. Colgate-Palmolive Company leverages its manufacturing scale to dominate mass-market toothpaste supply. Procter & Gamble competes through premium positioning in whitening strips and electric brush systems. Johnson & Johnson anchors professional channel sales through dental clinic partnerships across São Paulo state.
Oral care encompasses dentifrices, rinses, interdental cleaners, and aesthetic treatments formulated with active ingredients such as fluoride, hydrogen peroxide, and essential oils to prevent caries, reduce plaque, and improve dental aesthetics. Toothpaste leads volume throughput due to daily-use frequency and low per-unit price elasticity. Mouthwash registers faster value expansion as Brazilian households upgrade to therapeutic formulations targeting gingivitis. Dental Floss occupies a niche margin pool concentrated in dental clinic dispensing and premium drugstore placements.
ANVISA governs fluoride limits and cosmetic claims for whitening products in Brazil, while Argentina's national pharmaceutical regulator enforces comparable safety thresholds. Compliance with these frameworks shapes product registration timelines and labeling requirements. Stakeholders must monitor regulatory divergence between Mercosur members to optimize portfolio standardization versus localization trade-offs.
Market Dynamics
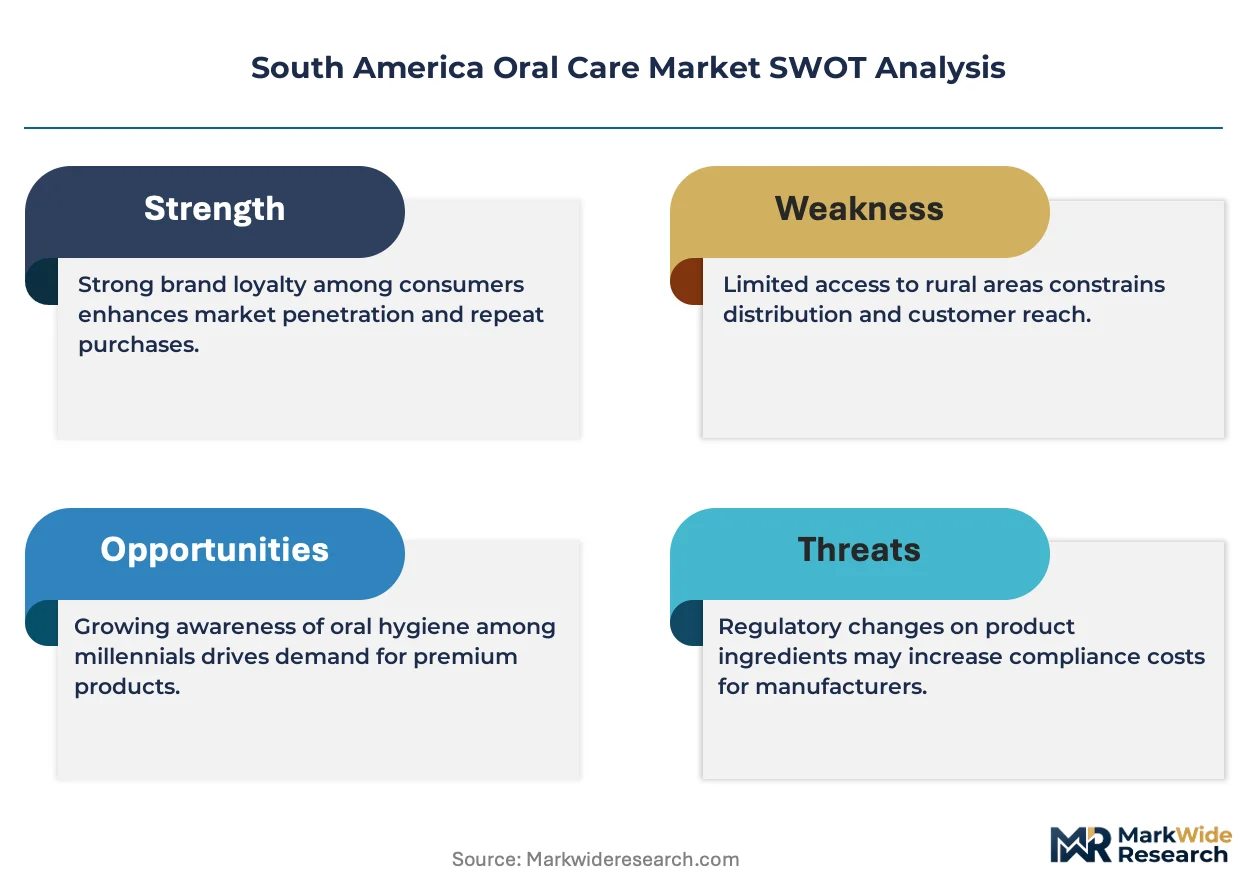
ANVISA's tightened fluoride concentration standards are forcing manufacturers to reformulate entire product portfolios, while supermarket buyer consolidation across Brazil and Argentina reshapes shelf access and pricing power for oral care suppliers.
Growth Catalysts
- Urban Premiumization:Young adult consumers in São Paulo and Rio de Janeiro state retail networks are driving adoption of whitening formulations with higher per-unit margins.
- Therapeutic Mouthwash Upgrades:Brazilian households are shifting from cosmetic rinses to formulations targeting gingivitis, expanding the value pool beyond basic oral hygiene.
- Professional Channel Expansion:Dental clinic dispensing networks across São Paulo state are anchoring premium floss and interdental cleaner sales.
Market Restraints
- Regulatory Divergence:ANVISA and Argentina's national pharmaceutical regulator enforce differing safety thresholds, complicating Mercosur portfolio standardization.
- Input Concentration:Hydrogen peroxide supply for whitening products concentrates among specialty chemical producers, creating formulation cost volatility.
- Modern Trade Gatekeeping:Consolidated supermarket chains in Brazil's southeast corridor control oral care shelf space, squeezing supplier margins.
Strategic Opportunities
- Argentina Market Development:Modern trade consolidation in Buenos Aires and Córdoba provinces offers shelf space expansion for therapeutic rinse portfolios.
- Electric Brush System Convergence:Battery technology improvements and pressure-sensor integration are opening premium positioning above manual brush replacement cycles.
- E-commerce Direct Channels:Subscription-based replenishment models are bypassing traditional drugstore intermediaries in Brazilian metropolitan zones.
Industry Challenges
- Reformulation Timelines:ANVISA product registration delays are extending time-to-market for modified fluoride concentrations.
- Clinical Validation Costs:Therapeutic claims for gingivitis-targeting mouthwashes require substantiation studies that strain mid-tier R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Oral Care Market |
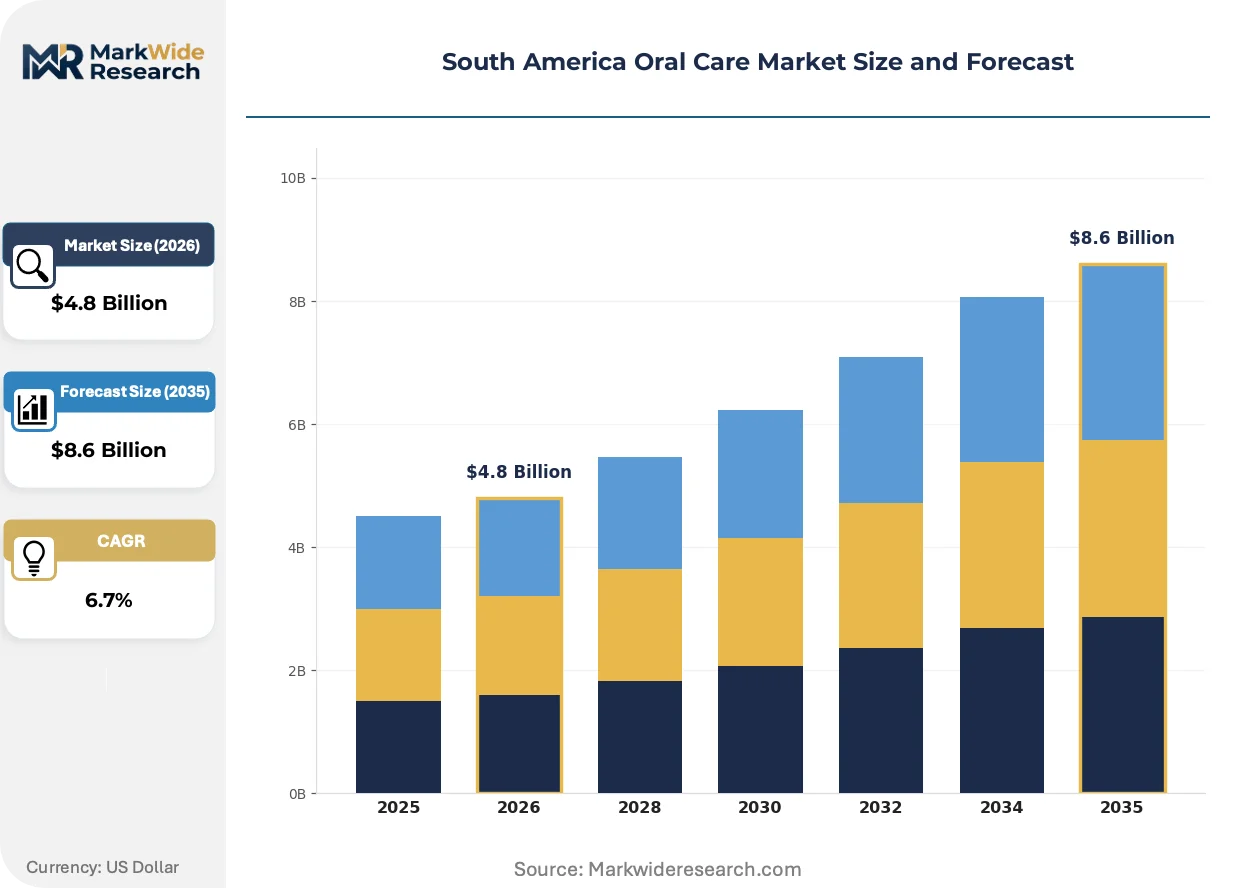
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Products End User: Households, Dental Clinics, Hospitals, Retail Pharmacies Distribution Channel: Online Retail, Supermarkets, Drugstores, Convenience Stores Packaging Type: Tubes, Bottles, Sachets, Jars |
| Companies Covered | GlaxoSmithKline PLC, Johnson & Johnson, Colgate-Palmolive Company, Haleon PLC, Sunstar Suisse SA, Procter & Gamble, Henkel AG & Co. KGaA, Dentek Oral Care Inc., Unilever, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Oral Care Market Evolving Landscape
Whitening technology convergence with daily-use dentifrices is compressing the distinction between cosmetic and therapeutic oral care, while regulatory scrutiny intensifies across South American markets.
Peroxide-activated whitening systems are consolidating into standard toothpaste bases, enabling daily-use convenience without separate treatment steps. Urban Brazilian consumers in the 25-35 age bracket are adopting these hybrid formulations fastest. This consolidation is compressing standalone whitening strip volumes into core dentifrice replacement cycles.
ANVISA's fluoride concentration standards are tightening permissible ranges for over-the-counter dentifrices, forcing active ingredient recalibration across mass-market portfolios. Manufacturers must resubmit registration dossiers for existing SKUs, extending compliance timelines by quarters. Brazil's southeast corridor retail networks are absorbing these reformulation costs through supplier margin compression.
Subscription-based replenishment models are displacing traditional pharmacy and supermarket restocking for premium electric brush heads and therapeutic rinses. Direct-to-consumer channels in São Paulo and Rio de Janeiro metropolitan zones are capturing recurring revenue streams. Argentina's urban centers are replicating this pattern as logistics infrastructure matures.
South America Oral Care Market Segmentation
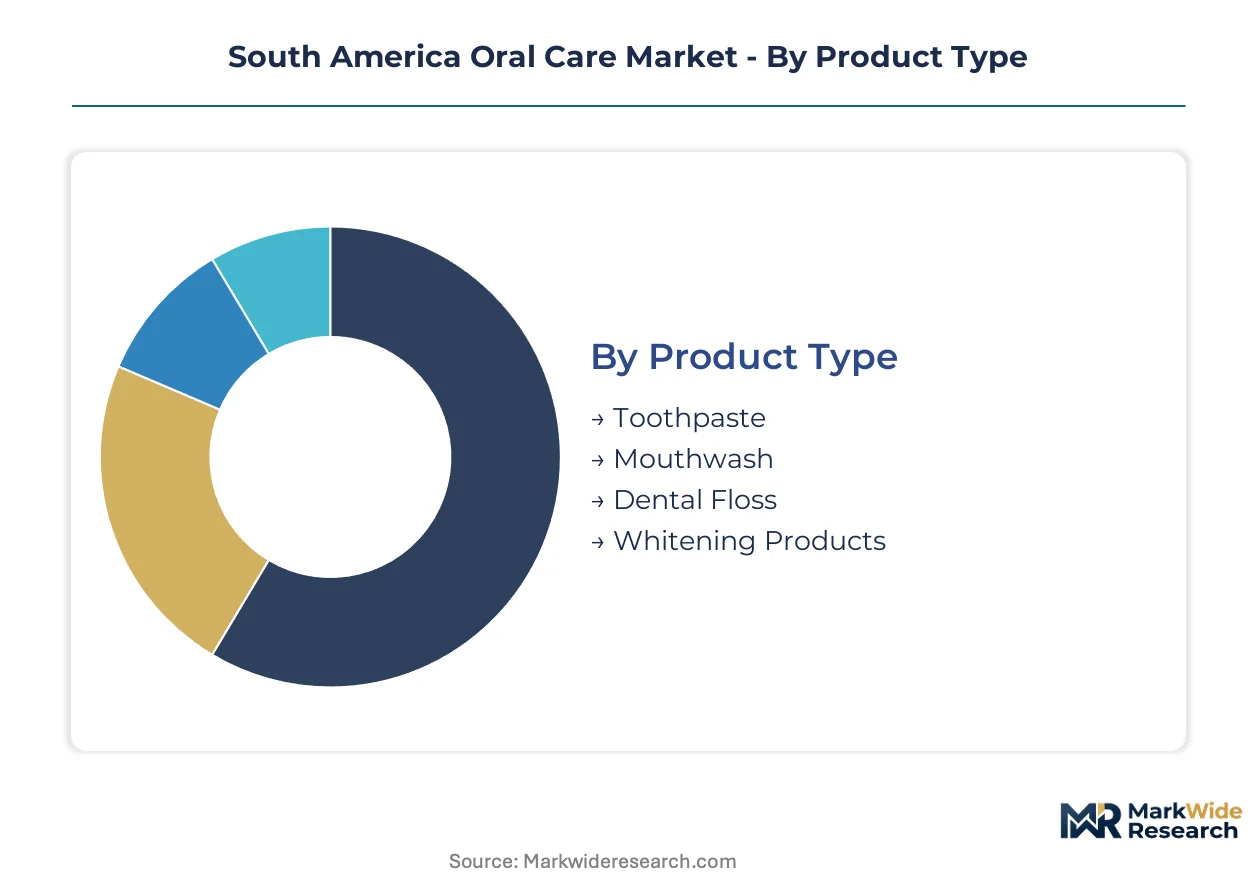
Oral care segmentation in South America reveals distinct margin architectures across product formulations and channel access points. Manufacturers must calibrate portfolio depth against regulatory compliance costs and modern trade consolidation patterns.
Product Type:
Standardization dominates mass-market dentifrices while therapeutic and aesthetic formulations demand customization to meet ANVISA's evolving fluoride and peroxide thresholds.
- Toothpaste:Formulated with fluoride, hydrogen peroxide, or essential oil actives in paste or gel bases. Daily-use frequency in Brazilian southeast corridor households sustains volume throughput despite low per-unit elasticity. ANVISA's tightened concentration standards are forcing active ingredient recalibration across mass-market portfolios.
- Mouthwash:Cosmetic and therapeutic rinses targeting plaque reduction or gingivitis prevention. Brazilian households upgrading from basic hygiene to therapeutic formulations are expanding the value pool fastest in São Paulo and Rio de Janeiro metropolitan networks.
- Whitening Products:Peroxide-activated systems including strips and trays. Urban young adults in Brazil's southeast corridor drive adoption of hybrid dentifrice-integrated formulations.
- Dental Floss:Waxed and unwaxed string or tape formats for interdental cleaning. Professional channel dispensing in São Paulo state dental clinics anchors premium margin capture.
Leading the category by volume: Toothpaste. Growing fastest: Mouthwash.
End User:
Volume concentration sits with household replenishment cycles while professional channels command pricing premiums through clinical validation requirements.
- Households:Individual and family consumers purchasing through retail networks for daily hygiene maintenance. Southeast Brazil's urban corridor generates the highest per-capita consumption of premium whitening and therapeutic rinse formulations.
- Dental Clinics:Professional dispensing of interdental cleaners, prescription-strength rinses, and patient education samples. São Paulo state clinic networks anchor premium floss and therapeutic product sales through practitioner recommendations.
- Hospitals:Institutional procurement for pre-operative oral preparation and inpatient hygiene protocols. Procurement concentrates in Brazil's public health system and private hospital chains.
- Retail Pharmacies:Counter sales of therapeutic mouthwashes and specialty dentifrices with clinical positioning. Argentine pharmacy chains in Buenos Aires and Córdoba provinces are expanding shelf space for gingivitis-targeting formulations.
Households dominate absolute consumption. Dental clinics deliver the steepest margin expansion trajectory.
Distribution Channel:
Physical retail retains volume supremacy while digital channels are compressing replenishment cycle lengths for subscription-compatible products.
- Supermarkets:Modern trade chains with consolidated oral care shelf space across Brazil and Argentina. Buyer concentration in Brazil's southeast corridor is squeezing supplier margins while controlling access for mass-market toothpaste and rinse brands.
- Drugstores:Pharmacy networks emphasizing therapeutic formulations and professional-grade products. Brazilian and Argentine drugstore chains are upgrading oral care assortments toward clinical positioning.
- Online Retail:E-commerce platforms and direct-to-consumer subscription models. São Paulo and Rio de Janeiro metropolitan zones are capturing recurring revenue streams for electric brush heads and therapeutic rinses.
- Convenience Stores:Small-format retail for emergency replenishment and travel-size products. Limited oral care assortment focuses on commodity toothpaste and single-use mouthwash sachets.
Supermarkets control the widest SKU breadth. Online retail is climbing the fastest on subscription attach rates.
Packaging Type:
Primary packaging formats balance shelf differentiation, dispensing convenience, and regulatory labeling compliance across diverse retail environments.
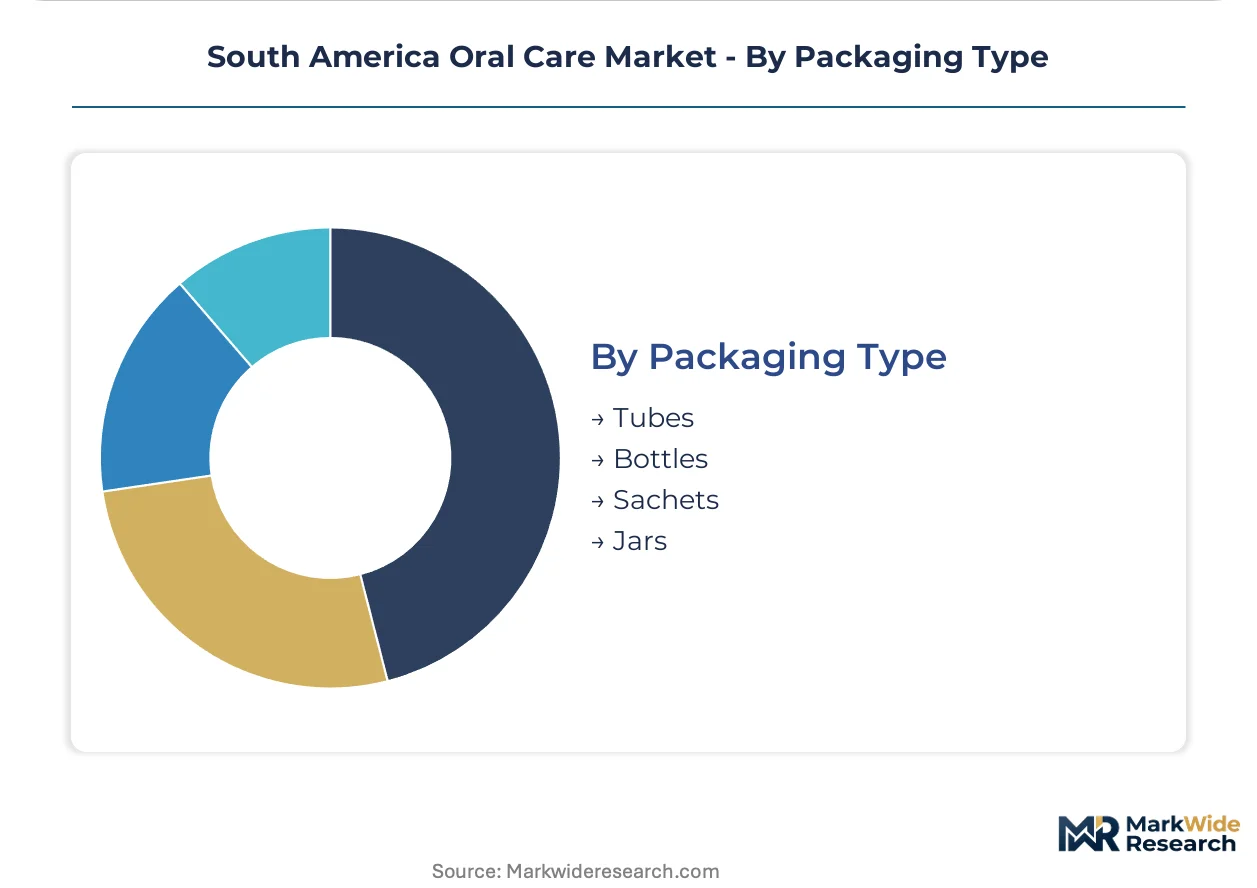
- Tubes:Collapsible aluminum or plastic laminate containers for toothpaste and some cream-based products. Standard format for mass-market dentifrices with established filling and sealing infrastructure.
- Bottles:Rigid plastic or glass containers for liquid mouthwashes and rinses. Therapeutic formulations require child-resistant closures and precise dosing mechanisms.
- Sachets:Single-serve flexible pouches for travel, samples, and emerging market price-point access. Convenience store and hospitality channel penetration drives format adoption.
- Jars:Wide-mouth rigid containers for powder dentifrices, specialty whitening compounds, and professional dispensing sizes. Limited to premium and professional channel distribution.
Tubes maintain the highest unit shipment volumes. Bottles are gaining share fastest on therapeutic rinse expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's southeast corridor, where São Paulo and Rio de Janeiro metropolitan networks generate the highest per-capita consumption of premium whitening and therapeutic rinse formulations across the continent.
Brazil
Urban young adults in São Paulo state drive adoption of peroxide-integrated whitening dentifrices with higher margins. ANVISA tightened fluoride concentration standards, forcing manufacturers to resubmit registration dossiers for existing SKUs. São Paulo and Rio de Janeiro retail networks absorb reformulation costs through supplier margin compression while sustaining volume throughput.
Argentina
Modern trade consolidation in Buenos Aires and Córdoba provinces expands shelf space for therapeutic rinse portfolios targeting gingivitis. Argentina's national pharmaceutical regulator enforces safety thresholds that diverge from ANVISA standards, complicating Mercosur portfolio standardization. Pharmacy chains in Buenos Aires upgrade oral care assortments toward clinical positioning.
Chile
Santiago metropolitan consumers demonstrate strong uptake of subscription-based replenishment models for electric brush heads and therapeutic rinses. The country's national pharmaceutical regulator maintains distinct cosmetic claims requirements for whitening products. E-commerce logistics infrastructure in Santiago and Valparaíso enables direct-to-consumer channel growth.
Colombia
Bogotá and Medellín urban clusters show emerging demand for premium interdental cleaners and professional-grade formulations. Colombia's national health regulator oversees fluoride limits and therapeutic claims registration. Drugstore networks in Bogotá expand shelf space for imported therapeutic mouthwash brands.
Peru
Lima metropolitan households represent an underpenetrated market for electric brush systems and hybrid whitening dentifrices. The country's national pharmaceutical regulator implements cosmetic and therapeutic product registration frameworks. Modern trade chains in Lima pilot oral care premiumization strategies targeting middle-income consumers.
South America Oral Care Market Competitive Landscape
Brazil-based manufacturing operations anchor the mass-market tier; European and North American multinationals hold premium positioning through brand equity and professional channel access. The market structure consolidates around three to four dominant manufacturers controlling supermarket shelf space, with mid-tier specialists competing through niche therapeutic formulations. Strategic archetypes include scale-driven mass-market suppliers, premium-brand portfolio owners, and professional-channel specialists. Competitive moves center on regulatory compliance-driven reformulation and e-commerce direct channel expansion.
Among multinational portfolio owners, Colgate-Palmolive Company exemplifies scale-driven mass-market supply dominance, while Procter & Gamble occupies a position within premium whitening and electric brush system segments. Johnson & Johnson anchors professional channel representation through dental clinic partnerships, particularly across São Paulo state networks.
| Leading Market Players |
|---|
| GlaxoSmithKline PLC |
| Johnson & Johnson |
| Colgate-Palmolive Company |
| Haleon PLC |
| Sunstar Suisse SA |
| Procter & Gamble |
| Henkel AG & Co. KGaA |
| Dentek Oral Care Inc. |
| Unilever |
| Others |
Value Network & Pricing Analysis
Peroxide-activated whitening system integration into daily-use dentifrice bases is simultaneously compressing production cost structures and concentrating formulation expertise among ANVISA-certified manufacturers in Brazil's southeast corridor. This convergence forces mid-tier suppliers to absorb margin compression while supermarket buyer consolidation amplifies pricing power asymmetries.
Pricing Analysis
Volume-throughput concentration in standard fluoride dentifrices sits opposite margin capture in therapeutic mouthwashes and hybrid whitening formulations. Three-tier pricing structure across premium, standard, and economy levels differentiates by active ingredient concentration and clinical validation status. Cost compression in mass-market toothpaste is intensifying because ANVISA reformulation requirements extend registration timelines. Household consumers in Brazil's urban corridor exhibit highest price sensitivity, while dental clinic dispensing networks show lowest elasticity.
Supply Chain Analysis
ANVISA certification and Argentine pharmaceutical regulator qualification gating restricts active ingredient sourcing to pre-approved specialty chemical producers in Brazil, Argentina, and Germany. Hydrogen peroxide supply for whitening formulations draws from concentrated specialty chemical producers, creating single-source vulnerability for peroxide-activated systems. Distribution runs through modern trade chains in Brazil's southeast corridor and pharmacy networks in Buenos Aires and Córdoba provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peroxide-integrated whitening dentifrices are displacing standalone whitening strips and cosmetic rinses, compressing legacy product cycles while opening premium positioning for validated therapeutic formulations.
For Market Incumbents: Extend professional channel partnerships in São Paulo state dental clinics to anchor premium interdental cleaner and prescription-strength rinse sales against subscription-based direct-to-consumer entrants. Deepen backward integration into hydrogen peroxide sourcing to buffer formulation cost volatility from specialty chemical supplier concentration. For New Entrants and Emerging Players: The gap between premium whitening systems and economy fluoride dentifrices offers white-space targeting through mid-tier therapeutic mouthwashes with gingivitis claims. Argentina's Buenos Aires and Córdoba pharmacy chains represent the most penetrable geography, accessible through clinical positioning and practitioner sampling programs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational consumer health portfolios seeking ANVISA-compliant manufacturing assets. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch ANVISA registration backlog clearance rates as inflection indicator for time-to-market competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Dossier Expansion | Accelerates market access for reformulated fluoride concentrations in Brazil's southeast retail networks. |
| Dental Clinic Partnership Deepening | Captures premium margin pools through practitioner recommendation in São Paulo state dispensing networks. |
| Subscription Model Launch | Bypasses supermarket buyer gatekeeping for electric brush head replenishment in metropolitan zones. |
| Therapeutic Mouthwash Portfolio Buildout | Addresses gingivitis-targeting demand upgrading in Brazilian and Argentine household segments. |
| E-commerce Direct Channel Investment | Reduces dependency on modern trade shelf space controlled by consolidated supermarket chains. |
Research Methodology
Independent corroboration across brand managers at multinational consumer health companies, category buyers at Brazilian supermarket chains, and procurement leads at Argentine pharmacy networks underwrites the qualitative findings. Secondary validation draws from ANVISA registration databases, Argentine pharmaceutical regulator filings, Nielsen retail audit data for oral care categories, and customs records of hydrogen peroxide imports. Bottom-up SKU-level volume estimates and top-down macroeconomic anchoring were reconciled through iterative triangulation.
Comparable-period anchoring to historical consumption patterns across Brazil's southeast corridor and Argentina's metropolitan provinces established baseline trajectory assumptions. Segmentation dimensions modeled include product formulation type, end-user channel, distribution format, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by regulatory event probabilities and channel shift elasticity parameters. Forecast inputs incorporated ANVISA compliance timeline distributions and supermarket buyer concentration indices.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time ANVISA registration processing data introduce uncertainty bands around near-term launch volume assumptions. Forecasts reflect documented scenario parameters including regulatory divergence persistence and hydrogen peroxide supply concentration. A model refresh is warranted upon material change in ANVISA fluoride concentration standard enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Kids Oral Care Products Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Oral Irrigator Market
Oral Care
Mouthwash Market
Oral Care
Herbal Toothcare Market
Oral Care
Oral Care Market
Oral Care
Oral Mucositis Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Xerostomia Treatment Market
Oral Care
LED Oral Care Kits Market
Oral Care
Toothcare Market
Oral Care
Oral Health Ingredient Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Oral Rinse Market