
 Europe Oral Hygiene Market | 2026-2036
Europe Oral Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oral Hygiene Market Intelligence
Germany is reshaping competitive dynamics in the Europe oral hygiene sector through expanded manufacturing capacity for therapeutic toothpaste and mouthwash formulations. Procter & Gamble leverages its established distribution infrastructure to sustain shelf dominance across Central European retail chains. Colgate-Palmolive differentiates through specialized enamel repair technologies that command premium positioning in pharmacy channels. Sunstar Suisse SA anchors the professional dental segment with clinician-endorsed periodontal care systems.
Europe oral hygiene encompasses consumer and professional products formulated with active ingredients such as fluoride compounds, chlorhexidine, hydrogen peroxide, and enzymatic complexes, manufactured through emulsion processing, aseptic filling, and stability-tested packaging to prevent microbial contamination and ensure therapeutic efficacy over shelf life. Toothpaste formulations occupy the largest value share within the product type dimension, while whitening products represent the fastest-expanding margin pool as aesthetic dentistry trends penetrate mass-market retail. The distribution channel structure tilts toward pharmacies in Northern Europe, where pharmacist consultation drives therapeutic product selection, whereas Southern European markets favor supermarket penetration for daily hygiene SKUs.
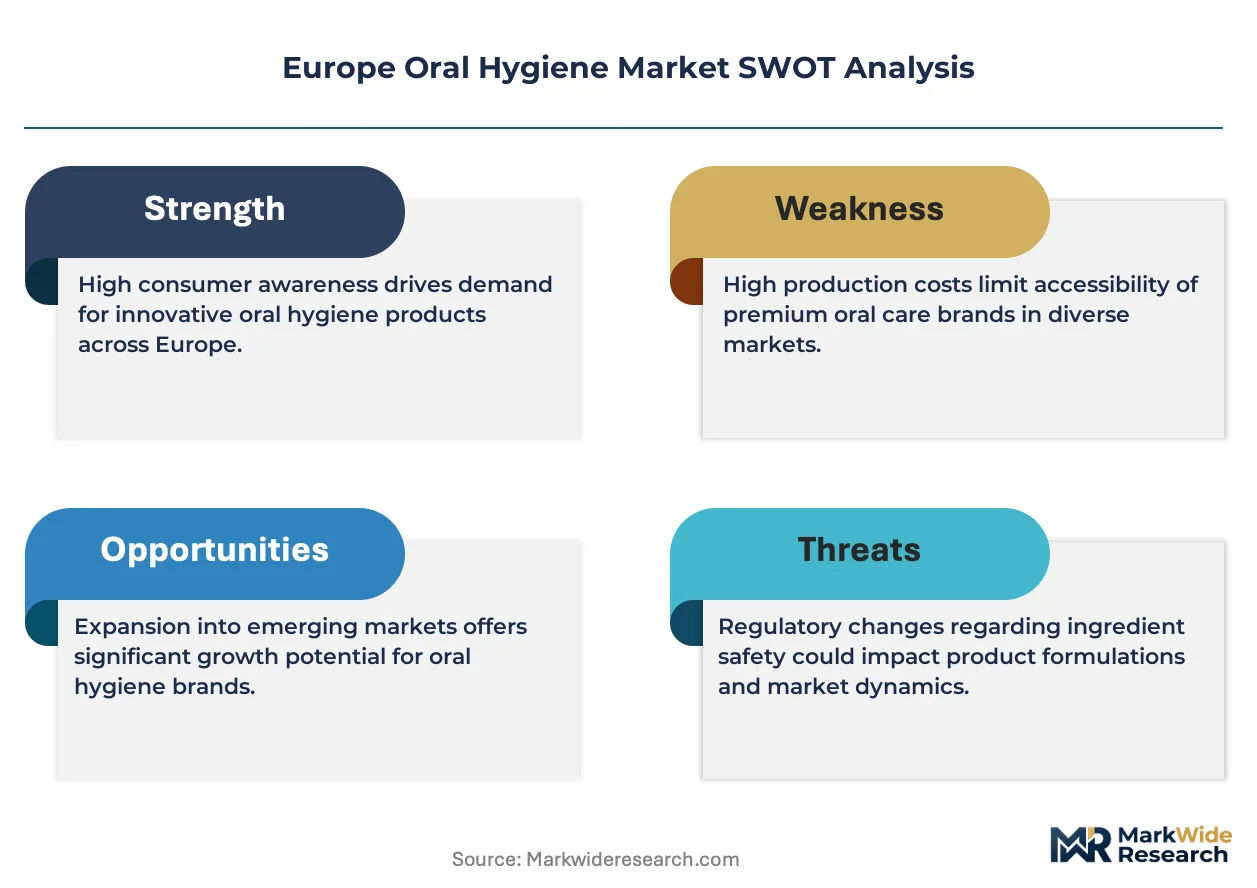
EMA guidelines on biocidal active substances and the EU Cosmetics Regulation govern ingredient safety thresholds and labeling requirements for oral care products sold across member states. ECHA's REACH enforcement mandates full supply chain transparency for chemical components, elevating compliance costs for imported formulations. CSRD disclosure rules now require sustainability reporting from large oral hygiene manufacturers, redirecting R&D investment toward biodegradable packaging and plant-derived surfactants. Stakeholders must monitor evolving EU packaging waste directives and biocidal product reauthorization timelines to anticipate reformulation cycles and supply chain restructuring.
Market Dynamics
ECHA's REACH enforcement is forcing full chemical disclosure across oral care supply chains, elevating compliance costs and favoring manufacturers with captive European production over import-dependent competitors.
Growth Catalysts
- Preventive dentistry protocols:Dental clinics in Germany and France are expanding non-invasive care programs that incorporate daily therapeutic toothpaste regimens. This institutional pull is creating stable demand for fluoride and enamel-repair formulations through professional recommendation channels.
- EU Cosmetics Regulation clarity:Harmonized safety thresholds across member states reduce formulation fragmentation. Manufacturers can scale single-SKU production runs for cross-border distribution rather than maintaining country-specific variants.
- Aesthetic dentistry normalization:Whitening product uptake in Spain and Italy is migrating from clinical settings to mass retail. Pharmacy chains in Madrid and Milan are dedicating premium shelf space to peroxide-based home treatments.
Market Restraints
- Biocidal reauthorization timelines:EMA's staggered review of chlorhexidine and other active ingredients creates formulation uncertainty. Manufacturers face stranded inventory risk if specific concentrations lose approval mid-cycle.
- Surfactant cost volatility:Plant-derived alternatives to sodium lauryl sulfate command 40-60% input premiums. European oleochemical supply concentrates in Southeast Asian palm and coconut processing clusters.
- Substitution by water flossers:Mechanical interdental cleaning devices are displacing traditional floss in Nordic markets. Oral-B and Waterpik systems claim bathroom counter space previously allocated to consumable string products.
Strategic Opportunities
- Eastern European pharmacy expansion:Poland and Romania maintain underdeveloped professional oral care channels. Therapeutic toothpaste positioning through Warsaw and Bucharest pharmacy networks remains open for first-mover capture.
- CSRD-aligned packaging innovation:The EU's Corporate Sustainability Reporting Directive creates procurement preference for biodegradable tubes and recyclable caps. Brand owners can differentiate through verified lifecycle assessments.
- Enzymatic-fluoride convergence:Dual-action formulations combining glucose oxidase with stabilized fluoride are emerging. These hybrid systems target the periodontal care segment with biofilm disruption plus remineralization claims.
Industry Challenges
- Stability testing capacity:Accelerated aging protocols for novel active ingredients require 12-24 month validation cycles. Contract laboratories in Switzerland and Germany report extended queue times.
- Legacy ERP integration:REACH-mandated supply chain transparency systems must interface with existing batch tracking infrastructure. Mid-size manufacturers face software customization costs exceeding six figures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oral Hygiene Market |
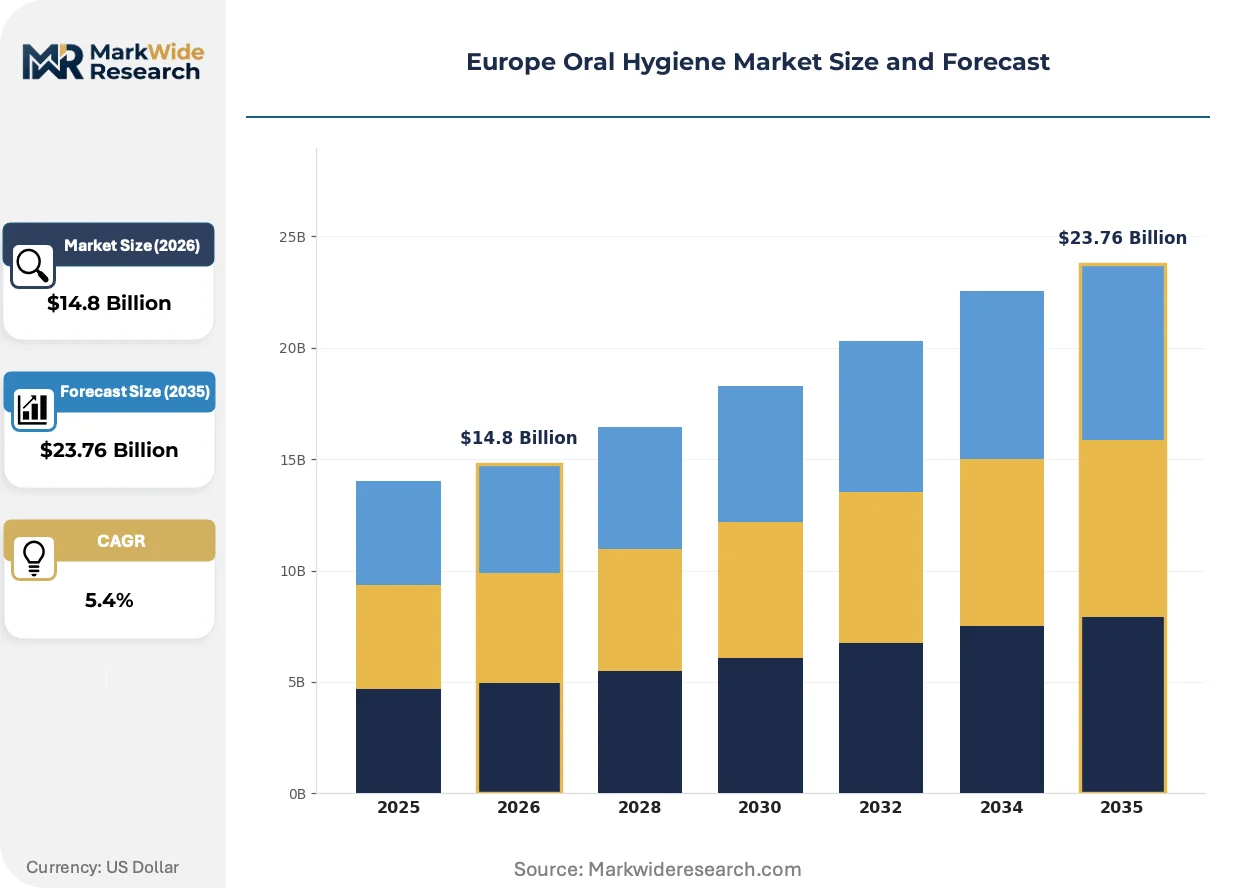
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Products Distribution Channel: Supermarkets, Pharmacies, Online Stores, Specialty Shops End User: Adults, Children, Elderly, Professionals Application: Preventive Care, Therapeutic Care, Cosmetic Enhancement, Daily Hygiene |
| Companies Covered | Haleon PLC, Church & Dwight Co., Inc., Procter & Gamble, Henkel AG & Co. KGaA, Sunstar Suisse SA, Colgate-Palmolive Company, GlaxoSmithKline PLC, Johnson & Johnson Consumer Inc, Unilever, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oral Hygiene Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to reshape how oral care products reach European consumers. Three distinct vectors are compressing development timelines and rewiring channel economics.
Enzymatic oral care technology is hybridizing with traditional chemical actives to create next-generation therapeutic positioning. Glucose oxidase and lactoperoxidase systems are gaining traction in German pharmacy channels where clinician endorsement drives selection. These bioactive platforms are enabling premium pricing tiers that compress standard fluoride margins in adjacent shelf positions.
CSRD disclosure rules are mandating granular sustainability reporting from large oral hygiene manufacturers. The framework requires documented supply chain emissions and packaging lifecycle assessments. Northern European markets are responding fastest, with Stockholm and Copenhagen retailers prioritizing SKUs with verified biodegradable tube certifications.
Pharmacist consultation is reclaiming influence over therapeutic product selection in France and Belgium. Supermarket penetration of daily hygiene SKUs had eroded this channel, but reimbursement alignment for periodontal prevention is reversing the pattern. Paris pharmacy chains are rebuilding dedicated oral care sections with trained staff.
Europe Oral Hygiene Market Segmentation
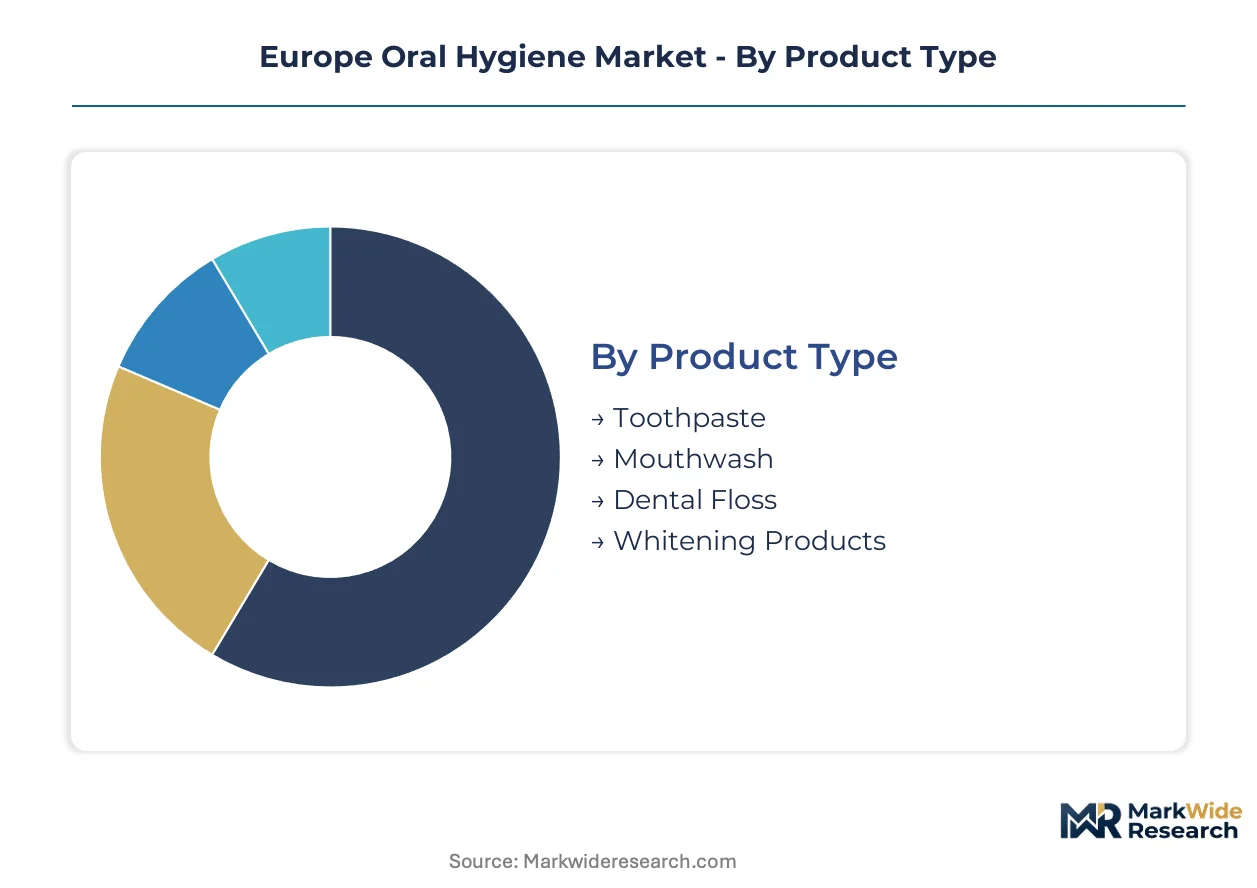
Europe's oral hygiene market fragments across four dimensions that each carry distinct margin profiles and replenishment rhythms. Product type segmentation governs manufacturing asset allocation, while distribution channel structure determines compliance burden and working capital intensity.
Product Type:
Toothpaste cycles through household pantries fastest, with average replenishment intervals under 60 days driving volume velocity. Whitening products and therapeutic rinses turn slower but command shelf-space premiums that alter retail negotiation leverage.
- Toothpaste:Emulsion-based formulations incorporating fluoride compounds, hydroxyapatite, or enzymatic complexes dominate production lines. German pharmacy chains in Munich and Hamburg prioritize therapeutic variants with clinician endorsement programs. ECHA REACH compliance elevates transparency costs for imported active ingredient bundles.
- Whitening Products:Peroxide-based gels and strips target aesthetic dentistry migration into mass retail. Spanish and Italian consumers in Madrid and Milan pharmacy networks drive uptake of home treatment systems. EMA biocidal substance reviews create formulation uncertainty for hydrogen peroxide concentrations.
- Mouthwash:Chlorhexidine and essential oil formulations serve periodontal protocols. French dental clinics recommend specific therapeutic rinses with reimbursement alignment.
- Dental Floss:Waxed and unwaxed nylon or PTFE variants face mechanical substitution from water flossers in Nordic markets.
Toothpaste dominates installed base. Whitening products are where expansion concentrates.
Distribution Channel:
Channel selection dictates regulatory exposure and customer acquisition economics. Pharmacy networks impose pharmacist consultation requirements that slow velocity but protect margin, while supermarket penetration sacrifices premium positioning for volume scale.
- Supermarkets:High-velocity daily hygiene SKUs concentrate here, with centralized procurement compressing supplier margins across Central European retail chains.
- Pharmacies:Therapeutic and clinician-endorsed formulations command premium positioning. Paris and Brussels pharmacy networks are rebuilding dedicated oral care sections with trained staff.
- Online Stores:Subscription models and direct-to-consumer whitening kits bypass traditional wholesale markups. Nordic markets show highest e-commerce penetration for mechanical cleaning devices.
- Specialty Shops:Organic and natural positioning variants cluster here, with CSRD-aligned sustainability claims driving procurement preference in Stockholm and Copenhagen.
Pharmacies dominate therapeutic value capture. Online stores are climbing the fastest as subscription mechanics reshape replenishment patterns.
End User:
User segmentation maps to life-stage dental risk profiles and reimbursement eligibility. Adult preventive regimens sustain baseline volume, while professional-grade demand concentrates in clinic-adjacent channels.
- Adults:Baseline preventive and cosmetic demand sustains mass-market production runs. German consumers show highest per-capita therapeutic toothpaste adoption.
- Children:Flavor-engineered formulations with controlled fluoride dosing address safety thresholds. French and Belgian reimbursement alignment supports pediatric preventive protocols.
- Elderly:Dry mouth and periodontal care formulations target aging demographics in Italy and Spain. Pharmacy consultation drives product selection for this segment.
- Professionals:Dental hygienists and clinicians specify clinical-grade products for patient home care regimens.
Adults dominate installed base. Elderly users are where expansion concentrates as demographic aging accelerates across Southern Europe.
Application:
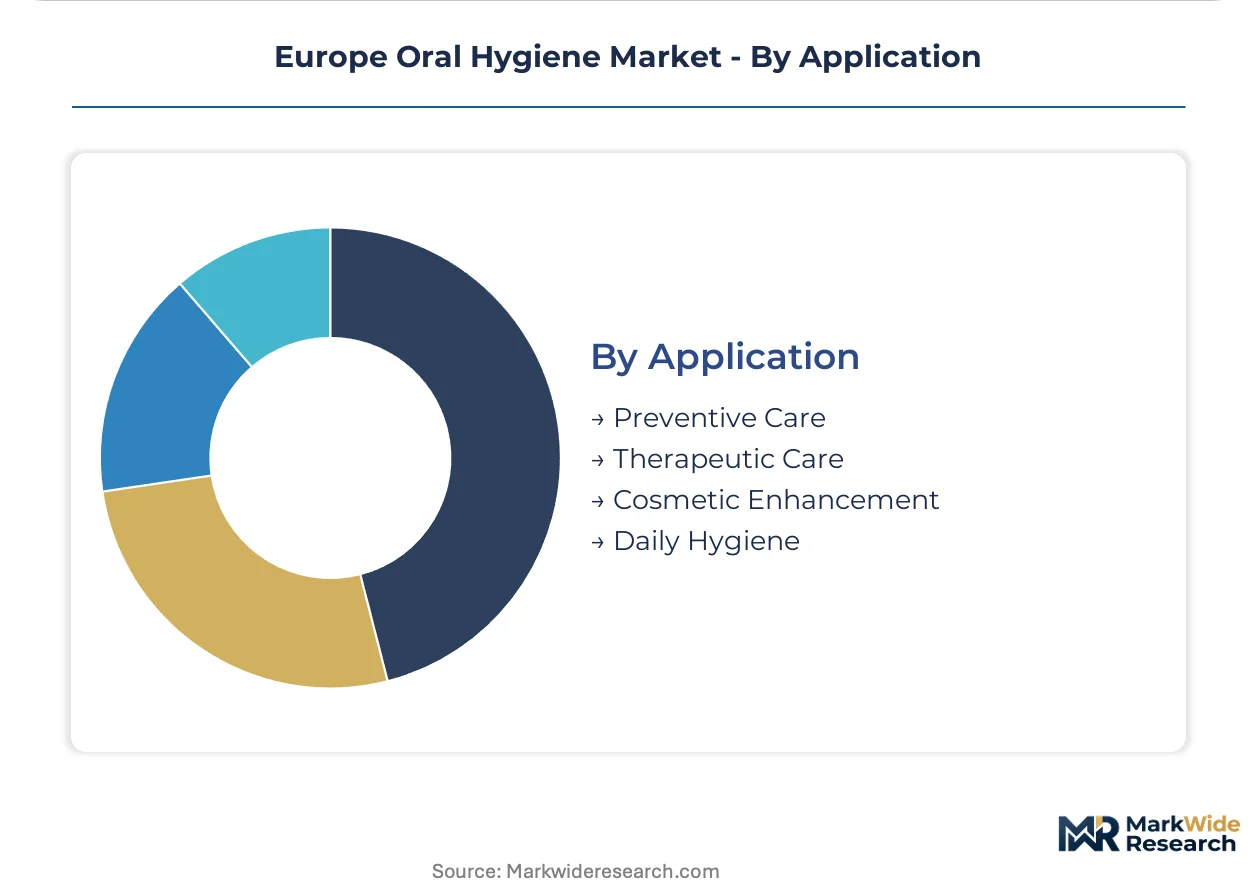
Application framing determines R&D allocation and clinical validation requirements. Preventive protocols enjoy institutional endorsement, while cosmetic positioning faces higher marketing spend intensity.
- Preventive Care:Fluoride and enamel repair formulations with clinical validation dominate German and French dental clinic recommendations. EMA guidelines on active substance safety govern formulation thresholds.
- Therapeutic Care:Chlorhexidine and enzymatic systems target periodontal disease management. Swiss and German contract laboratories face extended queue times for stability testing.
- Cosmetic Enhancement:Peroxide whitening and aesthetic positioning commands premium shelf space in Spanish and Italian retail. CSRD disclosure rules redirect investment toward biodegradable packaging.
- Daily Hygiene:Standard fluoride toothpaste and basic mouthwash sustain volume manufacturing.
Daily hygiene dominates installed base. Therapeutic care is gaining share fastest as preventive dentistry protocols expand clinic influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor underwrites Germany's distribution dominance across European oral care supply chains. This rail-waterway nexus connects manufacturing clusters in Basel and Frankfurt to Rotterdam port terminals, enabling 48-hour replenishment cycles for pharmacy and retail networks spanning twelve countries.
Germany
Therapeutic toothpaste adoption concentrates in Munich and Hamburg pharmacy networks where clinician endorsement programs drive selection. ECHA's REACH enforcement mandates full chemical disclosure for imported active ingredient bundles. The Rhine-Main manufacturing belt hosts formulation facilities supplying fluoride and enamel-repair products across Central Europe.
France
Reimbursement alignment for periodontal prevention is rebuilding pharmacist influence over therapeutic product selection. ANSM guidelines govern biocidal substance thresholds in mouthwash formulations. Paris pharmacy chains are reconstructing dedicated oral care sections with trained staff consultation protocols.
Italy
Whitening product uptake in Milan and Rome pharmacy networks is migrating aesthetic dentistry into mass retail channels. EU Cosmetics Regulation harmonization reduces formulation fragmentation for cross-border distribution. The Lombardy manufacturing cluster produces peroxide-based home treatment systems for Southern European markets.
Spain
Home whitening kit demand concentrates in Madrid and Barcelona retail networks where pharmacy chains dedicate premium shelf space to aesthetic positioning. EMA biocidal substance reviews create formulation uncertainty for hydrogen peroxide concentrations. The Catalan packaging corridor supplies biodegradable tube innovations to CSRD-aligned brand owners.
Poland
Underdeveloped professional oral care channels in Warsaw and Krakow present first-mover capture opportunities for therapeutic toothpaste positioning. National pharmaceutical regulator frameworks are aligning with EU Cosmetics Regulation safety thresholds. The Silesian industrial zone hosts contract manufacturing facilities serving Eastern European pharmacy expansion.
Europe Oral Hygiene Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in active ingredient and packaging supply. The vendor base concentrates around consumer goods conglomerates with established pharmacy distribution infrastructure, supplemented by mid-size therapeutic specialists with clinician endorsement relationships. Three archetypes dominate: scale-driven mass-market suppliers, premium therapeutic positioning specialists, and sustainability-forward niche operators. Competitive moves center on CSRD-aligned packaging innovation and enzymatic-fluoride formulation convergence.
Among Swiss-based therapeutic specialists, Sunstar Suisse SA occupies a position exemplifying clinician-endorsed periodontal care systems. Colgate-Palmolive Company and Procter & Gamble represent the scale-driven platform tier, anchoring shelf presence across Central European retail chains through established distribution infrastructure. These three entities collectively illustrate the competitive tension between mass-market velocity and premium therapeutic positioning.
| Leading Market Players |
|---|
| Haleon PLC |
| Church & Dwight Co., Inc. |
| Procter & Gamble |
| Henkel AG & Co. KGaA |
| Sunstar Suisse SA |
| Colgate-Palmolive Company |
| GlaxoSmithKline PLC |
| Johnson & Johnson Consumer Inc |
| Unilever |
| Others |
Cost & Logistics Intelligence
Overcapacity in Southeast Asian oleochemical processing is compressing surfactant input costs for European oral care manufacturers while elevating pricing leverage for buyers of plant-derived alternatives. This utilization dynamic rewards formulation houses with backward integration into active ingredient supply while squeezing margins for import-dependent competitors facing ECHA REACH disclosure mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs European oral care procurement, with pharmacist-endorsed therapeutic variants commanding 40-60% premiums over supermarket daily hygiene SKUs. Price differentiation rests on certification grade—EMA-compliant biocidal formulations versus standard cosmetic-grade products—and volume scale through centralized retail chain procurement. Cost compression in the standard tier is intensifying because German pharmacy networks are consolidating supplier rosters. Price sensitivity concentrates among supermarket buyers seeking daily hygiene SKUs, while pharmacy channels show elasticity for clinician-recommended periodontal systems.
Supply Chain Analysis
Contract manufacturing capacity concentrates among Swiss and German formulation houses, with Silesian industrial zone facilities serving Eastern European expansion. Geographic supply draws from German fluoride compound production, Italian peroxide processing clusters, and Southeast Asian palm-derived surfactant feedstocks. Raw material dependencies center on chlorhexidine API supply, hydrogen peroxide stabilization chemistry, and biodegradable packaging resins. Single-source vulnerability sits with REACH-mandated chemical disclosure systems that must interface with legacy batch tracking infrastructure. Distribution runs through the Rhine-Alpine freight corridor connecting Basel and Frankfurt manufacturing to Rotterdam port terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe oral hygiene market is recovering from formulation uncertainty cycles driven by EMA biocidal substance reauthorization timelines. This regulatory cyclicality creates predictable windows for repositioning before review outcomes stabilize.
For Market Incumbents: Entrench pharmacy channel control through clinician endorsement programs for enzymatic-fluoride hybrid formulations. Expand captive production of active ingredient bundles in the Rhine-Main manufacturing belt to deflect REACH compliance cost pressure from import dependencies. Deepen backward integration into biodegradable tube manufacturing to capture CSRD-aligned procurement preference.
For New Entrants and Emerging Players: Pursue white-space capture in Warsaw and Krakow pharmacy networks where therapeutic toothpaste positioning remains underdeveloped. Target elderly periodontal care segments in Italy and Spain where demographic aging accelerates demand for dry mouth formulations. Lead with subscription direct-to-consumer models for whitening kits to bypass entrenched retail markups.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic-fluoride specialists with clinician endorsement relationships. Long-term viability favors mid-size therapeutic players with validated stability testing capacity and pharmacy distribution infrastructure. Monitor EMA biocidal reauthorization outcomes as inflection signal for formulation obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic-Fluoride Formulation Launch | Hybrid bioactive systems command premium positioning in German pharmacy channels. |
| Biodegradable Packaging Transition | CSRD-aligned tube certifications drive procurement preference in Stockholm and Copenhagen. |
| Eastern European Pharmacy Expansion | Warsaw and Bucharest networks offer first-mover therapeutic positioning opportunities. |
| Backward Integration into Surfactants | Captive oleochemical supply deflects Southeast Asian input cost volatility. |
| Clinician Endorsement Program Buildout | Paris and Brussels pharmacy chains are rebuilding trained staff consultation protocols. |
Research Approach
Desk research of EMA biocidal substance filings, EU Cosmetics Regulation guidance documents, and CSRD sustainability disclosure frameworks preceded structured interviews with brand managers at consumer goods conglomerates, pharmacy chain category buyers, and formulation scientists at contract manufacturing facilities. Primary fieldwork with dental clinic procurement coordinators and retail distribution heads was cross-validated against secondary trade data from European customs records and pharmaceutical regulator enforcement reports. Bottom-up volume modeling was triangulated with top-down value estimates across the analysis window.
Assumptions held fixed include EMA reauthorization timelines proceeding as scheduled and REACH disclosure requirements maintaining current stringency. Variables tested encompass surfactant input cost trajectories, pharmacy channel share recovery rates, and whitening product aesthetic dentistry penetration. Segmentation dimensions modeled include product type, distribution channel, end user life stage, and application framing. CAGRs were derived from regression analysis of historical replenishment velocity and projected channel shift dynamics. Industry-specific inputs incorporated clinician endorsement program adoption curves and stability testing queue times at Swiss and German contract laboratories.
Sensitivities concentrate around EMA biocidal review outcomes, REACH enforcement intensity escalation, and Southeast Asian oleochemical supply disruptions. Forecasts reflect documented assumptions regarding regulatory trajectory and channel economics. Quarterly review of pharmacy procurement consolidation patterns and EMA substance review announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Thrush Market
Oral Care
Tongue Cleaner Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Oral Mucositis Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Us Oral Care Market
Oral Care
Mouthwash Market
Oral Care
Canker Sores Treatment Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Children's Oral Care Market
Oral Care
Kids Toothpaste Market
Oral Care
LED Oral Care Kits Market
Oral Care
Oral Antiseptics Market
Oral Care
United States Oral Hygiene Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Baby Oral Care Market