
 Oral Thrush Market | 2026-2036
Oral Thrush Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Thrush Market Outlook
Pharmaceutical manufacturing in India is recalibrating its oral antifungal output to serve contract supply agreements across North America and Europe. Pfizer Inc. leverages its established azole chemistry platforms to sustain bulk active pharmaceutical ingredient production for oral thrush therapies. GlaxoSmithKline plc anchors its competitive position through specialized distribution networks targeting hospital formularies in developed markets. Teva Pharmaceutical Industries Ltd. competes aggressively on cost structure across generic oral antifungal segments.
Oral thrush, medically termed oropharyngeal candidiasis, constitutes a mucosal infection caused by Candida species colonization; standard treatment relies on polyenes such as nystatin suspension or azole-class agents like fluconazole, typically administered in 100-200 mg daily dosing regimens for seven to fourteen days. Topical antifungals dominate current prescription volumes due to established safety profiles in pediatric and geriatric populations, while novel drug delivery systems represent the fastest-expanding technology category as manufacturers invest in mucoadhesive films and extended-release buccal tablets to improve patient compliance. The elderly age segment commands disproportionate clinical attention given polypharmacy interactions and recurrent infection patterns in this demographic.
The FDA governs new drug applications and bioequivalence standards for oral antifungal generics, while the EMA oversees centralized marketing authorization and pharmacovigilance across European member states, and the WHO maintains essential medicines list criteria that influence national procurement decisions in lower-income markets. Regulatory stringency around generic substitution and antimicrobial stewardship programs directly constrains prescribing flexibility and shapes manufacturer portfolio priorities. Stakeholders must monitor evolving resistance surveillance data and reimbursement policy shifts to align R&D investment with clinically differentiated product profiles.
Market Dynamics
FDA bioequivalence standards for generic antifungals are compressing approval timelines and forcing manufacturers toward differentiated delivery formats rather than commodity substitution. This regulatory pressure is concentrating investment in mucoadhesive and extended-release technologies that bypass traditional bioequivalence pathways.
Growth Catalysts
- Hospital formulary expansion:Rising immunocompromised patient volumes in oncology and transplant units are expanding procurement of systemic azoles for prophylactic use against oropharyngeal candidiasis.
- EMA pharmacovigilance harmonization:Streamlined adverse event reporting across European member states is accelerating post-market surveillance and building prescriber confidence in generic antifungal switching.
- Pediatric formulation innovation:Palatable nystatin suspensions and orodispersible fluconazole tablets are automating compliance in neonatal and geriatric populations previously resistant to topical therapy.
Market Restraints
- Active pharmaceutical ingredient concentration:Bulk azole production concentrates in Indian and Chinese contract manufacturers, creating supply vulnerability during export license delays or geopolitical friction.
- Antimicrobial stewardship constraints:Hospital infection control committees in the United States and Germany are restricting empiric antifungal prescribing through pre-authorization protocols that lengthen treatment initiation.
- Azole resistance surveillance gaps:Candida glabrata fluconazole resistance exceeds detection thresholds in long-term care facilities, limiting first-line therapeutic options and forcing escalation to polyene therapy with higher toxicity profiles.
Strategic Opportunities
- Buccal film delivery systems:Mucoadhesive polymer technologies that bypass hepatic first-pass metabolism offer bioavailability advantages for patients with gastrointestinal absorption impairment.
- Home infusion channel development:Specialty pharmacies are building clinical support infrastructure for outpatient parenteral antifungal therapy, displacing hospital-based treatment for stable oropharyngeal candidiasis cases.
- PLI scheme alignment:Indian manufacturers qualifying under the Production Linked Incentive scheme for active pharmaceutical ingredients are securing cost advantages for export contract supply to North American and European markets.
Industry Challenges
- Bioanalytical method transfer complexity:Contract research organizations face validation failures when moving antifungal bioequivalence studies between laboratories due to Candida strain variability in reference standards.
- Reimbursement code fragmentation:Topical versus systemic oral thrush therapies map to distinct billing categories across Medicare Part D and commercial formularies, complicating patient access navigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Thrush Market |
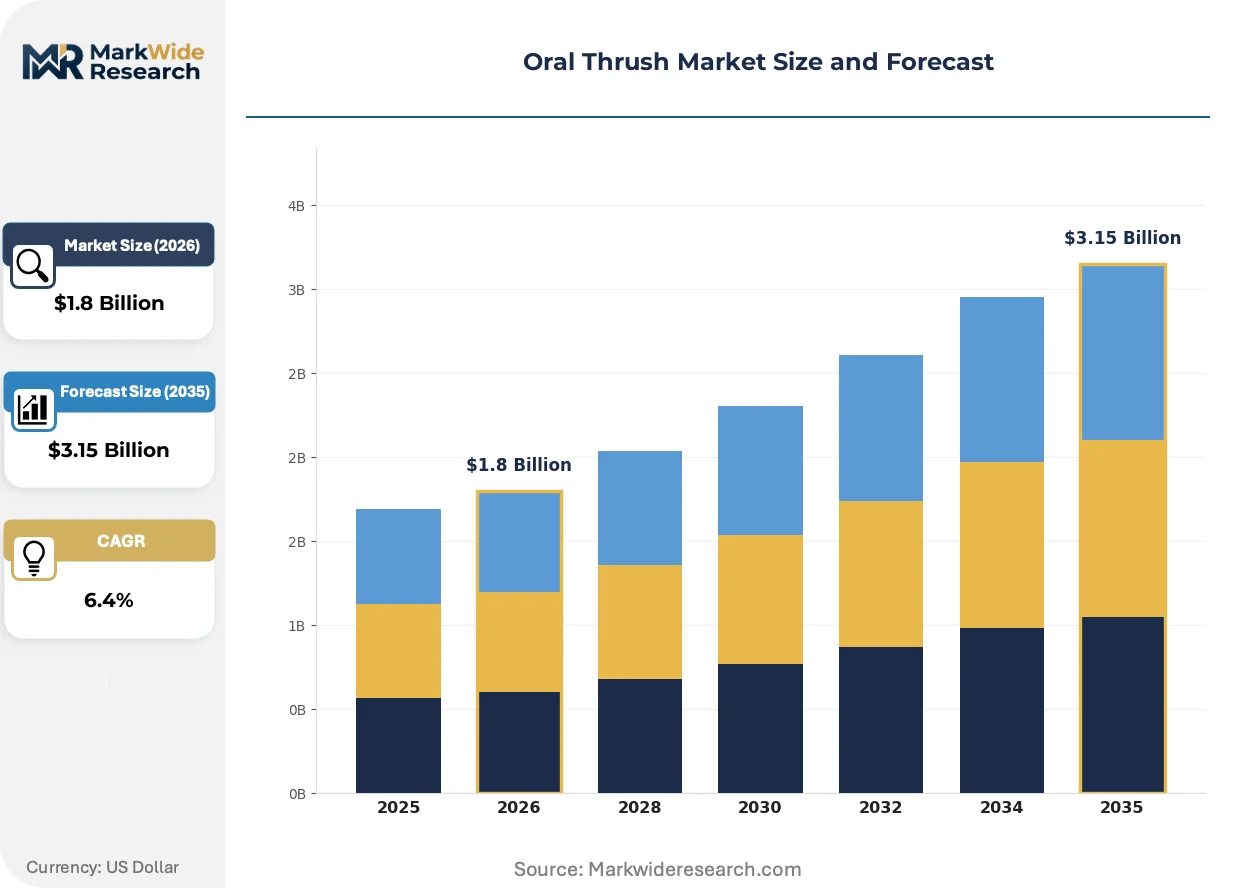
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Medications, Lozenges, Mouth Rinses Technology: Conventional Treatments, Novel Drug Delivery, Herbal Remedies, Combination Therapy End User: Hospitals, Pharmacies, Home Care, Clinics Age Group: Infants, Children, Adults, Elderly |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Merck & Co., Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Bayer AG, Astellas Pharma Inc., Johnson & Johnson Services, Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Thrush Market Strategic Shifts
Antifungal delivery technology is pivoting from conventional suspensions toward patient-centric formats that address compliance failures in polypharmacy populations. Regulatory science and manufacturing automation are converging to reshape competitive positioning.
Extended-release buccal tablets incorporating hydroxypropyl methylcellulose matrices are automating plasma level maintenance for immunocompromised patients requiring prolonged prophylaxis. Hospital formularies in the United States are adopting these formats for discharge planning. The technology is automating the shift from inpatient observation to outpatient self-administration.
REACH authorization requirements for residual solvents in polymer excipients are forcing European manufacturers toward aqueous coating processes. Compliance costs are compressing mid-tier generic portfolios. Pediatric liquid formulations face the steepest reformulation burden under the updated ECHA guidance.
Specialty pharmacy distribution is displacing traditional retail channels for high-cost systemic antifungal therapies. Payers are mandating prior authorization through limited distribution networks to manage utilization. This channel consolidation is most pronounced in Medicare Advantage plans covering long-term care transitions.
Oral Thrush Market Segmentation
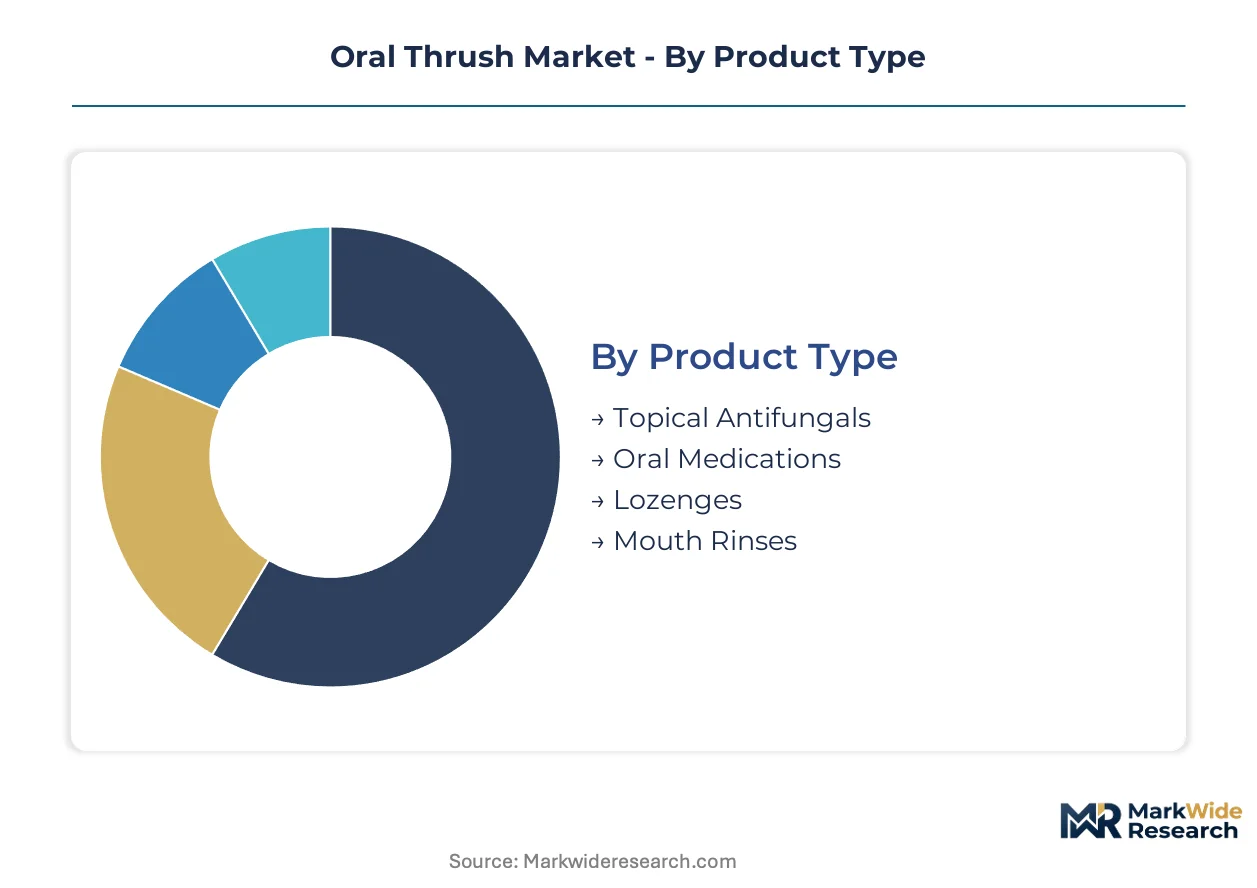
Oral thrush treatment selection hinges on patient physiology, infection severity, and care setting economics. Prescribers weigh bioavailability against toxicity profiles while procurement teams negotiate formulary placement across divergent reimbursement codes.
Product Type:
Hospital procurement committees prioritize acquisition cost against length-of-stay reduction when selecting among delivery formats.
- Topical Antifungals:Nystatin suspensions and clotrimazole troches dominate neonatal and geriatric prescribing due to minimal systemic absorption. Demand concentrates in long-term care facilities across the United States where polypharmacy interactions complicate oral systemic therapy.
- Oral Medications:Fluconazole tablets anchor prophylactic protocols in oncology units, with 100-200 mg daily regimens standard for immunocompromised patients. Volume clusters in Medicare Advantage plans covering hospital-to-home transitions where compliance monitoring justifies systemic over topical selection.
- Lozenges:Mucoadhesive polymer formulations improve retention time on oropharyngeal mucosa.
- Mouth Rinses:Chlorhexidine-based adjuncts address mixed bacterial-fungal colonization in denture wearers.
Volume sits with topical antifungals; growth tilts toward oral medications.
Technology:
Manufacturing investment flows toward formats that circumvent FDA bioequivalence bottlenecks for commodity generics.
- Conventional Treatments:Polyene and azole suspensions manufactured through established fermentation and chemical synthesis routes. Cost pressure from Indian contract suppliers compresses margins for European and North American finished dose producers.
- Novel Drug Delivery:Extended-release buccal tablets employing hydroxypropyl methylcellulose matrices bypass hepatic first-pass metabolism. Hospital discharge planners in Germany and the United States favor these for outpatient prophylaxis in transplant recipients.
- Herbal Remedies:Propolis and tea tree oil formulations occupy pharmacy shelves in markets with permissive dietary supplement regulation.
- Combination Therapy:Antifungal-antiseptic pairings target refractory cases in HIV clinics.
Conventional treatments capture current volume; novel delivery systems are climbing the fastest.
End User:
Channel economics determine whether patients receive observation-level care or self-administered home therapy.
- Hospitals:Oncology and transplant units drive systemic azole consumption through prophylactic protocols. Stewardship committees in German academic medical centers enforce pre-authorization requirements that lengthen initiation timelines.
- Pharmacies:Retail and specialty channels split along reimbursement complexity, with limited distribution networks handling high-cost parenteral antifungals.
- Home Care:Infusion services displace hospital observation for stable oropharyngeal candidiasis.
- Clinics:Outpatient settings handle uncomplicated cases with single-dose fluconazole regimens.
Hospitals anchor procurement volume; home care channels are gaining share fastest.
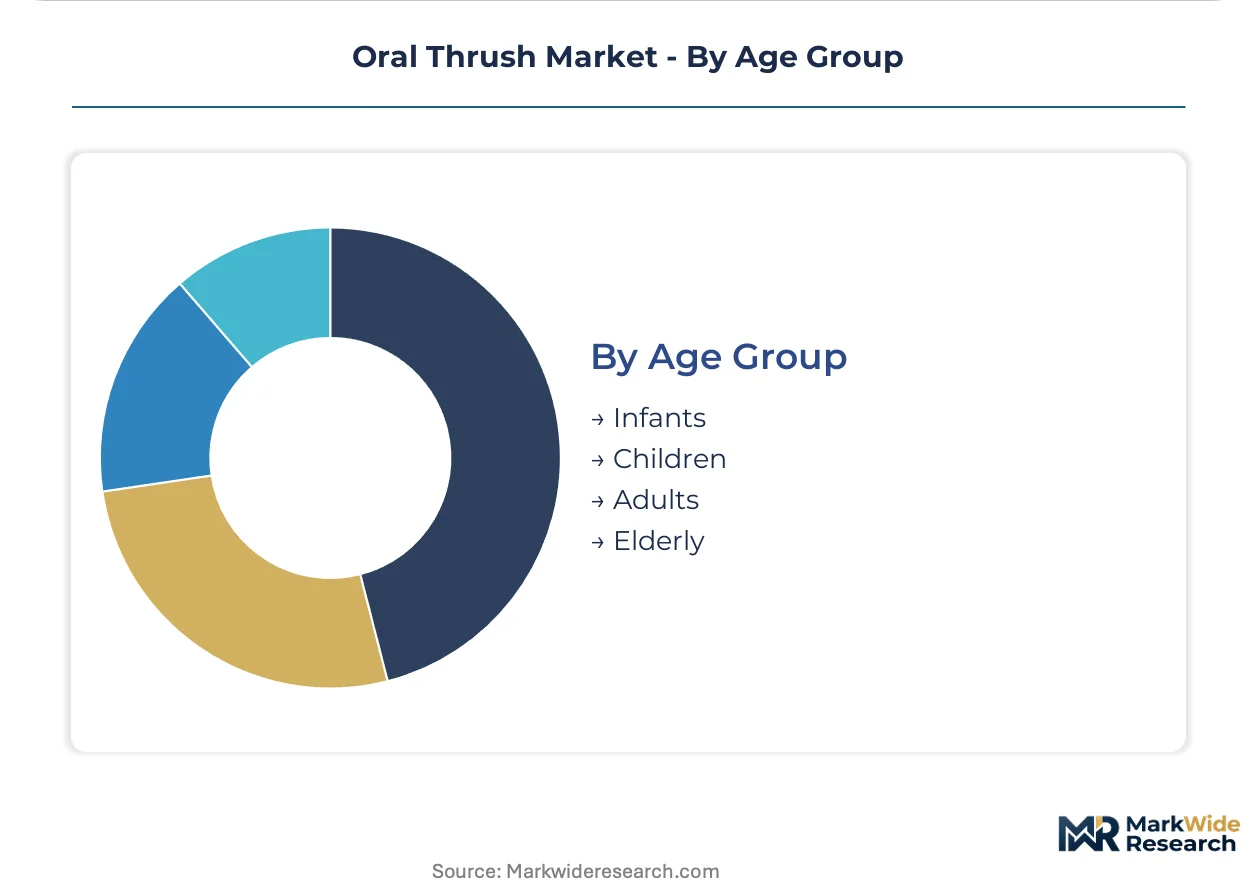
Age Group:
Physiologic vulnerability and medication tolerance shape dosing strategy across life stages.
- Infants:Nystatin suspension remains first-line due to established safety in neonatal pharmacokinetic studies. Prescription volume concentrates in Medicaid programs covering nursery discharge.
- Elderly:Recurrent infection patterns and xerostomia from polypharmacy sustain chronic prophylaxis demand. Long-term care facilities in the United States generate disproportionate prescription volume for palatable topical alternatives.
- Children:Orodispersible tablet development targets compliance failures in school-age populations.
- Adults:Immunocompetent patients typically receive short-course topical therapy.
Volume sits with the elderly; infants represent the steepest expansion trajectory for formulation innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad and Ahmedabad anchor bulk azole active pharmaceutical ingredient production for oral antifungal therapies distributed across North American and European hospital networks. Contract manufacturing clusters in these cities supply fermentation-derived polyenes and chemically synthesized azoles under long-term supply agreements with multinational pharmaceutical firms.
United States
Medicare Advantage enrollment growth and diabetes prevalence sustain prescription volumes for topical nystatin and systemic fluconazole in long-term care facilities. The FDA maintains tightened bioequivalence standards for generic antifungal approvals under 21 CFR 320. The Philadelphia-Camden corridor concentrates specialty pharmacy distribution infrastructure for hospital-to-home infusion services.
Germany
Academic medical center stewardship committees enforce pre-authorization protocols for empiric antifungal prescribing in oncology and transplant units. The EMA pharmacovigilance framework harmonizes adverse event reporting across member states under EU Regulation 1235/2010. The Rhine-Main cluster around Frankfurt hosts centralized hospital procurement consortia negotiating azole formulary contracts.
India
Domestic contract manufacturers qualify under the Production Linked Incentive scheme for active pharmaceutical ingredient production to serve export demand. The CDSCO regulates finished dose and bulk drug manufacturing facility inspections under Schedule M of the Drugs and Cosmetics Rules. Hyderabad's Genome Valley fermentation infrastructure supplies nystatin bulk to North American generic finished dose producers.
United Kingdom
NHS England antimicrobial stewardship programs restrict community prescribing of systemic antifungals to microbiology-confirmed cases. The MHRA operates under retained EU law for marketing authorization while implementing independent pharmacovigilance procedures post-Brexit. The Manchester-Liverpool corridor concentrates hospital pharmacy procurement for northern England NHS trusts.
Japan
Aging demographics and polypharmacy in elderly populations sustain demand for palatable topical formulations with minimal drug interaction profiles. The PMDA reviews new drug applications under the Pharmaceuticals and Medical Devices Act with accelerated pathways for pediatric formulations. The Kansai region around Osaka hosts fermentation-based bulk antifungal production for domestic and select Asian export markets.
Oral Thrush Market Competitive Environment
Global majors compete with regional champions across formulation technology and distribution reach in the oral thrush therapeutic space. The market structure tiers into research-intensive innovators, cost-optimized generic manufacturers, and specialized delivery technology developers. Three strategic archetypes dominate: bulk active pharmaceutical ingredient suppliers with backward integration into fermentation, finished dose specialists with hospital formulary relationships, and novel delivery system innovators patenting mucoadhesive polymer platforms. Competitive moves center on geographic expansion through contract manufacturing partnerships and portfolio diversification into pediatric-compliant formats.
Among research-intensive pharmaceutical conglomerates, Pfizer Inc. and GlaxoSmithKline plc occupy positions exemplifying the innovator archetype with established azole chemistry platforms and hospital formulary anchoring. Teva Pharmaceutical Industries Ltd. represents the cost-optimized generic tier competing on manufacturing scale and bioequivalence study throughput. These three entities collectively illustrate the competitive tension between proprietary delivery technology investment and commodity substitution economics that shapes manufacturer R&D allocation across the forecast window.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Bayer AG |
| Astellas Pharma Inc. |
| Johnson & Johnson Services, Inc. |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Fermentation-derived nystatin bulk costs from Hyderabad contract manufacturers cascade through three pricing tiers: hospital procurement consortia command volume discounts on unbundled active pharmaceutical ingredient supply, while retail pharmacies absorb higher per-unit rates for finished dose formulations with cold-chain logistics bundled into shelf price.
Pricing Analysis
Service bundling separates hospital formulary contracts from retail pharmacy transactions. Three-tier pricing structure across premium, standard, and economy levels tracks FDA bioequivalence certification status and pediatric formulation complexity. Price differentiation hinges on azole active pharmaceutical ingredient purity grade and CDSCO manufacturing facility audit tier. Cost compression in generic fluconazole tablets is intensifying because Indian PLI scheme recipients are expanding fermentation capacity. Long-term care facilities exhibit highest price sensitivity; transplant center procurement committees show lowest sensitivity due to bundled stewardship protocol pricing.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for North American hospital networks. Bulk azole production concentrates in India, China, and the United States; fermentation infrastructure draws from corn-derived dextrose, pharmaceutical-grade solvents, and polymer excipients. Single-source vulnerability sits with Hyderabad's Genome Valley nystatin fermentation cluster. Distribution runs through specialty pharmacy limited networks for systemic antifungals and retail wholesale for topical suspensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral thrush market has become a vertical-integration race as manufacturers pursue captive control over azole fermentation capacity to defend margin position against Indian contract suppliers.
For Market Incumbents: Lock in hospital formulary anchoring through extended-release buccal tablet exclusivity agreements before FDA bioequivalence pathways commoditize novel delivery formats. Add fermentation capacity in Ahmedabad to reduce dependence on Hyderabad contract supply. Certification investment in EMA centralized marketing authorization defends against emerging Indian finished dose exporters. For New Entrants and Emerging Players: FDA's tightened bioequivalence standards for generic antifungals in the United States opens a window for mucoadhesive polymer platform specialists to bypass traditional approval bottlenecks. Target pediatric orodispersible tablet development where compliance failures create unmet need. Pursue contract research organization partnerships for bioanalytical method validation as the go-to-market angle. For Investors and Strategic Acquirers: CDSCO Schedule M manufacturing facility inspection backlog is the leading indicator that Indian active pharmaceutical ingredient consolidation will accelerate. Five-to-ten year viability favors backward-integrated finished dose producers with captive fermentation supply. Acquisition target archetype: mid-tier generic manufacturers with pending FDA bioequivalence submissions and established hospital formulary relationships. Watch EMA pharmacovigilance harmonization implementation speed as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mucoadhesive Polymer Platform Development | Bypasses FDA bioequivalence bottlenecks for generic azole substitutions in hospital discharge planning. |
| Backward Integration into Fermentation Capacity | Captures PLI scheme cost advantages for nystatin bulk supply to North American generic producers. |
| Pediatric Formulation Innovation | Addresses compliance failures in Medicaid nursery discharge protocols with palatable nystatin suspensions. |
| Specialty Pharmacy Limited Distribution | Secures prior authorization control for high-cost systemic antifungal therapy in Medicare Advantage plans. |
| EMA Centralized Marketing Authorization | Unlocks streamlined adverse event reporting across German and UK hospital procurement consortia. |
Study Parameters
Independent corroboration across hospital formulary directors, CDSCO regulatory affairs leads, and Indian contract manufacturing executives underwrites the qualitative findings. Primary interviews with oncology unit stewardship committee members, specialty pharmacy procurement managers, and fermentation plant engineers in Hyderabad and Ahmedabad were validated against secondary sources including FDA 21 CFR 320 bioequivalence filings, EMA centralized marketing authorization submissions, and CMS Medicare Part D formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to cross-check segment-level outputs.
Comparable-period anchoring to historical azole consumption patterns in immunocompromised patient populations established the forecast baseline across the projection horizon. Segmentation dimensions modeled include delivery format, technology category, end-user channel, and age-group physiology. CAGRs were derived from regression analysis of hospital procurement volume trends and immunocompromised patient population growth curves. Industry-specific inputs incorporated antimicrobial stewardship protocol adoption rates and novel drug delivery system patent expiration timelines.
The model assumes a particular technology adoption path; alternative pathways for extended-release buccal tablets would alter the outlook if mucoadhesive polymer bioavailability advantages fail to demonstrate clinical differentiation in transplant recipient populations. Forecasts reflect assumptions regarding FDA bioequivalence standard stability and EMA pharmacovigilance framework continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Global Oral Hygiene Market
Oral Care
Oral Care Market
Oral Care
Tongue Cleaner Market
Oral Care
Adult Oral Care Products Market
Oral Care
Oral Mucositis Market
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Dry Mouth Relief Market
Oral Care
Herbal Toothpaste Market
Oral Care
South America Oral Care Market
Oral Care
Baby Teeth Care Products Market
Oral Care
LED Oral Care Kits Market
Oral Care
Global Oral Care Products Market
Oral Care
Mouthwash Market
Oral Care
Xerostomia Treatment Market
Oral Care
Us Oral Care Market
Oral Care
Baby Oral Care Market