
 Tongue Cleaner Market | 2026-2036
Tongue Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Tongue Cleaner Market Analytics
Buyer concentration in the dental channel is pivoting as independent oral care clinics multiply and diversify procurement beyond traditional retail pharmacy networks. Colgate-Palmolive Company leverages its established retail shelf presence to maintain consumer visibility, while Procter & Gamble anchors premium positioning through integrated oral care system marketing. Dr. Tung's specializes in copper and stainless steel designs that appeal to wellness-oriented consumers seeking alternatives to plastic.
A tongue cleaner is a handheld oral hygiene instrument, typically measuring 15–20 centimeters in length, designed with a scraping edge of plastic, metal, or natural material to mechanically remove bacterial biofilm and debris from the dorsal tongue surface. Manual plastic variants dominate unit volume due to low cost and mass retail accessibility, while stainless steel and copper segments command margin pools through durability claims and Ayurvedic wellness positioning. Electric and sonic technologies occupy nascent but expanding niches as consumers adopt powered oral care routines.
The US FDA regulates tongue cleaners as Class I medical devices with general controls, while the EU MDR requires CE marking and post-market surveillance for instruments sold to dental professionals. India's BIS standards and China's NMPA registration pathways shape market access timelines for imported products. Stakeholders must monitor regulatory divergence between consumer-grade and professional-grade classifications as classification decisions determine compliance costs and channel eligibility.
Market Dynamics
Dental clinic procurement protocols are consolidating purchasing authority into larger oral care networks, compressing vendor access and forcing tongue cleaner suppliers to demonstrate clinical efficacy data to maintain shelf placement.
Growth Catalysts
- Ayurvedic wellness positioning:Copper tongue cleaners gain traction among consumers seeking metal alternatives to plastic, with Ayurvedic practitioners in India and Germany recommending daily scraping rituals.
- EU MDR compliance pathways:Post-market surveillance requirements for professional-grade instruments are elevating quality benchmarks and filtering low-grade imports from European dental channels.
- Preventive hygiene protocols:Oral care clinics across North America are embedding tongue cleaning into standard patient education, expanding institutional volume beyond retail pharmacy networks.
Market Restraints
- Copper price volatility:Raw material fluctuations for antimicrobial metal variants compress margins for premium-positioned manufacturers dependent on Ayurvedic wellness claims.
- Plastic waste scrutiny:Single-use polymer tongue cleaners face mounting environmental liability as municipal waste regulations in Germany and France tighten extended producer responsibility frameworks.
- Low-cost Asian manufacturing concentration:Supply chain dependence on concentrated production zones creates vulnerability to logistics disruptions and tariff volatility affecting import timelines.
Strategic Opportunities
- Subscription oral care bundles:Direct-to-consumer channels enable recurring revenue models integrating tongue cleaners with toothpaste and floss systems, bypassing retail margin compression.
- Sonic technology convergence:Powered tongue cleaning attachments for existing electric toothbrush bases address consumer demand for consolidated bathroom counter devices.
- German dental association endorsements:Professional society recommendations create regulatory tailwind for clinically validated instruments seeking differentiation in saturated European markets.
Industry Challenges
- Biocompatibility testing timelines:FDA Class I device clearance and EU MDR technical documentation requirements extend product launch cycles for novel materials.
- Cross-border labeling harmonization:Divergent national requirements for antimicrobial claims and material safety disclosures fragment packaging runs and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tongue Cleaner Market |
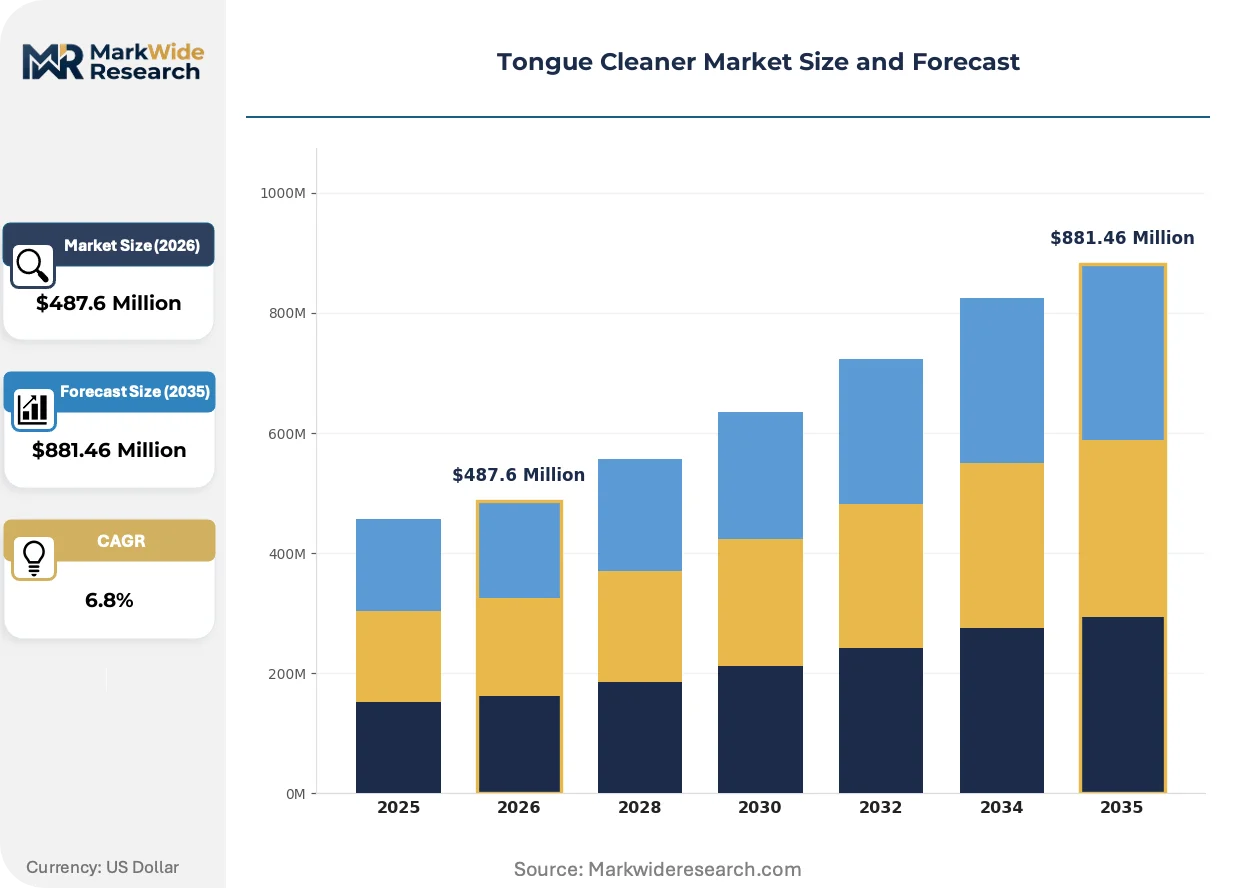
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Stainless Steel, Copper, Bamboo Technology: Manual, Electric, Sonic, Ultrasonic End User: Consumers, Dentists, Clinics, Hospitals Distribution Channel: Online, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Procter & Gamble, Johnson & Johnson, Colgate-Palmolive Company, DenTek Oral Care, Orabrush, Dr. Tung's, Church & Dwight Co., Inc., Dr. Fresh LLC, TePe Munhygienprodukter AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tongue Cleaner Market Evolving Landscape
Material science advances and regulatory convergence are compressing product lifecycles while elevating performance thresholds for market access. Three forces dominate the current innovation landscape.
Copper alloy formulations are decentralizing manufacturing geography by enabling smaller-scale foundries to produce antimicrobial tongue cleaners without pharmaceutical-grade cleanroom infrastructure. Wellness-oriented consumers in Germany and India are driving demand for these metal variants. Regional metalworking clusters in Gujarat and Saxony are capturing value previously concentrated in injection-molding hubs.
EU MDR post-market surveillance obligations are forcing professional-grade suppliers to maintain clinical evidence registries for instruments sold to dental clinics. Manufacturers must now track adverse events and device longevity across member states. German distributors are demanding ISO 13485 certification as a baseline qualification, filtering out consumer-grade suppliers attempting professional channel entry.
Direct-to-consumer subscription models are compressing traditional retail pharmacy margins by bundling tongue cleaners with recurring oral care shipments. Independent oral care clinics are responding by developing private-label instruments to capture patient lifetime value. This channel rotation is most visible in North American metropolitan markets where dental group purchasing organizations negotiate exclusive supply agreements.
Tongue Cleaner Market Segmentation
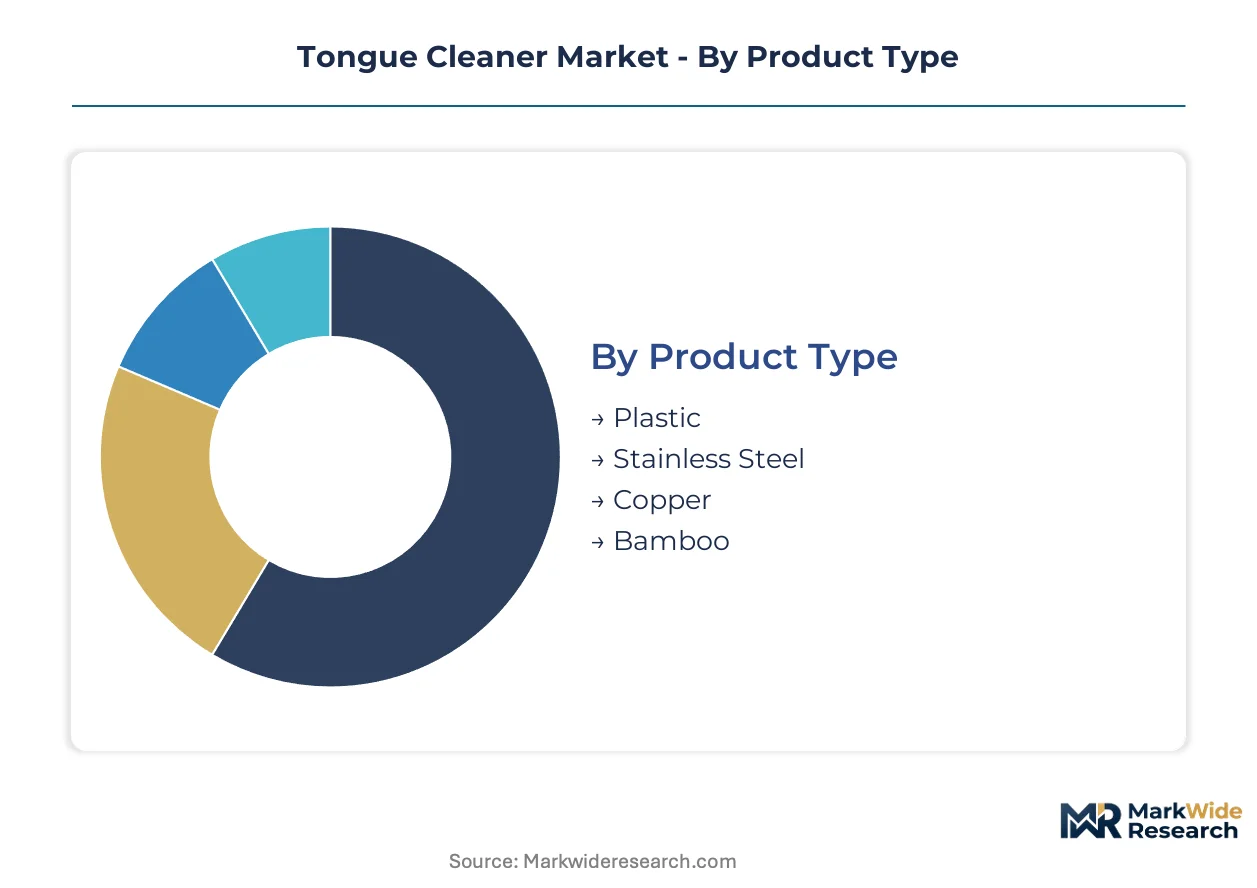
Tongue cleaner procurement splits sharply between mass-market disposable consumption and durable instrument investment, with material choice and power technology determining margin architecture. Segmentation reveals how clinical validation requirements and wellness positioning reshape channel access across retail, professional, and direct-to-consumer pathways.
Product Type:
Volume concentration favors low-cost polymer production, while premium tier capture concentrates in antimicrobial metals commanding wellness premiums.
- Plastic:Polypropylene and polystyrene variants dominate unit throughput through mass retail placement. Procurement concentrates in US supermarket chains and Indian pharmacy networks where price elasticity drives repurchase frequency. Environmental liability is mounting as Germany's extended producer responsibility frameworks tighten single-use polymer disposal requirements.
- Stainless Steel:Surgical-grade 304 and 316L alloys deliver durability claims validated by ISO 13485-certified manufacturers. Demand clusters in German dental clinics where professional associations recommend metal instruments for autoclave sterilization compatibility. Ayurvedic wellness positioning in India amplifies adoption among consumers seeking alternatives to disposable culture.
- Copper:Antimicrobial alloy formulations appeal to Ayurvedic practitioners in Gujarat and wellness consumers in Saxony. Raw material price volatility compresses margins for premium-positioned suppliers dependent on metal scarcity narratives.
- Bamboo:Biodegradable cellulose fiber construction targets zero-waste consumers in French health stores and Scandinavian online channels. Supply chains source from Vietnamese and Indonesian plantation clusters facing deforestation scrutiny.
Mature deployment sits with Plastic. Newer deployment is concentrated in Copper.
Technology:
Manual instruments anchor current revenue, though powered variants are climbing the fastest as electric toothbrush ecosystem integration accelerates.
- Manual:Hand-scraping designs require no power source, enabling universal accessibility across income tiers. Volume concentrates in Indian and Chinese retail pharmacy networks where battery infrastructure remains inconsistent. Simplicity limits clinical differentiation, forcing margin compression through private-label proliferation.
- Electric:Battery-powered oscillating heads attach to existing toothbrush bases from major oral care system manufacturers. Demand concentrates in North American metropolitan markets where bathroom counter consolidation drives attachment purchases. FDA Class I device clearance pathways extend launch timelines for novel motor configurations.
- Sonic:High-frequency vibration technology transfers from established electric toothbrush platforms. German consumers demonstrate strongest adoption where dental professional endorsement validates premium pricing. CE marking under EU MDR requires post-market surveillance registries for professional-grade distribution.
- Ultrasonic:Piezoelectric transducers generate cavitation effects for biofilm disruption without mechanical scraping. Clinical validation remains sparse, limiting channel access to experimental procurement in South Korean aesthetic dentistry clinics. NMPA registration in China and PMDA pathways in Japan determine Asian market entry sequencing.
Revenue concentration remains with Manual. Steepest expansion trajectory belongs to Sonic.
End User:
Consumer self-purchase dominates unit volume, while institutional procurement concentrates purchasing authority and demands clinical evidence packages.
- Consumers:Individual purchase decisions drive retail pharmacy and online channel throughput. Wellness-oriented segments in Germany and India demonstrate willingness to pay metal premiums. Subscription bundling with toothpaste and floss systems is displacing single-item supermarket purchases in North American direct-to-consumer channels.
- Dentists:Solo and group practice procurement requires ISO 13485 certification and biocompatibility documentation. German dental associations actively recommend tongue cleaning protocols, expanding instrument placement in patient education materials. EU MDR compliance filters low-grade imports from European professional channels.
- Clinics:Oral care clinic networks in North America are consolidating purchasing authority into larger organizations. Group purchasing organizations negotiate exclusive supply agreements, compressing vendor access and forcing efficacy data demonstrations. Preventive hygiene protocol standardization embeds tongue cleaners into routine patient visits.
- Hospitals:Inpatient oral care protocols in Indian and Chinese tertiary facilities specify single-use instruments for infection control. Bulk procurement tenders prioritize cost minimization over durability claims, favoring plastic variants. Central sterilization department capacity constraints limit metal instrument adoption.
Volume leadership sits with Consumers. Margin expansion concentrates in Clinics.
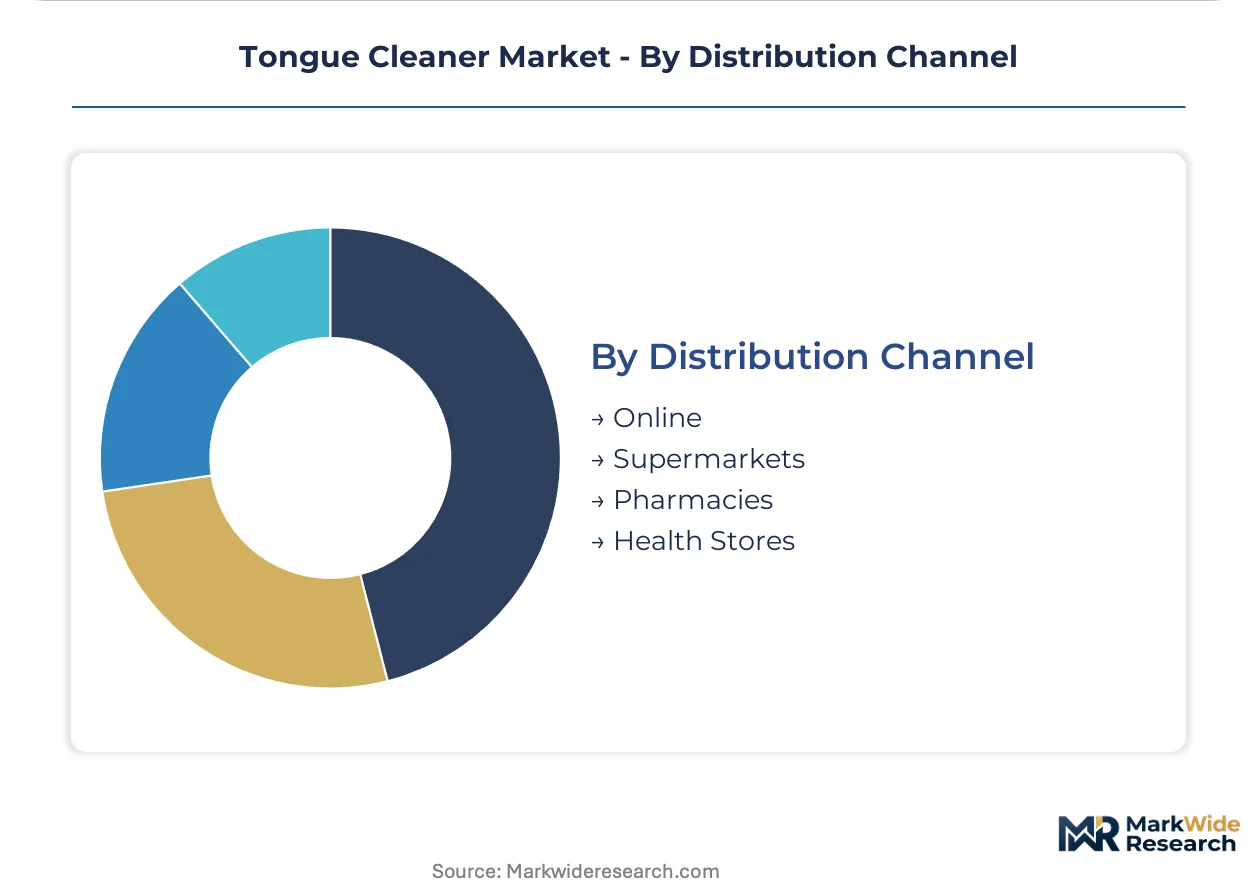
Distribution Channel:
Channel rotation is accelerating as subscription models bypass retail margin compression and professional networks consolidate procurement authority.
- Online:Direct-to-consumer platforms enable recurring revenue bundling and wellness narrative control. Amazon and specialized oral care sites capture metal variant premiums in Germany and India. Private-label penetration is highest here as digital-native brands bypass retail slotting fees.
- Supermarkets:Mass retail placement drives plastic variant volume through impulse purchase visibility. Colgate-Palmolive and Procter & Gamble leverage established shelf presence for consumer-grade positioning. German and French chains face extended producer responsibility compliance costs affecting polymer SKU profitability.
- Pharmacies:Professional recommendation environments support premium pricing for clinically validated instruments. Indian pharmacy chains stock copper variants alongside Ayurvedic product assortments. US retail pharmacy networks are losing share to online subscription models in metropolitan markets.
- Health Stores:Specialty retailers curate wellness-positioned metal and bamboo assortments for zero-waste consumers. French and Scandinavian health store networks demand comprehensive material safety disclosures. Certification requirements fragment packaging runs and inflate compliance overhead for multi-channel suppliers.
Established volume sits with Supermarkets. Channel share is gaining fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental professional associations actively promote tongue cleaning protocols, concentrating European demand for clinically validated instruments in Central Europe. Ayurvedic wellness positioning drives copper variant adoption across South Asian and Germanic consumer segments. North American oral care clinic networks are consolidating procurement authority, filtering vendor access through group purchasing organizations.
United States
FDA Class I medical device classification governs tongue cleaner market entry, requiring general controls for instruments sold through retail and professional channels. Oral care clinic networks in metropolitan markets embed tongue cleaning into preventive hygiene protocols, expanding institutional procurement beyond traditional pharmacy distribution. California and New York health systems pilot subscription bundling models integrating tongue cleaners with recurring oral care shipments.
Germany
Dental professional associations recommend metal tongue cleaners for autoclave sterilization compatibility, driving surgical-grade stainless steel demand. EU MDR post-market surveillance obligations filter low-grade imports from dental channels, elevating ISO 13485 certification requirements. Saxony metalworking clusters capture manufacturing value for copper alloy variants targeting wellness-oriented consumers.
India
Ayurvedic practitioners in Gujarat recommend daily copper scraping rituals, anchoring antimicrobial metal variant demand. BIS standards shape import timelines and quality benchmarks for oral care instruments entering domestic retail pharmacy networks. Maharashtra pharmaceutical distributors stock copper tongue cleaners alongside traditional Ayurvedic product assortments.
China
NMPA registration pathways determine market access timelines for imported tongue cleaning technologies targeting dental professionals. Pearl River Delta injection-molding hubs concentrate mass-market plastic variant production for export to North American retail chains. Shanghai dental equipment distributors navigate dual certification requirements for instruments serving both consumer and clinical segments.
France
Extended producer responsibility frameworks tighten single-use polymer disposal requirements, compressing plastic variant profitability in supermarket channels. ANSM oversight of medical device claims shapes antimicrobial metal positioning in health store networks. Paris-region wellness retailers curate bamboo and copper assortments for zero-waste consumer segments demanding comprehensive material safety disclosures.
Tongue Cleaner Market Competitive Landscape
US-based consumer goods conglomerates anchor one tier; European dental specialists and Asian contract manufacturers hold differentiated positions in professional and private-label supply. The vendor base stratifies across three archetypes: multinational oral care system integrators leveraging retail shelf presence, metal instrument specialists commanding wellness premiums through Ayurvedic positioning, and contract fabricators serving clinic private-label procurement. Competitive moves center on subscription channel expansion and M&A activity targeting direct-to-consumer capabilities.
Among diversified consumer health conglomerates, Procter & Gamble and Colgate-Palmolive occupy positions representing integrated oral care system marketing, while Johnson & Johnson exemplifies professional channel anchoring through clinical endorsement frameworks. Dr. Tung's represents the metal specialist archetype, with copper and stainless steel designs appealing to wellness-oriented consumers seeking alternatives to plastic variants.
| Leading Market Players |
|---|
| Procter & Gamble |
| Johnson & Johnson |
| Colgate-Palmolive Company |
| DenTek Oral Care |
| Orabrush |
| Dr. Tung's |
| Church & Dwight Co., Inc. |
| Dr. Fresh LLC |
| TePe Munhygienprodukter AB |
| Others |
Value Network & Pricing Analysis
Oral care clinic networks in North America operate on contract-based procurement frameworks that compress unit economics for tongue cleaner suppliers while rewarding scale-certified manufacturers with multi-year purchasing agreements.
Pricing Analysis
Volume-mass retail channels anchor economy-tier plastic variants where price elasticity drives repurchase frequency, while margin capture concentrates in antimicrobial metal segments validated by ISO 13485 certification and Ayurvedic wellness positioning. Price differentiation hinges on sterilization-grade material certification and clinical endorsement tier. Pricing pressure stems from extended producer responsibility compliance costs in Germany and France eroding polymer SKU profitability. Hospital procurement tenders in India and China demonstrate highest price sensitivity, whereas German dental clinics accept premium positioning for autoclave-compatible surgical-grade instruments.
Supply Chain Analysis
Domestic-content thresholds in India's BIS standards and China's NMPA registration pathways are reshaping sourcing geography for tongue cleaner manufacturers seeking market access. Supply concentrates in Pearl River Delta injection-molding hubs for plastic variants, Gujarat and Saxony metalworking clusters for copper alloys, and Vietnamese plantation networks for bamboo cellulose. Raw material dependencies include polypropylene resin, surgical-grade 304/316L stainless steel, and antimicrobial copper alloys. Single-source vulnerability runs through concentrated Asian manufacturing zones exposed to logistics disruptions. Distribution runs through retail pharmacy networks, direct-to-consumer subscription platforms, and consolidated oral care clinic group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR post-market surveillance obligations and FDA Class I device clearance pathways erect compliance cost barriers that filter low-grade competitors while embedding compliant incumbents in professional procurement channels.
For Market Incumbents: Extend certification investment into ISO 13485 quality management systems to defend professional channel placement against private-label entrants from consolidated clinic networks. Deepen backward integration into regional metalworking clusters in Saxony and Gujarat to secure copper alloy supply against raw material volatility. Lock in multi-year supply agreements with North American group purchasing organizations before subscription bundling displaces traditional pharmacy distribution. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for bypassing retail slotting fees and capturing recurring revenue through oral care system bundling. Target wellness-positioned copper variants in German health stores and Scandinavian online channels where Ayurvedic positioning commands premium acceptance. Pursue white-label manufacturing partnerships with Indian pharmaceutical distributors seeking copper tongue cleaner additions to Ayurvedic product assortments. For Investors and Strategic Acquirers: The window for entry favors metal instrument specialists with established ISO 13485 certification and regional manufacturing footprints in EU and Asian regulatory jurisdictions. Mid-scale manufacturers serving German dental associations demonstrate strongest defensive moats through professional endorsement lock-in. Monitor NMPA registration timeline acceleration in China as inflection signal for Asian market access liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks professional dental channel access across German clinic networks. |
| Direct-to-Consumer Launch | Subscription bundling bypasses retail margin compression in North American metropolitan markets. |
| Backward Integration into Copper Supply | Gujarat and Saxony metalworking cluster control insulates against raw material price volatility. |
| Hospital System Partnership | Indian tertiary facility procurement tenders prioritize bulk supply relationships for single-use instruments. |
| Sustainability Repositioning | Bamboo and biodegradable variants capture zero-waste consumer segments in French health stores. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and Indian BIS standards registries formed the secondary backbone, cross-referenced against primary interviews with dental clinic procurement managers, Ayurvedic product distributors, biomedical engineers at sterilization departments, and group purchasing organization contract specialists. Bottom-up volume triangulation from retail pharmacy audit data and top-down value estimation from import-export customs records converged on segment-level outputs.
Historical trendline analysis across material type, technology tier, and end-user channel dimensions established baseline growth trajectories extended through the projection horizon. Segmentation modeling incorporated product type splits across plastic, stainless steel, copper, and bamboo variants; technology differentiation between manual, electric, sonic, and ultrasonic platforms; and distribution pathway rotation across online, supermarket, pharmacy, and health store channels. CAGRs were derived from regression-weighted momentum indicators adjusted for regulatory compliance timeline impacts.
Inputs from German dental association protocol documentation and North American clinic network purchasing records were available through the study window; gaps in Chinese NMPA registration disclosure timelines and Indian state-level Ayurvedic practitioner survey data introduce uncertainty bands around Asia-Pacific penetration assumptions. Forecasts reflect documented regulatory pathway assumptions and material cost trajectory inputs. Copper price volatility, EU extended producer responsibility enforcement intensity, and clinic network consolidation pace represent primary revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Mouth Spray Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Global Oral Care Products Market
Oral Care
BRICS Oral Care Market
Oral Care
Global Halitosis Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Adult Oral Care Products Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Dry Mouth Relief Market
Oral Care
Herbal Toothpaste Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Oral Care Market
Oral Care
Kids Toothpaste Market
Oral Care
Oral Rinse Market
Oral Care
Oral Hygiene Products Market
Oral Care
Middle East and Africa Oral Care Market