
 Oral Hygiene Products Market | 2026-2036
Oral Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Hygiene Products Market Analysis
Pharmacy-to-digital retail transition is fragmenting as e-commerce platforms capture recurring subscription purchases while traditional drugstores defend foot traffic through clinic partnerships. Colgate-Palmolive leverages its therapeutic toothpaste portfolio to anchor professional channel loyalty. Procter & Gamble sustains mass-market dominance through multi-brand shelf positioning across supermarket chains. Haleon differentiates via specialist mouthwash formulations targeting post-procedural dental care segments.
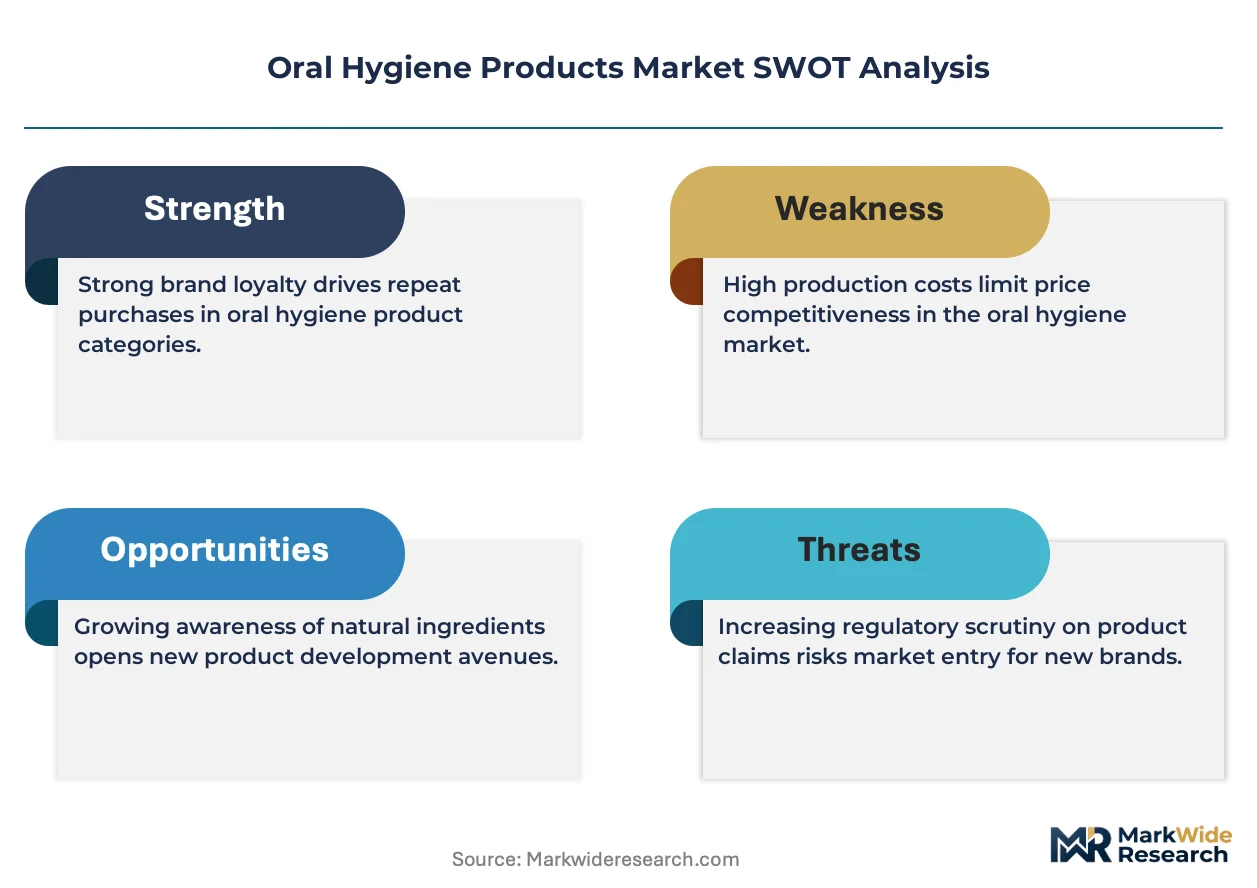
Oral hygiene products encompass formulations and devices designed to prevent dental caries, periodontal disease, and oral malodor through mechanical cleaning, chemical antimicrobial action, or cosmetic brightening; toothpastes typically contain abrasive silica particles at 15-20% concentration, fluoride sources at 1000-1500 ppm, and surfactant systems for biofilm disruption. Mouthwash and whitening strips command expanding margin pools as consumers trade up from basic paste routines toward adjunctive care protocols. Dental professionals represent the fastest-growing end-user channel as chair-side recommendations convert patients to prescription-strength and procedure-support products. Gel and strip formats gain traction among younger demographics seeking portability and aesthetic-specific outcomes.
FDA therapeutic claim oversight and ADA Seal of Acceptance requirements shape product development cycles and marketing permissible in the United States, while ISO 11609 governs toothpaste abrasivity testing methodologies internationally. REACH chemical registration in Europe constrains preservative and active ingredient selections for export-bound manufacturers. Stakeholders must monitor evolving fluoride concentration caps under pediatric safety reviews and decide between reformulation investments or geographic portfolio segmentation.
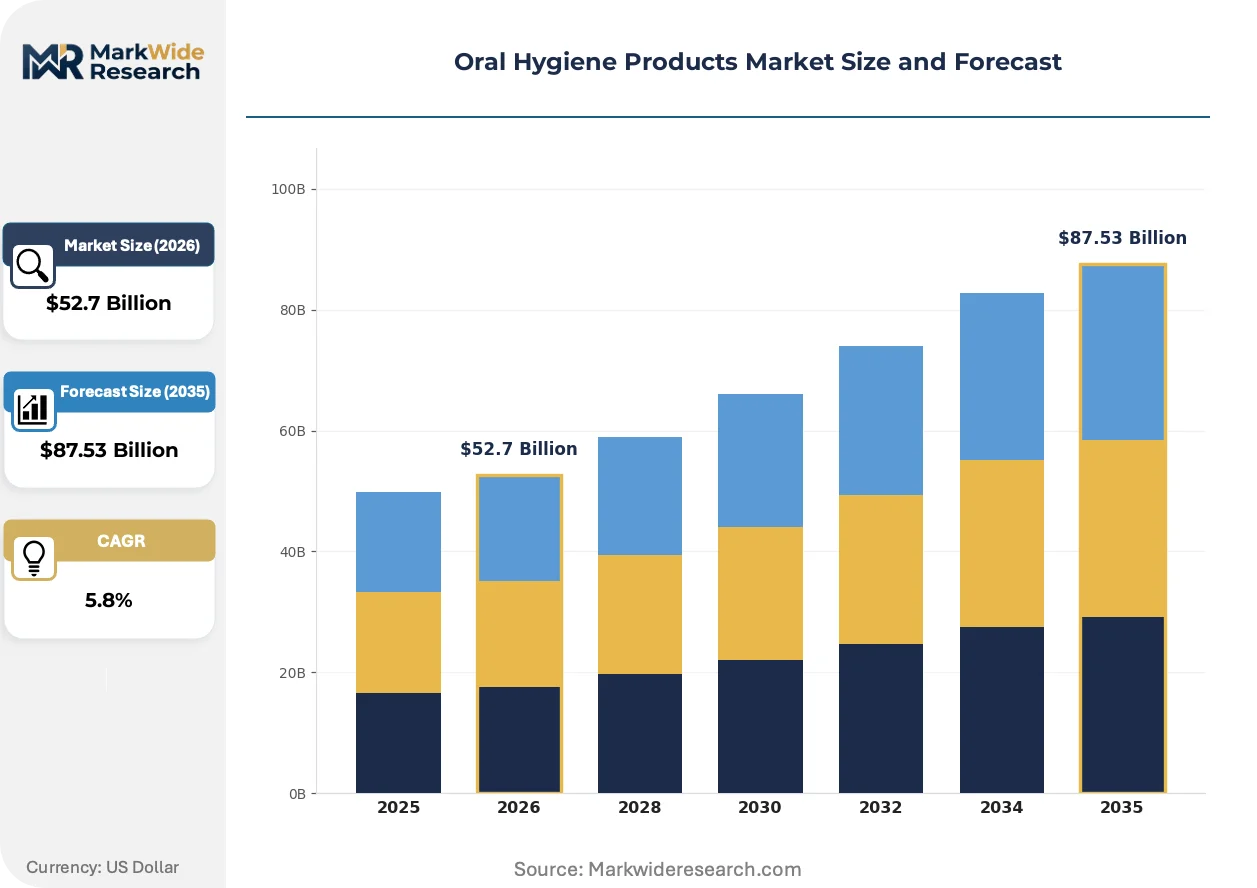
Market Dynamics
Dental professional recommendation channels are consolidating purchasing power as chair-side authority converts patients toward prescription-strength formulations and procedure-support regimens, compressing traditional retail influence.
Growth Catalysts
- Professional channel expansion:Chair-side product recommendations from dentists and hygienists convert patients to therapeutic toothpaste and post-procedural mouthwash protocols.
- FDA therapeutic claim pathways:Regulatory frameworks enabling fluoride concentration claims above 1500 ppm create premium positioning opportunities for manufacturers with clinical trial investments.
- Urban premiumization in China:Tier-1 city consumers trade basic paste routines for electric toothbrush and whitening adjunct systems.
Market Restraints
- Silica abrasive supply concentration:Precipitated silica production clusters in select industrial zones, exposing formulators to input cost volatility and logistics constraints.
- REACH chemical registration friction:European preservative and active ingredient restrictions limit export portfolio standardization for multinational manufacturers.
- Fluoride concentration caps:Pediatric safety reviews in multiple jurisdictions threaten reformulation investments for existing product lines.
Strategic Opportunities
- Subscription e-commerce channels:Recurring delivery models capture replenishment purchasing from households seeking convenience and personalization.
- Post-procedural care segments:Specialist mouthwash formulations targeting implant maintenance and periodontal therapy represent underdeveloped margin pools.
- Gel and strip portability formats:Younger demographics in metropolitan markets favor travel-sized whitening systems over traditional paste tubes.
Industry Challenges
- ADA Seal certification timelines:Clinical substantiation requirements for therapeutic claims extend product development cycles by 18-24 months.
- Multi-channel inventory complexity:Professional, retail, and direct-to-consumer segments demand incompatible packaging and promotional configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Hygiene Products Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $87.53 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Strips End User: Adults, Children, Seniors, Dental Professionals Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Dental Clinics Form: Gel, Paste, Liquid, Strip |
| Companies Covered | Colgate-Palmolive, Procter & Gamble, Haleon, Johnson & Johnson, Unilever, Church & Dwight, Kenvue, Koninklijke Philips, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Hygiene Products Market Emerging Trajectories
Connected devices and algorithmic personalization are reconfiguring how consumers monitor and manage oral health, shifting value capture from commodity formulations toward data-integrated care ecosystems.
Smart toothbrush hardware paired with pressure sensors and brushing-duration tracking is digitizing preventive care routines. Younger urban households adopt these systems fastest, with app-integrated feedback loops replacing passive mechanical cleaning. This convergence is digitizing the traditional paste-and-brush value chain into subscription-enabled hardware-software bundles.
REACH chemical registration revisions in Europe are constraining preservative selections for export-bound manufacturers. Formulators must reformulate or segment portfolios between compliant and non-compliant variants. Mouthwash categories face the steepest adaptation costs due to higher antimicrobial active loadings.
Pharmacy-to-digital transition is fragmenting traditional distribution as e-commerce platforms capture recurring replenishment purchases. Drugstore chains respond through clinic partnerships that defend foot traffic via professional service integration. China and South Korea demonstrate this channel tension most acutely, where mobile-first purchasing dominates urban consumer behavior.
Oral Hygiene Products Market Segmentation
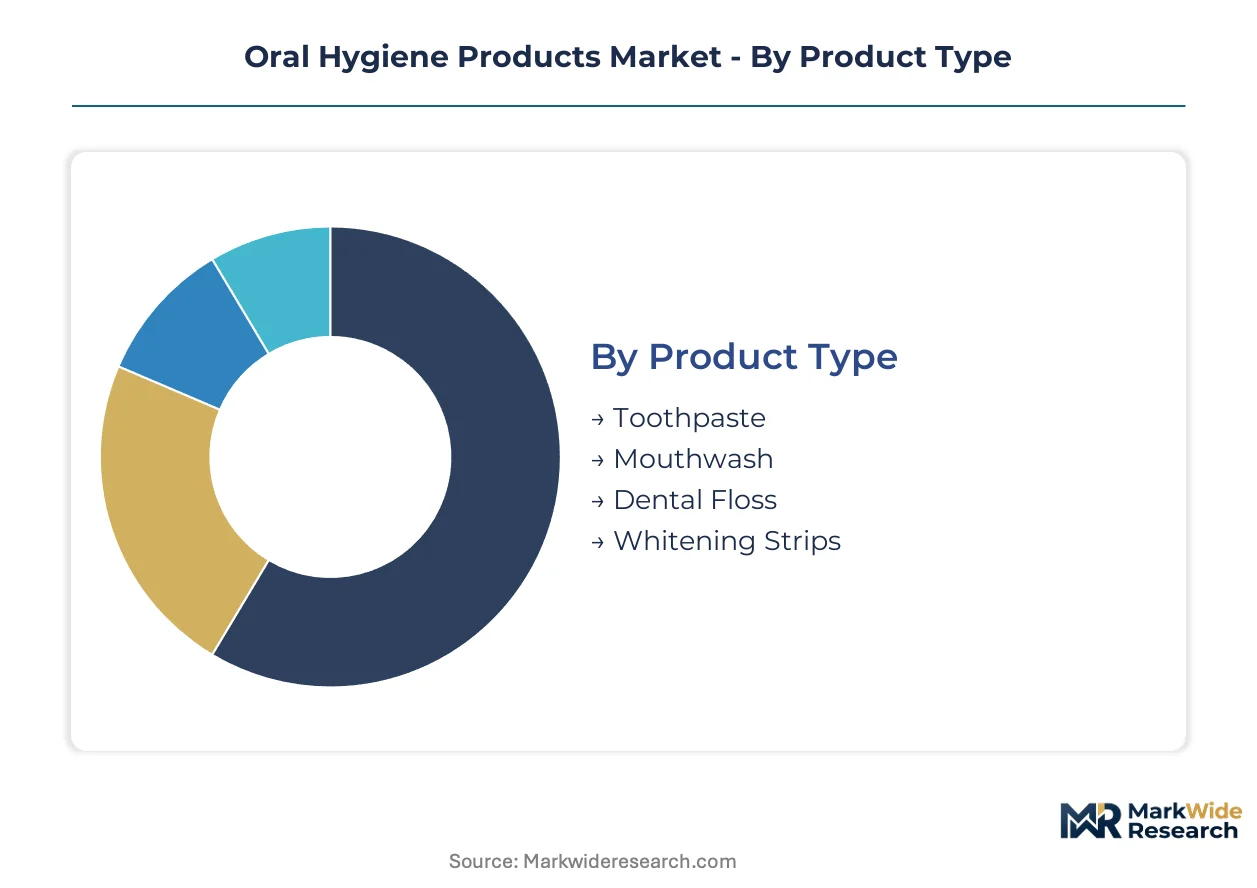
Segmentation in oral hygiene reveals how formulation chemistry, professional authority, and channel economics fragment purchasing behavior across consumer cohorts. Manufacturers must align R&D investment and packaging specifications to distinct usage contexts rather than treating oral care as a uniform commodity category.
Product Type:
Mature paste formulations dominate volume while emerging adjunct categories capture margin expansion through professional endorsement and aesthetic specialization.
- Toothpaste:Silica abrasive systems at 15-20% concentration combined with fluoride sources between 1000-1500 ppm deliver mechanical biofilm disruption and caries prevention. Adults in urban China trade basic variants for therapeutic formulations with desensitizing or gum-health positioning.
- Mouthwash:Liquid antimicrobial formulations containing cetylpyridinium chloride or essential oil blends target post-procedural care and breath-freshening protocols. Dental professionals in the United States drive fastest adoption through chair-side recommendation authority.
- Dental Floss:Polytetrafluoroethylene and nylon filament formats serve interdental cleaning with waxed and unwaxed variants.
- Whitening Strips:Hydrogen peroxide gel layers on flexible polyethylene substrates enable at-home aesthetic treatment.
Toothpaste retains volume leadership; whitening strips hold the steepest expansion curve.
End User:
Customer lifecycle positioning shapes fluoride concentration limits, flavor profiles, and professional channel engagement intensity.
- Adults:Primary revenue base consuming therapeutic and cosmetic formulations across all distribution channels. Urban professionals in tier-1 Chinese cities drive electric toothbrush pairing and subscription replenishment.
- Children:Pediatric safety caps on fluoride concentration below 1000 ppm constrain formulation flexibility in the United States under FDA oversight. Parents prioritize flavor acceptance and packaging safety mechanisms over therapeutic claims.
- Seniors:Dry mouth and periodontal maintenance needs shift demand toward alcohol-free mouthwash and specialized denture care.
- Dental Professionals:Prescription-strength fluoride pastes above 1500 ppm and procedure-support regimens convert chair-side authority into direct purchasing influence.
Adults command absolute spending volume; dental professionals are climbing the fastest as a recommendation channel.
Distribution Channel:
Channel selection determines packaging format, promotional cadence, and margin structure through professional credentialing versus mass-market scale.
- Pharmacies:Clinic-adjacent locations defend foot traffic through pharmacist consultation and prescription adjacency. South Korean drugstore chains integrate dental screening services to combat mobile commerce erosion.
- Supermarkets:Multi-brand shelf positioning and promotional stacking drive impulse replenishment purchasing. Procter & Gamble and Colgate-Palmolive deploy category captaincy to control planogram placement.
- Online Retailers:Subscription algorithms capture recurring household replenishment with personalization based on brushing device data.
- Dental Clinics:Chair-side dispensing of prescription formulations and post-procedural kits converts professional authority into immediate purchase behavior.
Supermarkets retain volume leadership; dental clinics hold the steepest expansion curve.
Form:
Physical state dictates portability, dosing precision, and compatibility with connected device ecosystems.
- Gel:Transparent silica-thickened systems enable whitening actives and aesthetic appeal for younger demographics. Travel-sized tubes target metropolitan commuters in Shanghai and Seoul.
- Paste:Conventional creamy formulations with higher abrasive loadings dominate family-sized packaging and value-tier positioning.
- Liquid:Mouthwash and rinse formats require preservative systems compliant with REACH registration constraints in Europe.
- Strip:Thin-film whitening systems offer discrete portability and precise peroxide dosing for aesthetic-focused consumers.
Paste retains volume leadership; strip formats hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese urban centers where premium electric toothbrush bundles command threefold markups over basic paste formulations, while European manufacturers absorb REACH compliance costs that compress margins on export-bound antimicrobial mouthwash lines.
United States
Dental professional channels drive prescription-strength fluoride adoption above 1500 ppm through chair-side dispensing authority. FDA therapeutic claim oversight shapes formulation development cycles and marketing permissible for caries-prevention positioning. Manufacturing clusters in New Jersey and Ohio concentrate silica abrasive sourcing and contract formulation services for private-label entrants.
China
Tier-1 city consumers in Shanghai and Beijing trade basic paste routines for subscription-enabled electric toothbrush systems with algorithmic brushing feedback. SAMR registration requirements and GB standards govern fluoride concentration labeling and antimicrobial active claims. The Yangtze River Delta anchors domestic manufacturing of smart oral care hardware and gel-format whitening systems for metropolitan commuters.
Germany
Pharmacy-dispensed therapeutic mouthwash maintains channel loyalty through pharmacist consultation adjacency despite e-commerce erosion. ECHA REACH registrations constrain preservative selections for export formulations targeting European markets. Industrial zones in North Rhine-Westphalia concentrate contract manufacturing capacity for alcohol-free periodontal maintenance formulations.
Japan
Metropolitan households in Tokyo and Osaka adopt portable strip-format whitening systems for discrete aesthetic maintenance between professional cleanings. PMDA and METI guidance governs hydrogen peroxide concentration limits in over-the-counter dental bleaching products. The Kansai region hosts specialized film-substrate manufacturing for flexible polyethylene whitening strip substrates.
South Korea
Mobile-first purchasing patterns in Seoul accelerate subscription e-commerce capture of replenishment purchasing from younger demographics. MFDS registration requirements shape antimicrobial active loadings in post-procedural care formulations. Drugstore chains in the capital integrate dental screening services to defend foot traffic against platform commerce displacement.
Oral Hygiene Products Market Vendor Landscape
Therapeutic-specialist and mass-market-omnichannel archetypes split the market between prescription-strength formulation authority and supermarket shelf-scale dominance. The structure consolidates around three tiers: multinational CPG conglomerates with professional channel credentialing, mid-cap regional specialists with format innovation focus, and private-label contract manufacturers serving retailer-owned brands. Dominant competitive moves include portfolio diversification into connected-device ecosystems and geographic segmentation between REACH-compliant and non-compliant formulation variants.
Within the therapeutic-specialist tier, Colgate-Palmolive and Haleon occupy positions anchored by professional endorsement authority and post-procedural care specialization. Procter & Gamble exemplifies the mass-market-omnichannel archetype through multi-brand shelf positioning that captures impulse replenishment across supermarket chains. These three entities represent the competitive poles around which mid-cap specialists and private-label manufacturers orient their market entry strategies.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| Procter & Gamble |
| Haleon |
| Johnson & Johnson |
| Unilever |
| Church & Dwight |
| Kenvue |
| Koninklijke Philips |
| Henkel |
| Others |
Supply Flow & Price Mechanics
Precipitated silica production clusters in China's Yangtze River Delta and select German industrial zones anchor input cost volatility for toothpaste formulators, compressing margins on economy-tier pastes while premium therapeutic variants absorb these fluctuations through professional channel markups. This upstream concentration funnels pricing power toward specialty chemical suppliers and away from finished goods manufacturers competing on supermarket shelf positioning.
Pricing Analysis
The customization-premium spread separates subscription-enabled smart toothbrush bundles from commodity paste tubes by a factor of three to five in Chinese tier-1 cities. Three-tier pricing structure across premium, standard, and economy levels stratifies around fluoride concentration thresholds and ADA Seal certification status. Price differentiation hinges on professional endorsement authority and connected device integration, with pricing pressure intensifying in mass retail as e-commerce algorithms erode brand loyalty. Value-tier buyers in emerging markets exhibit acute price sensitivity, while dental clinic dispensing channels sustain inelastic demand for prescription-strength formulations.
Supply Chain Analysis
Upstream feedstock dependencies center on precipitated silica from China and Germany, hydrogen peroxide from Belgium and the United States, and fluoride compounds from Morocco and China. Formulation chemistry rests on surfactant systems sourced from petrochemical complexes in South Korea and Singapore, with polyethylene film substrates for whitening strips concentrated in Japan and Taiwan. Supply chain risk manifests in REACH registration friction constraining antimicrobial preservative selections for European-bound mouthwash lines. Distribution runs through pharmacy-clinic partnerships defending foot traffic against platform commerce displacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected device ecosystems and algorithmic personalization are disrupting preventive care economics, with FDA therapeutic claim pathways enabling premium positioning for manufacturers with clinical trial investments.
For Market Incumbents: Insulate professional channel loyalty through exclusive prescription-strength fluoride formulations above 1500 ppm, while deepening backward integration into silica abrasive production to neutralize input cost volatility from Yangtze River Delta suppliers. Threats from subscription-native entrants and smart hardware-software bundles demand preemptive certification investment in ADA Seal pathways.
For New Entrants and Emerging Players: Pursue portable gel and strip formats targeting metropolitan commuters in Shanghai and Seoul, where aesthetic-specific outcomes command premium positioning absent from mass paste markets. Post-procedural care segments for implant maintenance represent the most penetrable white space, accessible through dental clinic partnerships rather than supermarket shelf competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional mouthwash specialists holding ECHA REACH-compliant formulations and pharmacist channel relationships in Germany. Long-term viability hinges on algorithmic personalization capabilities and subscription retention metrics. The signal to watch is MFDS registration acceleration in South Korea as a proxy for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Professional Channel Credentialing | ADA Seal investment compresses development cycles against FDA therapeutic claim timelines. |
| Connected Device Integration | Smart toothbrush hardware pairs with subscription algorithms to capture recurring replenishment. |
| REACH-Compliant Reformulation | Antimicrobial preservative substitution preserves European market access for mouthwash portfolios. |
| Post-Procedural Care Expansion | Specialist mouthwash for implant maintenance unlocks dental clinic dispensing authority. |
| Geographic Portfolio Segmentation | Fluoride concentration variants align with pediatric safety caps across regulatory jurisdictions. |
Methodological Framework
A spread of perspectives from brand managers at multinational CPG conglomerates, category buyers at supermarket chains, dental clinic procurement heads, and supply planners at silica abrasive manufacturers converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA 510(k) filings, SAMR registration databases, Nielsen retail audit data, and customs trade records. Bottom-up volume modeling triangulated against top-down macroeconomic sizing across product type, end user lifecycle, distribution channel, and physical format dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling spanning formulation chemistry tiers, professional versus retail channel economics, and geographic regulatory clusters. CAGRs derived from fitted growth curves incorporating electric toothbrush adoption rates, subscription e-commerce penetration, and chair-side recommendation conversion metrics. Forecast inputs included silica abrasive pricing indices and REACH registration compliance cost trajectories.
Sensitivities concentrate around fluoride concentration cap revisions under pediatric safety reviews and REACH chemical registration scope expansions. Cross-checking against SAMR registration velocity in China and MFDS approval timelines in South Korea is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Europe Oral Hygiene Market
Oral Care
Europe Oral Care Market
Oral Care
Manual Toothbrush Market
Oral Care
Global Halitosis Market
Oral Care
Kids Toothpaste Market
Oral Care
Adult Oral Care Products Market
Oral Care
South America Oral Care Market
Oral Care
Global Oral Hygiene Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Halitosis Treatment Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
China Oral Care Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Baby Oral Care Market
Oral Care
Children's Oral Care Market
Oral Care
Toothcare Market