
 Pharmaceutical Cleaning Validation Market | 2026-2036
Pharmaceutical Cleaning Validation Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Cleaning Validation Market Intelligence
Biotechnology firms is bifurcating demand away from traditional pharmaceutical packagers as complex biologics require more stringent cleaning verification protocols. SGS SA leverages its global laboratory network to anchor validation services across European manufacturing hubs. Waters Corporation differentiates through mass spectrometry platforms purpose-built for trace residue detection. Merck KGaA competes by supplying validated cleaning agents alongside analytical reference standards.
Pharmaceutical cleaning validation encompasses documented evidence that equipment surfaces are free of residual active pharmaceutical ingredients, cleaning agents, and microbial contaminants to predetermined acceptance criteria, typically verified through swab sampling with defined recovery factors and analytical methods such as HPLC or TOC analysis. Its primary purpose is preventing cross-contamination between product batches and ensuring patient safety in multi-use manufacturing environments. Cleaning agents dominate product type revenue due to recurring consumable demand, while validation software represents the fastest-expanding segment as facilities replace paper-based protocols with electronic batch records. Among applications, sterile products command premium pricing for validation services owing to the lethal risk profile of parenteral contamination.
FDA enforces cleaning validation through its Guidance for Industry on validation of cleaning processes, while EMA's Annex 15 mandates ongoing process verification including cleaning effectiveness. The EU GMP Annex 1 revision on sterile manufacture further tightens environmental monitoring requirements that cascade into validation scope. ISO 14644 cleanroom classification standards shape facility design parameters that precondition cleaning protocol design. Stakeholders must monitor regulatory divergence between FDA's risk-based approach and EMA's prescriptive verification frequencies when scaling validation programs across manufacturing networks.
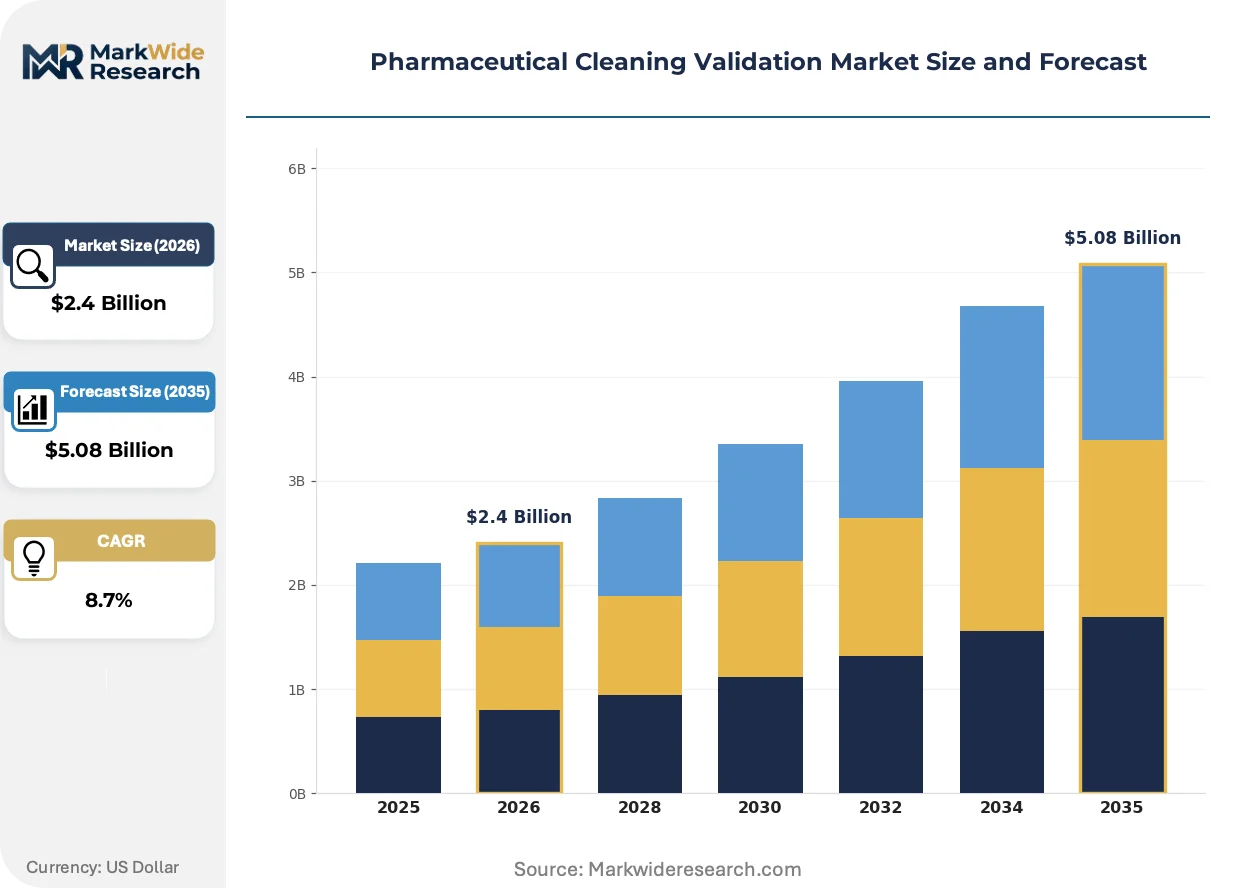
Market Dynamics
Multi-product biologics facilities face escalating pressure from tightened cross-contamination limits, forcing rapid displacement of paper-based validation protocols with integrated electronic batch record systems that embed real-time residue detection.
Growth Catalysts
- EMA Annex 15 mandates:Ongoing process verification requirements compel European sterile manufacturers to upgrade from periodic to continuous cleaning monitoring, expanding analytical service contracts.
- Biologics manufacturing concentration:Complex monoclonal antibody and cell therapy production in Germany, Massachusetts, and Hyderabad generates specialized demand for protein-specific residue detection methods.
- TOC analyzer miniaturization:Portable total organic carbon devices enable at-line verification without laboratory delays, accelerating batch release timelines for contract manufacturers.
Market Restraints
- Reference standard scarcity:Limited commercial availability of validated cleaning agent residue standards constrains method development timelines and increases analytical costs.
- Specialized labor concentration:Validation protocol designers and GMP auditors cluster in Basel, Boston, and Mumbai, creating hiring bottlenecks for facilities in secondary manufacturing locations.
- Equipment qualification burden:Automated sampling robots require extensive IQ/OQ/PQ documentation that extends deployment cycles beyond typical capital budgeting windows.
Strategic Opportunities
- Indian CDMO expansion:Domestic biologics capacity growth under PLI scheme incentives creates demand for validation partnerships that combine Western regulatory expertise with local operational presence.
- Continuous manufacturing integration:Single-use bioreactor adoption in gene therapy production necessitates novel cleaning validation approaches for disposable fluid contact surfaces.
- Cloud-based protocol repositories:Centralized electronic master files enable multi-site pharmaceutical companies to harmonize acceptance criteria across distributed manufacturing networks.
Industry Challenges
- Swab recovery factor variability:Surface-specific extraction efficiency studies consume significant analytical resources and delay protocol finalization for novel equipment geometries.
- Legacy equipment integration:Stainless steel vessels with fixed spray balls resist retrofitting for automated sampling, forcing hybrid manual-automated validation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Cleaning Validation Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Agents, Residue Monitors, Validation Software, Sampling Equipment, Cleaning Devices Application: Oral Solids, Injectables, Topical Formulations, Sterile Products, Biotechnology Products End User: Contract Manufacturers, Biotechnology Firms, Academic Research, Government Laboratories, Pharmaceutical Packaging Units Deployment: On-Premises, Cloud-Based, Hybrid Systems, Mobile Platforms, Web Interfaces |
| Companies Covered | Shimadzu Corporation, Intertek Group PLC, Merck KGaA, SGS SA, Hach, ProPharma Group, Waters Corporation, Lucideon Limited, Avomeen LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Cleaning Validation Market Strategic Shifts & Innovations
Validation technology is pivoting from retrospective documentation toward predictive contamination control, embedding sensors directly into equipment surfaces and connecting residue data to batch release algorithms in real time.
Raman spectroscopy is decomposing the traditional swab-send-analyze workflow by enabling non-contact identification of active pharmaceutical ingredients on equipment surfaces. Sterile injectables manufacturers in Switzerland and Ireland are piloting handheld devices for at-line verification. This technology is decomposing the 24-48 hour analytical hold that currently constrains batch turnover in multi-product suites.
EU GMP Annex 1 revision on sterile manufacture mandates enhanced environmental monitoring that cascades into expanded cleaning validation scope for Grade A and B areas. Pharmaceutical companies must now demonstrate correlation between surface residue levels and airborne particulate counts. Aseptic fill-finish operations in Germany and the Netherlands are redesigning protocols to incorporate this integrated contamination control philosophy.
CDMO procurement teams now bundle validation services into multi-year manufacturing agreements rather than contracting analytical work separately. Large biopharma sponsors in the United States are transferring protocol ownership to contract partners to accelerate tech transfer timelines. This consolidation is most advanced in the Boston-Cambridge cluster where virtual biotechs lack internal validation capabilities entirely.
Pharmaceutical Cleaning Validation Market Segmentation
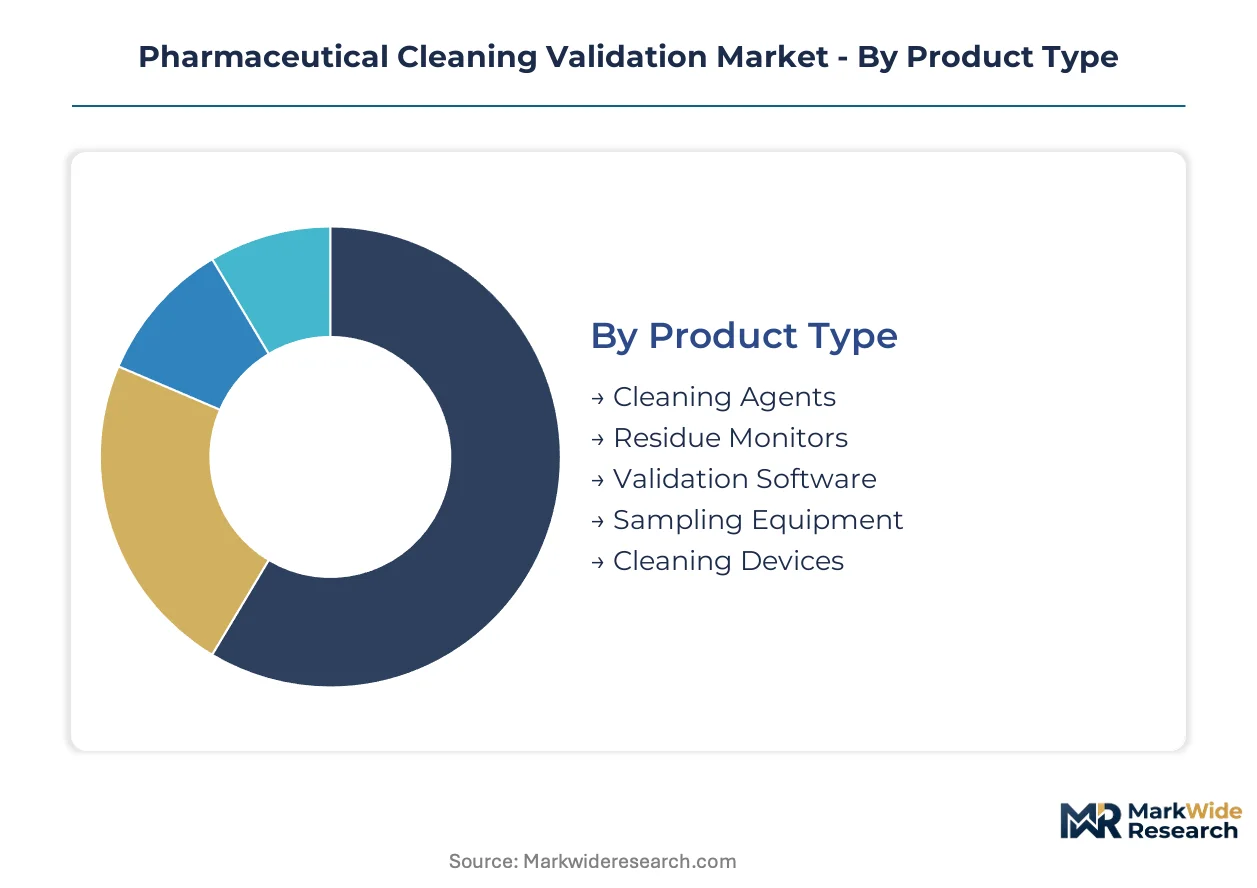
Cleaning validation markets fragment across equipment lifecycles, regulatory exposure, and data architecture choices. Segment boundaries increasingly blur as pharmaceutical manufacturers demand integrated validation ecosystems rather than point solutions.
Product Type:
Cleaning agents and residue monitors concentrate demand in domestic European and North American manufacturing clusters, while validation software and sampling equipment flow through export-led supply chains serving Asian contract manufacturers.
- Cleaning Agents:Formulated surfactant and solvent blends validated for specific equipment surfaces and active pharmaceutical ingredient chemistries. Demand clusters in Germany and Massachusetts where multi-product biologics facilities face EMA Annex 15 verification mandates. Recurring consumable procurement locks in steady revenue streams.
- Validation Software:Electronic batch record systems embedding automated protocol execution and deviation tracking. Export-led deployment dominates as Indian and Chinese contract manufacturers adopt Western regulatory compliance frameworks. Cloud-native architectures displace legacy paper-based documentation.
- Residue Monitors:At-line analytical instruments for total organic carbon and conductivity measurement.
- Sampling Equipment:Swabs, rinse collection apparatus, and recovery factor validation tools.
- Cleaning Devices:Automated spray balls, CIP skids, and ultrasonic cleaning systems.
Cleaning agents command the established base. The steepest expansion runs through validation software.
Application:
Cost tier stratification separates premium sterile validation from standard oral solid protocols, with biotechnology applications commanding specialized protein-specific residue detection at mid-tier pricing.
- Sterile Products:Parenteral and ophthalmic formulations requiring Grade A environmental correlation studies under EU GMP Annex 1. Swiss and Irish fill-finish operations drive premium service contracting. Lethal risk profile mandates exhaustive documentation and real-time monitoring integration.
- Biotechnology Products:Monoclonal antibody, cell therapy, and gene therapy manufacturing with complex protein residue matrices. Hyderabad and Boston-Cambridge clusters generate specialized method development demand. Host cell protein detection requires mass spectrometry platforms.
- Injectables:Small molecule parenteral formulations with established cleaning protocols.
- Oral Solids:Tablet and capsule manufacturing with standardized residue limits.
- Topical Formulations:Cream, ointment, and transdermal patch production.
Sterile products anchor the premium tier. Biotechnology applications are climbing the fastest as novel modalities multiply validation complexity.
End User:
Volume concentration tilts toward contract manufacturers consolidating multi-client validation protocols, while biotechnology firms fragment demand across specialized protein production requirements.
- Contract Manufacturers:CDMOs serving multiple pharmaceutical sponsors with shared equipment suites. Indian PLI scheme beneficiaries in Hyderabad and Ahmedabad expand capacity fastest. Procurement teams bundle validation services into multi-year manufacturing agreements.
- Biotechnology Firms:Virtual and mid-cap developers lacking internal validation capabilities. Massachusetts and Basel clusters outsource entirely to specialized service providers. Complex biologics force departure from traditional pharmaceutical packager relationships.
- Pharmaceutical Packaging Units:Primary and secondary packaging with secondary equipment cleaning requirements.
- Academic Research:University pilot plants with limited GMP compliance scope.
- Government Laboratories:National health institutes with vaccine production mandates.
Contract manufacturers concentrate procurement volume. Biotechnology firms represent the fastest-growing customer type as virtual development models proliferate.
Deployment:
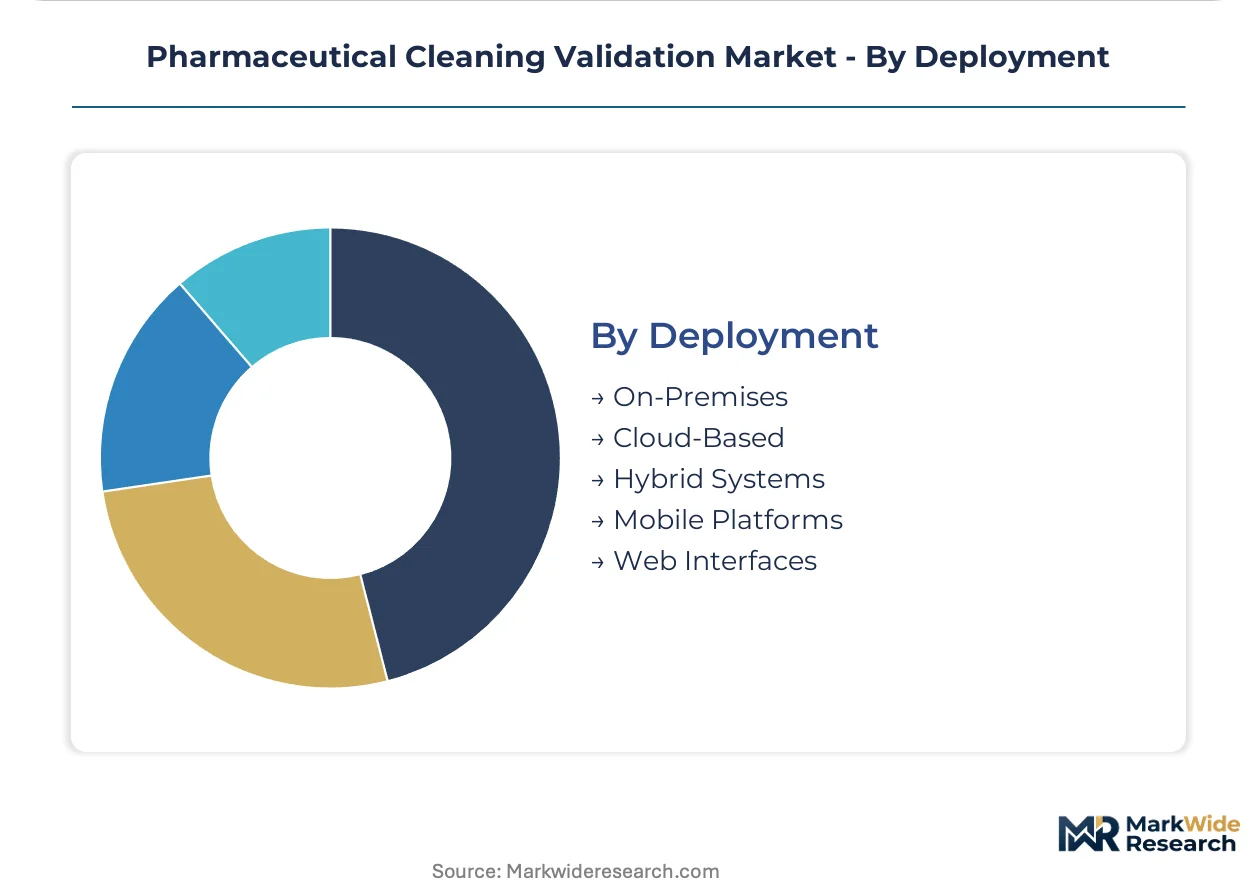
Customer type splits between validated pharmaceutical manufacturers requiring on-premises data sovereignty and emerging biotechs accepting cloud architectures for speed-to-market.
- Cloud-Based:Centralized electronic master files enabling multi-site harmonization. Large pharmaceutical networks in Germany and the United States standardize acceptance criteria across distributed facilities. Regulatory audit trails maintain 21 CFR Part 11 compliance.
- On-Premises:Local server installations for facilities with stringent data residency requirements. Government laboratories and certain European manufacturers resist external hosting. Capital intensity limits adoption among mid-tier contract manufacturers.
- Hybrid Systems:Edge computing with cloud backup for critical batch records.
- Mobile Platforms:Handheld devices for at-line verification in production suites.
- Web Interfaces:Browser-based protocol access for remote audit support.
On-premises deployments retain the incumbent installed base. Cloud-based systems are expanding most quickly as validation-as-a-service models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German validation service providers export protocol expertise to Indian contract manufacturers, while Massachusetts-based analytical instrument vendors supply residue detection platforms to European biologics clusters.
United States
FDA's Guidance for Industry on validation of cleaning processes drives protocol standardization across multi-product facilities. The IRA's domestic manufacturing incentives expand biologics capacity in Greater Boston, where virtual biotechs outsource entire validation workflows to specialized service providers. Massachusetts and North Carolina clusters concentrate demand for protein-specific residue detection methods.
Germany
EMA Annex 15 mandates compel sterile manufacturers to upgrade from periodic to continuous cleaning monitoring. The country's dense biologics manufacturing footprint in Bavaria and Baden-Württemberg generates specialized demand for monoclonal antibody validation protocols. Heidelberg and Munich host concentrated analytical service provider networks serving European fill-finish operations.
India
CDSCO alignment with international GMP standards accelerates validation protocol adoption across contract manufacturing expansion. PLI scheme incentives for domestic biologics capacity in Hyderabad and Ahmedabad create demand for Western regulatory expertise combined with local operational presence. Telangana and Gujarat clusters drive fastest uptake of automated validation systems.
Switzerland
Swissmedic enforcement of EU GMP Annex 1 revision tightens environmental monitoring requirements for sterile injectables. Basel's pharmaceutical headquarters concentration fragments demand across specialized protein production requirements. Swiss fill-finish operations pilot handheld Raman devices for at-line verification, decomposing traditional analytical hold periods.
United Kingdom
MHRA post-Brexit regulatory divergence from EMA creates protocol harmonization challenges for multinational manufacturing networks. Southeast England's biotech corridor generates mid-tier demand for cloud-based validation software replacing paper documentation. London-based procurement teams increasingly bundle validation services into multi-year manufacturing agreements.
Pharmaceutical Cleaning Validation Market Key Industry Players
Player mix skews toward diversified analytical instrumentation conglomerates with life science divisions, supplemented by specialized contract research organizations and consumables suppliers. Tiered competitive structure separates premium-tier platform vendors from mid-market service providers and commodity reagent suppliers. Strategic archetypes include mass spectrometry platform specialists, global laboratory network operators, and validated cleaning agent formulators. Dominant competitive moves encompass geographic expansion through validation service partnerships and portfolio diversification into continuous manufacturing support capabilities.
Within the instrumentation tier, Waters Corporation and Shimadzu Corporation occupy positions as platform technology anchors, while SGS SA represents the global laboratory network archetype. Merck KGaA exemplifies the integrated consumables and standards supplier model. These three entities collectively span the core technology, service, and reagent vectors that pharmaceutical manufacturers must coordinate when building comprehensive validation ecosystems.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Intertek Group PLC |
| Merck KGaA |
| SGS SA |
| Hach |
| ProPharma Group |
| Waters Corporation |
| Lucideon Limited |
| Avomeen LLC |
| Others |
Cost & Logistics Intelligence
Automated sampling robot displacement of manual swab protocols simultaneously redraws procurement geography toward German and Massachusetts automation vendors while compressing service pricing for legacy analytical providers. This substitution dynamic concentrates buyer power among CDMO procurement teams bundling multi-year validation contracts.
Pricing Analysis
Next-generation Raman spectroscopy platforms command 40-60% premiums over incumbent HPLC-TOC workflows, while prior-generation paper-based documentation systems face accelerating price erosion. Three-tier pricing structure across premium instrument platforms, mid-tier service contracts, and economy consumable supplies dominates procurement. Price differentiation hinges on FDA 21 CFR Part 11 certification tier and geographic service coverage density. Cost compression in mid-tier analytical services intensifies as Indian CDMOs consolidate procurement volume. Biotechnology firms exhibit lowest price sensitivity due to lethal risk profiles, while oral solid manufacturers drive hardest bargain terms.
Supply Chain Analysis
Germany and the United States anchor precision analytical instrument fabrication, while India concentrates consumable swab and reagent formulation. Critical inputs draw from specialized mass spectrometry component foundries in Massachusetts, validated surfactant chemical streams in Basel, and TOC sensor substrates in South Korea. Single-source vulnerability concentrates in reference standard production for protein-specific residue detection. Distribution runs through validation service provider networks that bundle hardware, software, and analytical labor into integrated procurement packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native validation platform economics are displacing point-solution vendors as pharmaceutical manufacturers demand interoperable electronic batch record ecosystems spanning distributed manufacturing networks.
For Market Incumbents: Fortify defensive moats through backward integration into reference standard production and captive supply of validated cleaning agents. Waters Corporation and SGS SA face emerging pressure from Indian CDMOs developing in-house analytical capabilities. Certification investment in EU GMP Annex 1 correlation protocols anchors premium positioning against mid-tier automation entrants. For New Entrants and Emerging Players: Differentiate on portable at-line verification devices targeting Hyderabad and Ahmedabad biologics clusters where rapid batch release commands procurement priority. White-space opportunity concentrates in single-use bioreactor validation protocols for gene therapy manufacturing. Go-to-market leverage rests on partnership models with Western regulatory expertise combined with local operational presence. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform consolidators over point-solution specialists. Long-term viability hinges on software recurring revenue streams displacing transactional analytical services. Acquisition target archetype: cloud-native validation software vendors with 21 CFR Part 11 compliance architecture. Signal to watch: CDMO procurement team consolidation of multi-year bundled contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Electronic master file harmonization enables multi-site acceptance criteria standardization across German and US manufacturing networks. |
| Regulatory Certification Pathway | FDA 21 CFR Part 11 and EU GMP Annex 15 compliance investments lock in premium pricing tiers against uncertified competitors. |
| Specialist Firm Acquisition | Protein-specific residue detection capabilities address biotechnology demand from Boston-Cambridge monoclonal antibody developers. |
| Geographic Expansion | Hyderabad and Ahmedabad validation service partnerships capture PLI scheme biologics capacity growth under CDSCO alignment mandates. |
| Continuous Manufacturing Support | Single-use bioreactor validation protocols address gene therapy production requirements in Swiss and Dutch fill-finish operations. |
Research Approach
Cross-validation between primary interviews with validation protocol designers and secondary regulatory filing analysis anchors the qualitative findings. Stakeholder engagement spanned GMP auditors at contract manufacturers, analytical instrumentation product managers, CDMO procurement leads, and regulatory affairs specialists at biotechnology firms. Secondary sources encompassed FDA Guidance for Industry documents, EMA Annex 15 submissions, ISO 14644 cleanroom classification standards, and CDSCO GMP compliance circulars. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Sensitivity analysis around EMA Annex 1 enforcement timelines and PLI scheme capacity addition rates stress-tested projection robustness across the analysis window. Segmentation modeling incorporated product type, application tier, end-user archetype, and deployment architecture dimensions. CAGRs derived from regression analysis of historical validation protocol adoption curves correlated with biologics manufacturing capacity expansion. Industry-specific inputs included TOC analyzer shipment data and CDMO service contract value disclosures.
Material uncertainties — regulatory divergence between FDA risk-based and EMA prescriptive verification frameworks, reference standard supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding cross-contamination limit tightening trajectories and automated system penetration rates. Recalibration cycles align with material shifts in biologics manufacturing geography and GMP regulatory harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market