
 Baby Oral Care Market | 2026-2036
Baby Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Oral Care Market Analysis
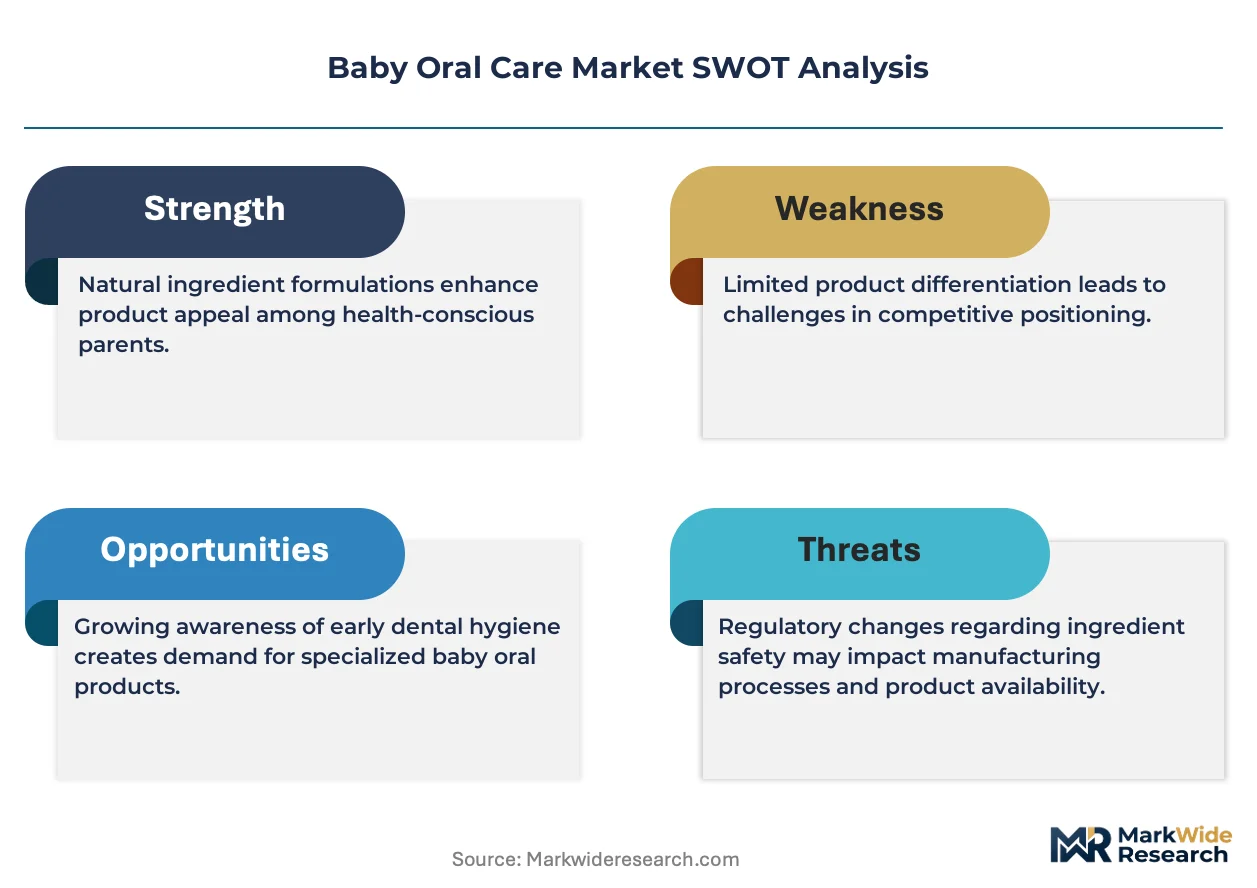
Subscription-based direct-to-consumer financing is tilting competitive dynamics toward brands with digital-native distribution. Procter & Gamble leverages its retail shelf dominance to sustain mass-market penetration across supermarkets and pharmacies. Colgate-Palmolive differentiates through pediatric dentist endorsements and fluoride-free innovation pipelines. Pigeon Corporation anchors its position in Asian markets with infant-specific soft-bristle designs and pharmacy channel control.
Baby oral care encompasses specially formulated hygiene products designed for children from birth through early childhood, featuring extra-soft bristles, low-foam surfactants, and controlled fluoride concentrations calibrated to developmental stages. These products prevent early childhood caries while establishing lifelong oral hygiene behaviors through age-appropriate textures and flavors. Toothpaste and toothbrush segments lead volume, with natural and fluoride-free ingredient categories capturing margin expansion as parental safety concerns reshape purchasing criteria. Online distribution channels represent the fastest-growing access point, though retail stores and pharmacies retain critical trust-building touchpoints for first-time buyers.
The US FDA regulates infant oral care as over-the-counter drug or cosmetic classifications depending on therapeutic claims, while the EU EFSA and REACH frameworks govern ingredient safety and labeling across member states. China's NMPA and GB standards impose additional testing requirements for imported baby formulations, creating compliance complexity for multinational portfolios. ISO 20126 toothbrush safety standards and national dental association certifications further stratify market access tiers. Stakeholders must monitor evolving pediatric fluoride exposure guidelines and emerging state-level ingredient disclosure mandates that could trigger rapid formulation pivots.
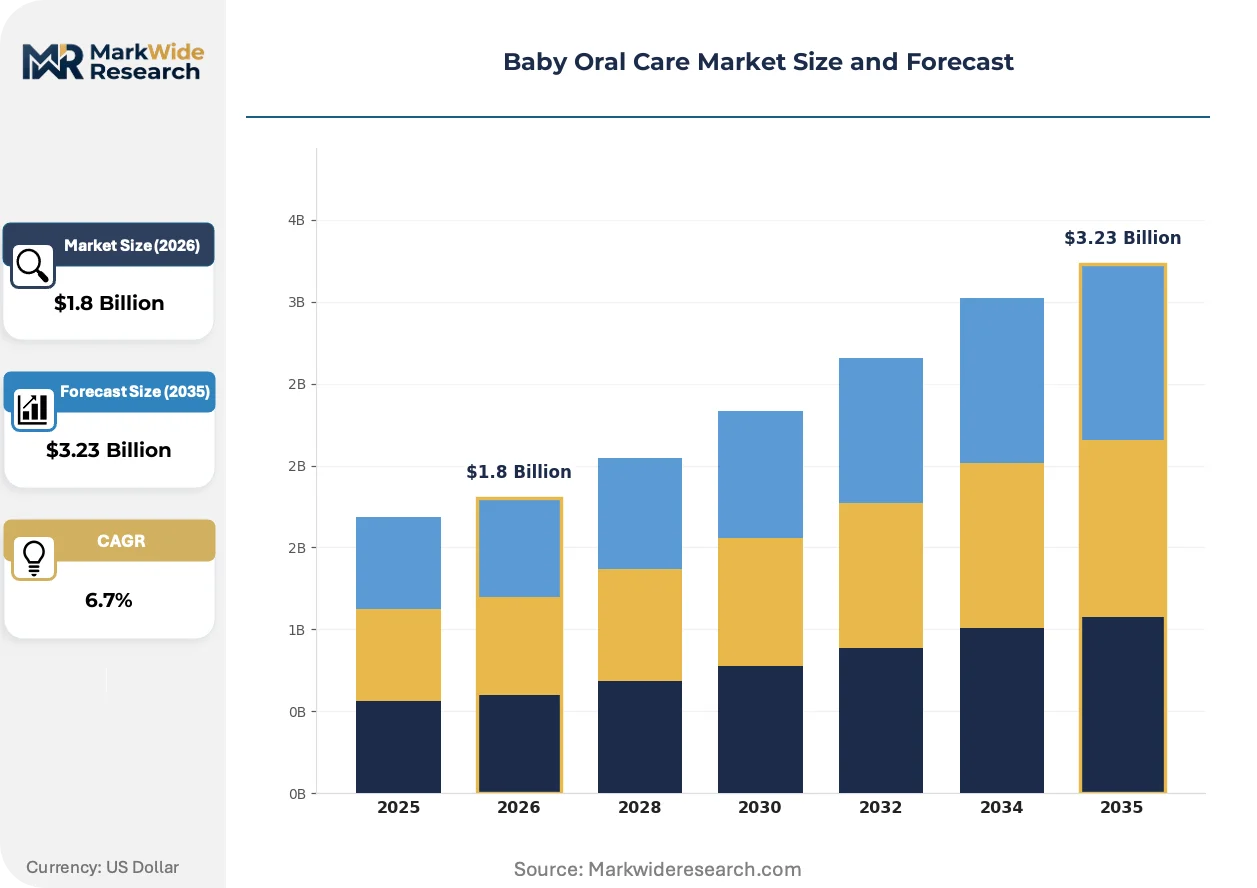
Market Dynamics
Millennial parental preference for fluoride-free and natural-ingredient formulations is restructuring competitive positioning across formulation portfolios and channel strategies. This demographic shift forces incumbent brands to accelerate clean-label pipelines while defending pharmacy and retail shelf relationships against digital-native entrants.
Growth Catalysts
- EFSA pediatric fluoride exposure guidelines:European regulatory clarity on safe thresholds drives parental confidence in age-appropriate formulations, expanding addressable market for calibrated-concentration products.
- Subscription direct-to-consumer models:Digital-native distribution captures recurring revenue streams and first-party data, tilting competitive dynamics toward brands with logistics infrastructure and content marketing capabilities.
- China's three-child policy:Expanded birth cohorts in tier-one cities concentrate demand for premium imported oral care, with NMPA registration requirements creating barrier-protected market access for compliant multinationals.
Market Restraints
- Xylitol supply concentration:Natural sweetener sourcing clusters in Chinese and Finnish birch processing facilities, exposing formulation costs to agricultural commodity volatility and geopolitical logistics friction.
- FDA over-the-counter drug classification:Therapeutic claims on infant toothpaste trigger costly New Drug Application pathways, compressing margin for innovation in anticavity functional positioning.
- Bioplastic bristle technical limitation:Plant-based nylon alternatives exhibit 40% faster degradation in humid storage, constraining shelf-life guarantees for sustainable toothbrush positioning.
Strategic Opportunities
- India tier-two city penetration:Underpenetrated pediatric dentist networks and rising disposable income in Surat, Indore, and Kochi create whitespace for pharmacy-chain exclusive distribution partnerships.
- Silicone finger brush convergence:Integration of food-grade elastomer molding with antimicrobial additive technology enables birth-to-toddler product continuity, extending customer lifetime value.
- EU Green Deal packaging mandates:Recyclable mono-material tube requirements accelerate R&D investment in barrier-coated paper solutions, rewarding first-movers with retail listing preference.
Industry Challenges
- Pediatric toxicology expertise scarcity:Formulation safety assessment for accidental ingestion scenarios requires specialized contract research organizations, elongating development timelines and inflating fixed costs.
- ISO 20126 third-party certification backlog:Accredited laboratory capacity constraints delay toothbrush safety testing, compressing seasonal launch windows and inventory planning precision.
- Legacy ERP integration with DTC fulfillment:Real-time inventory synchronization between wholesale retail systems and direct-to-consumer warehouses demands middleware investment that mid-cap brands struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Oral Care Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Toothbrush, Mouthwash, Teething Gel Age Group: Infants, Toddlers, Preschoolers, Newborns Ingredient Type: Natural, Fluoride-Free, Antimicrobial, Organic Distribution Channel: Retail Stores, Online, Pharmacies, Supermarkets |
| Companies Covered | Procter & Gamble, Colgate-Palmolive Company, Unilever, Johnson & Johnson, Pigeon Corporation, Church & Dwight Co., Inc., GlaxoSmithKline PLC, Lion Corporation, Sunstar Suisse SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Oral Care Market Emerging Trajectories
Formulation chemistry, regulatory disclosure mandates, and parental purchasing behavior are converging to reshape product architecture and channel economics simultaneously. These forces compress traditional competitive advantages while elevating transparency and traceability as differentiators.
Biodegradable bamboo fiber handles paired with castor-oil-derived bristle polymers are collapsing the cost-performance gap with petroleum-based alternatives. Premium eco-conscious parents in Germany and California are adopting these SKUs at twice the rate of conventional plastic brushes, forcing mass-market brands to absorb green-premium pricing or cede shelf space to specialist entrants.
REACH ingredient disclosure requirements are mandating full supply-chain transparency for surfactants and preservatives used in infant formulations. European manufacturers must now document sub-supplier identities and batch-level testing, raising compliance costs while creating competitive separation between integrated producers and brand-marketing intermediaries dependent on contract manufacturing.
Pharmacy-first buyers are migrating to telehealth-integrated subscription platforms where pediatric dentist video consultations bundle with automated replenishment. This channel shift is most pronounced in South Korea and urban China, where MFDS-regulated products combine with digital health ecosystems to disintermediate traditional retail discovery and trust-building functions.
Baby Oral Care Market Segmentation
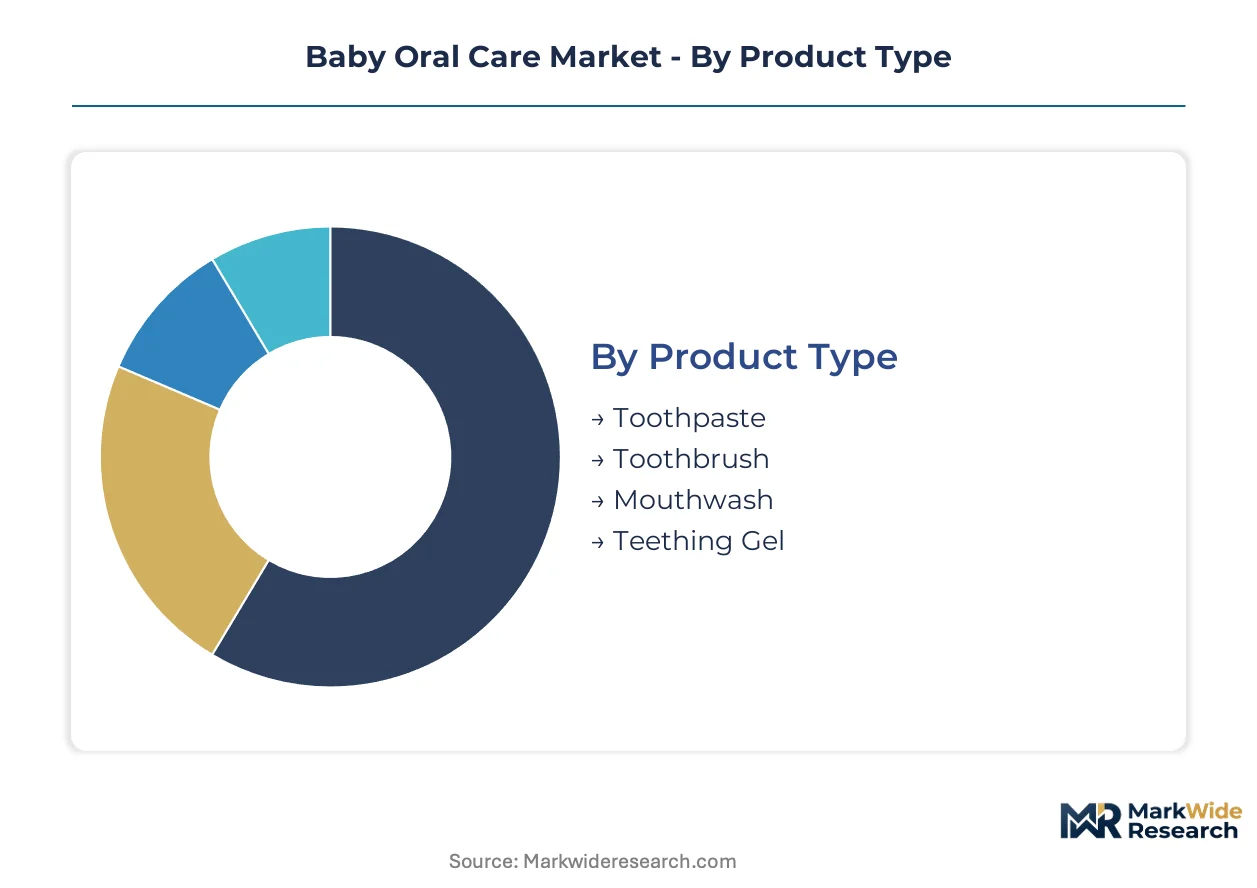
Baby oral care segmentation reflects distinct developmental needs, parental safety priorities, and channel access patterns that shape formulation chemistry and packaging design. Manufacturers calibrate product architectures across these dimensions to capture recurring purchase cycles from birth through early childhood.
Product Type:
Use-case spectrum spans preventive daily hygiene through acute symptom relief, with each format demanding specialized regulatory pathways and manufacturing competencies.
- Toothpaste:Age-calibrated fluoride concentrations and low-foam surfactant systems address accidental ingestion risks while delivering anticavity efficacy. Millennial parents in Germany and California are shifting volume toward fluoride-free and natural-ingredient variants as EFSA guidelines clarify safe exposure thresholds.
- Toothbrush:Extra-soft bristle arrays and ergonomic handle geometries accommodate developing motor skills and delicate gingival tissue. China's tier-one cities concentrate demand for premium imported designs with antimicrobial additive technology and food-grade elastomer components.
- Mouthwash:Alcohol-free formulations with controlled flavor intensity target preschool-aged children establishing rinse-and-spit behaviors.
- Teething Gel:Topical anesthetic and homeopathic formulations provide transient relief during primary dentition eruption phases.
Established volume favors toothpaste; emerging adoption favors toothbrush as replacement cycles accelerate and premium positioning expands.
Age Group:
Cost tier stratification separates mass-market newborn essentials from premium toddler and preschooler formulations with enhanced functional claims.
- Infants:Silicone finger brushes and gauze-based cleaning systems predominate before first tooth eruption, with pharmacy channel control dominating trust-sensitive first purchases.
- Toddlers:Training toothbrushes with safety shields and fruit-flavored pastes dominate volume as independent brushing behaviors emerge. Subscription direct-to-consumer models are capturing recurring revenue in South Korea and urban China through telehealth-integrated platforms.
- Preschoolers:Character-licensed designs and reward-system packaging sustain engagement through the 3-5 year window where parental supervision remains critical.
- Newborns:Gum wipes and oral cleansing pads address pre-dentition hygiene protocols, particularly in Asian markets with established traditional infant care practices.
Toddler segment anchors current revenue concentration; infant applications are climbing the fastest as silicone elastomer technology enables birth-to-toddler product continuity.
Ingredient Type:
Margin expansion concentrates in certified-natural and specialty-positioned formulations as parental safety scrutiny intensifies.
- Natural:Plant-derived surfactants, natural sweeteners, and botanical extracts replace synthetic chemistry. REACH disclosure mandates in Europe are forcing full supply-chain transparency that separates integrated producers from brand-marketing intermediaries dependent on contract manufacturing.
- Fluoride-Free:Xylitol and calcium phosphate alternatives address parental anxiety around early exposure. Sourcing concentration in Chinese and Finnish birch processing facilities exposes formulation costs to agricultural commodity volatility.
- Antimicrobial:Silver-ion and zinc-based additives target bacterial load reduction in high-caries-risk populations.
- Organic:Third-party certified ingredient sourcing commands shelf-space premiums in German and Californian retail environments.
Natural certification captures margin leadership; fluoride-free positioning is gaining share fastest as millennial preference reshapes purchasing criteria.
Distribution Channel:
Customer type and purchase occasion stratify across impulse retail, planned pharmacy consultation, and automated replenishment modalities.
- Retail Stores:Mass-market penetration depends on shelf-space negotiations with supermarket and pharmacy chains, with Procter & Gamble leveraging historic relationships to defend position.
- Online:Direct-to-consumer subscriptions and marketplace platforms are expanding most quickly in South Korea and urban China, where MFDS-regulated products integrate with digital health ecosystems to disintermediate traditional discovery functions.
- Pharmacies:Pediatric dentist endorsement and professional recommendation sustain trust-building functions for first-time buyers across European and Asian markets.
- Supermarkets:Price-promotional velocity and impulse purchase placement drive volume in North American and European mass-market tiers.
Pharmacy and supermarket channels anchor established volume; online distribution is expanding most quickly as logistics infrastructure and content marketing capabilities tilt competitive dynamics toward digital-native entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in baby oral care tilt toward net-importing developed markets with stringent safety standards, while manufacturing clusters concentrate in Asia-Pacific economies with established personal care infrastructure. Currency-adjusted purchasing power and regulatory compliance costs determine regional profitability tiers.
United States
Millennial parental preference for fluoride-free formulations drives SKU proliferation across pharmacy and subscription channels. FDA over-the-counter drug classification for therapeutic toothpaste claims shapes formulation strategy and margin structure. Greater Boston and Southern California concentrate demand for premium natural-ingredient imports.
Germany
REACH disclosure mandates and EU Green Deal packaging requirements accelerate R&D investment in recyclable mono-material tubes. EFSA pediatric fluoride exposure guidelines provide regulatory clarity that expands addressable market for age-calibrated products. Bavaria anchors manufacturing for barrier-coated paper packaging innovations.
China
The three-child policy expands birth cohorts in tier-one cities, concentrating demand for premium imported formulations. NMPA registration requirements and GB standards testing create barrier-protected market access for compliant multinationals. Shanghai and Beijing dominate telehealth-integrated subscription platform adoption.
Japan
MFDS-equivalent standards under PMDA oversight govern infant oral care safety with emphasis on accidental ingestion toxicology. Silicone elastomer technology leadership enables birth-to-toddler product continuity. Osaka-Kobe manufacturing corridor specializes in food-grade polymer molding for finger brush applications.
India
Rising disposable income in tier-two cities creates whitespace for pharmacy-chain exclusive distribution partnerships. BIS standards compliance remains fragmented across state-level enforcement. Surat, Indore, and Kochi emerge as priority markets for pediatric dentist network penetration.
Baby Oral Care Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material science and contract manufacturing. The vendor base stratifies across multinational consumer goods conglomerates with pharmacy shelf dominance, regional specialists with channel-specific control, and digital-native entrants capturing subscription revenue. Three archetypes predominate: retail-anchored mass-market defenders, pediatric-endorsed premium formulators, and direct-to-consumer data aggregators. Competitive moves center on clean-label pipeline acceleration and logistics infrastructure investment for recurring revenue capture.
Among multinational platform integrators, Procter & Gamble and Colgate-Palmolive occupy positions exemplifying retail-anchored and endorsement-driven archetypes respectively. Pigeon Corporation represents the Asia-Pacific regional specialist model with concentrated channel control. These three entities anchor competitive dynamics across mass-market penetration, professional recommendation networks, and geographic market defense.
| Leading Market Players |
|---|
| Procter & Gamble |
| Colgate-Palmolive Company |
| Unilever |
| Johnson & Johnson |
| Pigeon Corporation |
| Church & Dwight Co., Inc. |
| GlaxoSmithKline PLC |
| Lion Corporation |
| Sunstar Suisse SA |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese xylitol processing facilities is compressing natural sweetener contract rates while simultaneously forcing Finnish birch refiners to idle capacity, creating divergent supplier behavior that rewards buyers with multi-source qualification and punishes single-source dependence with volatile spot exposure.
Pricing Analysis
Millennial parents anchor pricing stratification across premium, standard, and economy tiers in baby oral care. Three-tier pricing structure separates fluoride-free natural formulations with EFSA-aligned certification from mass-market pharmacy SKUs and private-label supermarket alternatives. Pricing pressure stems from xylitol commodity volatility concentrated in Chinese and Finnish supply nodes. Pharmacy channel buyers exhibit lowest price sensitivity due to pediatric dentist endorsement dependency, while supermarket impulse purchasers drive volume through promotional elasticity.
Supply Chain Analysis
Birch-derived xylitol feedstock and food-grade silicone elastomer resins constitute critical upstream dependencies for natural-formulation and finger brush segments respectively. Manufacturing capacity clusters in China for sweetener processing, Japan for polymer molding, and Germany for barrier-coated paper packaging innovation. Single-source vulnerability in xylitol extraction exposes formulation costs to agricultural yield fluctuation and geopolitical logistics friction. Distribution runs through pharmacy-controlled professional recommendation networks for first-time buyers, with direct-to-consumer subscription platforms capturing recurring replenishment in South Korea and urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone elastomer convergence with antimicrobial additive technology is disrupting traditional toothbrush replacement economics, creating acceleration vectors for brands that capture birth-to-toddler product continuity.
For Market Incumbents: Insulate pharmacy shelf relationships through accelerated clean-label pipeline investment and exclusive distribution partnerships with pediatric dentist networks. Digital-native subscription entrants threaten recurring revenue capture in South Korea and urban China; backward integration into food-grade polymer molding secures supply continuity for finger brush SKU proliferation. For New Entrants and Emerging Players: Pursue tier-two Indian city whitespace through pharmacy-chain exclusive distribution partnerships in Surat, Indore, and Kochi where pediatric dentist networks remain underpenetrated. Telehealth-integrated subscription platforms offer the most penetrable go-to-market angle for capturing millennial parental preference for fluoride-free natural formulations. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue consumer staple play because subscription direct-to-consumer models generate first-party data assets and predictable cash flow characteristics. Acquisition targets should demonstrate logistics infrastructure for automated replenishment and content marketing capabilities. The signal to watch is NMPA registration backlog duration in China as indicator of compliant multinational access premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Captures recurring revenue and first-party data from millennial parents in South Korea and urban China. |
| Fluoride-Free Formulation Pipeline | Aligns product architecture with EFSA pediatric exposure guidelines and natural-ingredient preference shifts. |
| Silicone Elastomer Technology Integration | Enables birth-to-toddler product continuity through antimicrobial additive convergence in finger brush applications. |
| Pharmacy-Chain Exclusive Distribution | Secures trust-building touchpoints for first-time buyers in underpenetrated Indian tier-two cities. |
| Barrier-Coated Paper Packaging R&D | Anticipates EU Green Deal mono-material tube mandates and captures retail listing preference in Germany. |
Methodological Framework
A spread of perspectives from brand managers at multinational consumer goods conglomerates, category buyers at pharmacy chains, pediatric dentists, supply planners at silicone molding facilities, and regulatory affairs specialists converged on the working assumptions driving this analysis. Secondary validation drew from FDA over-the-counter drug classification filings, EFSA pediatric exposure guideline documentation, NMPA registration databases, Nielsen retail audit data, and customs import records. Bottom-up SKU-level volume aggregation and top-down macroeconomic adjustment produced convergent estimates.
Demand-supply balance modeling across product type, age group, ingredient certification tier, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs emerged from segment-level growth rate synthesis and cross-validation against demographic birth cohort projections and regulatory timeline assumptions. Xylitol commodity price trajectories and telehealth platform adoption curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in birth rate trends, disposable income growth in Chinese tier-one cities, or agricultural yield volatility for birch feedstock would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance cost evolution and channel migration velocity. Cross-checking against pediatric dentist prescribing database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Dry Mouth Relief Market
Oral Care
United States Oral Hygiene Market
Oral Care
Oral Thin Films Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Us Oral Care Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Oral Irrigator Market
Oral Care
Global Halitosis Market
Oral Care
Toothcare Market
Oral Care
Manual Toothbrush Market
Oral Care
South America Oral Care Market
Oral Care
Oral Rinse Market
Oral Care
Tongue Cleaner Market
Oral Care
Oral Antiseptics Market
Oral Care
Halitosis Treatment Market
Oral Care
Herbal Toothpaste Market