
 Motor Lamination Market | 2026-2036
Motor Lamination Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Lamination Market Intelligence
Expertise in high-frequency magnetic material stamping and bonding is rotating towards designs that minimize eddy current losses in high-speed motors. Eurogroup S.P.A leverages its extensive manufacturing footprint to serve European automotive clients. Pitti Laminations Ltd. specializes in precision laminations for industrial equipment across Asia. Tempel positions itself with advanced electrical steel processing capabilities for diverse end-user industries, including power generation and industrial automation, competing on material science innovation.
Motor lamination involves stacking thin sheets of electrical steel or other magnetic materials to form the core of a motor's stator and rotor. This construction method is critical for limiting the formation of parasitic eddy currents, which improves the motor's overall energy efficiency and thermal performance. Silicon Steel remains the dominant material due to its cost-effectiveness, while nanocrystalline alloys see adoption in high-performance applications. Demand from Electric Vehicle Manufacturers and Renewable Energy Systems represents the fastest-growing segments.
Regulations such as the EU's Ecodesign Directive and energy efficiency standards from the US EPA mandate higher performance levels for electric motors. Concurrently, China's dual carbon goals accelerate the transition to more efficient industrial equipment, directly influencing lamination material and design choices. The critical decision for manufacturers will be balancing material cost against the performance gains required by tightening international efficiency mandates and evolving end-user expectations.
Market Dynamics
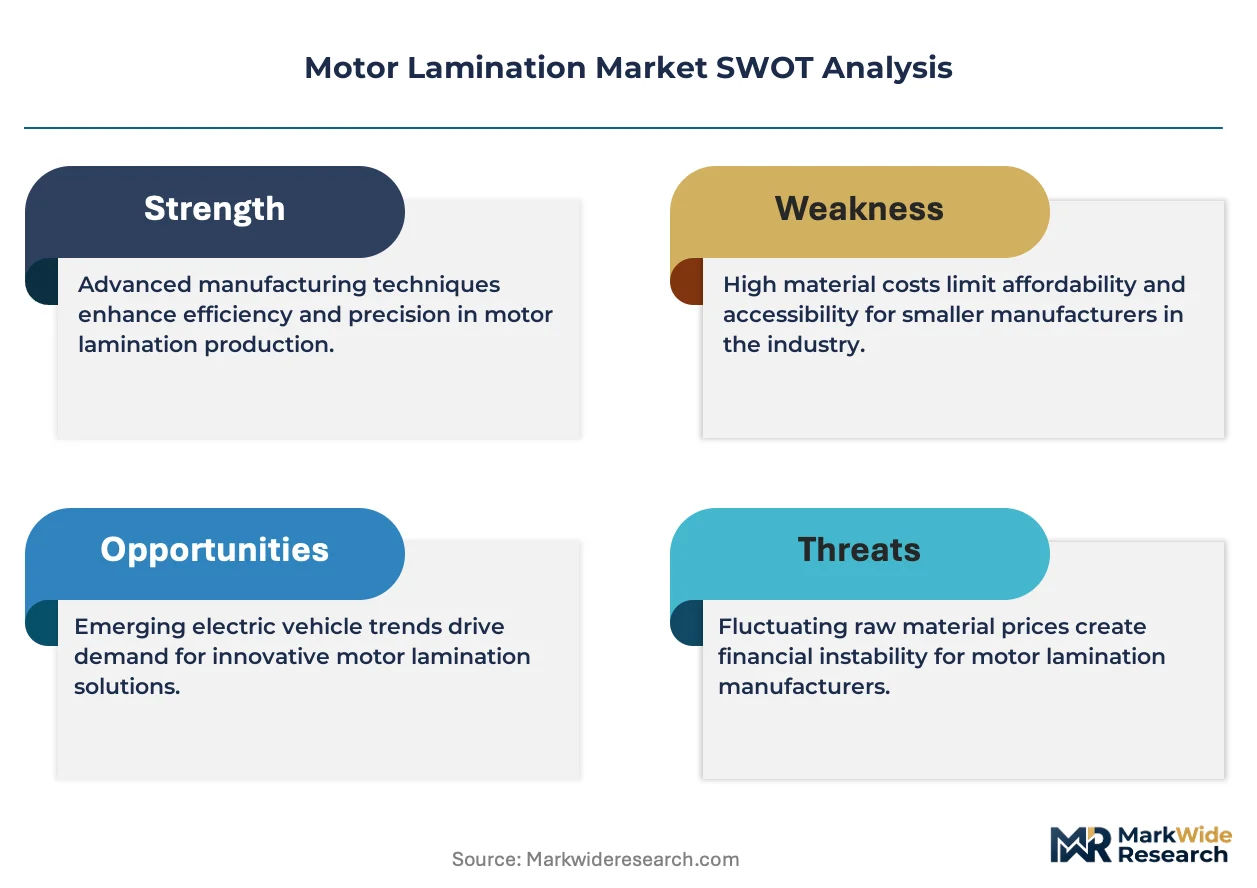
The central tension in the motor lamination market is the conflict between the performance gains demanded by electric vehicle manufacturers and stringent energy regulations, and the volatile cost and concentrated supply of high-performance electrical steel materials.
Growth Catalysts
- Electric Vehicle Expansion:Demand from automotive OEMs for lighter, more powerful, and efficient motors for battery electric vehicles (BEVs) and plug-in hybrid electric vehicles (PHEVs) is a primary growth engine for advanced lamination solutions.
- Regulatory Mandates:Policies such as the EU's Ecodesign Directive and China's dual carbon goals are compelling industrial and consumer appliance sectors to adopt motors with higher efficiency ratings, directly boosting demand for superior lamination materials.
- Material Innovation:The development of nanocrystalline and amorphous alloys, offering lower core losses at high frequencies, creates new performance tiers for specialized applications like aerospace and high-speed industrial machinery.
Market Restraints
- Material Cost Volatility:The price of high-grade electrical steel, the primary raw material, is subject to significant fluctuations based on global supply, tariffs, and input commodity costs, creating margin pressure for lamination manufacturers.
- Supply Chain Concentration:Production of the highest-purity, grain-oriented electrical steels is concentrated among a few suppliers, primarily in Asia, posing a supply chain risk for manufacturers in Europe and North America.
- Technical Processing Challenges:Processing ultrathin gauge and brittle materials like amorphous alloys requires specialized, high-cost stamping or laser cutting equipment and expertise, limiting widespread adoption and increasing production costs.
Strategic Opportunities
- Renewable Energy Systems:The increasing scale of wind turbine generators and solar tracking systems presents an opportunity for large-diameter, high-efficiency laminations designed for power generation applications, a distinct segment from traction motors.
- Advanced Bonding Technologies:Developing and patenting novel adhesive bonding techniques that improve stacking factor and reduce eddy current losses offers a path to differentiation beyond simple material composition or stamping precision. *Industrial Automation: The expansion of robotics and automated manufacturing in emerging economies creates a new market for precision laminations in servo motors and actuators, where efficiency and thermal performance are critical.
Industry Challenges
- Capital Equipment Intensity:The need for continuous investment in high-precision, high-speed presses, laser cutting systems, and automated stacking lines creates a significant capital barrier to entry and puts pressure on smaller manufacturers.
- Specialized Talent Scarcity:A shortage of engineers and technicians with combined expertise in magnetic materials science, high-speed motor design, and precision manufacturing processes hinders product development and process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Lamination Market |
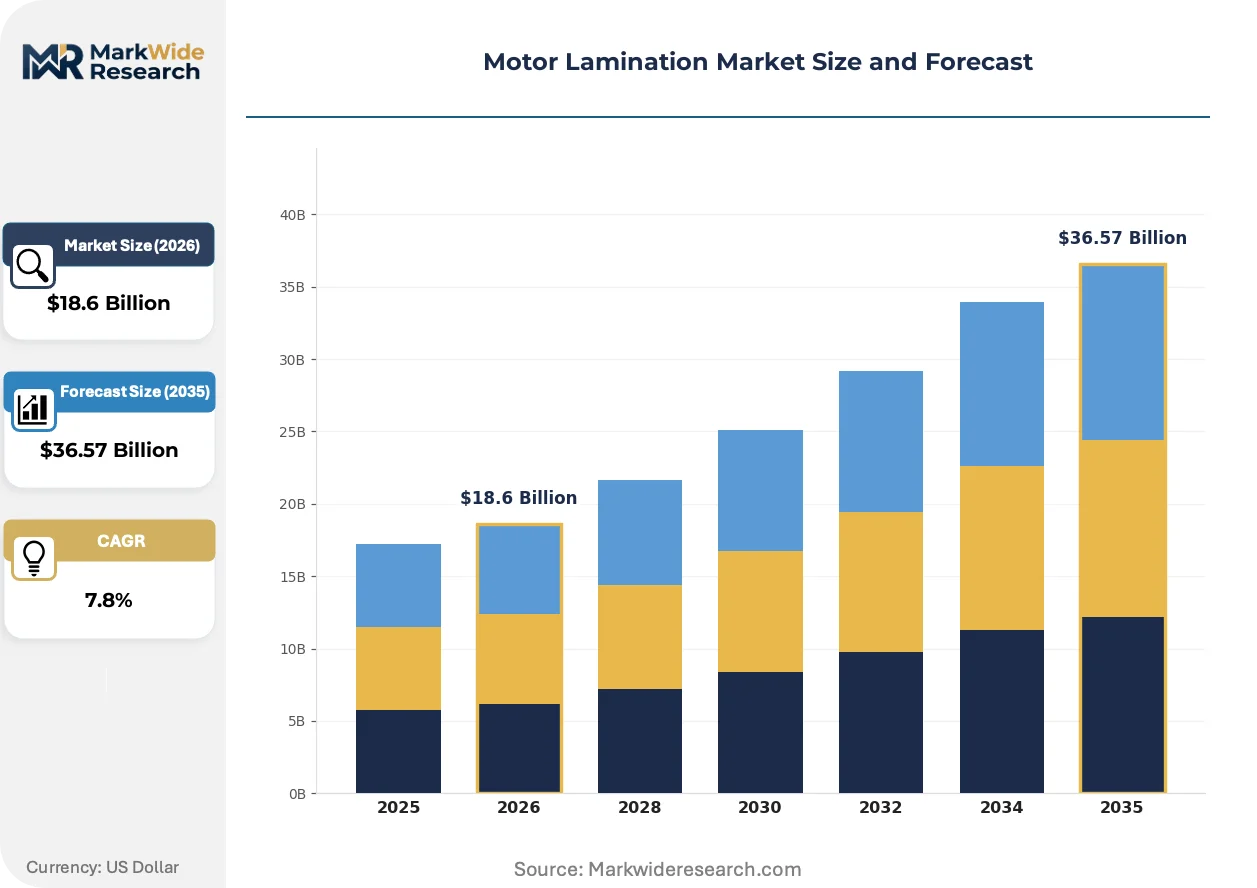
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $36.57 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motor Lamination, Generator Lamination, Transformer Lamination, Inductor Lamination Material: Silicon Steel, Electrical Steel, Amorphous Metal, Ferrite, Nanocrystalline Alloy Application: Home Appliances, Industrial Equipment, Renewable Energy Systems, Power Tools, HVAC Systems End User Industry: Manufacturing OEMs, Electric Vehicle Manufacturers, Aerospace Fabricators, Consumer Electronics Makers |
| Companies Covered | Tempel, Partzsch Elektromotoren E.K., Eurogroup S.P.A, R. Bourgeois, Polaris Laser Laminations, LLC., Lake Air Companies, Pitti Laminations Ltd., Thomas Laminations, Lamination Specialties Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Lamination Market Strategic Shifts & Innovations
Material science advancements and global energy efficiency mandates are compelling a fundamental shift in lamination design, material selection, and manufacturing processes. This evolution is moving the industry beyond cost-focused commodity production toward performance-driven, application-specific solutions.
Technology and Material Evolution
Advanced bonding technologies, which join individual laminations, directly influence a motor's magnetic flux leakage and mechanical stability. High-performance sectors like electric mobility are adopting adhesive bonding to reduce interlaminar losses. This trend is bifurcating the market, creating a division between premium, adhesively-bonded stacks and lower-cost, mechanically interlocked cores for general industrial use.
Regulatory and Standards Influence
Regulatory frameworks like the EU's Ecodesign Directive and efficiency standards from the US EPA are setting higher minimum performance levels for electric motors. These mandates compel the use of thinner gauge electrical steels and more precise stamping to mitigate energy losses. The industrial motor segment is most directly impacted, accelerating the phase-out of less efficient, thicker lamination designs.
Evolving Procurement Models
Co-development models are replacing traditional transactional purchasing between motor OEMs and lamination suppliers. This collaborative approach allows for the creation of custom lamination geometries optimized for specific torque, speed, and efficiency profiles. The practice is most prominent within the automotive sector, especially in Germany and China, where EV manufacturers seek a competitive edge through bespoke motor core designs.
Motor Lamination Market Segmentation
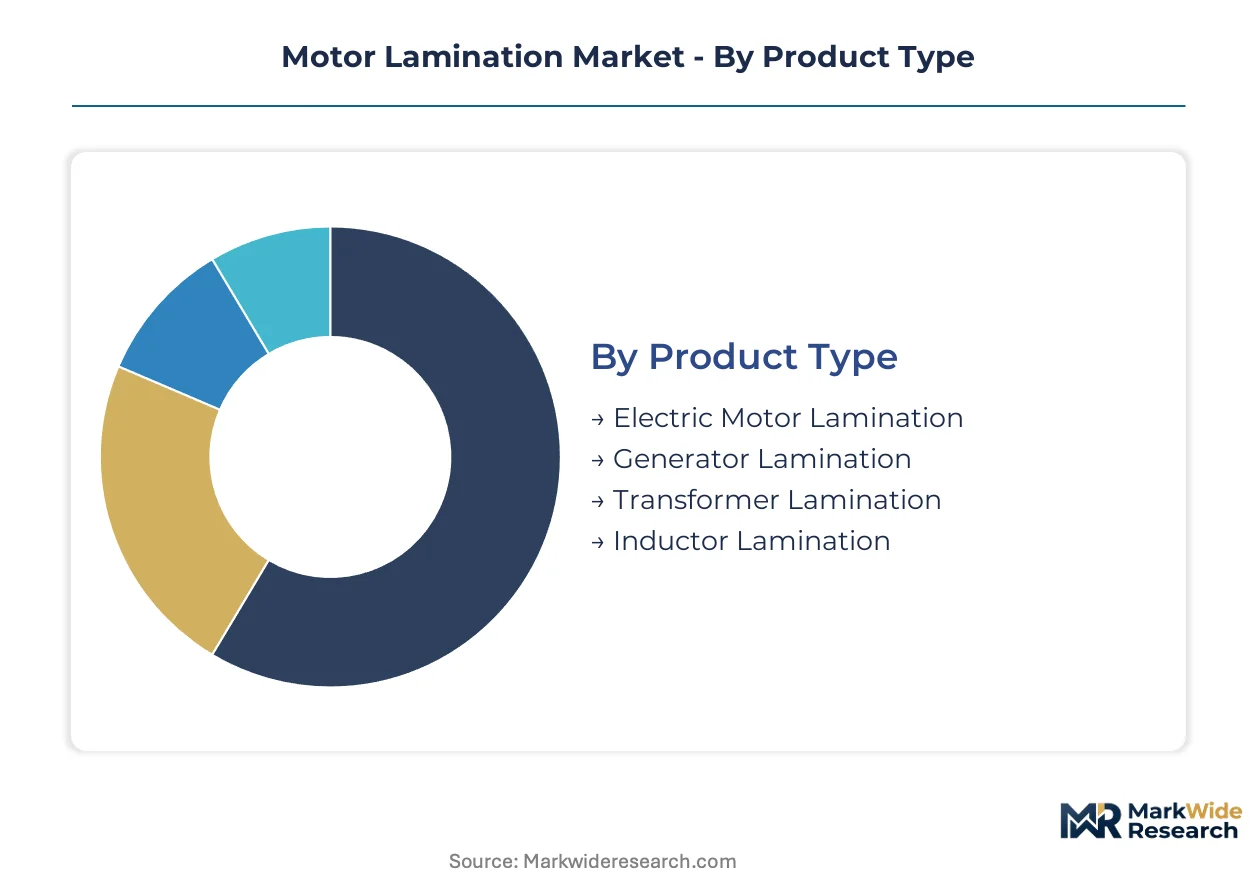
Motor lamination market segmentation highlights diverse product requirements and material science impacts. This analysis differentiates core technologies, end-use applications, and material compositions. Understanding these distinct segments helps manufacturers align production capabilities with specific market demands. Each segment faces unique regulatory pressures and performance expectations.
Product Type:
Regulatory frameworks increasingly differentiate lamination product types based on their specific energy efficiency impact.
- Electric Motor Lamination:These laminations form the core of electric motors, crucial for converting electrical energy into mechanical motion. Demand concentrates among Electric Vehicle Manufacturers seeking higher power density and reduced eddy current losses.
- Generator Lamination:Designed for electrical generators, these laminations facilitate the efficient conversion of mechanical energy into electrical power. Renewable Energy Systems, particularly wind turbine manufacturers, drive demand for large-diameter, high-efficiency generator laminations.
- Transformer Lamination:These components are essential for power transformers, enabling efficient voltage conversion with minimal energy loss.
- Inductor Lamination:Used in inductors, these laminations manage magnetic fields to control current flow in various electronic circuits.
Established volume favors Transformer Lamination; emerging adoption favors Electric Motor Lamination.
Material:
Material selection for motor laminations reflects a spectrum of cost-performance trade-offs.
- Silicon Steel:This material, primarily composed of iron and silicon, offers good magnetic properties and cost-effectiveness for general motor applications. Demand remains strong in industrial equipment manufacturing due to its balance of performance and affordability.
- Nanocrystalline Alloy:Characterized by ultra-fine grain structures, these alloys exhibit extremely low core losses and high permeability at high frequencies. Aerospace fabricators and specialized high-speed industrial machinery manufacturers drive demand for these advanced materials.
- Electrical Steel:A broad category encompassing various iron alloys optimized for magnetic properties, widely used in diverse motor and transformer applications.
- Amorphous Metal:These non-crystalline alloys offer very low core losses, making them suitable for high-efficiency power conversion.
- Ferrite:Ceramic magnetic materials, often used in high-frequency applications where lower magnetic flux density is acceptable.
Supply concentration for high-purity materials influences the availability of Amorphous Metal; broader availability characterizes Electrical Steel.
Application:
The diverse applications of motor laminations dictate specific performance and durability requirements.
- Industrial Equipment:This segment includes motors for pumps, compressors, conveyors, and various manufacturing machinery, requiring robust and efficient lamination solutions. China's dual carbon goals accelerate demand for higher efficiency industrial motors.
- Renewable Energy Systems:Laminations are critical for generators in wind turbines and motors in solar tracking systems, demanding high efficiency and large-diameter designs. The EU Green Deal mandates for sustainable energy production drive this segment's expansion.
- Home Appliances:Laminations in washing machines, refrigerators, and vacuum cleaners prioritize cost-effectiveness and quiet operation.
- Power Tools:Compact and efficient laminations are essential for drills, saws, and other portable power equipment.
- HVAC Systems:Motors in heating, ventilation, and air conditioning units require laminations optimized for continuous, reliable operation.
Performance drivers for Renewable Energy Systems focus on efficiency; Home Appliances prioritize cost and quietness.
End User Industry:
Different end-user industries exhibit distinct procurement models and technical specifications for motor laminations.
- Electric Vehicle Manufacturers:These OEMs require high-performance, lightweight laminations for traction motors in battery electric vehicles and plug-in hybrids. German and Chinese automotive manufacturers engage in co-development models to gain a competitive edge.
- Manufacturing OEMs:This segment encompasses a broad range of original equipment manufacturers producing industrial machinery, robotics, and automation systems. These OEMs seek durable and efficient lamination solutions for their diverse product portfolios.
- Aerospace Fabricators:These manufacturers demand ultra-lightweight and high-temperature resistant laminations for specialized aircraft components.
- Consumer Electronics Makers:This industry utilizes compact laminations for small motors in devices like drones, cameras, and personal gadgets.
Electric Vehicle Manufacturers are expanding most quickly; Consumer Electronics Makers maintain consistent demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power asymmetry characterizes the Motor Lamination market, with key material supply concentration in Asian economies influencing global costs. Demand centers in Europe and North America often face higher material acquisition expenses for advanced lamination solutions. This dynamic shapes manufacturing strategies and procurement models across continents.
Germany
German automotive manufacturers drive demand for high-efficiency laminations in electric vehicles and industrial automation. The EU's Ecodesign Directive mandates superior performance for electric motors. The Stuttgart region, a hub for automotive OEMs, engages in co-development for custom motor core designs.
China
Chinese Electric Vehicle Manufacturers drive demand for advanced motor laminations, prioritizing efficiency. China's dual carbon goals accelerate the transition to more efficient industrial equipment. The Yangtze River Delta, a major EV production center, sees collaborative efforts for bespoke motor core development.
United States
United States automotive OEMs require advanced lamination solutions for electric vehicles and plug-in hybrids. The US EPA's energy efficiency standards compel industrial and consumer appliance sectors to adopt higher-rated motors. Michigan's automotive cluster develops lightweight, high-performance laminations for traction motors.
Japan
Japanese manufacturers of high-speed industrial machinery and specialized applications seek advanced alloy laminations. METI initiatives promote energy efficiency, stimulating demand for superior magnetic materials. The Kanto region, a center for material science innovation, leads in developing advanced electrical steel processing capabilities.
India
India's expanding industrial equipment sector and nascent EV market contribute to growing demand for cost-effective, efficient laminations. BIS standards for motor efficiency compel the adoption of better lamination materials. Maharashtra, a prominent industrial manufacturing hub, is witnessing increased investment in local lamination production capabilities.
Motor Lamination Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the motor lamination market. The industry exhibits a tiered structure, with specialized material science innovators at the premium end and high-volume, cost-efficient manufacturers forming the broader base. Strategic archetypes include precision stamping specialists, advanced material processors, and integrated core solution providers. Competitive moves frequently involve capacity expansion to meet EV demand and strategic partnerships for material supply security.
Specialists in advanced material processing and electrical steel innovation, such as Tempel, occupy a position at the premium end, emphasizing material science and diverse end-user industries. Meanwhile, Eurogroup S.P.A, with its extensive manufacturing footprint, exemplifies a European-focused player leveraging scale to serve automotive clients. Pitti Laminations Ltd. represents a precision lamination provider catering to industrial equipment across Asia, highlighting regional specialization and application-specific expertise. These companies collectively illustrate the varied strategic approaches to market penetration and value creation.
| Leading Market Players |
|---|
| Tempel |
| Partzsch Elektromotoren E.K. |
| Eurogroup S.P.A |
| R. Bourgeois |
| Polaris Laser Laminations, LLC. |
| Lake Air Companies |
| Pitti Laminations Ltd. |
| Thomas Laminations |
| Lamination Specialties Incorporated |
| Others |
Cost & Logistics Intelligence
The EU's Ecodesign Directive gates both the qualification of advanced lamination materials and the price differentiation for high-efficiency motor cores. This directly impacts manufacturing strategies and procurement models.
Pricing Analysis
Configured-to-order pricing for specialized motor laminations commands a premium over standard, off-the-shelf offerings. The dominant pricing structure involves contract-based long-term offtake agreements, particularly for high-volume automotive clients. Price differentiation stems from the customization level required for specific torque and speed profiles and the quality grade of electrical steel. Margin pressure arises from volatile raw material costs, particularly for high-purity electrical steel. Home appliance manufacturers exhibit the highest price sensitivity, while Electric Vehicle Manufacturers are less sensitive, prioritizing performance gains.
Supply Chain Analysis
Port congestion in major Asian trade lanes impacts the inbound logistics costs for high-grade electrical steel. Supply concentration for the highest-purity, grain-oriented electrical steels is notable across China, Japan, and South Korea. The market relies heavily on specific raw material inputs like silicon and specialized nanocrystalline alloys. A key supply chain risk is single-source vulnerability for advanced magnetic materials. Downstream distribution runs predominantly through direct sales channels to large Original Equipment Manufacturers and specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Motor Lamination market offers a service-attach opportunity, with co-development and bespoke optimization services expanding faster than core lamination sales due to specific performance requirements.
For Market Incumbents: Shield market share through continuous investment in advanced bonding technologies that reduce interlaminar losses. Counter emerging competition by expanding capacity in high-precision laser cutting equipment for ultrathin gauge materials. The primary threat stems from material cost volatility. Vertical integration into electrical steel processing offers a lever to secure supply and manage costs.
For New Entrants and Emerging Players: Anchor in niche applications like aerospace fabricators or specialized high-speed industrial machinery, where performance and material science innovation are critical. Target underpenetrated segments that require specific expertise in amorphous or nanocrystalline alloys. A strong go-to-market angle involves collaborative research and development with specialized Original Equipment Manufacturers, focusing on bespoke material solutions.
For Investors and Strategic Acquirers: The EU Green Deal reshapes the acquisition landscape, favoring firms with proven capabilities in high-efficiency lamination solutions. Long-term viability (5-10 years) favors specialists with intellectual property in advanced material processing and bonding. Acquisition targets should include precision stamping specialists with strong relationships with Electric Vehicle Manufacturers. Increased M&A activity for companies offering advanced electrical steel processing capabilities is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Addresses concentrated supply of high-grade electrical steel for global demand. |
| Advanced Bonding Technology R&D | Reduces eddy current losses in high-speed electric vehicle motors. |
| Joint Venture for Electrical Steel | Secures stable supply amidst material cost volatility for lamination manufacturers. |
| Co-development with EV OEMs | Optimizes lamination geometries for bespoke motor designs, enhancing efficiency. |
| Investment in Laser Cutting | Enables processing of ultrathin gauge amorphous alloys for high-performance applications. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, government energy efficiency mandates, patent databases, and corporate financial filings. Primary interviews engaged motor design engineers, lamination procurement managers, material science researchers, and Electric Vehicle manufacturing heads. This approach utilized both bottom-up and top-down triangulation to ensure data accuracy and market coverage.
The analytical framework modeled segmentation dimensions including product type, material, application, end-user industry, and lamination thickness across the analysis window. Compound Annual Growth Rates were derived from historical trends and projected efficiency gains, considering the impact of regulatory frameworks. Key forecast inputs included Electric Vehicle production forecasts and renewable energy system installation targets.
Decision-makers should treat outputs as directional under base assumptions of stable material supply and consistent regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect these assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
RV Battery Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Snowplows Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Automotive Wheel Speed Sensor Market