
 Automotive Brake Valves Market | 2026-2036
Automotive Brake Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Valves Market Analysis
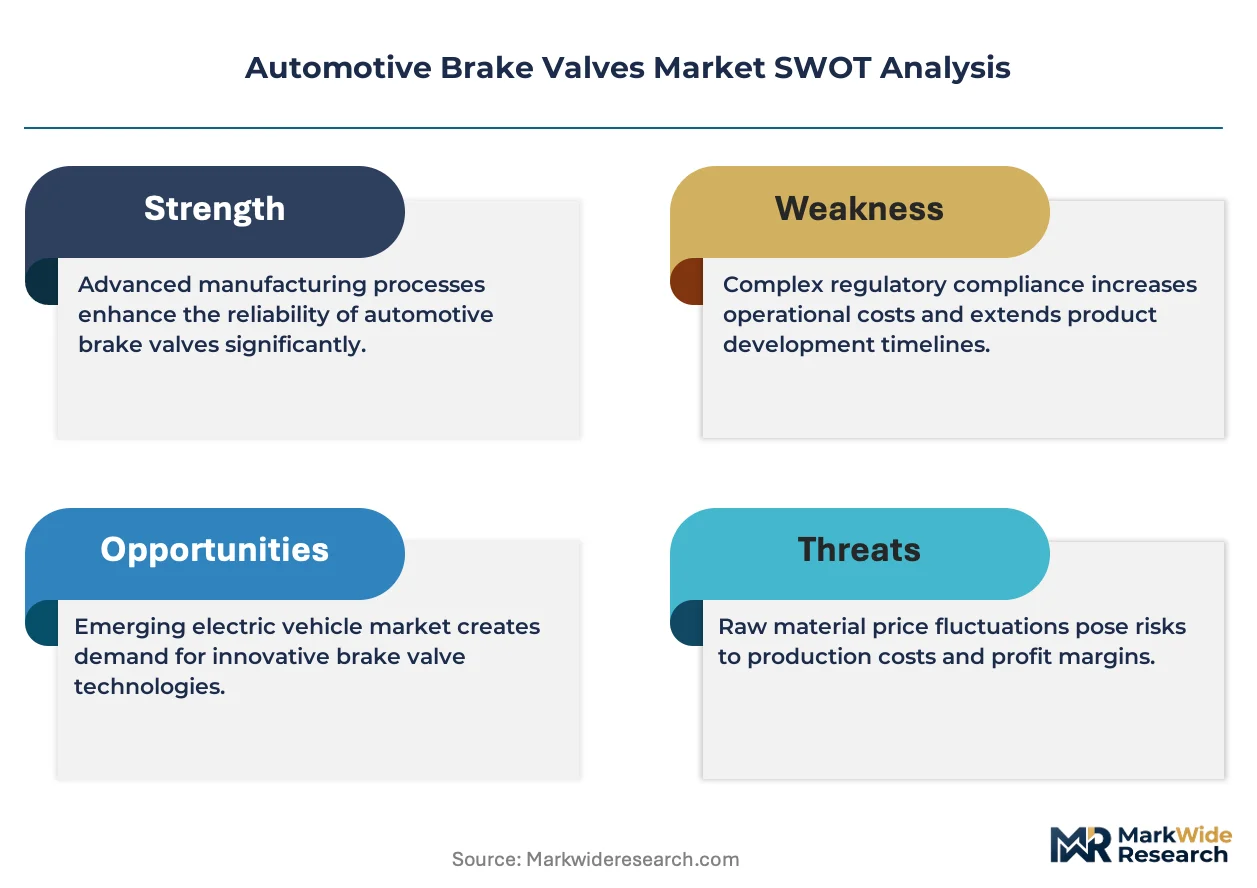
SAE J1939-compliant electronic control specifications are unwinding legacy pneumatic architectures across heavy-duty platforms. Robert Bosch GmbH leverages integrated mechatronics capabilities to anchor European OEM supply chains. Continental AG specializes in electro-hydraulic actuation modules for electric commercial vehicles. ZF Friedrichshafen AG dominates air brake valve production for North American truck manufacturers through its WABCO heritage.
Automotive brake valves modulate hydraulic or pneumatic pressure distribution to wheel cylinders and calipers, typically operating at pressures ranging from 8 to 13 bar in commercial air systems and 100 to 180 bar in passenger hydraulic circuits. Their primary purpose is to prevent wheel lock-up, balance braking force, and maintain vehicle stability under variable load conditions. Anti-lock valve configurations command premium positioning within OEM channels due to mandatory stability control integration. Electronic technology segments capture expanding margin pools as brake-by-wire architectures displace conventional hydraulics in electric vehicle platforms. Drum valve categories retain cost-sensitive aftermarket volume in emerging-market commercial fleets.
NHTSA Federal Motor Vehicle Safety Standards and ECE R13 homologation requirements mandate specific response times and pressure modulation accuracy for brake valves sold into regulated markets. EPA heavy-duty vehicle greenhouse gas rules indirectly shape valve specifications by pressuring weight reduction and friction optimization. China's MIIT new energy vehicle certification and GB/T braking standards impose additional testing protocols on suppliers targeting domestic OEM qualification. Stakeholders must monitor divergence between regional electromagnetic compatibility standards for electronic brake control modules.
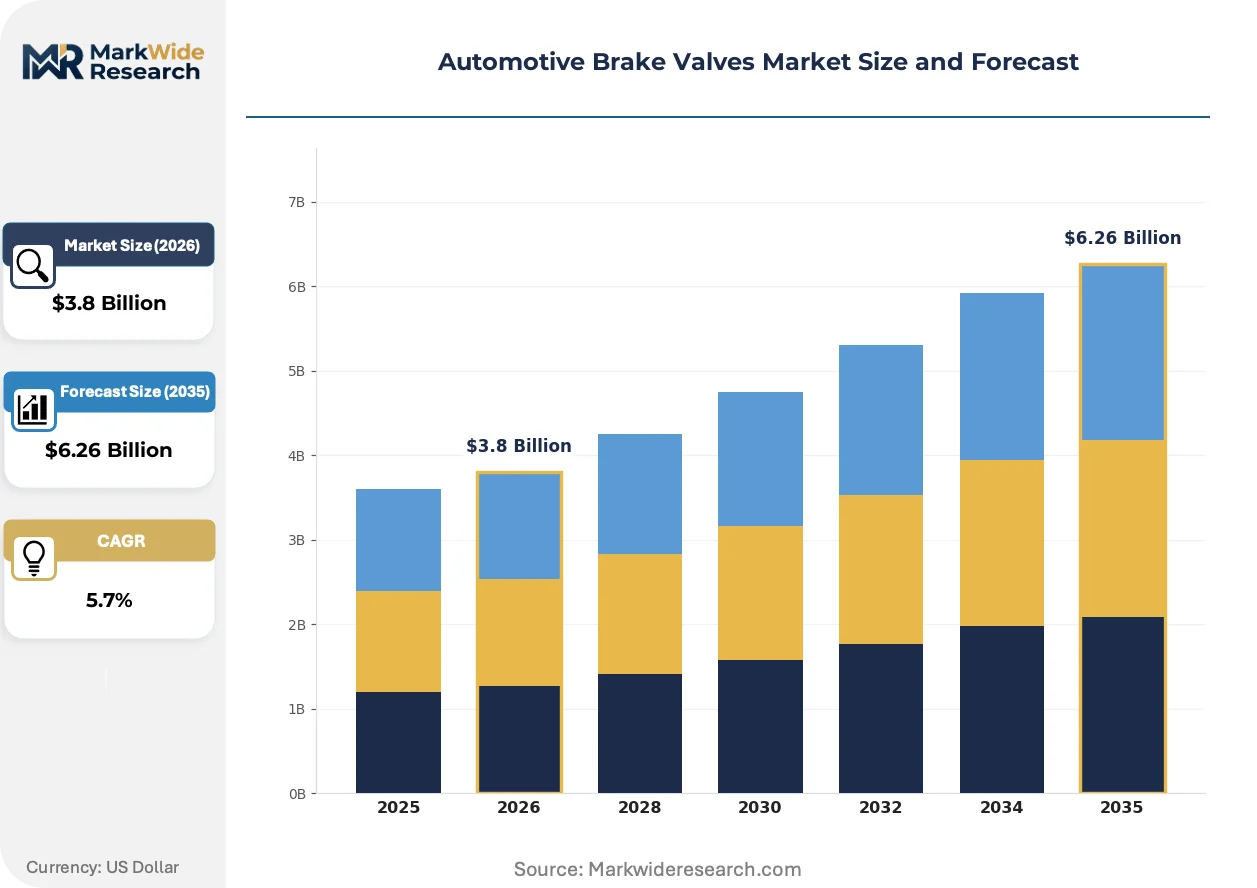
Market Dynamics
SAE J1939-compliant electronic brake valve architectures are decomposing legacy pneumatic systems across heavy-duty commercial platforms, forcing suppliers to reconfigure production footprints and R&D priorities around mechatronics integration rather than conventional machining.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standards:Mandated stability control integration across commercial vehicle classes creates compulsory demand for anti-lock valve configurations in US truck manufacturing.
- Electric commercial vehicle platforms:Brake-by-wire architectures in battery-electric trucks require electro-hydraulic actuation modules that eliminate pneumatic infrastructure entirely.
- Germany's automotive engineering corridor:Concentrated OEM engineering activity around Stuttgart and Munich accelerates specification cycles for next-generation valve systems.
Market Restraints
- Aluminum and copper input volatility:Cast valve housings and solenoid windings face margin compression from base metal price swings that suppliers cannot fully pass through.
- European supplier concentration:Mechatronics capability clusters heavily in southwestern Germany, creating geographic single-source risk for electronic brake module procurement.
- Pneumatic infrastructure lock-in:Emerging-market commercial fleets retain drum valve architectures due to maintenance ecosystem entrenchment and technician skill bases.
Strategic Opportunities
- India's commercial vehicle electrification:PLI scheme incentives for electric bus and truck manufacturing create qualification windows for brake-by-wire suppliers.
- EPA heavy-duty vehicle greenhouse gas rules:Weight reduction mandates indirectly favor compact electronic valve modules over bulky pneumatic assemblies.
- Over-the-air calibration channels:Software-defined brake control enables remote parameter updates, opening recurring revenue streams beyond hardware shipment.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D compliance for electronic brake control modules extends development cycles and strains validation resources.
- Legacy fleet interoperability:Mixed pneumatic-electronic architectures in retrofit applications create integration complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Valves Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc, Drum, Anti-lock, Proportioning Technology: Hydraulic, Pneumatic, Electro-mechanical, Electronic End User: Truck Manufacturers, Passenger Vehicles, Motorcycles, Heavy Equipment Application: OEM, Aftermarket, Racing, Fleet Vehicles |
| Companies Covered | Knorr-Bremse AG, Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, WABCO Holdings Inc., Aisin Corporation, Brembo S.p.A., Mando Corporation, Haldex AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Valves Market Emerging Trajectories
Electronic actuation is rewriting brake valve design priorities, compressing traditional component hierarchies and elevating software competence alongside fluid power engineering.
Electro-hydraulic brake valves is decomposing conventional master cylinder and booster assemblies into distributed actuator nodes. Electric truck manufacturers at Volvo and Daimler Truck are specifying integrated pedal simulators and wheel-end modules that eliminate vacuum dependence. This topology shift is decomposing the historical tiering between foundation brake suppliers and controls specialists.
ECE R13 homologation amendments are tightening response time tolerances for electronic brake control modules in European commercial vehicle certification. The industrial consequence is accelerated validation investment and closer OEM-supplier co-development relationships. North American truck manufacturers are responding by pre-qualifying European-certified designs to streamline parallel NHTSA submission.
Service contract unbundling is fragmenting traditional aftermarket relationships for brake valve replacement. Fleet maintenance providers are sourcing remanufactured electronic modules directly from specialized rebuilders rather than franchised dealer networks. This channel shift is most visible in US long-haul trucking, where cost-per-mile optimization dominates procurement criteria.
Automotive Brake Valves Market Segmentation
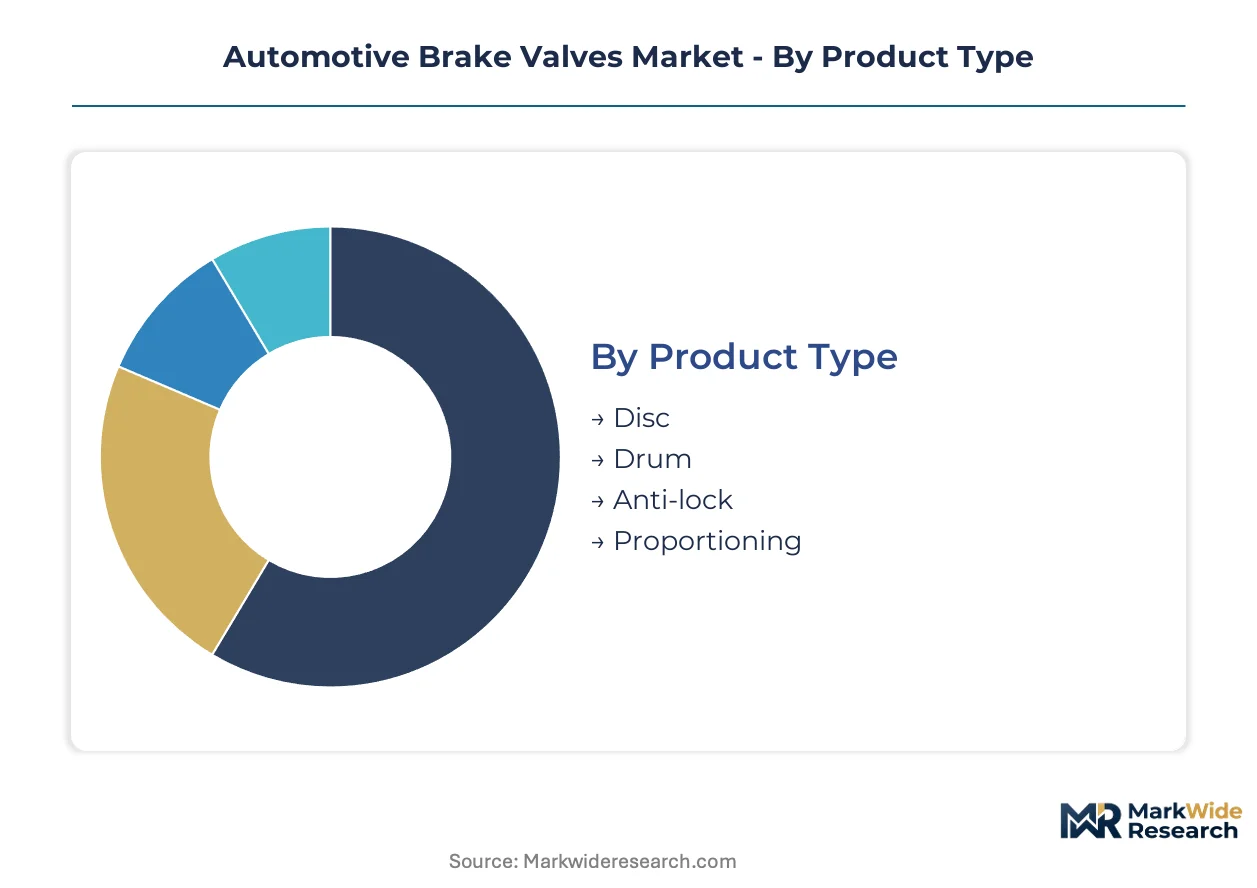
Brake valve segmentation reveals divergent technology trajectories across vehicle electrification and regulatory domains. Supplier positioning depends on matching product architectures to specific OEM platform requirements and regional homologation standards.
Product Type:
Domestic production clusters around disc and anti-lock configurations for European and North American OEM qualification, while drum valve manufacturing concentrates in export-oriented facilities serving emerging-market commercial fleets.
- Disc:These valves modulate hydraulic pressure to caliper assemblies through precision-machined piston bores and seal grooves. Demand concentrates in German passenger vehicle engineering corridors around Stuttgart, driven by mandatory stability control integration under ECE R13 amendments.
- Anti-lock:Pulse-width-modulated solenoid valves cycle at frequencies up to 15 Hz to prevent wheel lock-up during emergency braking. North American truck manufacturers specify these for NHTSA FMVSS compliance, creating compulsory demand across Class 8 vehicle platforms.
- Drum:S-cam and wedge-actuated designs persist in cost-sensitive commercial applications.
- Proportioning:Pressure-reducing valves balance front-rear brake bias under variable load conditions.
Disc holds the largest share; momentum sits with anti-lock.
Technology:
Cost tier stratification separates commodity pneumatic systems from premium electronic modules, with electro-mechanical architectures occupying an intermediate position for hybrid commercial platforms.
- Electronic:Brake-by-wire modules integrate pedal sensors, motor-driven actuators, and ASIL-D safety controllers in distributed architectures. Volvo and Daimler Truck specify these for battery-electric heavy-duty platforms, eliminating pneumatic infrastructure entirely.
- Hydraulic:Conventional master cylinder and booster assemblies transmit pedal force through fluid columns at 100-180 bar operating pressure. Passenger vehicle OEMs in Germany retain these for internal combustion platforms pending full electrification transitions.
- Pneumatic:Compressed air systems at 8-13 bar dominate commercial vehicle foundation braking.
- Electro-mechanical:Motor-on-caliper designs bridge hydraulic and fully electronic topologies.
Hydraulic retains volume leadership; electronic climbs the fastest.
End User:
Application-driven demand patterns separate heavy-duty commercial procurement cycles from passenger vehicle replacement intervals, with motorcycle and equipment markets following distinct specification pathways.
- Truck Manufacturers:Class 8 vehicle builders specify integrated brake control modules through SAE J1939 network architectures. US-based fleet operators demand 500,000-mile service intervals, driving supplier validation investment.
- Passenger Vehicles:OEM channels prioritize compact electro-hydraulic integration for electric platform weight reduction.
- Motorcycles:Single-channel ABS valves address emerging-market safety mandates.
- Heavy Equipment:Mining and construction applications require sealed housings for contamination resistance.
Truck manufacturers command the largest share; momentum sits with passenger vehicles.
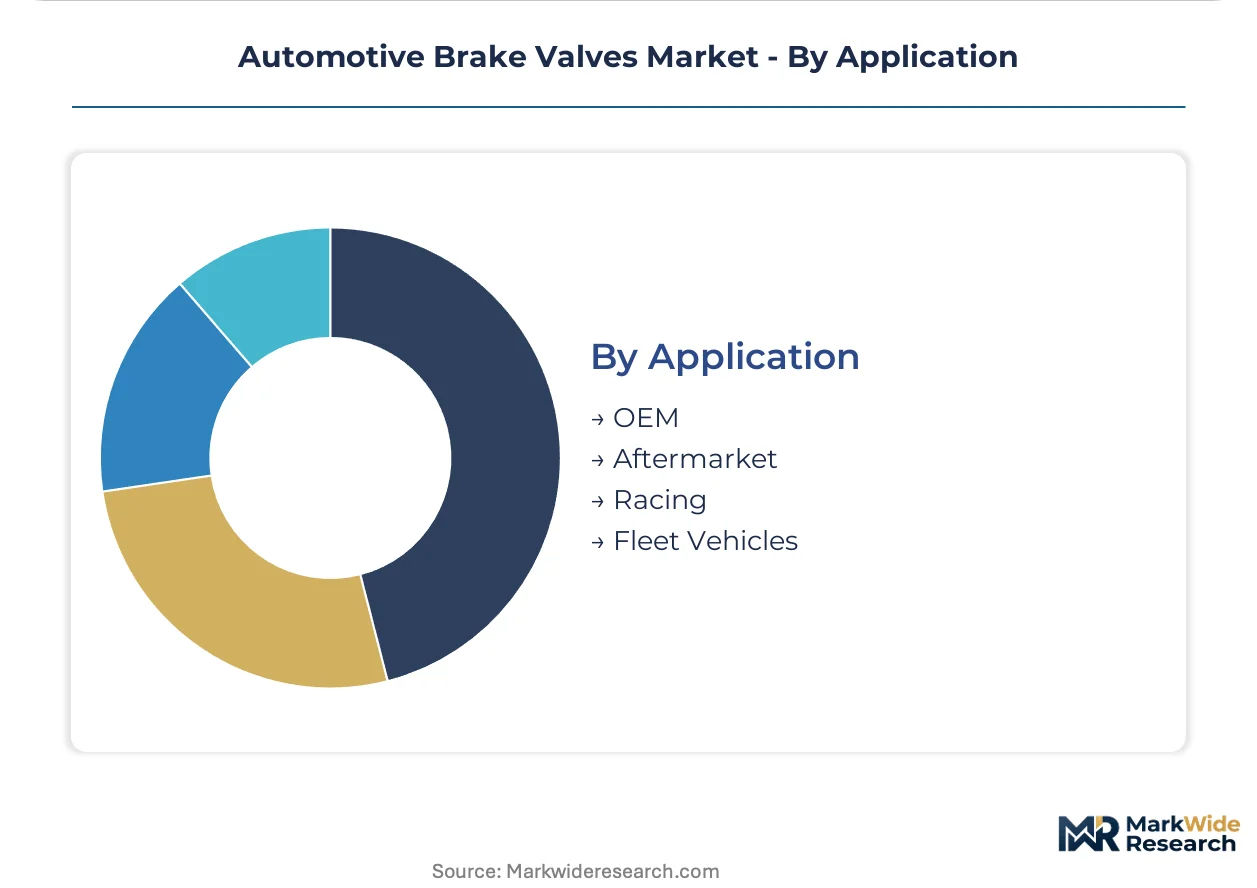
Application:
Customer type determines channel economics, with OEM qualification requiring multi-year development cycles while aftermarket and fleet segments prioritize inventory availability and cost-per-mile optimization.
- OEM:Direct supply relationships demand ISO 26262 functional safety certification and collaborative design engineering. German automotive corridors around Munich accelerate specification cycles through concentrated OEM engineering activity.
- Aftermarket:Remanufactured electronic modules and replacement pneumatic valves flow through independent distributors and specialized rebuilders.
- Racing:Motorsport applications specify adjustable bias valves and titanium hardware for weight minimization.
- Fleet Vehicles:Long-haul operators source brake valves through maintenance contracts emphasizing total cost of ownership.
OEM holds the largest share; fleet vehicles gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers export brake valve systems to North American truck manufacturers through established transatlantic supply corridors. This trade flow reflects concentrated mechatronics capability in southwestern Germany serving dispersed OEM assembly footprints.
United States
Class 8 truck manufacturers specify SAE J1939-compliant electronic brake modules for NHTSA Federal Motor Vehicle Safety Standards compliance. EPA heavy-duty vehicle greenhouse gas rules indirectly shape valve specifications through weight reduction mandates. Detroit-based engineering centers coordinate validation protocols with German component suppliers.
Germany
Passenger vehicle OEMs in Stuttgart and Munich drive specification cycles for electro-hydraulic integration in electric platforms. ECE R13 homologation amendments tighten response time tolerances for electronic brake control modules. The Baden-Württemberg automotive engineering corridor anchors European brake valve R&D concentration.
China
Domestic electric commercial vehicle manufacturers source brake-by-wire modules under MIIT new energy vehicle certification requirements. GB/T braking standards impose additional testing protocols on suppliers targeting domestic OEM qualification. Yangtze River Delta production clusters assemble valve systems for both domestic consumption and export markets.
India
PLI scheme incentives for electric bus and truck manufacturing create qualification windows for brake-by-wire suppliers entering the market. Central government safety mandates for commercial vehicle ABS installation expand addressable demand. Tamil Nadu and Maharashtra automotive manufacturing belts concentrate assembly operations for domestic and export-bound commercial vehicles.
Japan
Domestic OEMs integrate compact electro-hydraulic modules for hybrid and battery-electric passenger platforms. METI industrial policy supports advanced brake system component development through targeted R&D subsidies. Kanto region engineering centers coordinate specification development with tier-one valve suppliers.
Automotive Brake Valves Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and geographic reach dimensions. The supplier base consolidates around mechatronics-integrated electronic brake modules while maintaining pneumatic legacy production for cost-sensitive segments. Three archetypes dominate: diversified automotive conglomerates with brake system divisions, pure-play brake component specialists, and diversified industrial manufacturers with automotive exposure. Capacity expansion in electronic module production and strategic partnerships for brake-by-wire development constitute the primary competitive moves.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify integrated mechatronics capabilities anchoring European OEM supply chains. ZF Friedrichshafen AG occupies a position bridging heritage pneumatic expertise with electronic transition requirements through its WABCO heritage. These three Germany-based entities represent the geographic concentration of brake valve engineering competence.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| WABCO Holdings Inc. |
| Aisin Corporation |
| Brembo S.p.A. |
| Mando Corporation |
| Haldex AB |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between North American Class 8 truck manufacturers and southwestern German valve suppliers lock in multi-year supply access while anchoring price visibility against aluminum and copper volatility. These contractual structures insulate OEM procurement teams from spot market swings in cast housing materials and solenoid windings.
Pricing Analysis
Next-generation electronic brake-by-wire modules command substantial premiums over legacy pneumatic systems, while prior-generation drum valve architectures compete on cost-per-unit in emerging-market fleets. Three-tier pricing structure across premium ASIL-D certified modules, standard hydraulic assemblies, and economy drum configurations segments buyer budgets. Pricing pressure stems from aluminum input volatility that suppliers cannot fully pass through to OEM customers. Aftermarket fleet operators exhibit highest price sensitivity, prioritizing cost-per-mile optimization over specification grade.
Supply Chain Analysis
Strait of Malacca transit routes underpin raw material flows for Southeast Asian valve assembly plants serving Chinese electric commercial vehicle manufacturers. Manufacturing concentrates in Germany, China, and Mexico, with precision machining of piston bores and seal grooves drawing from specialized tooling networks in Baden-Württemberg. Raw material dependencies center on aluminum castings, copper windings, and rare-earth magnets for actuator motors. Single-source vulnerability in southwestern German mechatronics clusters creates geographic concentration risk. Distribution runs through Tier 1 supplier hubs co-located with OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vehicle production cycles are recovering from trough conditions, with EPA heavy-duty greenhouse gas phase-in schedules and NHTSA stability control mandates creating compulsory demand pull through the mid-2030s.
For Market Incumbents: Consolidate mechatronics capabilities through targeted acquisitions of brake-by-wire software specialists, countering emerging entrant threats in electronic actuation. Expand captive aluminum casting capacity in Mexico to offset input cost volatility and secure tariff-advantaged supply for North American OEM customers. For New Entrants and Emerging Players: Lead with brake-by-wire qualification for India's PLI-supported electric bus manufacturing, where incumbent presence remains thin and domestic certification pathways offer faster market entry. Partner with Tamil Nadu-based commercial vehicle assemblers to establish local validation credentials before expanding to passenger vehicle applications. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors acquisition of Tier 2 electro-hydraulic module specialists with pending ISO 26262 certification. Long-term viability hinges on software-defined brake control capabilities over hardware manufacturing scale. Monitor NHTSA rulemaking timelines for advanced emergency braking system mandates as the key demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Development | Volvo and Daimler Truck specifications eliminate pneumatic infrastructure entirely in battery-electric heavy-duty platforms. |
| ASIL-D Functional Safety Certification | ISO 26262 compliance extends development cycles but unlocks OEM qualification for electronic brake control modules. |
| Aluminum Casting Backward Integration | In-house housing production insulates margins from base metal price swings and secures supply continuity. |
| Over-the-Air Calibration Infrastructure | Software-defined brake parameters enable recurring revenue streams beyond initial hardware shipment. |
| India PLI Scheme Qualification | Domestic electric commercial vehicle incentives create first-mover windows for brake-by-wire suppliers. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement directors, aftermarket fleet maintenance managers, and brake system R&D leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against NHTSA Federal Motor Vehicle Safety Standards filings, ECE R13 homologation databases, EPA heavy-duty vehicle greenhouse gas rule dockets, and vehicle production registration data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled span product type, technology generation, end-user category, and application channel across the analysis window. Vehicle class stratification, propulsion architecture transitions, and content-per-vehicle trajectories for electronic versus pneumatic systems informed volume projections. CAGRs derived from regression analysis of historical adoption curves, adjusted for regulatory mandate timing and OEM platform launch schedules.
Forecasts assume regulatory continuity in NHTSA Federal Motor Vehicle Safety Standards and ECE R13 homologation regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EPA heavy-duty vehicle greenhouse gas rule stringency and China MIIT new energy vehicle subsidy trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Rail Components Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
HCV Axles Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Headlight Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Automotive Sensors Market