
 Tipper Body Equipment Market | 2026-2036
Tipper Body Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Tipper Body Equipment Market Outlook
The EU Green Deal is realigning procurement criteria for tipper body equipment across European municipal fleets. Hyva leverages its hydraulic cylinder integration to sustain margins in premium segments. Schmitz Cargobull anchors its position through standardized modular platforms that reduce lead times for construction contractors.
Tipper body equipment comprises hydraulically actuated cargo containers mounted on truck chassis, engineered from high-tensile steel or aluminum alloys with payload ratings typically spanning 10 to 40 metric tons, designed for gravity-assisted discharge of bulk materials in construction, mining, and waste handling operations. Steel-bodied units dominate volume in emerging markets where acquisition cost governs fleet decisions, while aluminum configurations command margin pools in European logistics applications where payload optimization reduces per-ton transport costs. The waste management application segment shows structural momentum as municipalities convert open-bed fleets to sealed container systems under tightening environmental protocols.
EMA emission benchmarks, REACH material compliance, and EU F-Gas Regulation on hydraulic refrigerants collectively reshape product certification requirements for equipment sold across European member states. EPA Tier 4 Final and NHTSA greenhouse gas standards impose parallel design constraints on North American suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where engineering investments will yield market access advantages.
Market Dynamics
Euro VI emission standards are compressing permissible chassis weights and forcing tipper body manufacturers toward high-strength aluminum alloys and composite substructures to preserve payload ratings.
Growth Catalysts
- Australian mining fleet renewal:Surface and underground operators are replacing aging rigid hauler support fleets with highway-legal articulated tippers for pit-to-port logistics.
- EU Green Deal municipal procurement:European cities now mandate sealed-container waste tippers with integrated weighing and telematics for pay-as-you-throw billing systems.
- High-tensile steel adoption:Emerging market contractors specify Hardox and similar wear-resistant grades to extend body life in abrasive ore and aggregate applications.
Market Restraints
- Aluminum ingot price volatility:European and North American body builders face margin compression when LME aluminum spikes above sustainable hedging thresholds.
- Hydraulic cylinder supply concentration:Premium telescopic cylinder production clusters in Northern Italy and Southern Germany, creating single-source vulnerability for remote assembly plants.
- Battery-electric chassis payload penalty:Current generation electric truck platforms sacrifice 800-1200 kg of legal payload to battery mass, degrading tipper economics in weight-sensitive hauls.
Strategic Opportunities
- Indian construction equipment leasing:Equipment rental penetration remains below fifteen percent for tipper bodies, presenting channel innovation potential for fleet-as-a-service operators.
- REACH-compliant coating systems:Water-based and powder coating technologies that eliminate solvent-based zinc primers open premium positioning for environmentally certified municipal tenders.
- Telematics-integrated hydraulics:Convergence of IoT load sensors with automated tipping angle control enables remote diagnostics and predictive maintenance contracts.
Industry Challenges
- Welding technician scarcity:Certified aluminum MIG and friction-stir welders command wage premiums that inflate production costs for alloy-bodied variants.
- Homologation timeline fragmentation:Divergent whole-vehicle type approval requirements between Germany's KBA and France's DREAL delay cross-border fleet deployments.
- Legacy chassis integration:Retrofit tipper installations on Euro V and older chassis face compatibility gaps with modern CAN-bus hydraulic controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tipper Body Equipment Market |
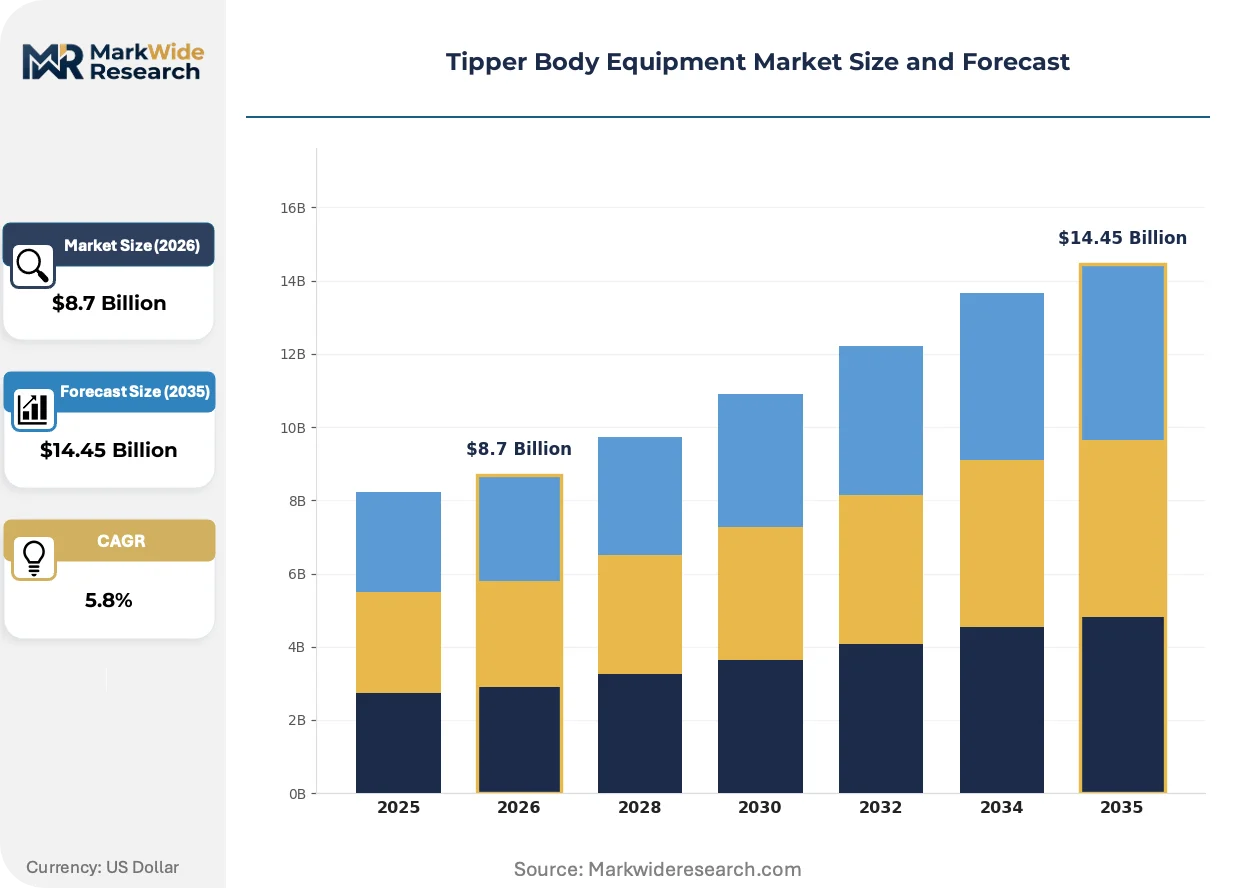
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Others Application: Construction, Mining, Agriculture, Waste Management Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Trailers, Specialized Vehicles End User: Contractors, Municipalities, Logistics Companies, Mining Firms |
| Companies Covered | Hyva, Schmitz Cargobull, Crysteel Manufacturing Inc., Meiller Kipper, Thompsons Ltd, GES, ShinMaywa Industries, Palfinger, Marrel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tipper Body Equipment Market Strategic Shifts
Material substitution and digital integration are redefining how tipper bodies are specified, operated, and maintained across construction and waste verticals.
Advanced aluminum alloys with scandium micro-additions are expanding into European logistics fleets where every kilogram of body weight reduction translates to additional revenue payload. Bulk cement and grain haulers in Germany's industrial corridor specify these grades despite thirty-percent material cost premiums. The technology is expanding into premium segments as lifecycle cost calculators demonstrate payback through fuel savings and toll avoidance.
EPA Tier 4 Final and NHTSA greenhouse gas Phase 2 standards are forcing North American manufacturers to certify tipper bodies as part of complete vehicle aerodynamic packages. Body-side fairings and integrated tarp systems now contribute to fleet-wide compliance scores. Vocational truck operators in California's Central Valley face the strictest constraints and have accelerated adoption of streamlined steel designs with reduced frontal area.
Rental and leasing channels are capturing share from direct equipment purchase in European construction markets. Contractors in France and Benelux increasingly specify tipper bodies through multi-year operating leases with full maintenance inclusion. This shift concentrates specification authority with lessors who standardize on modular platform designs to maximize residual value and inter-fleet transferability.
Tipper Body Equipment Market Segmentation
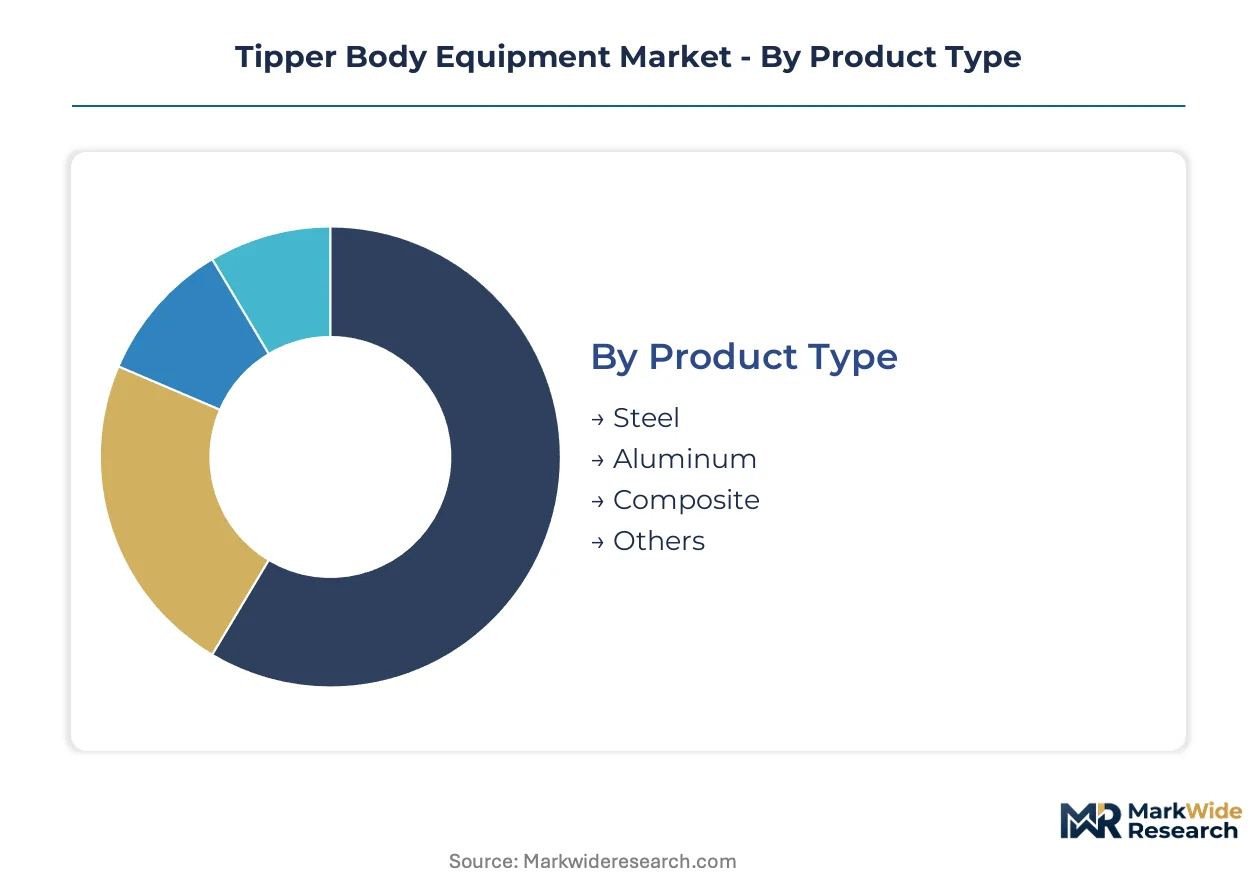
Tipper body equipment procurement decisions pivot on payload optimization, regulatory compliance, and lifecycle cost calculations. Segmentation reveals how material choices, application demands, and fleet operator types create distinct specification clusters across construction, mining, and waste handling verticals.
Product Type:
Standardization dominates high-volume steel production while aluminum and composite variants command premium customization for weight-sensitive logistics.
- Steel:High-tensile grades like Hardox 450 and 500 deliver abrasion resistance for aggregate and ore hauling. Australian mining contractors specify these bodies for pit-to-port rigid hauler support fleets facing abrasive silica loads. Leading the category by volume: Steel. Growing fastest: Aluminum.
- Aluminum:Scandium-microalloyed grades reduce body mass by 40-50% versus steel, enabling additional payload within legal axle limits. German bulk cement haulers in the industrial corridor adopt these despite material cost premiums to optimize per-ton transport economics under Euro VI weight restrictions.
- Composite:Glass-reinforced polymer substructures with steel wear plates target niche applications requiring corrosion resistance and electromagnetic transparency.
- Others:Hybrid configurations combining aluminum structural members with bolt-on steel liners address specific wear-pattern requirements in high-impact loading zones.
Specification authority concentrates with fleet operators who model total cost of ownership across fuel, tolls, and maintenance intervals.
Application:
Volume tiers separate cyclical construction demand from structurally expanding waste management procurement under environmental compliance mandates.
- Construction:Highway-legal articulated tippers handle sand, gravel, and demolition debris with 20-32 metric ton payload ratings. French and Benelux contractors increasingly source these through operating leases with full maintenance inclusion, shifting specification control to lessors.
- Mining:Surface and underground operators in Australia are replacing aging support fleets with highway-compliant units for pit-to-port logistics, driving demand for heavy-duty steel bodies with reinforced tipping pivots.
- Agriculture:Grain and silage tippers prioritize smooth interior surfaces and sealed tailgates to prevent contamination and spillage during field-to-elevator transport.
- Waste Management:European municipalities under EU Green Deal procurement mandates specify sealed-container systems with integrated weighing and telematics for pay-as-you-throw billing, expanding fastest among all applications.
Construction claims the largest installed base. Waste management demonstrates the steepest expansion trajectory.
Vehicle Type:
Chassis integration complexity increases with duty rating, creating specification handoffs between body builders and OEMs.
- Light Duty Trucks:Municipal and landscaping fleets specify 3.5-7.5 ton GVW units with single-acting hydraulic cylinders for frequent short-cycle tipping.
- Heavy Duty Trucks:Euro VI emission standards compress permissible chassis weights, forcing body builders toward high-strength aluminum alloys and composite substructures to preserve payload ratings in 18-40 ton configurations.
- Trailers:Central axle and drawbar configurations dominate European construction logistics, with standardized modular platforms reducing lead times for fleet operators.
- Specialized Vehicles:Underground mining tippers and aircraft catering lift trucks require custom chassis integration with CAN-bus hydraulic controls.
Heavy duty trucks anchor volume. Trailers gain share through rental channel expansion.
End User:
Procurement sophistication varies sharply between price-sensitive contractors and compliance-driven municipal buyers.
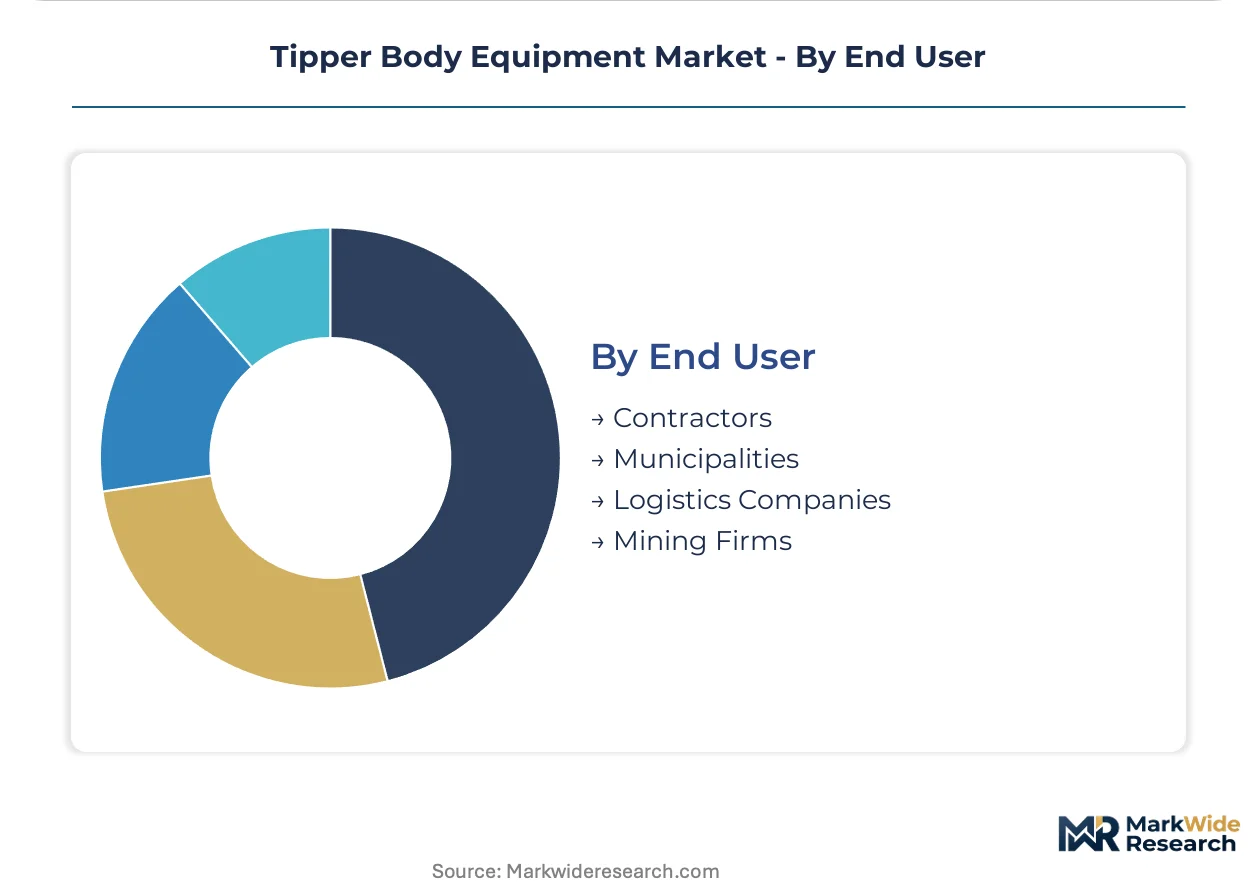
- Contractors:Small and mid-sized construction firms prioritize acquisition cost over lifecycle optimization, sustaining steel body demand in emerging markets.
- Municipalities:European cities under EMA and REACH mandates specify REACH-compliant coating systems and telematics-integrated hydraulics, creating premium positioning for certified suppliers.
- Logistics Companies:German bulk haulers calculate payload optimization returns against aluminum cost premiums using fuel price and toll avoidance models.
- Mining Firms:Australian surface operators specify Hardox-bodied units through fleet renewal programs, with procurement committees evaluating wear life in abrasive ore applications.
Contractors represent the broadest addressable base. Municipalities deliver the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor between the Rhine and Ruhr valleys anchors European tipper body procurement intensity, with bulk cement haulers and construction logistics operators driving specification standards for lightweight aluminum configurations.
Germany
KBA homologation requirements and Euro VI weight restrictions compress chassis allowances, pushing body builders toward scandium-microalloyed aluminum grades. REACH-compliant coating systems eliminate solvent-based primers from municipal tender specifications. The Rhine-Ruhr corridor concentrates demand from bulk cement and aggregate haulers optimizing payload per axle.
Australia
Surface mining operators in Western Australia and Queensland are replacing rigid hauler support fleets with highway-legal articulated tippers for pit-to-port logistics. The country's national environmental regulator enforces strict dust suppression mandates on open-bed operations. Perth-based fleet operators specify Hardox-bodied units through renewal programs targeting abrasive ore conditions.
United States
EPA Tier 4 Final and NHTSA greenhouse gas Phase 2 standards force body-side fairing integration into complete vehicle aerodynamic packages. California's Air Resources Board imposes the strictest vocational truck constraints, accelerating streamlined steel adoption in the Central Valley. Midwest aggregate haulers balance acquisition cost against compliance-driven design premiums.
India
Construction equipment leasing penetration below fifteen percent creates channel innovation potential for fleet-as-a-service operators. BIS certification requirements and state-level vehicle fitness rules govern body mounting standards. Maharashtra and Gujarat industrial zones concentrate contractor demand for high-tensile steel bodies in highway and urban infrastructure projects.
France
Operating lease penetration among Benelux and French contractors shifts specification authority to lessors standardizing on modular platforms. DREAL type approval timelines diverge from German KBA protocols, delaying cross-border fleet deployments. Lyon and Lille logistics clusters drive sealed-container waste tipper demand under EU Green Deal procurement mandates.
Tipper Body Equipment Market Competitive Environment
The competitive structure tilts toward specialized hydraulic integration specialists and modular platform standardizers. Consolidation pressure concentrates among European incumbents with captive cylinder production, while Asian fabricators compete on steel body volume. Three archetypes dominate: integrated hydraulic system providers, modular platform specialists, and regional steel fabricators. Capacity expansion in aluminum welding and strategic partnerships for electric chassis integration represent the dominant competitive moves.
Among European-integrated specialists, Hyva and Schmitz Cargobull occupy positions reflecting divergent specialization vectors. Hyva exemplifies the hydraulic-integrated archetype through its cylinder technology anchoring. Schmitz Cargobull represents modular platform standardization for residual value optimization. Crysteel Manufacturing Inc. sits within the North American vocational fabricator tier. Meiller Kipper and Thompsons Ltd reflect regional European fabrication concentration. ShinMaywa Industries and Palfinger demonstrate diversified industrial equipment portfolios extending into tipper applications. Marrel represents French hydraulic specialization heritage.
| Leading Market Players |
|---|
| Hyva |
| Schmitz Cargobull |
| Crysteel Manufacturing Inc. |
| Meiller Kipper |
| Thompsons Ltd |
| GES |
| ShinMaywa Industries |
| Palfinger |
| Marrel |
| Others |
Value Chain & Pricing Dynamics
Certified aluminum MIG and friction-stir welders concentrated in Northern Italy and Southern Germany command wage premiums that inflate production costs for alloy-bodied variants, creating labor-cost differentials that separate premium European fabricators from emerging-market steel-body competitors.
Pricing Analysis
Payload-per-ton transport economics anchor value-based pricing for bulk cement and grain haulers calculating fuel savings and toll avoidance against body-weight reductions. Three-tier pricing structure across premium scandium-microalloyed aluminum, standard high-tensile steel, and economy-grade mild steel separates specification clusters. Pricing pressure stems from LME aluminum volatility when ingot prices spike above sustainable hedging thresholds. Contractors in emerging markets exhibit acute price sensitivity, while German logistics companies demonstrate lowest sensitivity due to lifecycle cost modeling.
Supply Chain Analysis
Refurbishment flows for Hardox-bodied mining units create secondary supply channels extending body life in Australian pit-to-port operations. Premium telescopic cylinder production clusters in Northern Italy and Southern Germany, drawing from high-grade steel billet and precision-machined component inputs. Single-source vulnerability for remote assembly plants represents structural supply chain risk. Distribution runs through OEM chassis integration partnerships and rental fleet lessors standardizing on modular platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified aluminum welder scarcity props pricing for alloy-bodied variants, constraining capacity expansion and sustaining margin pools for incumbents with captive welding expertise.
For Market Incumbents: To counter hydraulic cylinder supply concentration in Northern Italy and Southern Germany, secure dual-source agreements with secondary cylinder fabricators in Eastern Europe and invest in in-house production of telescopic stages to reduce single-source vulnerability for remote assembly plants. For New Entrants and Emerging Players: The price-point gap between premium aluminum configurations and economy steel bodies opens white-space targeting for mid-tier high-tensile steel variants with powder-coated finishes serving Indian construction equipment leasing channels and Southeast Asian contractor fleets through fleet-as-a-service operating lease structures. For Investors and Strategic Acquirers: Re-rating potential sits with integrated hydraulic system providers given telematics-integrated hydraulics convergence creating recurring revenue streams from predictive maintenance contracts, with long-term viability hinging on electric chassis integration capabilities. Monitor battery-electric truck platform payload penalty resolution as inflection indicator for tipper economics viability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Welding Capacity Expansion | Secures certified MIG and friction-stir welder pipelines against Northern Italian wage inflation. |
| Telematics-Integrated Hydraulic Cylinder Development | Enables IoT load sensor convergence with automated tipping angle control for predictive maintenance contracts. |
| REACH-Compliant Coating System Certification | Unlocks premium positioning in EU Green Deal municipal tenders eliminating solvent-based zinc primers. |
| Electric Chassis Integration Partnership | Addresses 800-1200 kg battery payload penalties degrading tipper economics in weight-sensitive hauls. |
| Modular Platform Standardization | Reduces lead times for French and Benelux contractors shifting to operating leases with full maintenance inclusion. |
Study Parameters
Trade association filings, customs and import-export records, and OEM chassis production databases formed the secondary backbone, supplemented by primary interviews with fleet maintenance directors, construction equipment procurement managers, rental fleet lessors, and hydraulic systems engineers. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market sizing.
Bottom-up modeling aggregated unit economics across material grades and application verticals, while top-down cross-checks applied macro fleet renewal patterns from Australian mining and EU municipal procurement mandates. Segmentation dimensions included product type, application vertical, vehicle class, and end-user procurement sophistication. CAGRs derived from regression analysis of historical replacement cycles and regulatory phase-in schedules, with Euro VI weight restriction impacts and battery-electric chassis adoption curves as industry-specific forecast inputs.
Inputs from fleet operator maintenance records and municipal tender databases were available through the study window; gaps in real-time aluminum ingot price hedging data and electric truck platform payload specifications introduce uncertainty bands around material substitution forecasts. Practitioners should monitor KBA and DREAL homologation timeline convergence and LME aluminum volatility spikes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
HCV Axles Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Refrigerated Trailer Hinges Market