
 Steering Knuckle Market | 2026-2036
Steering Knuckle Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Knuckle Market Intelligence
Aluminum is realigning steering knuckle economics as OEMs pursue mass reduction for electric vehicle range extension. Bharat Forge leverages its massive forging infrastructure to supply hollow aluminum knuckles at scale. Thyssenkrupp anchors European supply through integrated steel-to-aluminum process development for premium chassis modules. Magna International competes on modular corner-assembly integration, bundling knuckles with suspension and brake hardware.
A steering knuckle is the pivoting suspension component that connects the wheel hub to the control arms and strut assembly, typically manufactured from forged steel or aluminum alloys with yield strengths exceeding 275 MPa to withstand steering, braking, and vertical loads. Its primary function is to maintain wheel geometry while transmitting forces between the tire contact patch and the vehicle chassis. Forged steering knuckles retain dominance in heavy-duty commercial and off-road applications where fatigue resistance commands premium positioning. Electric vehicle application demand is accelerating fastest as dedicated EV platforms require redesigned knuckle geometry to accommodate in-wheel motor packaging and regenerative braking torque paths.
NHTSA crashworthiness standards and EPA fuel-economy mandates in the United States compel material-lightening investments, while EU Green Deal carbon-border adjustments pressure European foundries to decarbonize aluminum sourcing for knuckle production. China's MIIT new-energy vehicle technical guidelines explicitly incentivize chassis-weight reduction, redirecting domestic supplier R&D toward aluminum-intensive architectures. Stakeholders must monitor how battery-electric platform proliferation reshapes knuckle load-case specifications and whether regional carbon-accounting rules fragment material-certification requirements across export markets.
Market Dynamics
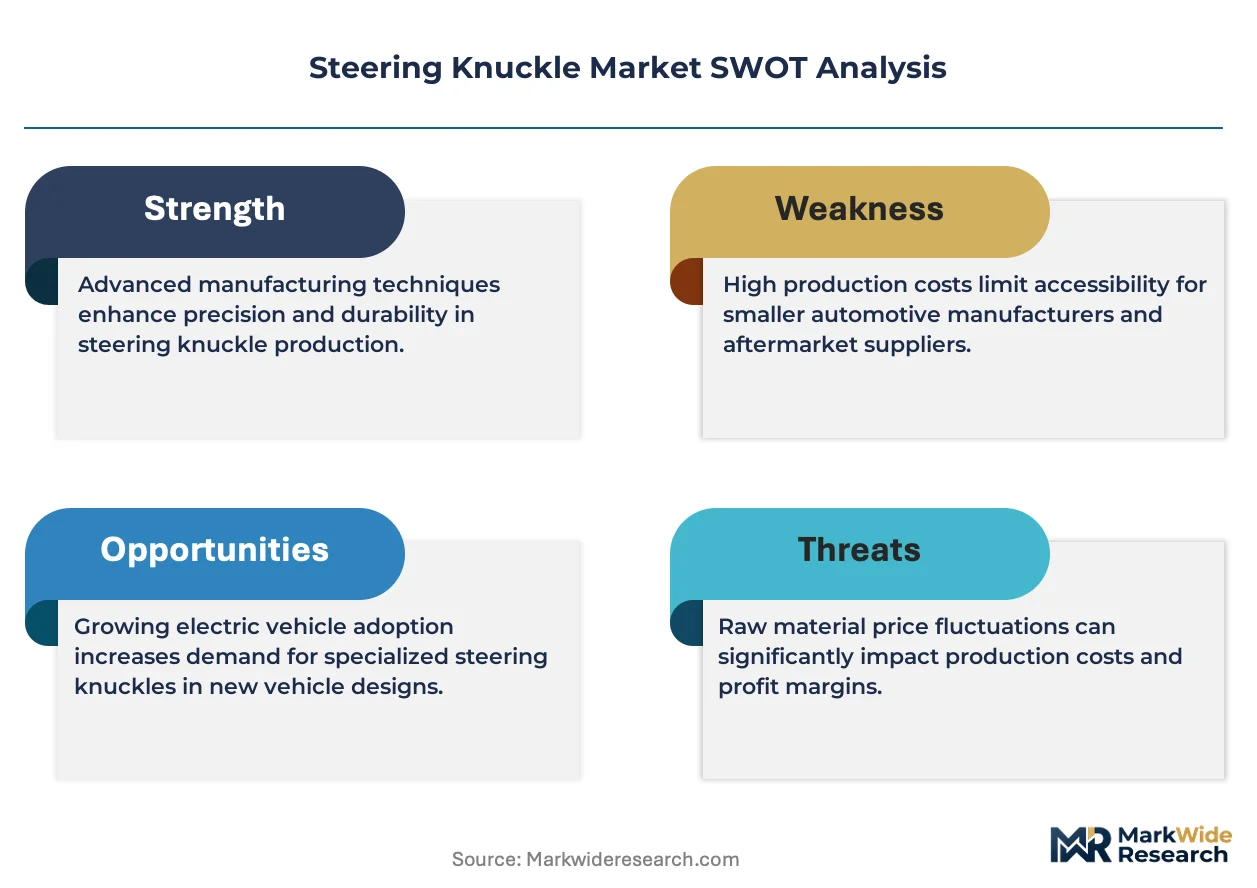
Aluminum-to-steel material substitution is compressing legacy forging economics while EV platform architectures force knuckle redesigns for in-wheel motor packaging and regenerative braking load paths.
Growth Catalysts
- EPA fuel-economy mandates:US light-truck CAFE standards compel chassis mass reduction, accelerating aluminum knuckle adoption in Detroit Three vehicle programs.
- MIIT new-energy vehicle guidelines:China's technical directives explicitly weight chassis-lightening scores in NEV subsidy calculations, redirecting domestic supplier R&D budgets.
- Hollow-forging process maturation:Advanced aluminum extrusion and internal cavity forming now yield fatigue-resistant knuckles at commercial scale for electric SUVs.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings compress foundry margins and deter long-term supply contracts for high-volume programs.
- European foundry concentration:Germany, Italy, and France host 70% of EU aluminum knuckle capacity, creating single-source vulnerability for premium OEMs.
- Fatigue-test protocol divergence:SAE J2562 and ISO 3918 load-case specifications differ on cyclic bending thresholds, forcing redundant validation for export markets.
Strategic Opportunities
- India commercial vehicle expansion:BharatBenz and Volvo Eicher are localizing heavy-duty knuckle sourcing for tipper and tractor-trailer platforms under PLI scheme incentives.
- EU Green Deal carbon-border adjustments:CBAM phase-in rewards low-carbon aluminum sourcing, advantaging European foundries with renewable-powered smelter contracts.
- In-wheel motor packaging convergence:Integration of steering knuckles with hub motor mounts and brake-by-wire modules creates corner-assembly bundling potential.
Industry Challenges
- Multi-material joining expertise scarcity:Aluminum-steel hybrid knuckle architectures require friction-stir welding and laser-brazing skills that outpace vocational training pipelines in manufacturing clusters.
- Homologation timeline compression:EV platform development cycles now run 24-30 months versus 48-60 months for ICE architectures, squeezing fatigue-test and field-correlation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Knuckle Market |
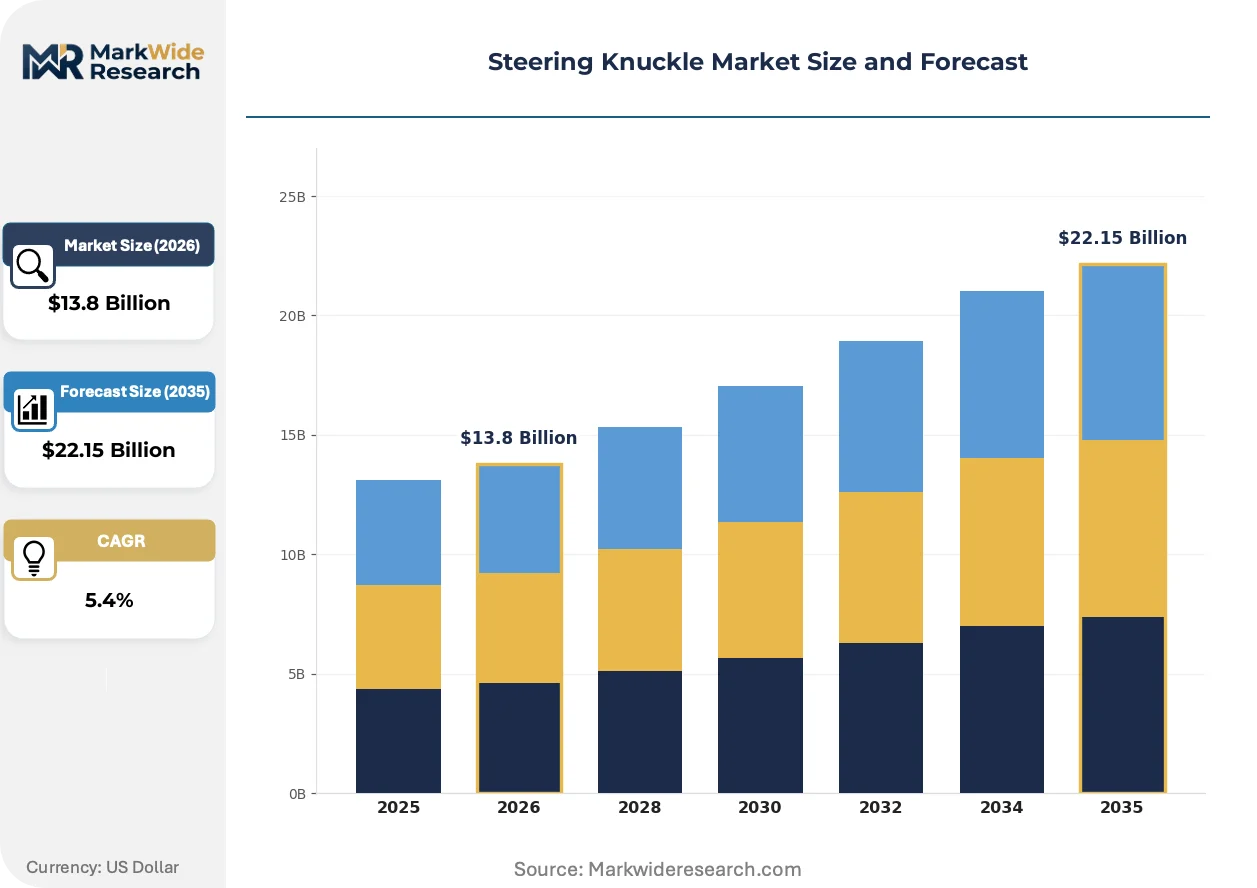
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Steering Knuckle, Cast Steering Knuckle, Machined Steering Knuckle, Molded Steering Knuckle Technology: CNC Machining, Powder Metallurgy, Hydroforming, Die Casting, Investment Casting Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles, Two-Wheelers End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Component Manufacturers |
| Companies Covered | Bharat Forge, Benteler, ZF Friedrichshafen, Bosch, Thyssenkrupp, Magna International, Dana Incorporated, Nexteer Automotive, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Knuckle Market Strategic Shifts & Innovations
Process innovation and regulatory carbon accounting are rewriting material selection criteria and supplier qualification protocols across steering knuckle procurement.
Hollow aluminum forging is converging with topology-optimized lattice structures to cut unsprung mass by 35-40% versus solid steel designs. Premium EV platforms from German and US OEMs are adopting these knuckles for range-critical sedan and crossover segments. The technology is converging with automated inline inspection systems that reduce scrap rates and compress process validation cycles.
EU Green Deal carbon-border adjustments are forcing foundries to document Scope 3 emissions from bauxite refining through billet casting. European OEMs now embed carbon-intensity thresholds in supplier scorecards, disqualifying high-emission aluminum sources. Premium chassis module suppliers in Germany and Austria are securing renewable-energy certificates and closed-loop scrap agreements to maintain contract eligibility.
Fleet operators and lease-finance providers are unbundling knuckle replacement from full suspension overhaul contracts, creating independent aftermarket demand for certified remanufactured units. This pattern fragments traditional Tier-1 captive aftermarket channels and opens direct procurement relationships between rebuild specialists and regional distributors. North American heavy-duty truck fleets are piloting this model most aggressively to compress total cost-per-mile calculations.
Steering Knuckle Market Segmentation
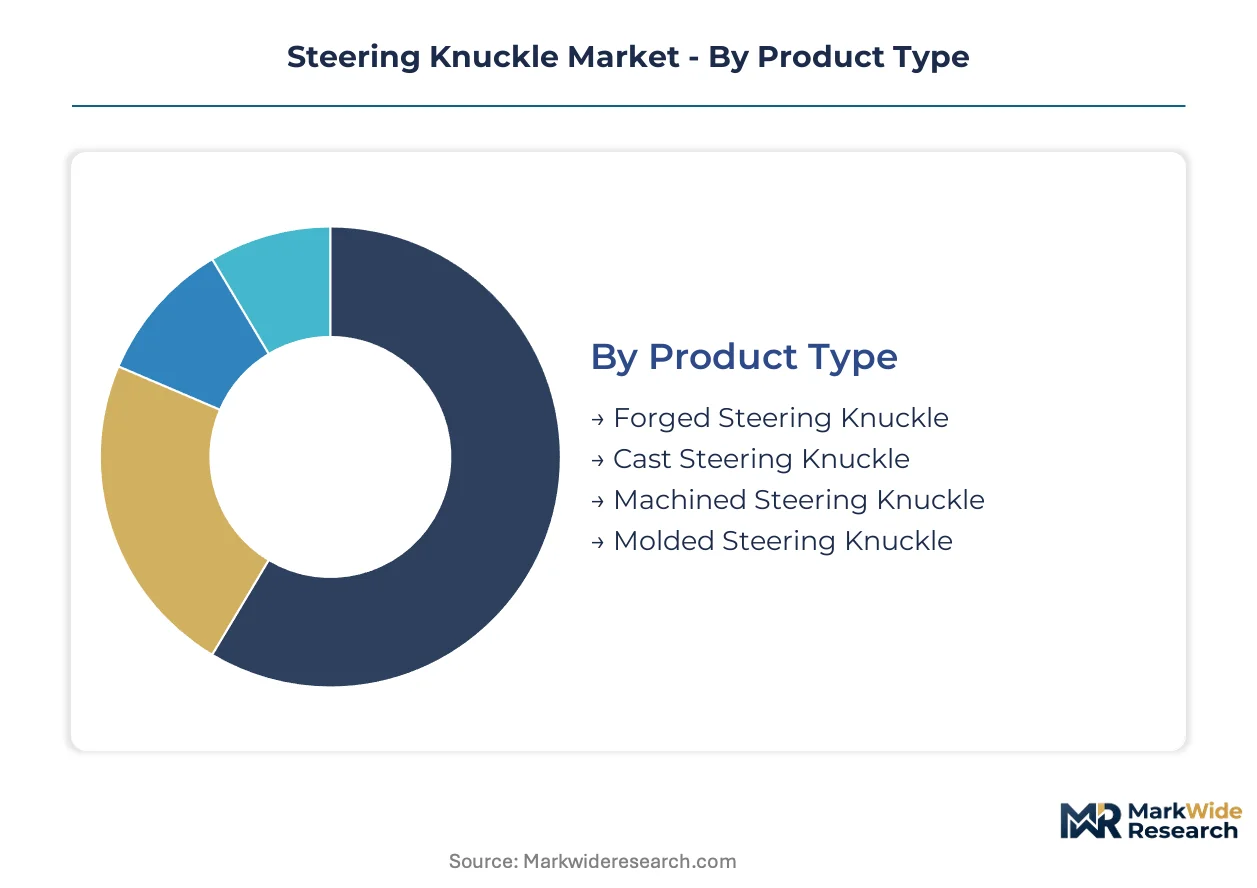
Steering knuckle procurement patterns diverge sharply across manufacturing methods, vehicle architectures, and supply chain tiers. Each segmentation axis reveals distinct margin structures, technical qualification barriers, and growth trajectories that reshape supplier competitive positioning.
Product Type:
Cost tier separates legacy forging investments from emerging lightweight alternatives.
- Forged Steering Knuckle:Hot- or cold-formed steel or aluminum blanks deliver yield strengths exceeding 275 MPa for heavy-duty load paths. Detroit Three light-truck programs and German premium SUV platforms anchor demand as NHTSA crashworthiness standards tighten frontal-impact requirements.
- Cast Steering Knuckle:Aluminum gravity or low-pressure casting enables complex geometric integration for multi-link rear suspensions. Chinese NEV platforms and European compact electric crossovers concentrate procurement as MIIT chassis-lightening guidelines redirect supplier R&D budgets.
- Machined Steering Knuckle:CNC-machined from solid billet for prototype validation and ultra-low-volume motorsport applications.
- Molded Steering Knuckle:Polymer-composite hybrid structures emerging in autonomous shuttle and last-mile delivery pod segments.
Forged steering knuckles lead volumes today; cast aluminum variants are gaining share fastest.
Technology:
Application criticality dictates process selection across fatigue-load specifications and production scale thresholds.
- CNC Machining:Five-axis milling centers finish forged or cast blanks to micron-level tolerances for steering-axis inclination and scrub radius precision. Tier-1 chassis module suppliers in Germany and the United States deploy automated cells for premium OEM programs where geometry compliance commands warranty protection.
- Die Casting:High-pressure aluminum injection achieves near-net-shape hollow sections with cycle times under 90 seconds. Chinese foundries scale this technology for domestic electric SUV platforms under state-directed NEV production quotas.
- Powder Metallurgy:Sintered pre-alloyed steels offer net-shape capability for small knuckle variants in two-wheeler and urban mobility applications.
- Hydroforming:Internal pressure forming of aluminum tubes creates seamless hollow structures for unsprung mass reduction in performance EV architectures.
- Investment Casting:Ceramic-shell processes produce intricate geometry for integrated hub-bearing knuckle assemblies in limited-volume premium segments.
CNC machining dominates value extraction today; die casting climbs the fastest as EV platform volumes scale.
Application:
Customer type fragments between fleet operators prioritizing total cost-per-mile and OEMs optimizing platform-commonality economics.
- Passenger Vehicles:Unibody architectures demand knuckle designs that package MacPherson strut or double wishbone attachments within tight wheel-well envelopes. German and Japanese OEMs specify aluminum-intensive variants for C-segment and above as EPA fuel-economy mandates compress fleet-average consumption curves.
- Electric Vehicles:Dedicated EV platforms require knuckle redesigns to accommodate in-wheel motor torque paths, regenerative braking loads, and battery-pack mass redistribution. Chinese, German, and US manufacturers coordinate chassis-system integration for range-critical sedan and crossover segments.
- Commercial Vehicles:Heavy-duty forged steel knuckles withstand tipper and tractor-trailer duty cycles where fatigue resistance commands premium positioning.
- Off-Road Vehicles:Extreme articulation requirements and impact loading drive thick-section steel forgings for mining and construction equipment.
- Two-Wheelers:Cost-optimized stamped or cast steel knuckles serve high-volume scooter and motorcycle production concentrated in India and Southeast Asia.
Passenger vehicle applications anchor current procurement volumes; electric vehicle demand is expanding most quickly.
End User:
Supply concentration determines pricing power and technical collaboration depth across the value chain.
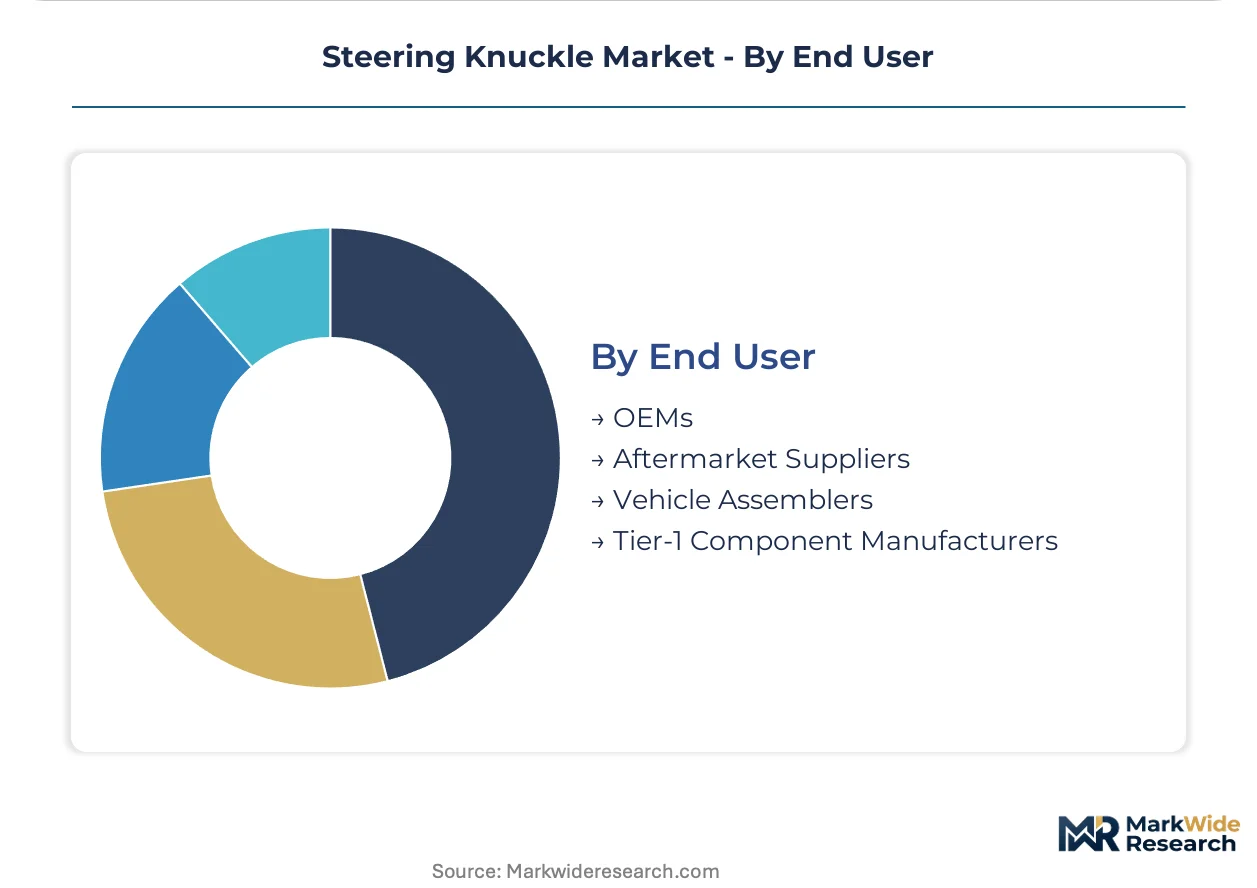
- OEMs:Vertically integrated chassis engineering teams at German and US manufacturers specify knuckle geometry, material grade, and supplier qualification protocols directly. These relationships lock in multi-year program commitments with stringent PPAP validation timelines.
- Tier-1 Component Manufacturers:Magna International, Thyssenkrupp, and Bharat Forge bundle knuckles into corner-module assemblies spanning suspension, braking, and steering subsystems. Their system-integration capabilities command design-in influence and captive aftermarket channels.
- Vehicle Assemblers:Contract manufacturers and emerging EV startups procure pre-validated knuckle modules to compress development cycles.
- Aftermarket Suppliers:Independent distributors and remanufacturing specialists serve fleet operators unbundling knuckle replacement from full suspension overhaul contracts.
Tier-1 component manufacturers lead value capture today; aftermarket suppliers are climbing fastest as fleet-service models fragment traditional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chassis engineering clusters in Germany, China, and the United States coordinate steering knuckle procurement for electric vehicle platforms. OEMs and Tier-1 suppliers in these markets align material specifications with regional carbon-accounting rules and crashworthiness mandates.
United States
Detroit Three light-truck programs anchor forged steel knuckle demand as NHTSA tightens frontal-impact standards. EPA fuel-economy mandates compress fleet-average consumption curves, redirecting supplier R&D toward aluminum-intensive architectures. Michigan and Ohio host concentrated forging capacity serving domestic OEM chassis integration teams.
Germany
Premium SUV and sedan platforms from Stuttgart and Munich manufacturers specify hollow aluminum knuckles for range-critical electric variants. EU Green Deal carbon-border adjustments pressure foundries to document Scope 3 emissions from bauxite refining through billet casting. Bavaria and Baden-Württemberg anchor European supply through integrated steel-to-aluminum process development.
China
State-directed NEV production quotas accelerate die-cast aluminum knuckle adoption for domestic electric SUV platforms. MIIT technical directives weight chassis-lightening scores in subsidy calculations, redirecting supplier budgets toward aluminum-intensive designs. Yangtze River Delta foundries scale high-pressure injection processes for volume programs.
India
BharatBenz and Volvo Eicher localize heavy-duty knuckle sourcing for tipper and tractor-trailer platforms under PLI scheme incentives. BIS certification requirements align with global fatigue-test protocols for export-market qualification. Pune and Chennai manufacturing clusters expand forging capacity to serve commercial vehicle expansion.
Japan
Kanto-based OEMs specify precision-machined knuckles for hybrid and battery-electric platform commonality. METI energy-efficiency guidelines pressure suppliers to reduce manufacturing carbon intensity per unit. Aichi Prefecture suppliers coordinate chassis-system integration with domestic and Southeast Asian vehicle assembly networks.
Steering Knuckle Market Key Industry Players
Global majors compete with regional champions across material substitution and platform integration capabilities. The supplier base organizes around forging scale, aluminum process expertise, and modular corner-assembly bundling. Three archetypes dominate: integrated steel-to-aluminum converters, hollow-forging specialists, and system-integration bundlers. Capacity expansion and strategic partnerships represent the dominant competitive moves as EV platform volumes scale.
Among German-based fabricators, Thyssenkrupp anchors European supply chain positioning through process development capabilities. Bharat Forge leverages Indian forging infrastructure to serve commercial vehicle and emerging electric platform demand. Magna International occupies the system-integration tier, bundling knuckles with adjacent chassis hardware to capture design-in influence and captive aftermarket channels.
| Leading Market Players |
|---|
| Bharat Forge |
| Benteler |
| ZF Friedrichshafen |
| Bosch |
| Thyssenkrupp |
| Magna International |
| Dana Incorporated |
| Nexteer Automotive |
| Continental |
| Others |
Cost & Logistics Intelligence
Performance-grade bifurcation between hollow-forged aluminum and solid steel knuckles drives divergent margin structures across OEM procurement tiers. Premium EV platforms absorb 40% higher unit costs for unsprung mass reduction, while commercial vehicle fleets negotiate long-term steel forging contracts indexed to scrap aluminum spreads.
Pricing Analysis
Input-cost pass-through from LME aluminum volatility compresses foundry margins and forces quarterly price renegotiation in high-volume programs. Three-tier pricing structure across premium, standard, and economy levels reflects fatigue-test certification tier, with NHTSA-compliant hollow forgings commanding 25-30% premiums over BIS-grade commercial variants. Pricing pressure stems from Chinese die-casting capacity expansion flooding mid-market segments. Fleet operators exhibit highest price sensitivity, while German premium OEMs prioritize geometry compliance over unit cost.
Supply Chain Analysis
PPAP qualification gates and OEM-specific fatigue-test protocols fragment supplier eligibility across export markets. Manufacturing concentrates in Germany, China, and the United States, with Yangtze River Delta foundries feeding domestic NEV platforms and Bavarian suppliers serving Stuttgart premium architectures. Supply chains draw from primary aluminum billets, high-strength steel forgings, and ceramic-shell investment casting materials. Single-source vulnerability pervades European hollow-forging capacity. Distribution runs through Tier-1 chassis module assemblers bundling knuckles with corner assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into structural demand shifts as EPA fuel-economy mandates and EU carbon-border adjustments simultaneously tighten material specifications and carbon-accounting requirements.
For Market Incumbents: To counter hollow-forging technology diffusion from Chinese foundries, Thyssenkrupp and Bharat Forge should deepen backward integration into renewable-powered aluminum smelting and secure closed-loop scrap agreements. Locking in multi-year renewable energy certificates preserves contract eligibility under EU Green Deal carbon-border adjustments. For New Entrants and Emerging Players: MIIT chassis-lightening guidelines in China open a window for die-casting specialists to capture share in domestic electric SUV platforms underserved by legacy forging incumbents. Targeting vehicle assemblers and emerging EV startups with pre-validated knuckle modules bypasses lengthy OEM qualification timelines. A direct procurement pitch emphasizing 24-month PPAP compression versus traditional 36-month cycles unlocks design-in conversations. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-material joining expertise scarcity outpaces vocational training pipelines in manufacturing clusters. Mid-cap hollow-forging specialists with renewable aluminum sourcing contracts represent prime acquisition targets over a 5-10 year horizon as carbon-intensity thresholds harden in supplier scorecards. Watch for CBAM phase-in acceleration as the inflection signal triggering premium valuation multiples for low-carbon aluminum knuckle producers.| Strategic Initiative | Industry Significance |
|---|---|
| Hollow-Forging Capacity Expansion | Bharat Forge scales aluminum cavity forming to serve Detroit Three EV truck programs under EPA mandates. |
| Renewable Aluminum Supply Agreement | European foundries secure hydro-powered smelter contracts to maintain OEM eligibility under EU Green Deal CBAM rules. |
| Corner-Module Integration | Magna International bundles knuckles with brake-by-wire hardware to capture design-in influence and captive aftermarket channels. |
| Multi-Material Joining Certification | Suppliers invest in friction-stir welding validation to enable aluminum-steel hybrid knuckle architectures for EV platforms. |
| Regional Manufacturing Footprint | Pune and Chennai clusters expand forging capacity to serve BharatBenz and Volvo Eicher under India's PLI scheme incentives. |
Research Approach
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and foundry operations directors grounded qualitative findings in operational reality. Secondary validation drew from NHTSA crashworthiness filings, EPA fuel-economy compliance data, MIIT new-energy vehicle technical guidelines, and EU ETS carbon-accounting disclosures. Bottom-up and top-down triangulation cross-checked production volume assumptions against OEM platform rollout schedules and foundry capacity announcements.
Bottom-up modeling segmented volumes across forged, cast, and machined product types, then layered propulsion architecture splits between ICE, hybrid, and battery-electric platforms. Top-down demand calibration referenced vehicle production databases and content-per-vehicle assumptions by weight class and regional regulatory cluster. CAGRs emerged from regression analysis of historical substitution patterns between steel and aluminum knuckles, adjusted for MIIT subsidy phase-outs and EPA fleet-average tightening trajectories.
Revisions become necessary when primary aluminum price volatility exceeds historical bands, when fatigue-test protocol divergence forces redundant validation cycles, or when CBAM implementation accelerates beyond current phase-in schedules. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Rail Components Market
Vehicle Components
Composite Bearings Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market