
 Electric Vehicles Component Market | 2026-2036
Electric Vehicles Component Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicles Component Market Analysis
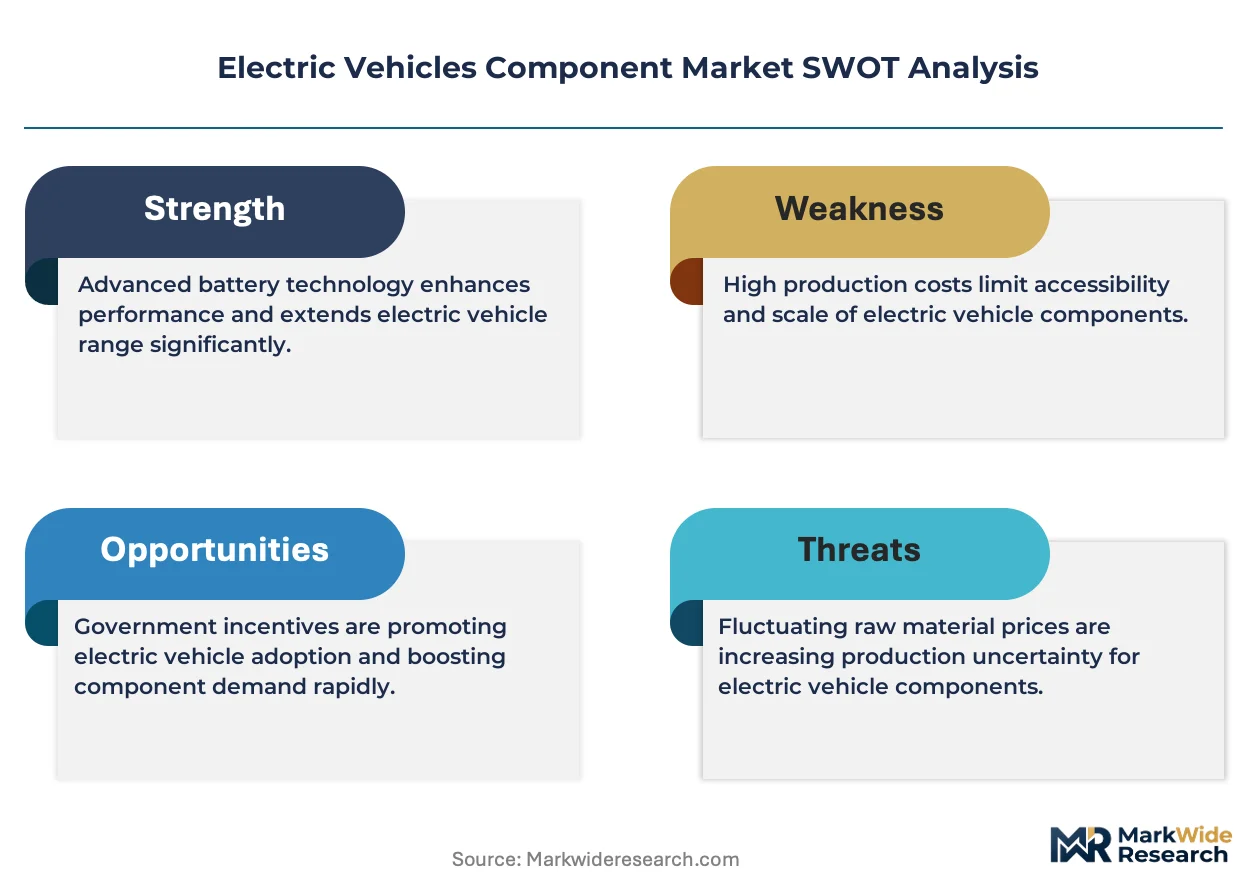
Automotive power electronics engineering talent is rotating from internal combustion programs toward battery management and inverter design teams. CATL leverages its vertical reach into cathode material refining to lock in lithium supply. Bosch anchors European demand through its integrated e-axle manufacturing footprint. Panasonic competes in cylindrical cell formats with sustained investment in high-nickel chemistry lines.
Electric vehicles components encompass electrochemical storage cells, torque-generating electric machines, power conditioning inverters, and conductive charging interfaces, typically operating at 400–800 volts DC with silicon carbide switching substrates. Their primary purpose is to replace hydrocarbon combustion with efficient electron-to-motion energy conversion across passenger and commercial transport platforms. Battery packs command the largest value share within component type segmentation, while solid-state chemistry within technology segmentation attracts the most capital deployment despite remaining pre-commercial. OEMs dominate end user segmentation through captive sourcing, though aftermarket providers are building diagnostic and refurbishment capabilities for out-of-warranty battery systems.
The EPA tailpipe standards and NHTSA corporate average fuel economy rules in the United States mandate fleet electrification percentages that cascade directly into component procurement volumes. EMA and REACH frameworks in Europe impose substance restriction and recycling accountability on battery cell imports, reshaping supplier qualification criteria. Stakeholders must monitor how divergent chemistry approval timelines between FDA-adjacent transportation safety bodies and EU battery passport requirements affect cross-border platform standardization decisions.
Market Dynamics
Solid-state battery chemistry is redirecting capital flows from liquid electrolyte manufacturing lines toward dry electrode coating and sulfide electrolyte synthesis infrastructure, compressing incumbent capacity planning cycles.
Growth Catalysts
- EPA Tailpipe Standards:Fleet electrification mandates under NHTSA corporate average fuel economy rules cascade directly into powertrain component procurement volumes across US commercial vehicle operators.
- Silicon Carbide Substrates:800-volt architectures are displacing 400-volt systems in premium passenger platforms, driving inverter and charging hardware refresh cycles.
- Cathode Material Concentration:China, Germany, and the United States concentrate the majority of active material demand, pulling precursor chemical investment toward these manufacturing clusters.
Market Restraints
- Lithium Price Volatility:Spodumene and brine supply instability transmits directly into cell cost structures, constraining OEM pricing flexibility for mass-market vehicle segments.
- Refining Concentration Risk:Cathode precursor processing capacity clusters in specific East Asian jurisdictions, creating single-point vulnerability for European and North American cell manufacturers.
- Solid-State Technical Limitations:Dendrite suppression and interface stability challenges delay commercialization timelines, freezing capital in pilot-scale facilities.
Strategic Opportunities
- EU Battery Passport Requirements:Digital traceability mandates create service revenue pools for software-enabled lifecycle tracking and second-life certification providers.
- Commercial Fleet Electrification:Depot-charging infrastructure buildout opens aftermarket service contracts for battery health monitoring and predictive thermal management.
- Solid-State and Dry Electrode Convergence:Elimination of solvent-based coating processes reduces facility footprint and energy intensity for next-generation cell manufacturing.
Industry Challenges
- Power Electronics Talent Scarcity:Inverter design and battery management system engineering expertise rotates from internal combustion programs faster than vocational pipelines replenish.
- Multi-Chemistry Certification Timelines:Divergent approval pathways between NHTSA safety validation and EU battery passport technical documentation compress platform launch windows.
- Legacy Supply Chain Reconfiguration:Tier-1 internal combustion component suppliers face stranded asset risk as OEMs consolidate procurement around integrated e-axle systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicles Component Market |
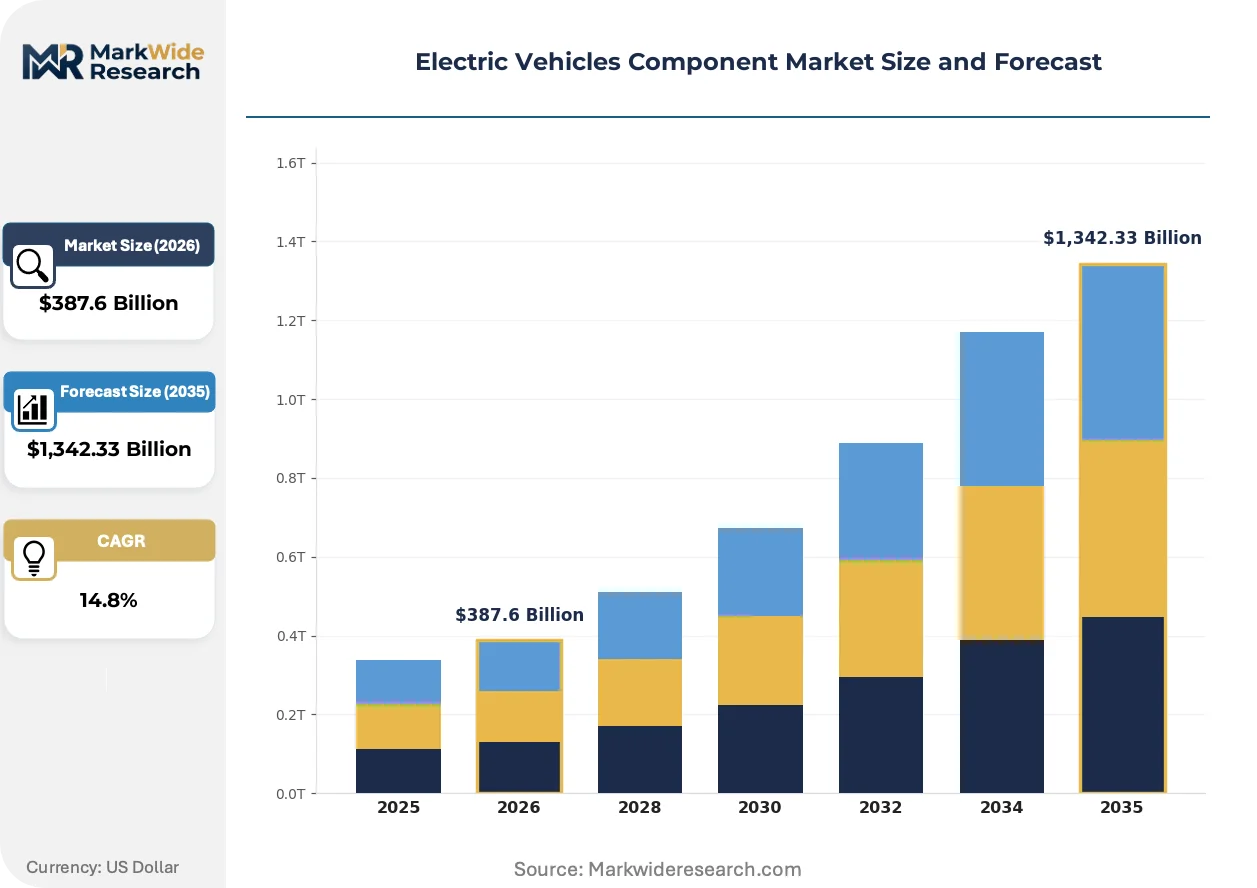
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,342.33 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Battery, Electric Motor, Charger, Inverter Technology: Lithium-Ion, Solid-State, Fuel Cell, Induction End User: OEMs, Aftermarket Providers, Fleet Operators, Charging Stations Material: Aluminum, Carbon Fiber, Copper, Lithium |
| Companies Covered | CATL, Bosch, ZF Friedrichshafen, Magna International, MAHLE, Nemak, Georg Fischer Casting Solutions, ABB, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicles Component Market Emerging Trajectories
Component architectures are compressing around integrated subsystems that merge thermal management, power conditioning, and energy storage into unified physical envelopes.
Silicon carbide MOSFET technology is fragmenting the power semiconductor landscape by enabling higher switching frequencies at elevated temperatures. Tier-1 suppliers are adopting these devices for 800-volt traction inverters, displacing silicon IGBT modules in next-generation platforms. This transition is fragmenting supplier relationships as semiconductor foundries capture margin previously held by discrete component assemblers.
REACH substance restrictions and EU battery passport requirements are reshaping supplier qualification criteria for European market entry. Cell manufacturers must now document carbon intensity and material provenance across extraction-to-assembly chains. European OEMs are responding by consolidating sourcing around vertically integrated cathode material producers with EU-based refining assets.
Fleet operators are unbundling battery system procurement from vehicle chassis contracts, creating separate financing and service agreements for energy storage assets. Leasing structures now dominate commercial EV procurement in North American logistics corridors, displacing traditional capital purchase models. This shift concentrates negotiating power among large fleet aggregators and compresses component supplier margins through volume-scale pricing agreements.
Electric Vehicles Component Market Segmentation
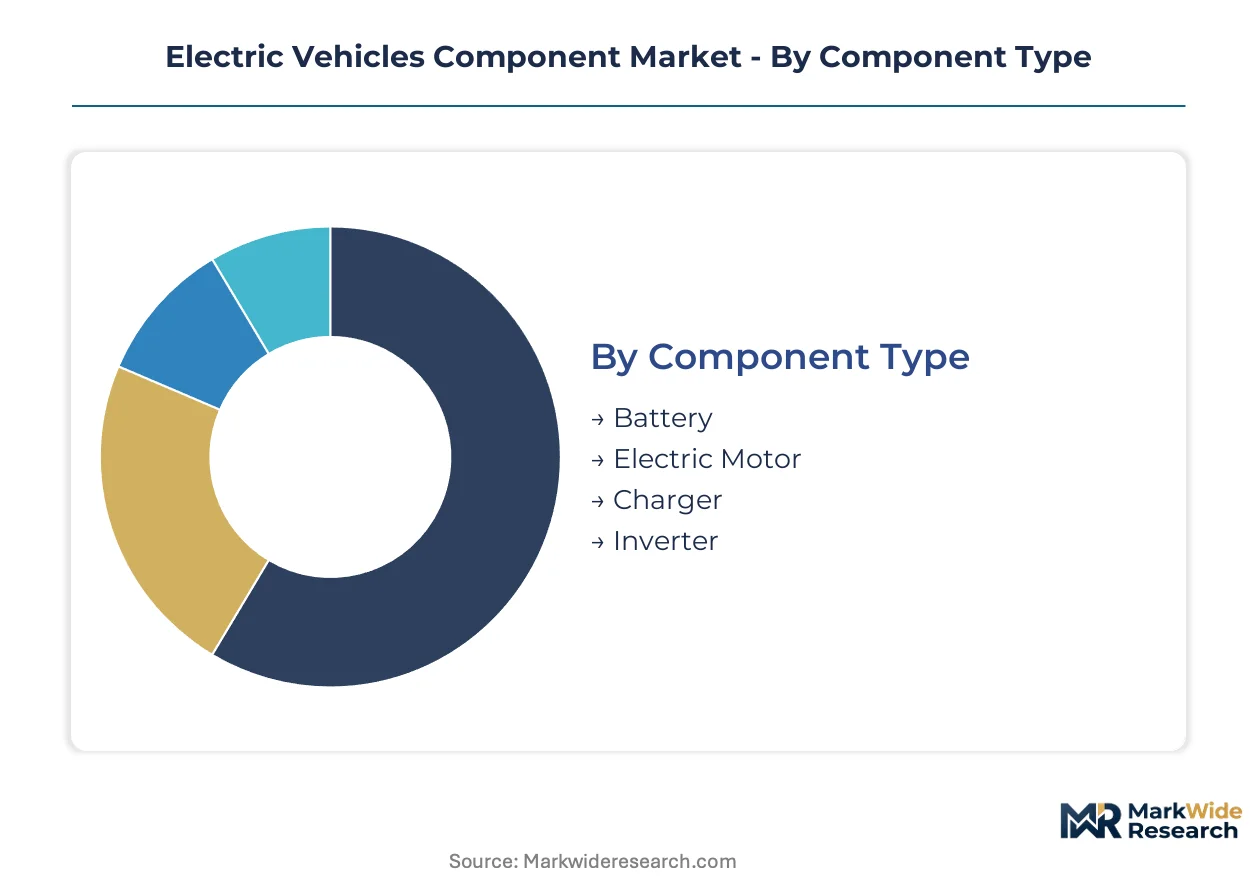
Component segmentation in the electric vehicle supply chain determines capital allocation across divergent technology maturity curves and regulatory compliance requirements. Suppliers must align production footprints with the geographic concentration of cathode material demand and the voltage architecture preferences of major OEM platforms.
Component Type:
Domestic production clusters in Germany and the United States supply battery and motor assemblies for regional OEMs, while inverter and charger manufacturing concentrates in East Asian export hubs serving multiple continents.
- Battery:Electrochemical storage cells utilizing nickel-manganese-cobalt or lithium-iron-phosphate cathodes constitute the highest value component within EV architectures. Demand concentrates around CATL's Ningdao facilities and Tesla's Nevada gigafactory, driven by EPA tailpipe standards mandating fleet electrification percentages. Pack assembly commands premium margins where silicon carbide battery management systems integrate with 800-volt platforms.
- Electric Motor:Permanent magnet synchronous machines and induction motors generate torque through copper windings and rare-earth rotor elements. Procurement volumes cluster with Bosch's Stuttgart e-axle manufacturing footprint and Nidec's Kyoto production lines, pulled by commercial fleet electrification timelines in North American logistics corridors. Torque density specifications differentiate premium passenger from heavy-duty commercial applications.
- Charger:Conductive charging interfaces operate at 400–800 volts DC with silicon carbide switching substrates for efficiency gains.
- Inverter:Power conditioning units convert DC battery output to AC motor drive signals, with silicon carbide MOSFET technology displacing silicon IGBT modules.
Battery holds the largest share; momentum sits with Inverter as voltage architectures climb toward 800-volt standards.
Technology:
Cost tiers separate commercialized liquid electrolyte systems from pre-commercial solid-state platforms requiring dry electrode coating infrastructure investment.
- Lithium-Ion:Liquid electrolyte cells with graphite anodes and layered oxide cathodes dominate current production volumes across cylindrical, prismatic, and pouch formats. Manufacturing concentrates in China's Jiangsu province and South Korea's Gyeonggi region, constrained by lithium price volatility in spodumene and brine markets. Cell producers compete on energy density metrics and fast-charge cycle durability.
- Solid-State:Sulfide and oxide electrolyte architectures promise higher energy density with improved thermal stability, though dendrite suppression challenges delay commercialization. Pilot-scale facilities in Toyota's Aichi prefecture and QuantumScape's San Jose location attract capital despite interface stability limitations. Dry electrode coating eliminates solvent-based processes, reducing facility footprint requirements.
- Fuel Cell:Proton exchange membrane systems convert hydrogen to electricity for extended-range commercial applications, with stack production clustering in Japan and Germany.
- Induction:Wireless power transfer technologies enable depot charging without physical connector wear, gaining traction in commercial fleet depot configurations.
Lithium-Ion retains dominant volume; Solid-State captures the steepest expansion trajectory as sulfide electrolyte synthesis matures.
End User:
Customer type determines procurement structure, with captive OEM sourcing contrasting against third-party fleet aggregator negotiations.
- OEMs:Original equipment manufacturers source components through vertically integrated programs or tier-1 supplier contracts, consolidating procurement around integrated e-axle systems to reduce assembly complexity. Volkswagen's Wolfsburg operations and General Motors' Detroit engineering centers specify battery pack geometries and thermal management protocols. Platform standardization decisions hinge on divergent NHTSA and EU battery passport certification timelines.
- Fleet Operators:Commercial vehicle aggregators unbundle battery procurement from chassis contracts, creating separate financing and service agreements for energy storage assets. Leasing structures dominate North American logistics corridor procurement, compressing supplier margins through volume-scale pricing. Depot-charging infrastructure buildout opens aftermarket service contracts for battery health monitoring.
- Aftermarket Providers:Diagnostic and refurbishment capabilities for out-of-warranty battery systems are building in European and North American service networks.
- Charging Stations:Infrastructure operators procure power electronics and connector hardware for public and private charging networks, with demand tied to utility interconnection approvals.
OEMs command the largest procurement volumes; aftermarket providers are expanding most quickly as first-generation EVs exit warranty coverage.
Material:
Supply concentration for refined materials shapes geographic procurement patterns and carbon intensity documentation requirements.
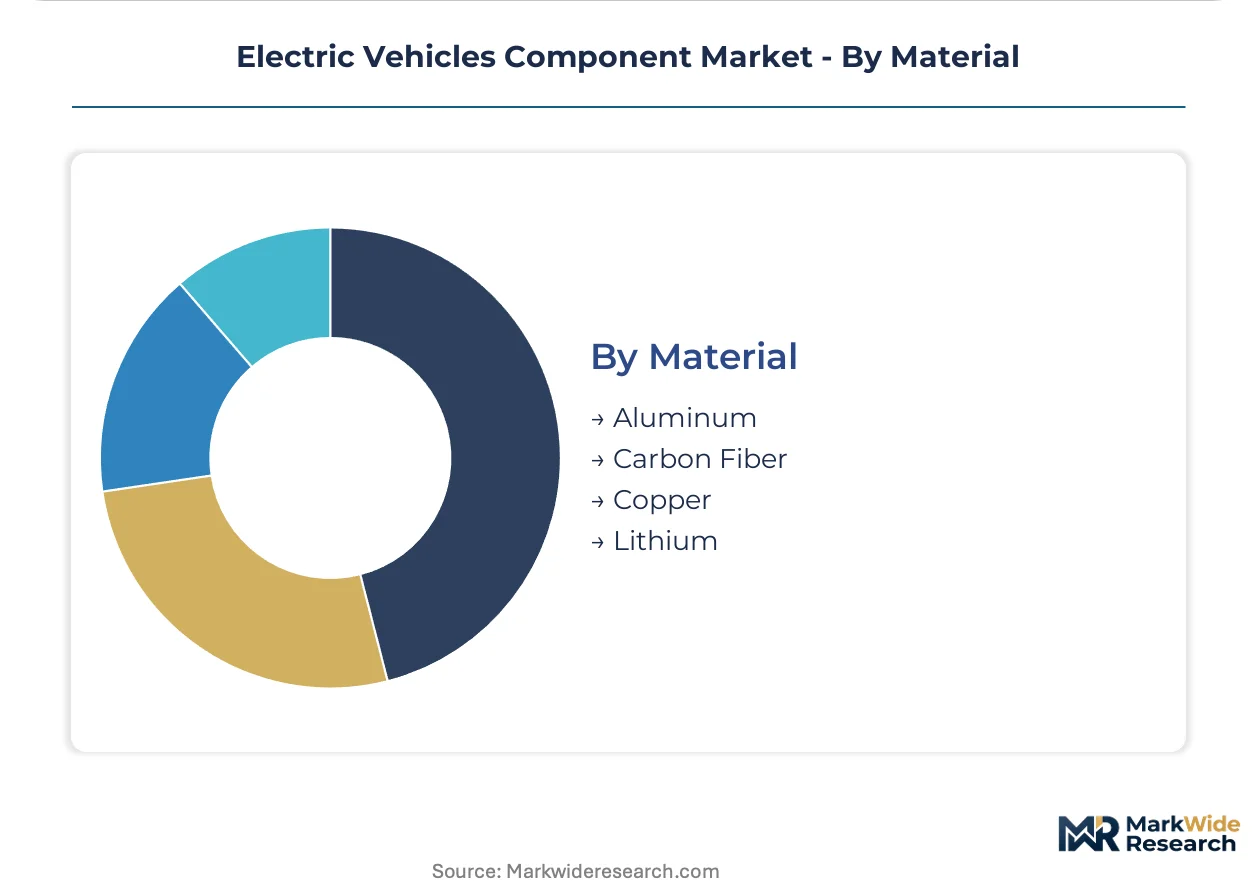
- Lithium:Spodumene hard-rock deposits in Western Australia and brine evaporation ponds in Chile's Atacama supply carbonate and hydroxide for cathode production. Refining capacity clusters in China's Sichuan province, creating single-point vulnerability for European and North American cell manufacturers. REACH substance restrictions and EU battery passport mandates reshape supplier qualification criteria toward provenance documentation.
- Copper:High-conductivity winding wire for electric motors and busbar connections draws from Chilean concentrate and Zambian smelter output, with fabrication in German and Japanese wire-drawing facilities.
- Aluminum:Lightweight structural castings and thermal management housings utilize primary and recycled feedstock, with extrusion and die-casting concentrated near OEM assembly plants.
- Carbon Fiber:High-strength composite materials enable mass reduction in premium vehicle architectures, with precursor production in Japan and the United States.
Copper holds the largest share by tonnage; Lithium gains share fastest as cathode active material demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys EV components at manufacturing scale, while Germany and the United States concentrate procurement around premium platform engineering and fleet electrification mandates respectively.
China
CATL's Ningdao facilities and BYD's Shenzhen operations anchor cathode active material demand, processing the majority of global lithium carbonate. MIIT dual carbon goals and GB standards for new energy vehicles compress supplier qualification timelines. Jiangsu province cell manufacturing clusters attract precursor chemical investment from Korean and Japanese material suppliers seeking proximity to OEM assembly plants.
Germany
Bosch's Stuttgart e-axle manufacturing footprint and Volkswagen's Wolfsburg engineering centers specify integrated powertrain architectures for European platforms. REACH substance restrictions and EU battery passport mandates reshape supplier documentation requirements toward carbon intensity tracking. Bavarian automotive clusters concentrate inverter and charging hardware production for export to Nordic and Benelux markets.
United States
EPA tailpipe standards and NHTSA corporate average fuel economy rules cascade into powertrain component procurement volumes across commercial vehicle operators. Tesla's Nevada gigafactory and General Motors' Detroit engineering centers specify battery pack geometries for 800-volt platform transitions. Midwest manufacturing corridors attract silicon carbide semiconductor foundry investment to serve domestic OEM thermal management requirements.
Japan
Panasonic's Osaka cylindrical cell production and Toyota's Aichi prefecture solid-state pilot facilities attract capital despite interface stability limitations. METI technology roadmaps prioritize sulfide electrolyte synthesis infrastructure for next-generation energy density targets. Kyoto electric motor manufacturing clusters supply torque density specifications for premium passenger and heavy-duty commercial applications.
South Korea
LG Energy Solution's Gyeonggi region facilities and Samsung SDI's domestic production lines compete on fast-charge cycle durability metrics. MFDS-equivalent transportation safety validation and KBA certification requirements compress platform launch windows for European market entry. Seoul capital area semiconductor foundries capture margin from silicon carbide MOSFET transitions in traction inverter assemblies.
Electric Vehicles Component Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with battery cell producers and power electronics fabricators occupying distinct competitive lanes. Consolidation pressures concentrate procurement decisions around vertically integrated cathode material suppliers with captive refining assets. Three archetypes dominate: Asian cell manufacturers with upstream chemical control, European tier-1 system integrators with e-axle manufacturing footprints, and semiconductor foundries capturing margin from silicon carbide transitions. Competitive moves center on capacity expansion in sulfide electrolyte synthesis and strategic partnerships for solid-state pilot-scale facilities.
Within the integrated cell manufacturing tier, CATL and Panasonic exemplify divergent geographic and format strategies. CATL occupies a position anchored in Chinese vertical chemical control, while Panasonic represents sustained investment in cylindrical high-nickel chemistry lines. Among European system integrators, Bosch anchors demand through its consolidated e-axle procurement relationships with regional OEMs. These three entities sit within distinct competitive lanes that resist direct substitution.
| Leading Market Players |
|---|
| CATL |
| Bosch |
| ZF Friedrichshafen |
| Magna International |
| MAHLE |
| Nemak |
| Georg Fischer Casting Solutions |
| ABB |
| Panasonic |
| Others |
Supply Flow & Price Mechanics
Ninety-day cathode precursor inventory cycles in European cell manufacturing anchor pricing power with Chinese lithium refiners, compressing margin flexibility for downstream pack assemblers facing EPA tailpipe compliance deadlines. This lead-time asymmetry concentrates contract negotiation leverage among vertically integrated material suppliers while forcing OEMs into long-term offtake commitments to secure volume allocation.
Pricing Analysis
Long-term offtake contracts dominate battery cell procurement, with spot markets confined to marginal lithium carbonate volume and project-based pricing reserved for solid-state pilot-scale output. Price differentiation rests on cathode chemistry grade and silicon carbide certification tier, with NMC811 cells commanding premiums over LFP alternatives. Cost compression in standard-range passenger segments is intensifying because fleet aggregators extract volume-scale concessions. Commercial fleet operators exhibit highest price sensitivity, while premium OEM platforms show lowest.
Supply Chain Analysis
Inventory buffers at Jiangsu province cell manufacturing clusters average sixty days of lithium hydroxide coverage, exposing European and North American assemblers to supply interruption risk. Geographic supply concentration centers on China, South Korea, and Japan for cell production, with cathode precursor processing anchored in China's Sichuan province. Raw material dependencies draw from Australian spodumene, Chilean brine, and Indonesian nickel laterite. Single-source vulnerability in sulfide electrolyte synthesis creates chokepoint exposure. Distribution runs through tier-1 system integrators with captive e-axle assembly footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American logistics corridors is shifting procurement leverage toward volume aggregators, fragmenting supplier pricing power as battery procurement unbundles from chassis contracts.
For Market Incumbents: Consolidate cathode material refining capacity within EU and US jurisdictions to offset REACH substance restriction compliance costs and reduce single-point exposure to East Asian precursor processing. Lock in silicon carbide semiconductor supply through foundry partnerships as 800-volt platform transitions accelerate. Prioritize dry electrode coating R&D to capture solid-state chemistry margins before pilot-scale facilities achieve commercial scale. For New Entrants and Emerging Players: EU battery passport certification fast-tracks offer entry pathway for software-enabled lifecycle tracking providers, with second-life battery refurbishment representing the most penetrable white-space. Target aftermarket diagnostic services for out-of-warranty NMC packs in European service networks. Pursue depot-charging infrastructure partnerships with commercial fleet aggregators as anchor customer acquisition channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state electrolyte synthesis infrastructure, favoring early-stage sulfide chemistry specialists with pilot-scale validation over liquid electrolyte incumbents facing stranded asset risk. Five-to-ten-year viability hinges on interface stability resolution and OEM qualification timelines. Acquisition target archetype: vertically integrated cathode producers with EU-based refining assets and carbon intensity documentation capabilities. Signal to watch: NHTSA-EU battery passport regulatory convergence accelerating platform standardization decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Partnership | Locks in sulfide electrolyte supply for next-generation energy density platforms ahead of commercialization. |
| Silicon Carbide Foundry Investment | Captures margin from 800-volt traction inverter transitions displacing silicon IGBT modules. |
| EU Battery Passport Compliance Program | Enables European market entry through carbon intensity documentation and material provenance tracking. |
| Commercial Fleet Service Contract Expansion | Secures recurring revenue from battery health monitoring and predictive thermal management systems. |
| Integrated E-Axle Manufacturing Scale-Up | Consolidates procurement relationships with OEMs seeking reduced assembly complexity and faster platform launches. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement directors, commercial fleet operations managers, and aftermarket service network heads, then refined through secondary validation against SEC 10-K filings, EPA regulatory dockets, IHS Markit vehicle production databases, and EU battery passport technical documentation. Bottom-up cell production capacity modeling was triangulated with top-down OEM procurement volume estimates.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution. Forecast inputs incorporated silicon carbide adoption curves in traction inverters and solid-state chemistry commercialization timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EPA tailpipe standard enforcement and lithium price volatility within historical bands; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Electric Forklifts Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Headlight Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Global Boat Trailers Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Trailers and Semi-Trailers Market