
 Global Electric Motor Market | 2026-2036
Global Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Motor Market Analysis
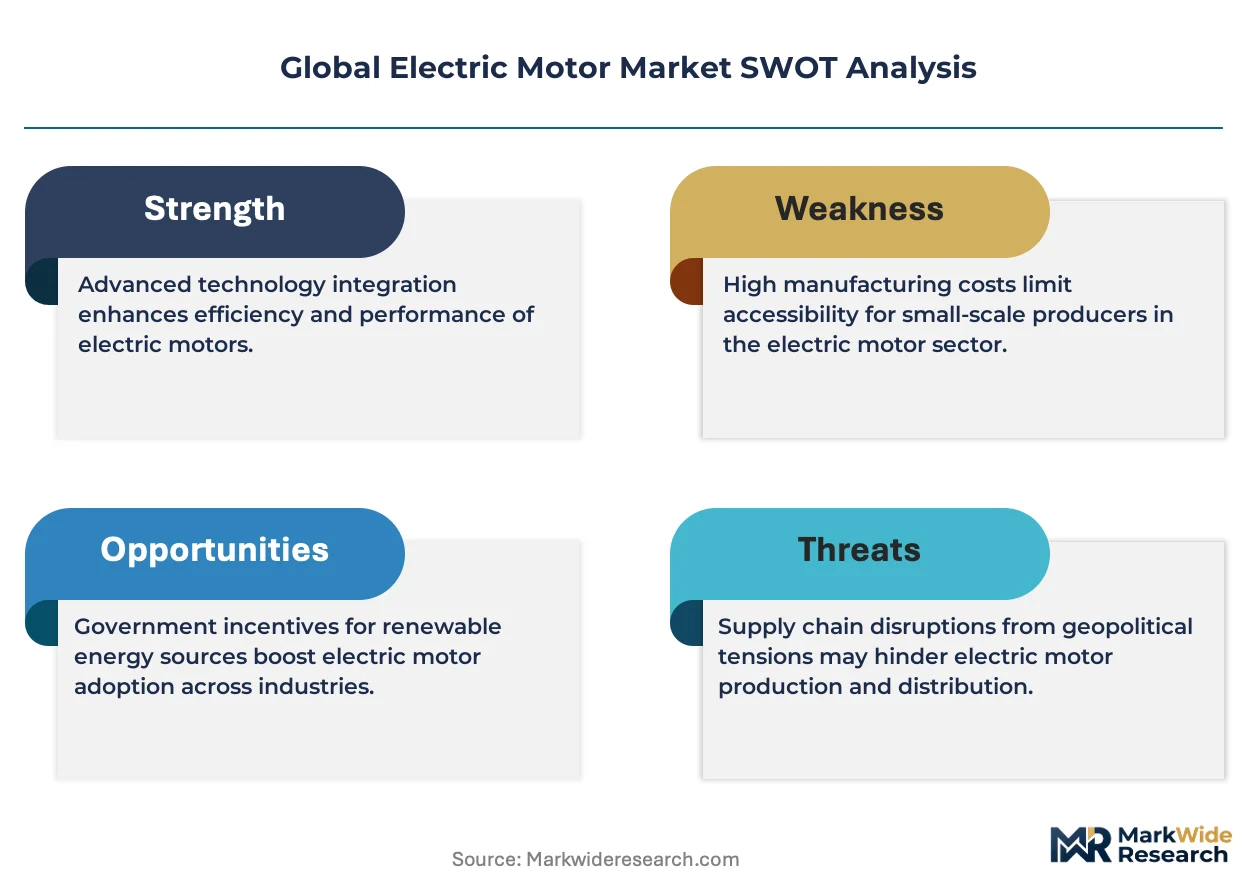
Data center cooling operators is reorganizing procurement priorities toward high-efficiency HVAC motors, pulling demand away from traditional industrial machinery buyers. Nidec Corporation dominates fractional horsepower supply for consumer appliances through vertically integrated magnet sourcing. Siemens anchors large-drive systems for process industries with embedded digital diagnostics. WEG competes aggressively in renewable energy nacelle applications from its Brazilian manufacturing base.
An electric motor converts electrical energy into mechanical rotation through electromagnetic interaction between stator windings and a rotor assembly, typically achieving efficiency ratings from IE1 through IE5 depending on lamination quality, conductor material, and control algorithm precision. AC motors sustain the largest revenue pool across industrial infrastructure, while brushless DC architectures capture the fastest expansion in robotics and electric vehicle traction applications where precise torque vectoring matters. Servo motor demand concentrates in aerospace actuation and semiconductor manufacturing equipment where positional accuracy below one arc-minute justifies premium pricing.
The US Department of Energy enforces minimum efficiency standards through its motor rulemaking framework, while the EU Ecodesign Directive phases out IE2-rated units in favor of IE3 and IE4 classifications across member states. China's GB 18613 standard mandates IE3 minimums for general-purpose motors above certain power thresholds, tightening market access for non-compliant imports. Stakeholders must monitor rare earth supply chain concentration in upstream magnet processing and evaluate alternative ferrite or synchronous reluctance designs before regulatory deadlines compress.
Market Dynamics
Silicon carbide inverter pairing with permanent magnet motors is compressing powertrain dimensions while multiplying torque density, forcing incumbent suppliers to retool lamination stacks and magnet architectures or surrender traction contracts to integrated drivetrain specialists.
Growth Catalysts
- IE3 Mandates:China's GB 18613 standard and the EU Ecodesign Directive phase out IE2-rated motors above threshold power ratings, compelling fleet retrofits and new equipment procurement across manufacturing bases.
- Data Center Cooling:Hyperscale operators in Northern Virginia and Frankfurt prioritize high-efficiency HVAC motors, redirecting demand from traditional industrial machinery channels toward precision airflow management systems.
- Copper Substitution:Aluminum winding adoption in fractional horsepower ranges reduces raw material exposure while maintaining conductivity adequate for appliance and pump duty cycles.
Market Restraints
- Neodymium Concentration:Rare earth magnet processing clusters in Jiangxi and Inner Mongolia create single-source vulnerability for permanent magnet motor supply chains serving automotive and aerospace actuation.
- IE5 Cost Barrier:Amorphous metal laminations and advanced conductor geometries push premium motor costs beyond payback horizons for price-sensitive agricultural pump and compressor OEMs.
- Synchronous Reluctance Limits:Torque ripple and power factor constraints restrict brushless alternatives to constant-speed applications, blocking penetration into servo positioning and traction markets.
Strategic Opportunities
- India Industrialization:PLI scheme incentives for domestic motor manufacturing attract greenfield investment targeting textile processing and cement grinding applications in Gujarat and Tamil Nadu.
- Aviation Electrification:Distributed propulsion architectures for regional electric aircraft demand fault-tolerant motor designs with kilowatt densities exceeding conventional industrial benchmarks.
- Digital Diagnostics Convergence:Embedded vibration and thermal sensors married to edge analytics enable predictive maintenance contracts, shifting revenue from hardware sales to uptime guarantees.
Industry Challenges
- Lamination Stamping Expertise:Thin-gauge electrical steel processing requires tool-and-die craftsmanship scarce in emerging manufacturing regions, constraining local content targets.
- Multi-Standard Certification:Simultaneous compliance with US Department of Energy rulemaking, EU Ecodesign, and China GB standards extends validation timelines and fragments test facility capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Motor Market |
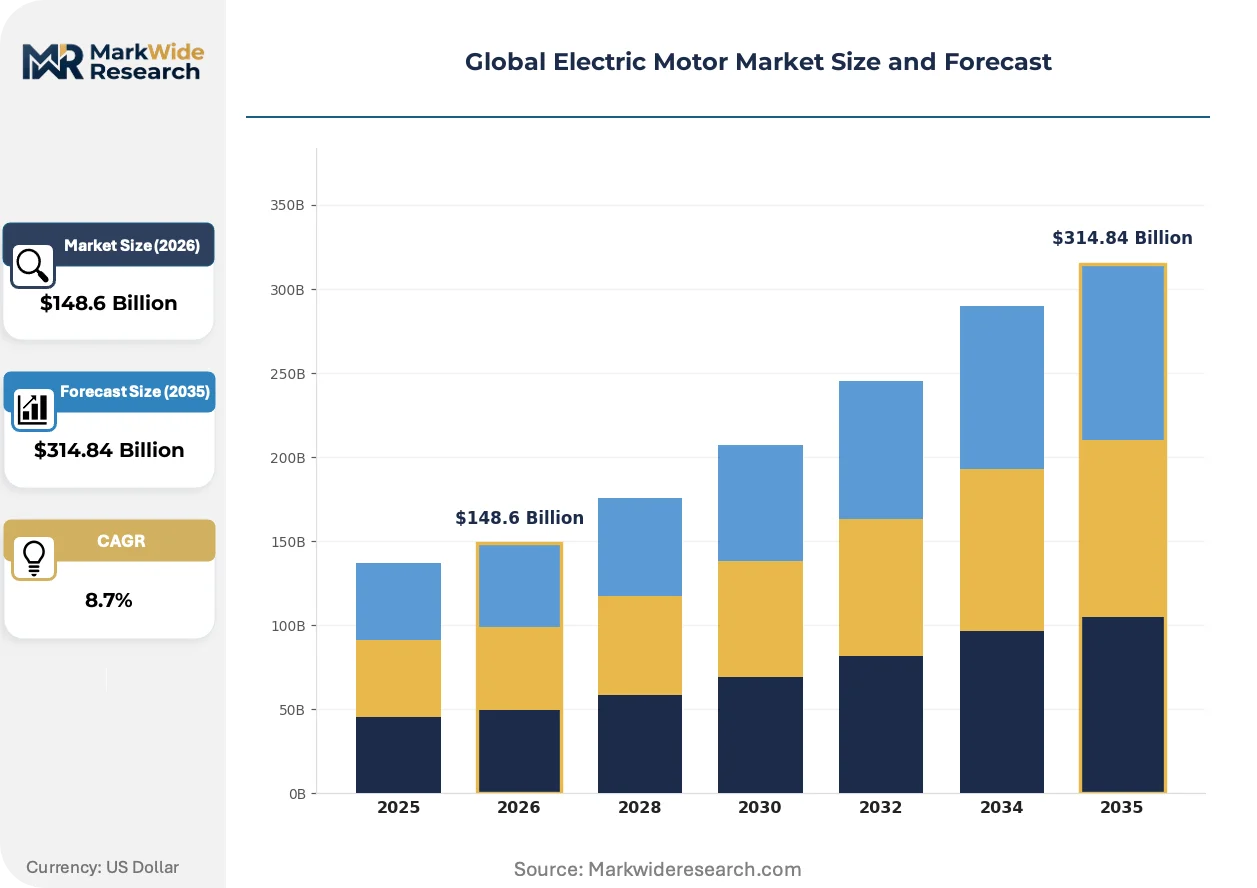
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $314.84 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motor, DC Motor, Stepper Motor, Servo Motor End User: Industrial Machinery, HVAC, Automotive, Renewable Energy Technology: Brushless, Brushed, Synchronous, Asynchronous Application: Consumer Appliances, Robotics, Transportation, Aerospace |
| Companies Covered | Denso Corporation, WEG, Nidec Corporation, General Electric, Bosch, ABB, Johnson Electric, Toshiba Corporation, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Motor Market Emerging Trajectories
Magnet architecture and thermal management are converging to redefine performance ceilings across power classes, with material science advances enabling geometries previously constrained by demagnetization thresholds and copper losses.
Hairpin winding configurations are displacing traditional round-wire stator constructions in automotive traction and commercial vehicle applications. Tier 1 suppliers in Stuttgart and Detroit have transitioned volume programs to flattened conductor geometries that improve slot fill factors above 70 percent. The technology is displacing conventional distributed windings in platforms above 50 kilowatts, compressing motor axial length while raising continuous power ratings.
The EU F-Gas Regulation and REACH restrictions on fluorinated compounds are accelerating hydrocarbon and CO2 refrigeration system adoption. These alternative refrigerants operate at higher pressures and temperatures, demanding motor insulation systems rated for elevated thermal stress and chemical exposure. Compressor OEMs in Italy and Poland are qualifying modified stator varnishes and bearing seals to maintain warranty coverage under revised duty cycles.
Buyers in process industries are unbundling motor supply from installation and commissioning services, treating rotating equipment as standardized commodities sourced through industrial distributors rather than direct manufacturer relationships. This pattern is most pronounced in German chemical processing and US water utility sectors, where maintenance departments maintain qualified vendor lists and negotiate frame-size interchangeability across multiple suppliers.
Global Electric Motor Market Segmentation
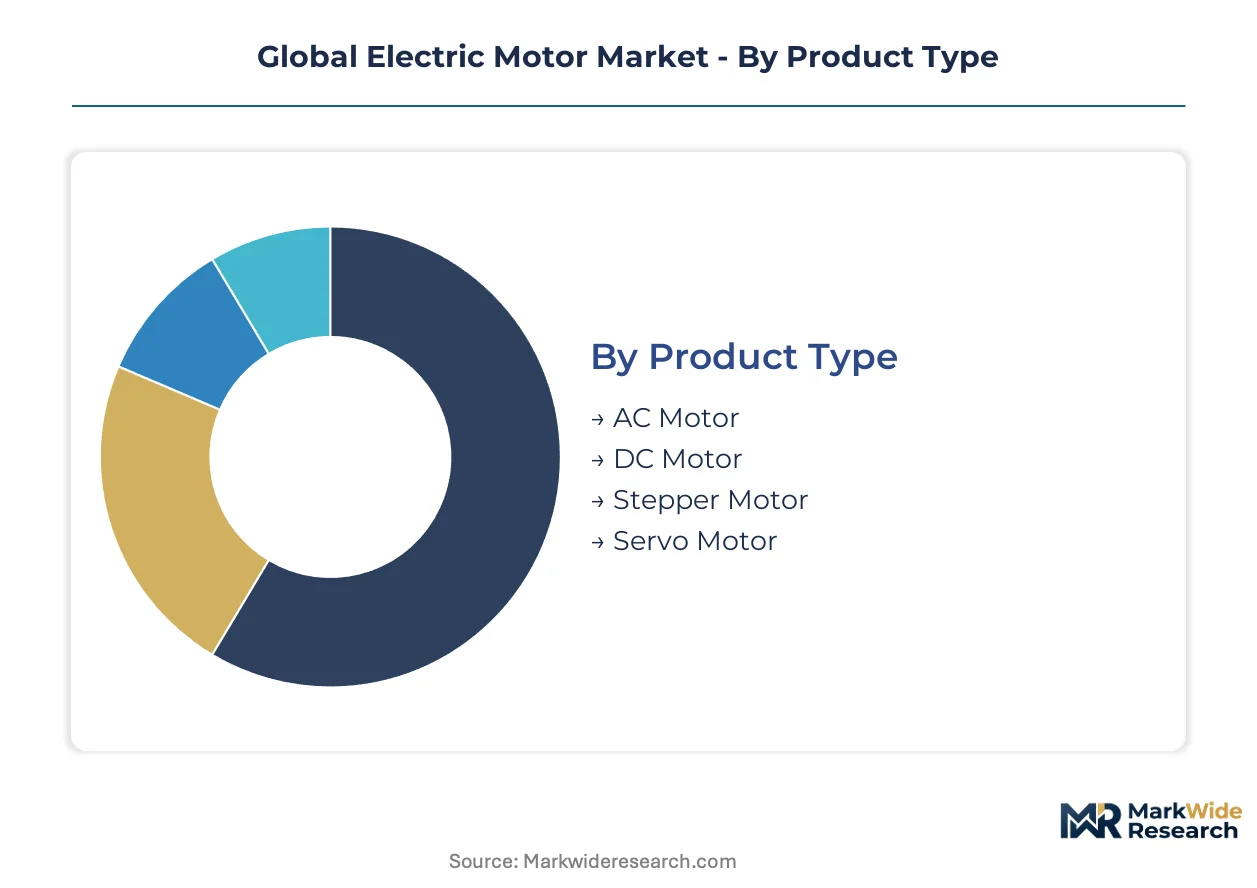
Electric motor segmentation reveals divergent margin structures across product architectures and end-use verticals. Technology choices determine raw material exposure and regulatory compliance pathways, while application mix dictates service intensity and pricing power.
Product Type:
Margin pools concentrate in high-efficiency permanent magnet designs where magnet sourcing and lamination precision create differentiation.
- AC Motor:Induction and synchronous architectures dominate industrial infrastructure with IE3 and IE4 efficiency ratings. Demand clusters in Chinese manufacturing bases and German process industries as energy mandates tighten. The technology benefits from mature supply chains but faces pressure from silicon carbide inverter pairings in premium segments.
- DC Motor:Brushed and brushless configurations serve automotive traction and robotics where torque vectoring precision matters. Automotive OEMs in Stuttgart and Detroit are pulling volume toward hairpin-wound permanent magnet variants. Magnet supply concentration in Jiangxi and Inner Mongolia creates cost volatility for this segment.
- Stepper Motor:Incremental rotation control for 3D printing and semiconductor positioning equipment.
- Servo Motor:Closed-loop feedback systems for aerospace actuation and CNC machinery demanding sub-arc-minute accuracy.
The dominant share belongs to AC Motor, while DC Motor is closing the gap fastest.
End User:
Customer procurement patterns range from commodity distributor purchasing to integrated drivetrain partnerships, reshaping vendor economics.
- Industrial Machinery:Pumps, compressors, and conveyors constitute the volume foundation with replacement cycles tied to capital expenditure cycles. German chemical processors and US water utilities are unbundling motor supply from installation services, treating units as interchangeable commodities.
- HVAC:Data center cooling operators in Northern Virginia and Frankfurt are redirecting procurement toward high-efficiency precision airflow systems. Hyperscale facility expansion is displacing traditional industrial channels as the demand engine.
- Automotive:Electric vehicle powertrain integration is compressing supplier tiers toward drivetrain specialists.
- Renewable Energy:Wind turbine nacelle applications favor direct-drive permanent magnet generators with fault-tolerant designs.
Industrial Machinery retains the largest installed base, though HVAC is expanding most quickly.
Technology:
Architecture selection determines magnet dependence, control complexity, and thermal management requirements.
- Brushless:Permanent magnet and reluctance variants eliminate commutator maintenance while enabling precise digital control. Robotics and electric vehicle traction applications favor this technology for torque density and efficiency. The design requires rare earth magnet supply security or ferrite alternative qualification.
- Synchronous:Rotor field locking to stator frequency enables constant-speed operation with power factor correction. Process industries in cement and textiles deploy these motors where grid stability matters. Amorphous metal laminations push IE5 efficiency but cost premiums limit penetration.
- Brushed:Commutator-based designs persist in cost-sensitive fractional horsepower applications.
- Asynchronous:Induction motors dominate general-purpose industrial duty with simpler control requirements.
Brushless architectures command premium positioning, while Synchronous designs are gaining share fastest in efficiency-sensitive installations.
Application:
Use-case environments dictate insulation ratings, sealing requirements, and diagnostic feature integration.
- Transportation:Electric vehicle traction and commercial vehicle electrification demand fault-tolerant designs with kilowatt densities exceeding industrial benchmarks. Aviation electrification for regional aircraft is pulling motor performance into uncharted territory. Thermal management and redundancy certification extend development timelines.
- Robotics:Collaborative and industrial automation requires compact frame sizes with precise positional feedback. Semiconductor manufacturing equipment and surgical robotics justify servo-grade accuracy. Integration with harmonic drives and encoders creates subsystem partnerships.
- Consumer Appliances:Fractional horsepower motors face aluminum winding substitution and distributor channel consolidation.
- Aerospace:More-electric aircraft architectures demand high-reliability actuation with extended temperature ranges.
Transportation captures the steepest expansion trajectory, with Robotics following in positioning precision markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's industrial motor distribution, while China's ultra-high-voltage grid interconnects anchor Asia-Pacific manufacturing concentration. Germany's Rhine-Main corridor and India's Western Dedicated Freight Corridor complete the infrastructure backbone shaping regional supply patterns.
China
Electric vehicle powertrain demand from BYD and CATL suppliers drives permanent magnet motor expansion. GB 18613 mandates IE3 minimum efficiency for general-purpose motors above threshold power ratings. Jiangxi and Inner Mongolia processing clusters concentrate rare earth magnet supply, creating single-source vulnerability for automotive traction applications.
Germany
Process industry retrofits and chemical sector efficiency upgrades sustain large-drive system procurement. EU Ecodesign Directive phases out IE2-rated units in favor of IE3 and IE4 classifications across member states. Stuttgart anchors automotive traction development, while Ruhr Valley industrial bases demand embedded digital diagnostics for predictive maintenance contracts.
United States
Data center cooling operators in Northern Virginia redirect HVAC motor procurement toward precision airflow management. Department of Energy motor rulemaking enforces minimum efficiency standards through federal procurement guidelines. Detroit's electrification programs compress supplier tiers toward integrated drivetrain specialists serving commercial vehicle platforms.
India
Textile processing and cement grinding applications in Gujarat and Tamil Nadu attract greenfield manufacturing investment. PLI scheme incentives for domestic motor manufacturing reduce import dependence for industrial infrastructure. Western Dedicated Freight Corridor connectivity improves component logistics between Mumbai port hinterlands and northern manufacturing zones.
Brazil
Renewable energy nacelle applications favor direct-drive permanent magnet generators for wind turbine installations. ANVISA regulatory alignment with IEC standards streamlines certification for export-oriented producers. WEG's manufacturing base in Santa Catarina competes aggressively for Latin American renewable energy project contracts.
Global Electric Motor Market Vendor Landscape
Concentration sits with diversified industrial conglomerates controlling fractional horsepower supply and large-drive systems simultaneously. The vendor base organizes into three strategic archetypes: vertically integrated magnet processors, systems integrators with embedded diagnostics capabilities, and regional specialists serving renewable energy nacelle applications. Dominant competitive moves include backward integration into rare earth magnet sourcing and capacity expansion targeting electric vehicle traction contracts.
Within the diversified conglomerate tier, Nidec Corporation and Siemens occupy positions spanning consumer appliance fractional horsepower through industrial megawatt-class systems. WEG exemplifies the regional specialist archetype, anchoring Latin American renewable energy supply from its Brazilian manufacturing base. These three entities represent contrasting strategic postures: captive magnet supply security, digital diagnostics convergence, and geographic specialization respectively.
| Leading Market Players |
|---|
| Denso Corporation |
| WEG |
| Nidec Corporation |
| General Electric |
| Bosch |
| ABB |
| Johnson Electric |
| Toshiba Corporation |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Fractional horsepower scale economies in Chinese consumer appliance manufacturing compress unit economics while establishing price floors that smaller regional producers cannot match. GB 18613 efficiency mandates and EU Ecodesign Directive compliance costs concentrate procurement power among buyers capable of absorbing IE3 and IE4 certification premiums.
Pricing Analysis
Volume-discount tiering structures separate IE5 premium permanent magnet motors from IE3 standard induction units and IE2 economy replacements facing phase-out. Price differentiation hinges on lamination grade and silicon carbide inverter pairing capability, with automotive OEMs in Stuttgart and Detroit least sensitive and agricultural pump OEMs most cost-constrained. Cost compression in standard-efficiency tiers intensifies as aluminum winding substitution erodes copper-linked pricing benchmarks.
Supply Chain Analysis
China and Germany anchor rare earth magnet processing and precision lamination stamping respectively. Jiangxi and Inner Mongolia supply neodymium feedstock while Stuttgart and Detroit integrate hairpin winding production. Raw material exposure centers on electrical steel coils, copper and aluminum conductors, and permanent magnet alloys. Single-source vulnerability in upstream magnet refining threatens automotive traction supply chains. Distribution runs through industrial distributors unbundling motors from installation services in German chemical processing and US water utility sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around IE3 and IE4 efficiency mandates creates defensive moats for incumbents with certified manufacturing footprints and test facility access. Switching costs rise as multi-standard certification fragments validation capacity.
For Market Incumbents: Secure captive magnet supply through backward integration into Jiangxi and Inner Mongolia processing clusters or ferrite alternative qualification. Expand IE5 amorphous metal lamination capacity in Germany and the United States ahead of efficiency mandate tightening. Defend against integrated drivetrain specialists by embedding digital diagnostics for predictive maintenance contracts. For New Entrants and Emerging Players: Predictive maintenance service gaps in US water utilities and German chemical processing offer white-space entry where incumbents under-serve aftermarket intelligence needs. Target India's PLI scheme jurisdictions in Gujarat and Tamil Nadu for greenfield manufacturing cost advantages. Pursue aviation electrification partnerships with regional aircraft developers seeking fault-tolerant motor architectures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostics-embedded motor systems with uptime guarantee contracts rather than transactional hardware sales. Long-term viability favors suppliers with dual-source magnet security and multi-regional certification capability. Monitor rare earth export policy signals from China's Ministry of Commerce as inflection indicators for permanent magnet cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Jiangxi and Inner Mongolia supply security reduces automotive traction cost volatility. |
| IE5 Amorphous Metal Lamination Scale-Up | German and US capacity expansion captures efficiency mandate premium pricing. |
| Digital Diagnostics Platform Launch | Embedded sensors shift revenue from hardware sales to uptime guarantees in process industries. |
| Aviation Electrification Partnership | Regional aircraft distributed propulsion pulls motor performance beyond industrial benchmarks. |
| India PLI Scheme Manufacturing Entry | Gujarat and Tamil Nadu greenfield sites reduce import dependence for textile and cement applications. |
Methodological Framework
Cross-validation between motor OEM procurement leads and industrial distributor channel partners anchors the qualitative findings. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with customs trade data, SEC 10-K filings, and IHS Markit vehicle production databases. Bottom-up unit economics and top-down macroeconomic triangulation validate segment-level outputs.
Sensitivity analysis across product architecture, end-use vertical, and efficiency certification tier shapes the analytical framework. Segmentation models incorporate motor type, application environment, power rating class, and regional regulatory cluster throughout the forecast period. CAGRs derive from installed base replacement cycles, electrification penetration curves, and mandate compliance deadlines. Hyperscale data center capex trajectories and automotive platform electrification timelines feed sector-specific demand inputs.
Forecasts assume regulatory continuity in US Department of Energy rulemaking, EU Ecodesign Directive implementation, and China GB standards enforcement; material policy shifts would require re-modeling. Rare earth export restrictions, silicon carbide supply bottlenecks, or amorphous metal lamination capacity shortfalls could revise trajectory assumptions. Recalibration cycles align with material shifts in efficiency mandate deadlines and electrification program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Traction Motors Market
Electric Motor
Motorcycle Battery Market
Electric Motor
Frameless Motor Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Automotive Heater Fan Motor Market