
 Automotive Wheel Speed Sensor Market | 2026-2036
Automotive Wheel Speed Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Speed Sensor Market Analysis
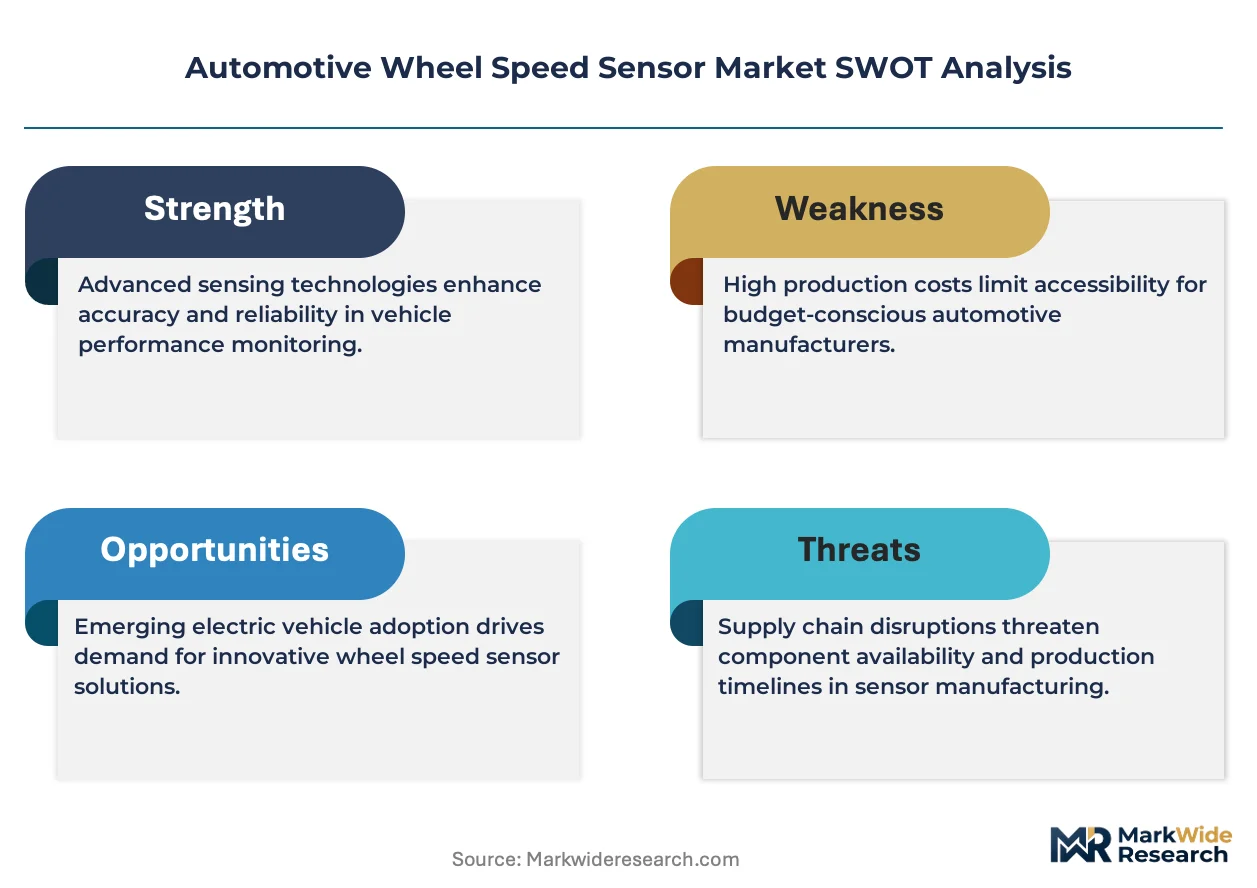
Magnetics engineering talent is rotating toward automotive sensor design as electrification programs drain analog semiconductor expertise from legacy suppliers. Robert Bosch GmbH leverages in-house wafer fabrication to sustain cost advantages across Hall Effect wheel speed modules. Continental AG anchors European OEM relationships through integrated braking-sensor bundles that reduce assembly complexity.
An automotive wheel speed sensor detects rotational velocity at each wheel hub, typically employing Hall Effect or variable reluctance principles with output signals ranging from zero to several kilohertz for ABS and traction control modules. These devices translate mechanical rotation into electrical pulses that powertrain controllers process for slip detection, torque vectoring, and odometer calibration. Hall Effect technology dominates premium vehicle platforms where immunity to dirt and vibration justifies higher unit costs, while inductive passive sensors retain volume share in economy segments where magnetic simplicity reduces failure modes. Active sensor architectures are displacing legacy passive units as OEMs consolidate wheel-end electronics to support brake-by-wire transitions.
NHTSA mandates electronic stability control on all light vehicles sold in the United States, forcing sensor precision upgrades that ripple through supplier qualification programs. ECE R13 and UN Regulation 78 govern braking system performance across European type approvals, with EMA-coordinated harmonization pushing unified test protocols that reduce certification duplication. Stakeholders must monitor how brake-by-wire architectures and centralized vehicle computing redefine whether wheel speed intelligence migrates to domain controllers or remains distributed at the axle.
Market Dynamics
Brake-by-wire electrification is compressing sensor architecture decisions as OEMs debate whether wheel-speed intelligence stays distributed at the axle or migrates to centralized domain controllers.
Growth Catalysts
- NHTSA ESC Mandate:Electronic stability control requirements on all light vehicles sold in the United States force precision upgrades that cascade through supplier qualification programs.
- Hall Effect Technology:Active Hall Effect architectures displace passive inductive units as electrified platforms demand immunity to vibration and contamination.
- China OEM Demand:Domestic automakers in China accelerate procurement of integrated axle-mounted sensor modules for battery-electric vehicle platforms.
Market Restraints
- Rare Earth Magnet Costs:Neodymium and dysprosium price volatility squeeze margins on Hall Effect sensor production concentrated in Asian processing facilities.
- Wafer Fabrication Concentration:Analog semiconductor foundry capacity for automotive-grade Hall ICs concentrates in Taiwan and South Korea, creating single-source vulnerability.
- Passive Sensor Substitution Resistance:Economy vehicle segments retain inductive variable reluctance sensors where magnetic simplicity outweighs performance gains.
Strategic Opportunities
- India Production Localization:PLI scheme incentives for automotive electronics manufacturing create white space for sensor module assembly serving domestic and export demand.
- Brake-by-Wire Convergence:Integration of wheel speed sensing with electromechanical brake actuators enables simplified wheel-end architectures.
- EMA Harmonization:Coordinated ECE R13 and UN Regulation 78 test protocols reduce certification duplication across European type approvals.
Industry Challenges
- Magnetics Engineering Scarcity:Electrification programs drain analog semiconductor expertise from legacy suppliers, forcing competitive recruiting for Hall Effect design talent.
- ISO 26262 Certification Timelines:Functional safety validation for ASIL-rated wheel speed modules extends development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Speed Sensor Market |
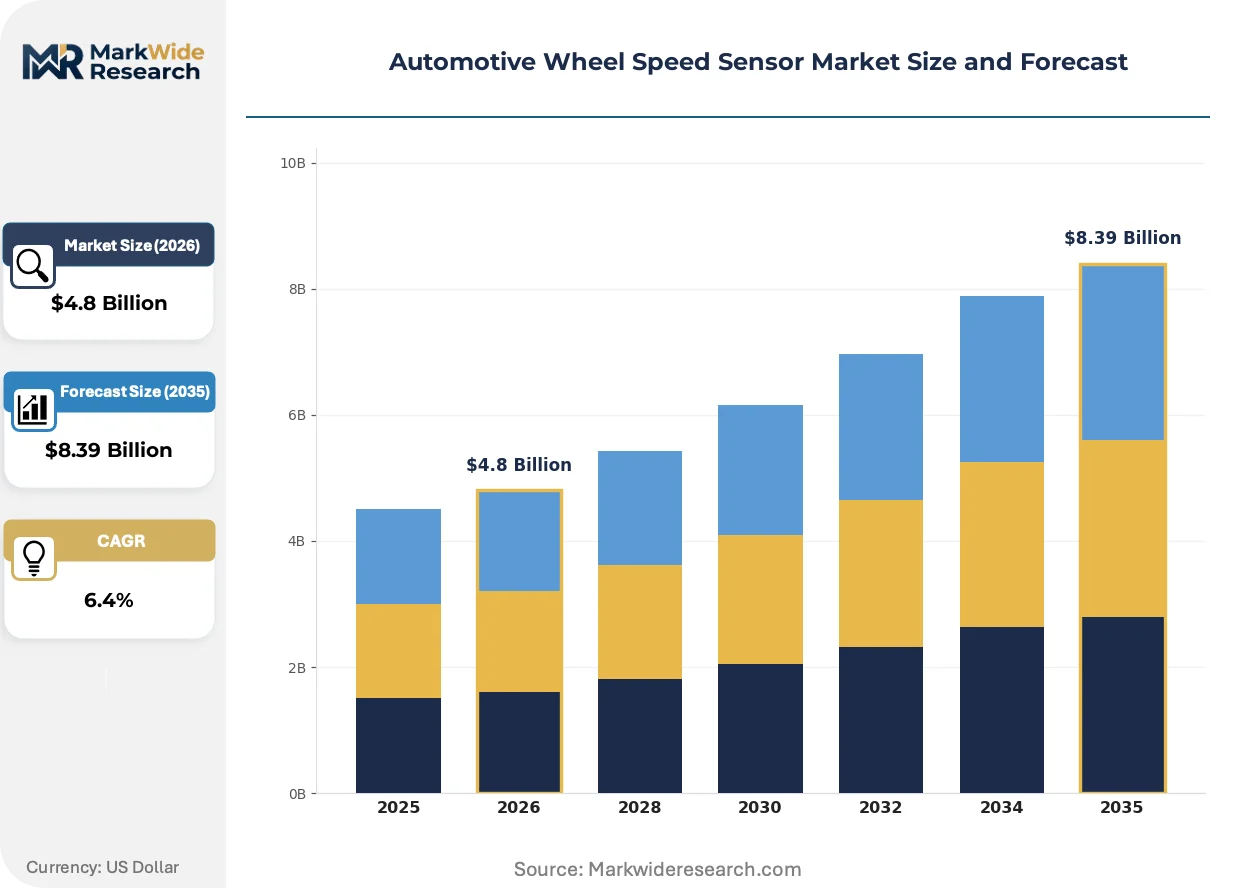
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Sensors, Active Sensors, Magnetic Sensors, Optical Sensors Technology: Inductive, Hall Effect, Infrared, MEMS End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation: Front Axle, Rear Axle, Integrated Systems, Standalone Units |
| Companies Covered | ZF Friedrichshafen AG, NXP Semiconductors, Robert Bosch GmbH, TE Connectivity, Hitachi Metals, Ltd., Continental AG, Hella GmbH & Co. KGaA, Melexis NV, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Speed Sensor Market Emerging Trajectories
Sensor intelligence is migrating from discrete measurement units toward integrated wheel-end systems that combine speed detection with bearing condition monitoring and brake temperature sensing.
Active Hall Effect sensor architecture is bifurcating the market into premium platforms demanding sealed, vibration-immune packages and economy segments tolerating simpler inductive solutions. Luxury OEMs in Germany and the United States specify fully encapsulated Hall modules for brake-by-wire readiness. This technology divergence is compressing supplier R&D budgets as dual product lines require parallel qualification investments.
ECE R13 and UN Regulation 78 harmonization through EMA coordination is standardizing braking system performance tests across European type approvals. The industrial consequence eliminates redundant certification procedures for suppliers serving multiple EU national markets. Wheel speed sensor manufacturers with German KBA relationships gain first-mover advantage in streamlined approval pathways.
Buyer concentration among tier-1 braking system integrators is consolidating procurement decisions toward bundled sensor-actuator packages. Continental AG and Robert Bosch GmbH now specify wheel speed modules as subcomponents of integrated braking contracts rather than standalone purchases. This channel compression is most visible in European OEM relationships where brake system outsourcing has advanced furthest.
Automotive Wheel Speed Sensor Market Segmentation
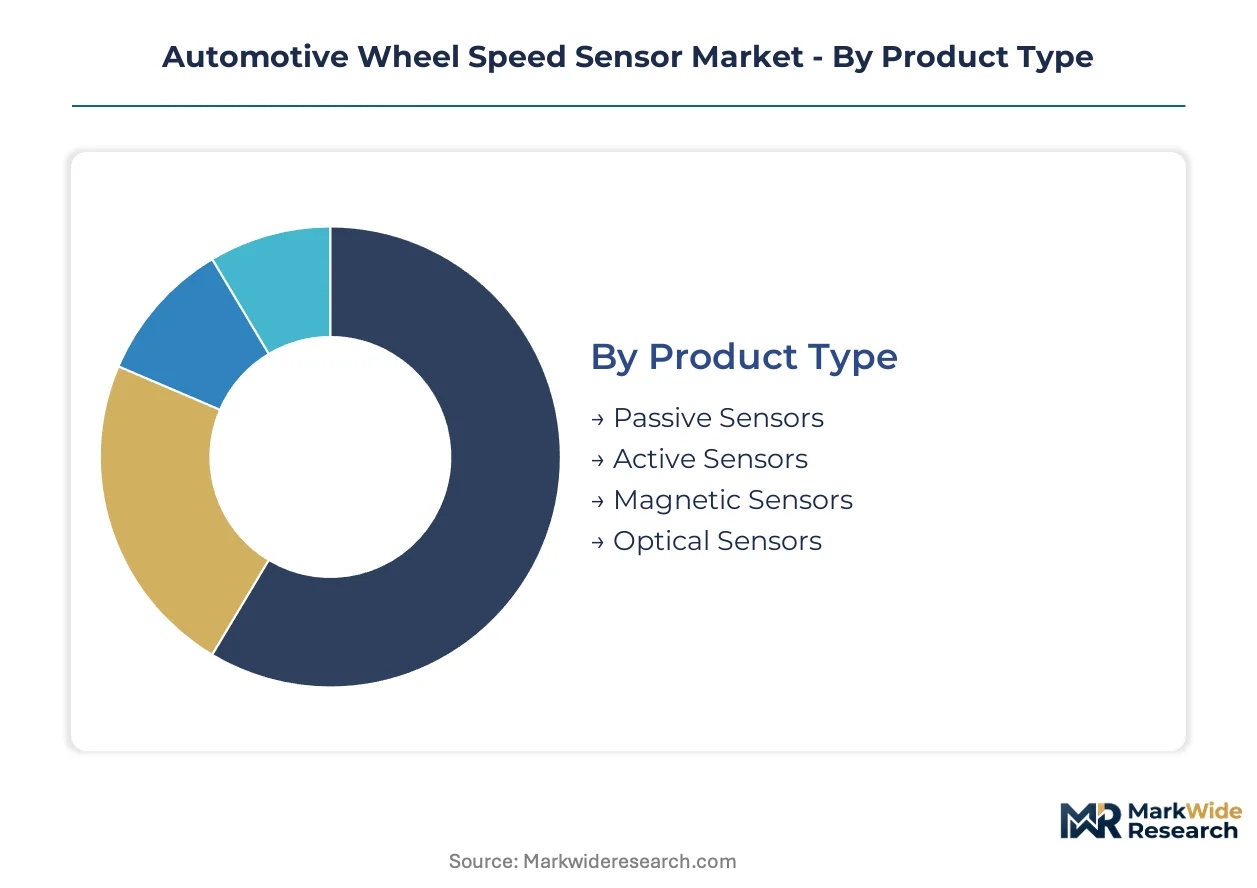
Wheel speed sensor procurement splits across incompatible technical standards and divergent supply chain logics. OEMs source integrated axle-mounted units through tier-1 braking contracts, while aftermarket channels serve legacy vehicle parc with standalone replacements.
Product Type:
NHTSA electronic stability control mandates and ECE R13 braking performance rules create divergent certification burdens across active versus passive architectures.
- Active Sensors:Sealed Hall Effect architectures with integrated signal conditioning circuits deliver vibration immunity for brake-by-wire platforms. German and United States luxury OEMs specify these units exclusively for ESC-compliant vehicle programs.
- Passive Sensors:Variable reluctance designs with wound copper coils and permanent magnets serve economy vehicle segments where magnetic simplicity reduces failure modes. China domestic automakers retain these units for cost-optimized battery-electric platforms.
- Magnetic Sensors:Rare-earth magnet assemblies face neodymium price volatility from Asian processing concentration.
- Optical Sensors:Photoelectric encoders find limited automotive adoption due to contamination sensitivity in wheel-end environments.
Active sensors handle the majority of new vehicle throughput; passive sensors are expanding most quickly in emerging market economy segments.
Technology:
Wafer fabrication capacity for automotive-grade Hall ICs concentrates in Taiwan and South Korea, concentrating cost structures for premium sensor tiers.
- Hall Effect:Semiconductor-based magnetic field detection enables zero-speed measurement and direction discrimination critical for ABS modulation. Robert Bosch GmbH and Continental AG anchor European supply through captive wafer fabrication or foundry partnerships.
- Inductive:Coil-and-magnet assemblies generate AC voltage proportional to rotational speed without external power. Tier-1 suppliers specify these for emerging market vehicle platforms where electromagnetic robustness outweighs precision requirements.
- Infrared:Optical speed detection through interrupted beam patterns sees minimal automotive deployment due to sealing cost burdens.
- MEMS:Micromechanical accelerometers integrated with wheel speed modules enable combined slip and vibration sensing for advanced chassis control.
Hall Effect technology commands the dominant share of precision-critical applications; MEMS architectures are gaining share fastest in integrated chassis sensing bundles.
End User:
Procurement authority concentrates among tier-1 braking system integrators who bundle wheel speed modules with electromechanical actuator contracts.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH specify sensor subcomponents within integrated braking system packages sold to OEM assembly plants. These contracts eliminate standalone sensor procurement for European and North American vehicle programs.
- OEMs:Direct sensor specification persists among premium German and United States manufacturers who retain design authority over wheel-end electronics architectures.
- Aftermarket Providers:Independent distributors serve vehicle parc replacement demand through catalog-matched passive sensor units.
- Vehicle Assemblers:Contract manufacturers in China and India source pre-integrated axle modules from tier-1 suppliers under PLI scheme incentives.
Tier-1 suppliers capture the dominant procurement volume; aftermarket channels are climbing the fastest as vehicle parc age extends replacement cycles.
Installation:
Brake-by-wire electrification compresses architecture decisions between distributed axle-mounted intelligence and centralized domain controller migration.
- Integrated Systems:Combined wheel speed, bearing condition, and brake temperature sensing modules reduce assembly complexity at the axle. German OEMs specify these units for next-generation electromechanical brake platforms.
- Front Axle:Dual-sensor configurations support ABS and traction control priority circuits with higher pulse resolution requirements.
- Rear Axle:Single-sensor or paired installations serve stability control and odometer calibration with relaxed precision tolerances.
- Standalone Units:Discrete sensor replacements persist in aftermarket channels and legacy vehicle architectures without integrated braking bundles.
Integrated systems are gaining share fastest as OEMs consolidate wheel-end electronics; front axle installations retain the dominant throughput position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in India by a substantial margin, reflecting divergent certification burdens and supply chain maturity. NHTSA mandates in the United States and ECE R13 harmonization across Europe create tiered regulatory entry costs that reshape competitive positioning by geography.
United States
NHTSA electronic stability control mandates and brake-by-wire electrification programs drive precision sensor demand from Detroit-based OEMs. Federal Motor Vehicle Safety Standard 126 governs ESC performance thresholds that cascade into supplier qualification requirements. Michigan and Ohio industrial corridors concentrate tier-1 braking system integration facilities serving domestic vehicle assembly.
Germany
Premium OEM specification of fully encapsulated Hall modules for brake-by-wire platforms sustains above-average unit pricing. KBA type approval procedures under ECE R13 harmonization streamline certification pathways for integrated axle-mounted sensor bundles. Baden-Württemberg and Bavaria host captive wafer fabrication and sensor module assembly operations for Continental AG and Robert Bosch GmbH.
China
Domestic battery-electric vehicle platforms accelerate procurement of integrated axle-mounted sensor modules from local tier-1 suppliers. MIIT new energy vehicle mandates and GB standards for braking performance create dual compliance frameworks for Hall Effect architectures. Yangtze River Delta manufacturing clusters concentrate rare-earth magnet processing and Hall IC packaging capacity.
India
PLI scheme incentives for automotive electronics manufacturing attract sensor module assembly investments serving domestic OEM demand and export markets. Automotive Industry Standard 145 governs ABS performance requirements that propagate into wheel speed sensor specifications. Tamil Nadu and Maharashtra vehicle assembly corridors integrate tier-1 braking system suppliers under localization mandates.
Japan
Precision chassis control systems for hybrid and electric platforms sustain demand for MEMS-integrated wheel speed sensing architectures. METI carbon neutrality roadmaps accelerate brake-by-wire development programs requiring sealed sensor packages. Aichi Prefecture and Kanto industrial belts concentrate Denso Corporation and Hitachi Metals sensor design and manufacturing operations.
Automotive Wheel Speed Sensor Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with Hall Effect specialists commanding premium pricing while inductive sensor fabricators compete on volume scale. The vendor base stratifies across three tiers: integrated braking system bundlers, discrete sensor specialists, and captive semiconductor producers. Scale-driven consolidation among tier-1 suppliers compresses standalone procurement channels. Dominant competitive moves include backward integration into wafer fabrication and strategic bundling of wheel-end electronics with electromechanical brake actuators.
Among European integrated system providers, Robert Bosch GmbH and Continental AG exemplify the bundler archetype that now specifies wheel speed modules as subcomponents of braking contracts rather than standalone purchases. Melexis NV occupies a specialist position within the semiconductor tier, supplying Hall ICs to tier-1 integrators without direct OEM relationships. These three entities represent distinct competitive positions: captive vertical integration, system-level bundling, and component-focused supply.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| NXP Semiconductors |
| Robert Bosch GmbH |
| TE Connectivity |
| Hitachi Metals, Ltd. |
| Continental AG |
| Hella GmbH & Co. KGaA |
| Melexis NV |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Twelve-to-sixteen week lead times for automotive-grade Hall ICs concentrate pricing power among foundry operators in Taiwan and South Korea, while tier-1 braking integrators compress supplier margins through bundled procurement contracts. This inventory-to-pricing feedback loop tightens when rare-earth magnet volatility in Asian processing facilities coincides with NHTSA-mandated precision upgrades.
Pricing Analysis
Configured-to-order pricing for sealed Hall Effect modules commands a 40-60% premium over catalog inductive sensors, with three-tier pricing structure across premium, standard, and economy levels anchored by ISO 26262 ASIL certification grades. Price differentiation stems from wafer fabrication source—captive versus foundry—and volume scale commitments in multi-year braking system contracts. Pricing pressure intensifies in economy vehicle segments as Chinese domestic OEMs specify cost-optimized passive architectures. Tier-1 braking integrators exhibit lowest price sensitivity due to bundled actuator-sensor procurement, while aftermarket distributors face highest sensitivity from price-transparent catalog competition.
Supply Chain Analysis
Just-in-time inventory strategies dominate tier-1 braking module assembly, though strategic stockpiling of rare-earth magnets persists among Hall Effect sensor fabricators exposed to neodymium price swings. Geographic supply concentration centers on Taiwan and South Korea for wafer fabrication, China for rare-earth magnet processing, and Germany for precision module assembly. Raw material dependencies span semiconductor-grade silicon wafers, neodymium-iron-boron magnet alloys, and automotive-grade epoxy encapsulants. Single-source vulnerability concentrates in analog foundry capacity for automotive Hall ICs. Distribution runs through tier-1 braking system integrators who bundle wheel speed modules with electromechanical actuator contracts rather than standalone channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward tier-1 braking system integrators as Continental AG and Robert Bosch GmbH consolidate procurement decisions into bundled sensor-actuator contracts, marginalizing standalone sensor vendors.
For Market Incumbents: Consolidate backward integration into wafer fabrication or captive magnet sourcing to defend margin position against rare-earth price volatility and foundry capacity constraints. Prioritize ISO 26262 ASIL-D certification investments to maintain tier-1 braking contract eligibility as functional safety requirements tighten. Lock in multi-year supply agreements with Yangtze River Delta magnet processors before PLI scheme incentives attract competing capacity. For New Entrants and Emerging Players: Differentiate on MEMS-integrated wheel speed architectures for chassis control bundles, where incumbent Hall Effect specialists lack combined slip-vibration sensing capability. Target India's PLI-incentivized automotive electronics manufacturing corridor for module assembly serving domestic OEM demand and export markets. Pursue direct OEM relationships with premium German and United States manufacturers who retain wheel-end electronics design authority outside tier-1 braking contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized automotive sensor divisions lacking scale to compete in bundled procurement environments. Long-term viability hinges on positioning within brake-by-wire electrification programs requiring sealed, vibration-immune sensor packages. Monitor NHTSA rulemaking on autonomous emergency braking thresholds as the signal to watch for precision upgrade inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Fabrication | Robert Bosch GmbH sustains cost advantages through in-house Hall IC production for ESC-compliant modules. |
| Brake-by-Wire Sensor-Actuator Integration | Continental AG simplifies wheel-end architectures by embedding speed sensing within electromechanical brake platforms. |
| PLI Scheme Manufacturing Localization | Tamil Nadu assembly investments reduce import dependency for Indian OEMs under Automotive Industry Standard 145 mandates. |
| MEMS-Integrated Chassis Sensing Bundles | Denso Corporation combines wheel speed with vibration detection for hybrid platform precision control. |
| Rare-Earth Magnet Supply Security | Melexis NV diversifies magnet sourcing beyond Yangtze River Delta concentration to mitigate neodymium price volatility. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and SEC filings from tier-1 braking suppliers preceded structured interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and Hall IC design specialists. Primary fieldwork combined with secondary validation from NHTSA rulemaking dockets, ECE R13 harmonization protocols, and MIIT new energy vehicle mandates. Bottom-up sensor unit demand models triangulated against top-down braking system market estimates.
Variance decomposition across the projection horizon isolates volume drivers—vehicle production by propulsion architecture, content per vehicle for ESC compliance, and OEM tier penetration—from price drivers including rare-earth commodity cycles and foundry utilization rates. Segmentation dimensions span active versus passive sensor architectures, Hall Effect versus inductive versus MEMS technologies, and integrated versus standalone installation formats. CAGRs derive from slope-intercept modeling of historical penetration curves against regulatory mandate timelines, with brake-by-wire adoption rates and PLI scheme capacity buildouts as automotive-specific forecast inputs.
Material uncertainties—neodymium price volatility, Taiwan foundry disruption, and NHTSA autonomous braking rulemaking acceleration—sit outside the modeled envelope. Forecasts reflect assumptions of continued EMA harmonization progress and stable tier-1 braking integrator market structure. Revision becomes warranted when brake-by-wire platform deployment crosses 25% of premium vehicle production or when rare-earth magnet prices sustain 40% elevation above trailing averages.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
China Forklift Battery Market