
 Portable Truck Access System Market | 2026-2036
Portable Truck Access System Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Truck Access System Market Analytics
North American manufacturing capacity for industrial access equipment is reshaping supplier economics across the portable truck access system value chain. SafeRack leverages its Gulf Coast fabrication footprint to dominate chemical and energy sector contracts. Capital Safety sustains R&D intensity in fall-arrest integration for mobile ramp architectures. Altec competes through aerial work platform technology transfer into truck-mounted access systems.
Portable truck access systems comprise mobile ramps, fixed ramps, modular platforms, and safety barriers engineered from aluminum, steel, composite, or plastic materials with load ratings typically spanning 8,000 to 40,000 pounds for commercial vehicle servicing. These systems enable safe personnel and equipment transfer between ground level and truck beds or railcars in logistics yards, construction sites, and warehousing facilities. Aluminum mobile ramps lead product type demand due to weight advantages and corrosion resistance in outdoor deployment. Heavy duty size configurations capture premium margin pools where mining and construction operators specify reinforced deck structures for continuous cycle operations. Composite materials represent the fastest-growing material segment as transport firms seek reduced manual handling weights without sacrificing structural capacity.
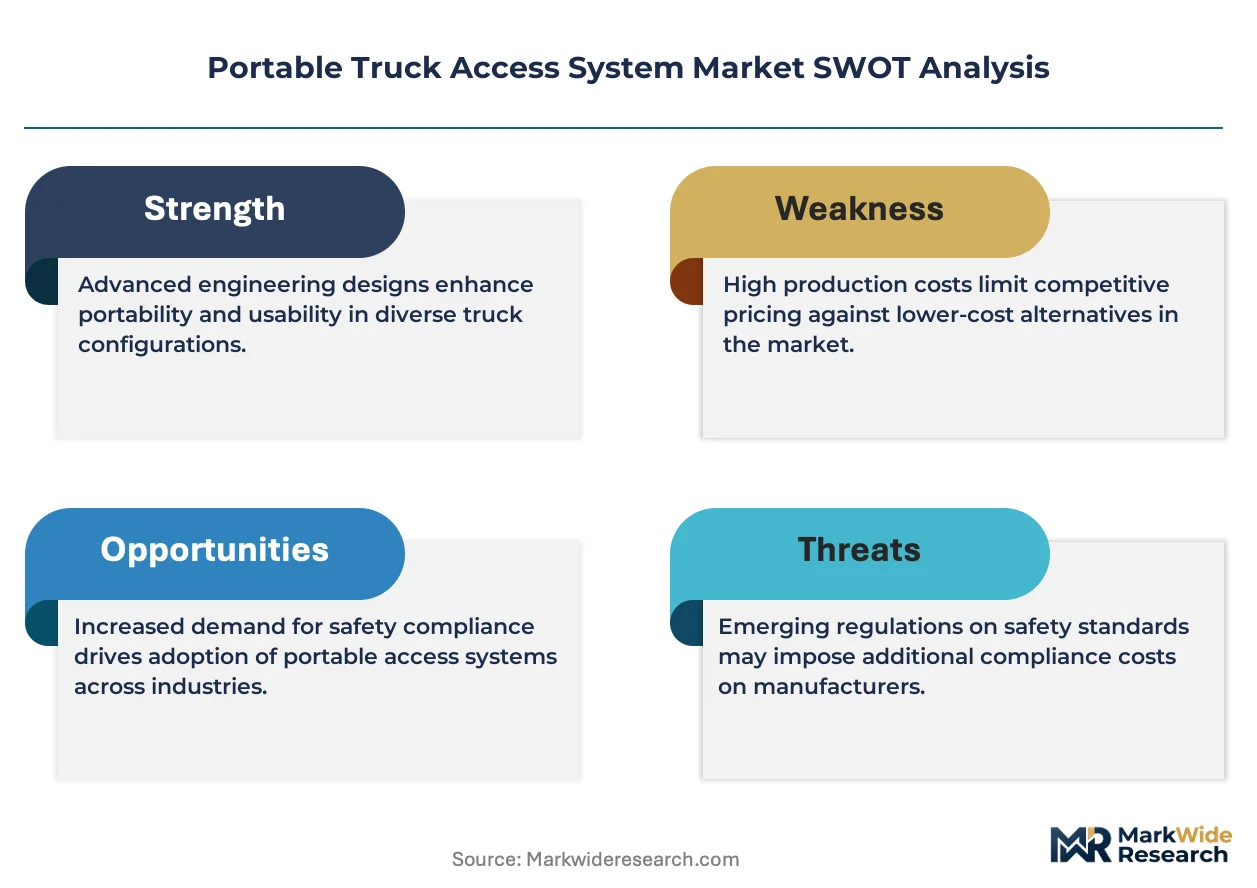
OSHA fall protection standards and EPA spill containment regulations directly shape product design requirements for portable truck access systems deployed in United States industrial environments. The American National Standards Institute publishes load testing and guardrail height specifications that manufacturers must certify against for commercial and federal contract eligibility. European Union machinery safety directives through CE marking and the EU Green Deal material sustainability frameworks create parallel compliance architectures for export-oriented suppliers. Stakeholders must monitor evolving state-level warehouse safety enforcement intensity and composite material recycling mandates to anticipate specification shifts in procurement cycles.
Market Dynamics
OSHA fall protection mandates are compressing replacement cycles for mobile ramp systems across United States logistics yards, forcing fleet operators to accelerate capital deployment toward compliant access equipment before enforcement deadlines.
Growth Catalysts
- Warehouse automation:E-commerce fulfillment centers in the United States are retrofitting loading docks with mobile ramp systems to match automated material handling throughput. Last-mile delivery hubs drive specification upgrades for rapid vehicle turnaround.
- Composite material substitution:Transport firms specify glass-reinforced polymer decking to reduce manual handling weights while maintaining 40,000-pound load ratings. Corrosion resistance extends deployment life in coastal and chemical environments.
- OSHA 1910.28:The fall protection standard mandates guardrail systems on all elevated work platforms above four feet, eliminating non-compliant legacy equipment from federal and commercial procurement pools.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot costs fluctuate with energy pricing in smelter regions, compressing fabrication margins for mobile ramp producers during contract bidding cycles.
- Fabrication concentration:Gulf Coast metalworking clusters dominate heavy-duty access equipment production, creating geographic supply risk during hurricane season disruption.
- Fixed ramp substitution:Permanent concrete loading infrastructure at new-build distribution centers displaces portable system demand in greenfield warehouse development.
Strategic Opportunities
- Electric vehicle servicing:Battery-electric truck fleets require insulated access platforms for high-voltage compartment maintenance, opening specification gaps for dielectric composite systems.
- Rental channel expansion:Equipment rental networks are adding mobile ramp categories to construction and event portfolios, reducing capital burden on intermittent-use buyers.
- IRA clean fleet incentives:United States tax credits for zero-emission commercial vehicles accelerate fleet turnover, bundling access equipment replacement into vehicle procurement packages.
Industry Challenges
- Welding certification gaps:Aluminum TIG welding for structural ramp fabrication requires specialized operator credentials that lag demand in regional fabrication labor markets.
- Third-party load testing:ANSI certification timelines extend 8-12 weeks for new product configurations, delaying commercial launch windows for redesigned deck structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Truck Access System Market |
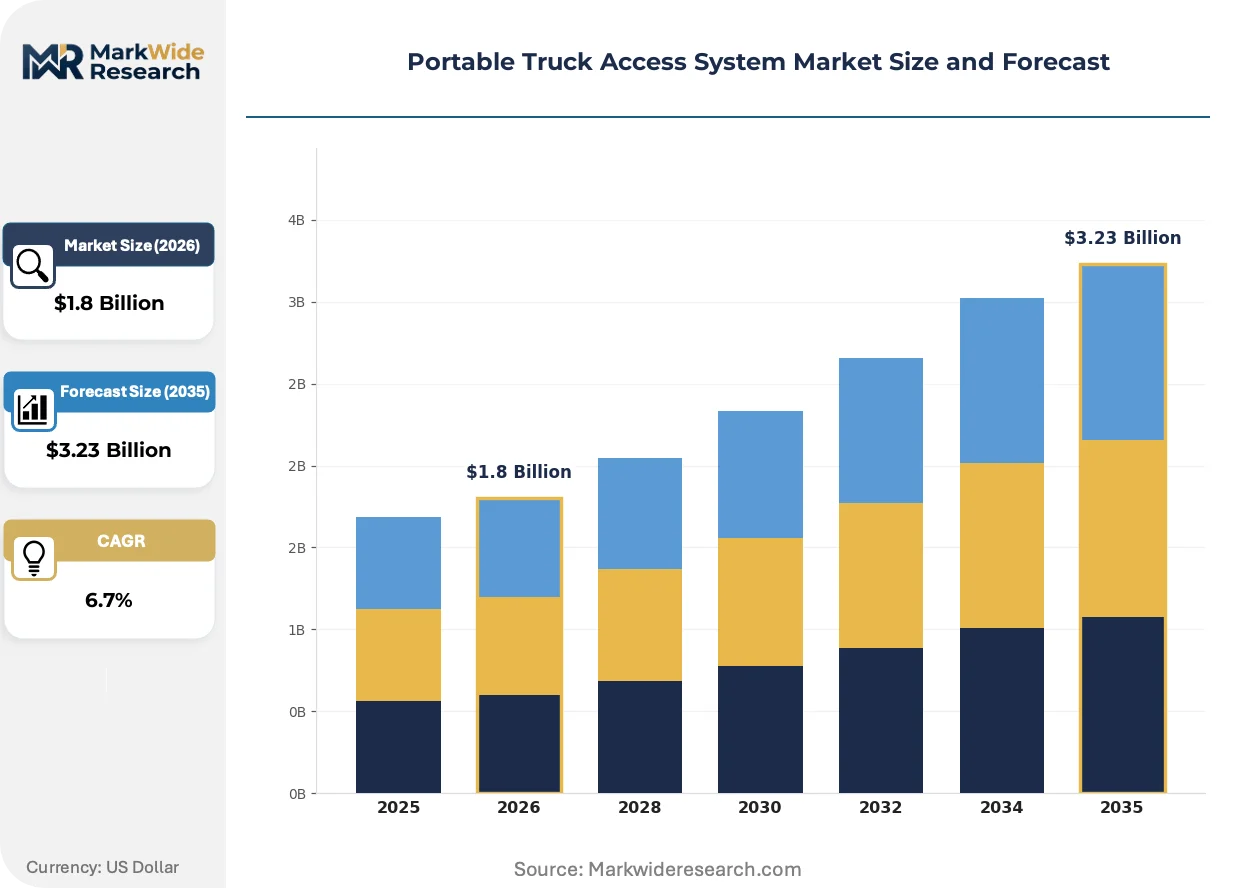
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Ramps, Fixed Ramps, Modular Platforms, Safety Barriers Material: Aluminum, Steel, Composite, Plastic End User: Logistics Companies, Transport Firms, Construction Sites, Warehousing Facilities Size: Standard, Heavy Duty, Lightweight, Customizable |
| Companies Covered | SafeRack, Capital Safety, Altec, Tadano, Aichi, Terex, Bronto Skylift, CTE, Ruthmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Truck Access System Market Evolving Landscape
Sensor integration and predictive maintenance architectures are redefining how fleet operators specify and deploy portable access equipment, shifting procurement criteria from static load ratings to lifecycle performance data.
IoT-enabled load monitoring is digitizing ramp utilization tracking across multi-site logistics operations. Third-party fleet managers embed strain gauges and wireless transmitters into aluminum deck structures to capture real-time weight distribution and cycle counts. This data stream enables predictive replacement scheduling and is digitizing traditional time-based maintenance contracts into condition-triggered service models.
EPA spill containment regulations are tightening material specifications for chemical sector access equipment. Secondary containment decking and sealed joint systems now dominate petrochemical and energy terminal procurement. Gulf Coast operators specify integrated containment trays as standard, compressing demand for basic open-grating designs in hazardous material handling zones.
Rental-first procurement is displacing direct equipment ownership among mid-size construction contractors. United States equipment rental penetration for mobile access systems now exceeds fifty percent in commercial building segments. This channel shift compresses manufacturer margin structures while expanding volume through fleet refresh cycles managed by national rental networks.
Portable Truck Access System Market Segmentation
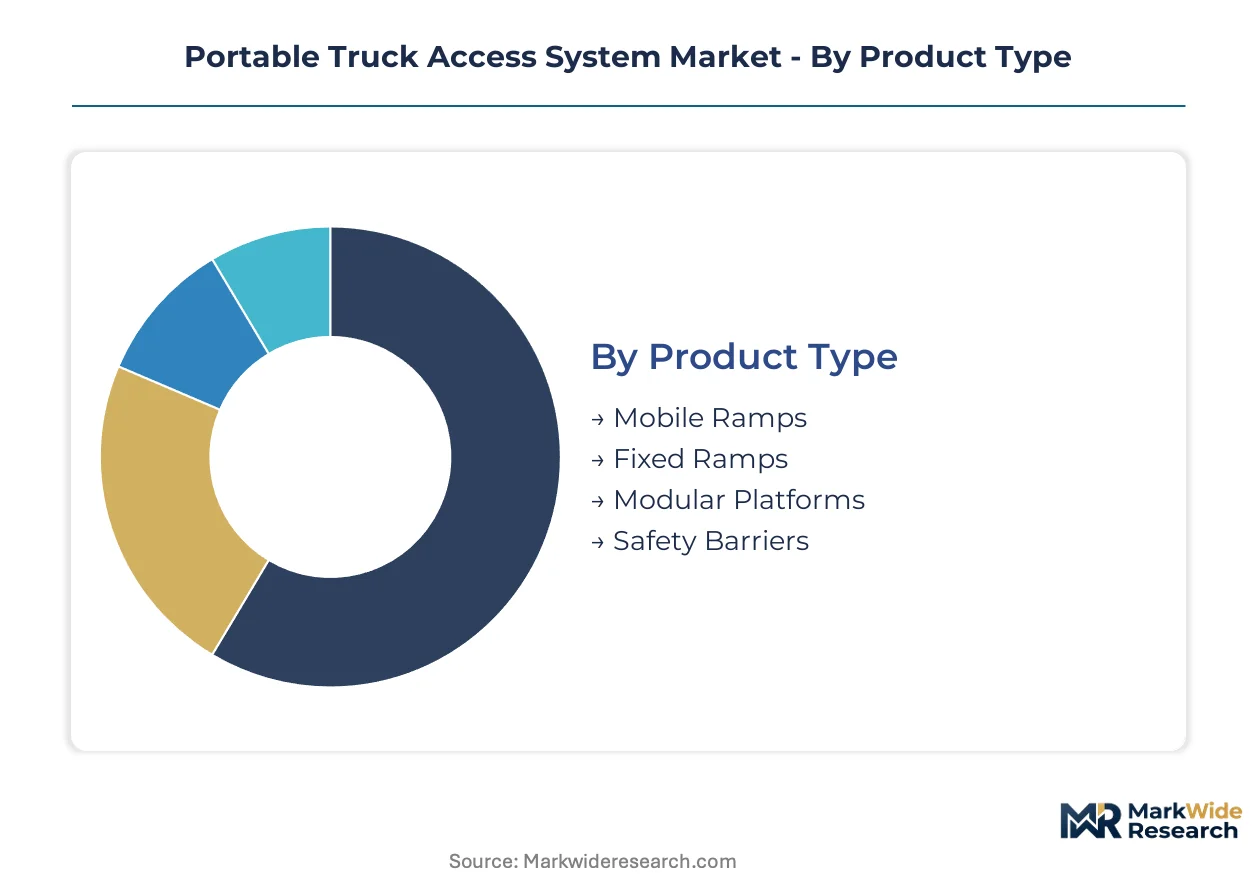
Portable truck access systems fragment across four distinct dimensions that reshape service contract structures and replacement cycle timing. Product architecture and material composition determine field maintenance intensity, while end-user verticals and size specifications dictate capital deployment patterns and rental penetration rates.
Product Type:
After-sales-service intensity varies sharply across product architectures, with mobile ramp systems requiring quarterly inspection protocols and modular platforms demanding annual recertification cycles.
- Mobile Ramps:Aluminum-framed portable units with wheeled bases enable rapid repositioning across loading yards. Logistics operators in the United States specify these for e-commerce fulfillment centers where vehicle turnaround compression demands flexible dock configurations.
- Fixed Ramps:Permanent steel installations bolted to concrete foundations serve dedicated loading positions. Construction sites with stable long-term material handling requirements favor fixed installations for reduced ongoing mobility maintenance.
- Modular Platforms:Interlocking deck sections assemble into customized access configurations. Warehousing facilities specify these for irregular vehicle geometries and non-standard bed heights.
- Safety Barriers:Guardrail and gate systems integrate with ramp structures for OSHA fall protection compliance. Chemical terminals mandate these as standalone retrofits for legacy equipment.
Mobile Ramps holds the largest share; momentum sits with Modular Platforms.
Material:
Cost tier positioning separates premium composite systems from commodity aluminum offerings, with fabrication labor intensity and raw material volatility driving margin divergence across supplier portfolios.
- Aluminum:Lightweight alloy construction delivers corrosion resistance and manual handling efficiency. Transport firms specify aluminum mobile ramps for last-mile delivery hubs where operator fatigue reduction accelerates throughput cycles.
- Steel:Reinforced structural grade supports extreme load ratings for mining and heavy construction applications. High material density limits deployment to fixed installations with mechanical lifting assistance.
- Composite:Glass-reinforced polymer decking achieves dielectric insulation for electric vehicle servicing. Battery-electric truck fleets specify these for high-voltage compartment access safety.
- Plastic:Molded polymer components serve lightweight temporary access needs and spill containment applications. Coastal chemical operators deploy these for rapid deployment in corrosive atmospheres.
Aluminum dominates volume; Composite gains share fastest.
End User:
Customer type determines procurement channel selection, with logistics companies favoring direct manufacturer relationships and construction contractors shifting toward rental network intermediaries.
- Logistics Companies:Fleet-scale operators deploy standardized mobile ramp inventories across distributed hub networks. United States parcel carriers drive specification uniformity for maintenance parts commonality.
- Transport Firms:Trucking operators specify access equipment for driver safety during loading supervision. Long-haul carriers integrate ramps into terminal infrastructure for freight consolidation efficiency.
- Construction Sites:Project-based contractors favor rental procurement for intermittent equipment needs. Commercial building segments show rental penetration exceeding fifty percent for mobile access categories.
- Warehousing Facilities:Third-party logistics providers retrofit aging docks with compliant access systems. OSHA enforcement deadlines accelerate replacement cycles in multi-tenant distribution centers.
Logistics Companies anchor demand; Construction Sites show steepest rental channel shift.
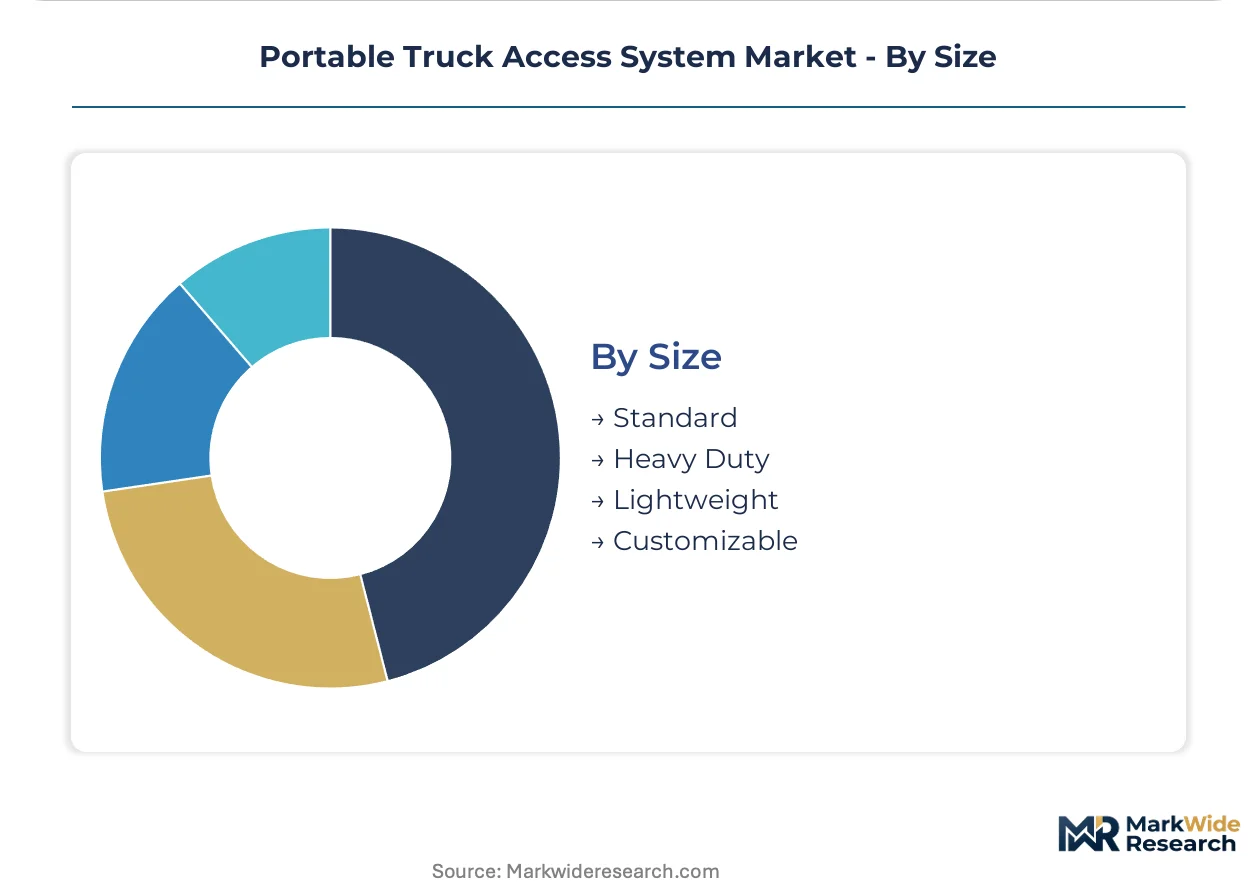
Size:
Volume concentration clusters in standard configurations, while margin pools concentrate in heavy-duty and customizable segments where engineering certification requirements limit supplier competition.
- Standard:8,000 to 20,000-pound load ratings serve commercial vehicle fleets and general logistics applications. Broad supplier availability compresses pricing in this configuration tier.
- Heavy Duty:Reinforced deck structures rated 30,000 to 40,000 pounds support continuous cycle mining operations. Specified by extraction sector operators for equipment loading under extreme static and dynamic loads.
- Lightweight:Reduced-mass designs prioritize manual portability over maximum load capacity. Event logistics and temporary access applications specify these for rapid deployment without mechanical assistance.
- Customizable:Engineered-to-order dimensions and load ratings serve non-standard vehicle geometries. Defense and aerospace ground support equipment procurement drives specification complexity in this tier.
Standard configurations capture volume; Heavy Duty commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States logistics operators prioritize mobile aluminum ramps for rapid dock reconfiguration, while German chemical terminals specify fixed steel installations with integrated containment. Japanese automotive plants favor lightweight modular platforms for mixed-model production lines.
United States
E-commerce fulfillment centers and last-mile delivery hubs drive specification upgrades for rapid vehicle turnaround. OSHA 1910.28 mandates guardrail systems on elevated platforms above four feet, eliminating non-compliant legacy equipment from federal procurement pools. Gulf Coast fabrication clusters in Texas and Louisiana dominate heavy-duty access equipment production for chemical and energy sector contracts.
Germany
Automotive manufacturing plants and chemical processing facilities anchor demand for precision-engineered access systems. EU machinery safety directives through CE marking and REACH material compliance frameworks shape product certification requirements. Industrial concentration in North Rhine-Westphalia and Bavaria sustains specialized fabrication capacity for modular platform architectures.
China
Construction sector expansion and logistics infrastructure modernization propel mobile ramp deployment across inland distribution networks. GB standards for industrial equipment safety and MIIT manufacturing quality certifications govern domestic market entry. Yangtze River Delta manufacturing bases in Shanghai and Jiangsu province concentrate aluminum fabrication capacity for export-oriented suppliers.
Japan
Automotive assembly plants and precision electronics logistics drive demand for lightweight, high-cycle access equipment. METI industrial safety guidelines and JIS structural standards establish baseline compliance thresholds for domestic procurement. Kanto region manufacturing clusters around Tokyo and Yokohama specialize in composite material integration for electric vehicle servicing platforms.
Canada
Mining operations in Alberta and British Columbia specify heavy-duty steel ramps for equipment loading under extreme static loads. Health Canada occupational safety regulations and provincial fall protection enforcement align with OSHA-equivalent compliance frameworks. Ontario manufacturing corridors near Toronto supply standardized mobile ramp configurations for North American logistics integration.
Portable Truck Access System Market Competitive Landscape
Capability concentration sits with specialized fabrication tiers; scale advantage sits with diversified industrial equipment portfolios. The market structures around three distinct player archetypes: Gulf Coast metalworking specialists with chemical sector relationships, diversified access equipment manufacturers leveraging technology transfer, and regional fabrication shops serving construction rental channels. Dominant competitive moves include strategic partnerships for composite material sourcing and geographic expansion through equipment rental network integration.
Among North American specialists, SafeRack exemplifies the chemical-sector-focused fabrication archetype with its Gulf Coast concentration. Capital Safety occupies a position within fall-protection-integrated system design, representing the safety-engineering tier. Altec anchors the diversified industrial equipment segment, sitting within technology transfer strategies from aerial work platforms into truck-mounted access architectures.
| Leading Market Players |
|---|
| SafeRack |
| Capital Safety |
| Altec |
| Tadano |
| Aichi |
| Terex |
| Bronto Skylift |
| CTE |
| Ruthmann |
| Others |
Value Network & Pricing Analysis
Primary aluminum smelter concentration in the Yangtze River Delta and Gulf Coast fabrication clusters directly determines where margin pools accumulate downstream, with raw material volatility compressing fabrication margins while heavy-duty specification tiers retain pricing power through engineering certification barriers.
Pricing Analysis
Long-term offtake contracts dominate procurement for fleet-scale logistics operators, while spot purchasing serves intermittent construction rental demand. Three-tier pricing structure across premium, standard, and economy levels separates dielectric composite systems for electric vehicle servicing from commodity aluminum mobile ramps. Cost compression in standard aluminum configurations is intensifying because energy-linked ingot price volatility feeds directly into fabrication bids. Logistics companies show least price sensitivity due to OSHA compliance deadlines, while mid-size construction contractors exhibit highest sensitivity through rental channel intermediation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for aluminum alloy inputs and finished mobile ramp assemblies. Manufacturing gravity centers on China for primary aluminum processing, the United States for heavy-duty fabrication, and Germany for precision-engineered modular platforms. Raw material dependencies span primary aluminum ingot, glass-reinforced polymer resin, and structural steel grades. Single-source vulnerability concentrates in specialized TIG welding consumables for aluminum fabrication. Distribution runs through direct manufacturer relationships for fleet operators and national rental networks for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service contracts for inspection, recertification, and predictive maintenance are expanding faster than hardware sales, creating attach-rate opportunities that reshape lifetime customer value calculations for access equipment suppliers.
For Market Incumbents: Build certification moats around ANSI load testing and OSHA fall protection integration to defend against composite material specialists entering from adjacent industrial access markets. Deepen backward integration into aluminum alloy sourcing to offset smelter energy cost volatility. Capture channel control through exclusive rental network partnerships that lock out competing fabrication shops. For New Entrants and Emerging Players: Establish a beachhead in electric vehicle servicing platforms where dielectric composite specifications create specification gaps unaddressed by legacy metal fabricators. Target mid-size warehousing facilities facing OSHA 1910.28 retrofit deadlines with rapid-deployment modular platforms. Pursue go-to-market alignment with equipment rental networks seeking to expand mobile ramp categories. For Investors and Strategic Acquirers: Capital is best deployed toward Gulf Coast fabrication specialists with captive chemical sector relationships and in-house TIG welding certification programs. Long-term viability hinges on service revenue attachment rates exceeding hardware replacement cycles. Watch for inflection when IRA clean fleet incentives accelerate battery-electric truck procurement bundles.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Sourcing Partnership | Secures glass-reinforced polymer supply for dielectric electric vehicle servicing platforms. |
| Predictive Maintenance Platform Launch | Converts IoT-enabled load monitoring data into recurring service contracts with logistics fleets. |
| Rental Network Integration | Expands volume through national equipment rental channels serving construction contractors. |
| OSHA Compliance Certification Investment | Accelerates ANSI testing timelines to capture federal procurement pool eligibility. |
| Geographic Fabrication Footprint Expansion | Reduces hurricane season supply risk through diversification beyond Gulf Coast clusters. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at logistics fulfillment centers, procurement leads at trucking fleet operators, aftermarket service heads at rental networks, and maintenance directors at chemical terminals, then refined through secondary validation against OSHA enforcement databases, ANSI certification registries, SEC filings from diversified industrial equipment manufacturers, customs trade data for aluminum alloy imports, and rental fleet utilization reports, with bottom-up volume modeling triangulated against top-down industry spend analysis.
Demand-supply balance across mobile ramp, fixed ramp, modular platform, and safety barrier architectures anchored the analytical framework over the projection horizon, with segmentation across aluminum, steel, composite, and plastic materials plus logistics, transport, construction, and warehousing end users. CAGRs were derived from replacement cycle timing, fleet expansion rates, and regulatory deadline clustering. Forecast inputs incorporated OSHA enforcement intensity projections and electric vehicle fleet turnover assumptions.
Stress conditions across aluminum price volatility bands, hurricane season fabrication disruption scenarios, and fixed ramp substitution rates at greenfield distribution centers were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory deadline adherence and rental channel penetration trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Transmission Components Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Throttle Cable Market
Vehicle Components
HCV Axles Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
China Automotive Carbon Fiber Composites Market