
 Global Fuel Tank and Delivery System Market | 2026-2036
Global Fuel Tank and Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fuel Tank and Delivery System Market Intelligence
The integration of multi-layer polymer composites for tank construction is reconfiguring design parameters for evaporative emissions control. This shift away from traditional steel tanks addresses stricter environmental mandates and vehicle weight reduction targets. Continental AG leverages its material science expertise in developing these advanced polymer solutions. Magna International Inc. specializes in complete system integration for automotive and industrial clients. DENSO Corporation competes on the precision engineering of its high-pressure electric fuel pumps and injectors.
A fuel tank and delivery system is an engineered assembly designed to securely store volatile fuels and supply them to an engine. These systems often feature multi-layer construction with an ethylene vinyl alcohol (EVOH) barrier to prevent hydrocarbon permeation. The primary purpose is to deliver a consistent fuel flow at a specific pressure. Electric pumps have become the standard in the delivery system technology segment, displacing older mechanical designs. In terms of application, systems for power generation and agricultural machinery represent the fastest-growing areas of demand.
Regulatory frameworks are a primary force shaping component design and material choice. The US EPA's evaporative emissions standards and Europe's REACH regulations on chemical substances directly influence tank material selection. These rules compel manufacturers to use low-permeation plastics and validate system integrity through rigorous testing. System suppliers must decide whether to invest in advanced polymer co-extrusion capabilities or focus on niche metal tank applications for specialized equipment.
Market Dynamics
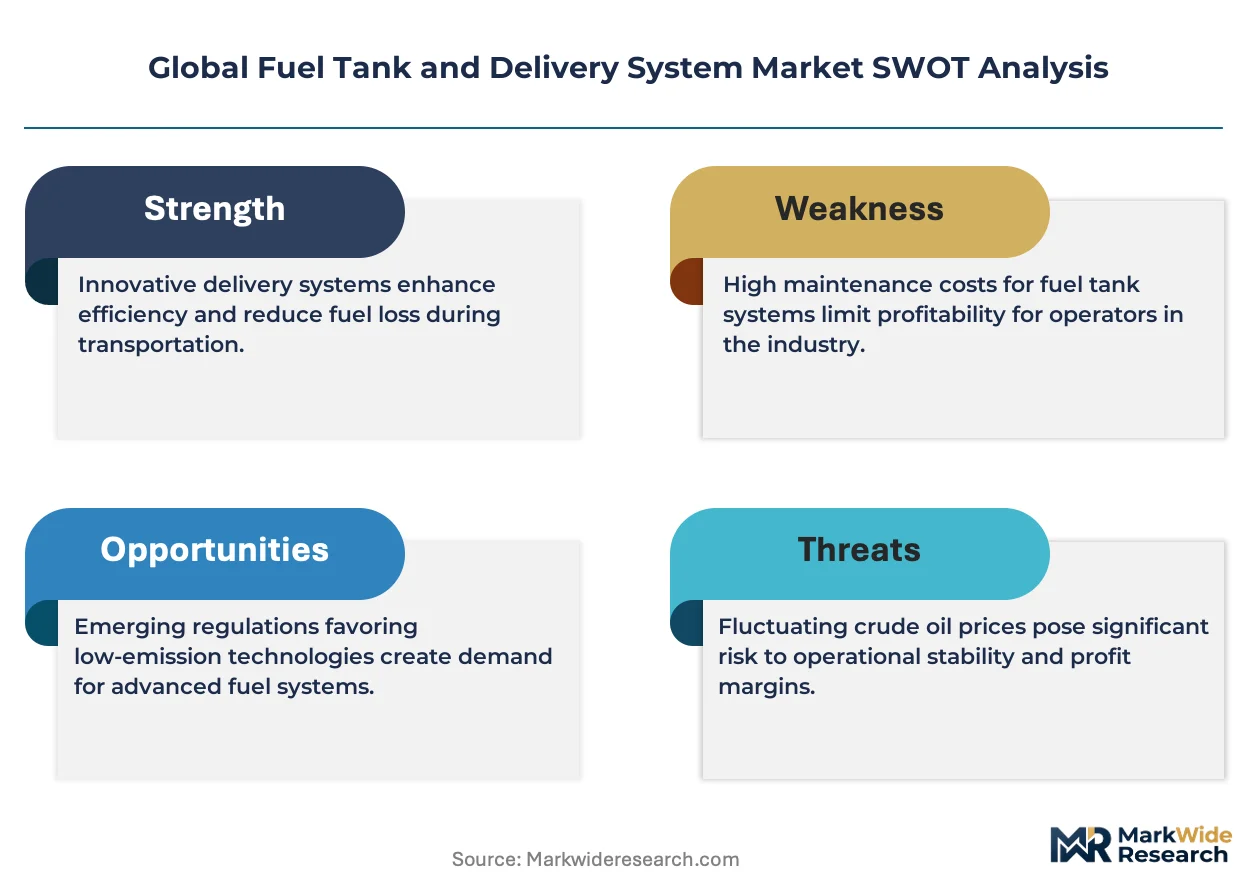
The central tension shaping the fuel tank market is the concurrent push for stringent evaporative emissions control and vehicle weight reduction, forcing a material science-led transition from traditional steel to advanced multi-layer polymer composites.
Growth Catalysts
- Infrastructure Expansion:Infrastructure and industrial projects in developing economies, particularly India, are accelerating demand for construction and agricultural machinery, which require robust fuel systems.
- Advanced Materials Adoption:The use of lightweight composite materials, including polymers with ethylene vinyl alcohol (EVOH) barriers, enables design flexibility and helps OEMs meet fuel efficiency targets.
- Agricultural Modernization:Government-supported initiatives to modernize agriculture in several regions drive the replacement of older equipment with new machinery featuring more efficient and compliant fuel delivery systems.
Market Restraints
- Higher Input Costs:The price of specialized polymers and barrier materials like EVOH is significantly higher than that of conventional steel, creating a cost barrier for adoption in price-sensitive vehicle segments.
- System Integration Complexity:Integrating advanced polymer-based fuel systems with existing vehicle platforms and engine architectures requires significant engineering and validation, potentially delaying model rollouts.
- Stringent Validation Cycles:Compliance with regulations such as the US EPA standards and Europe's REACH framework necessitates lengthy and expensive testing protocols to validate system integrity and material safety.
Strategic Opportunities
- Stationary Power Systems:The expansion of distributed power generation and backup power for data centers creates an opportunity for specialized fuel delivery systems designed for continuous-duty generator sets.
- Smart System Integration:Incorporating advanced sensors for real-time fuel level, pressure, and vapor leak detection into a single module offers a value-added solution for OEMs seeking enhanced diagnostics and safety.
- Non-Road Mobile Machinery:Beyond agriculture, demand for advanced fuel systems is growing in other non-road mobile machinery (NRMM) sectors like mining and forestry, which are also facing new emissions rules.
Industry Challenges
- Capital-Intensive Manufacturing:The acquisition and maintenance of multi-layer co-extrusion blow molding machinery for complex plastic tank production require substantial capital investment, limiting market entry.
- Specialized Engineering Talent:A shortage of engineers with combined expertise in polymer science, fuel chemistry, and emissions control systems creates a bottleneck for product development and innovation.
- Supply Chain Volatility:The supply chain for critical raw materials, including specialized resins and barrier polymers, is concentrated among a few suppliers, creating vulnerability to price fluctuations and disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fuel Tank and Delivery System Market |
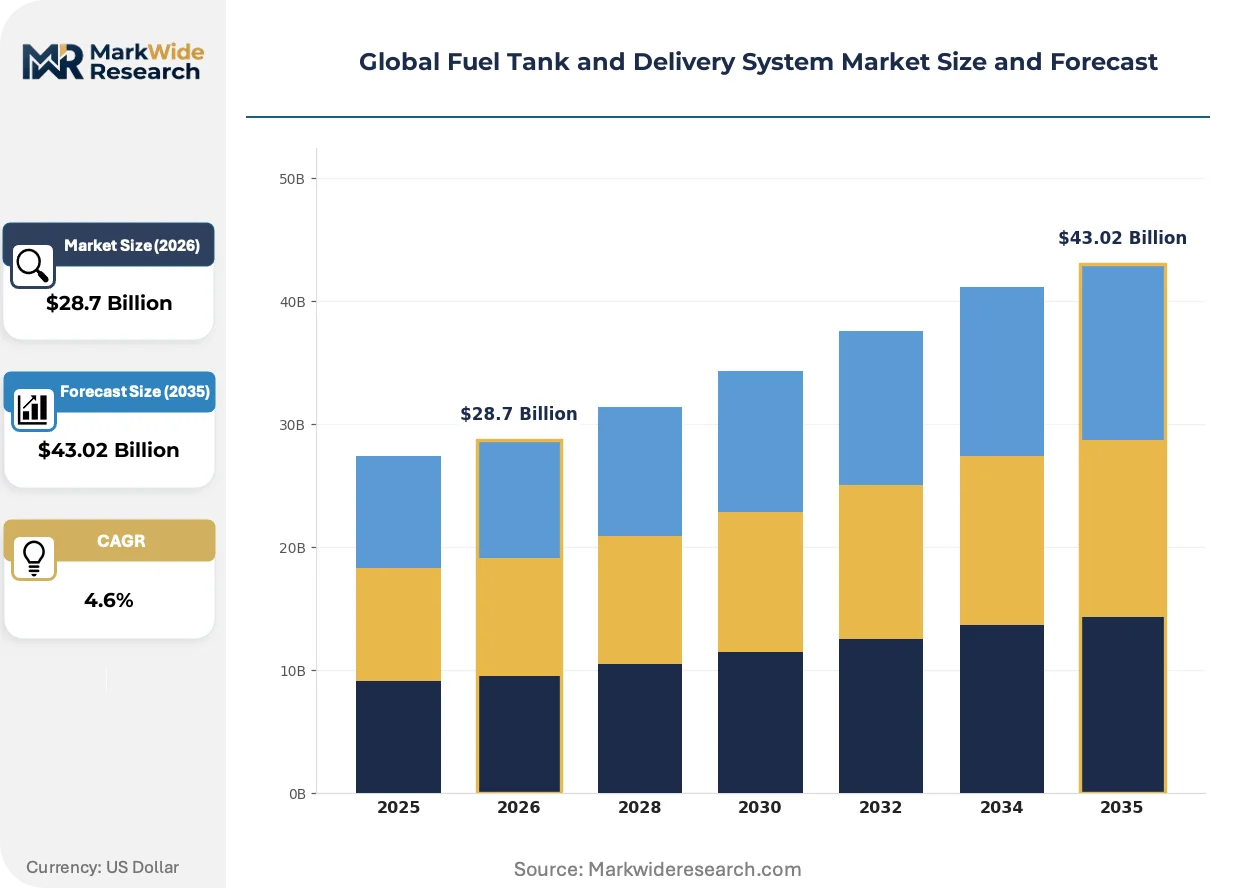
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Tank Type: Aboveground, Underground, Portable, Cryogenic, Modular Delivery System Technology: Mechanical Pumps, Electric Pumps, Gravity Feed, Pressure Feed, Vacuum Feed Application Sector: Construction Equipment, Marine Vessels, Agricultural Machinery, Aviation, Power Generation End User Industry: Oil & Gas Exploration, Mining Operations, Public Transportation, Emergency Services |
| Companies Covered | DENSO Corporation, Robert Bosch GmbH, Continental AG, Magneti Marelli S.p.A, Magna International Inc, TI Automotive, Keihin Corporation, Toyoda Gosei, Delphi Automotive Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fuel Tank and Delivery System Market Strategic Shifts & Innovations
The market's evolution is defined by a move from passive fuel storage to actively managed systems. This shift is driven by the need to control hydrocarbon emissions and integrate seamlessly with complex powertrain electronics, reconfiguring supplier capabilities around material science and systems engineering.
Multi-layer polymer composites serve as the primary material for modern fuel tank construction, offering a lightweight and corrosion-proof alternative to steel. Automotive and agricultural machinery manufacturers are the primary adopters, seeking to reduce vehicle weight and gain greater design freedom for packaging. The technology is migrating from simple single-layer plastic tanks to complex co-extruded structures that incorporate an EVOH barrier layer to meet stringent emissions mandates.
Regulatory frameworks like the US EPA's evaporative emissions standards are a primary force shaping component design. These rules impose strict limits on the amount of hydrocarbon vapor that can escape from a vehicle's fuel system. Consequently, system suppliers must engineer and validate tanks, lines, and connections to ensure low permeation, directly influencing the adoption of multi-layer plastics over traditional metal in the automotive sector.
A preference for integrated system modules is altering OEM purchasing behavior. Instead of sourcing individual components like tanks, pumps, and fuel lines separately, vehicle manufacturers now favor pre-assembled and pre-validated fuel delivery modules from a single supplier. This trend is most pronounced in the high-volume automotive segments of North America and Europe, as it streamlines assembly processes and transfers integration risk to the supplier.
Global Fuel Tank and Delivery System Market Segmentation
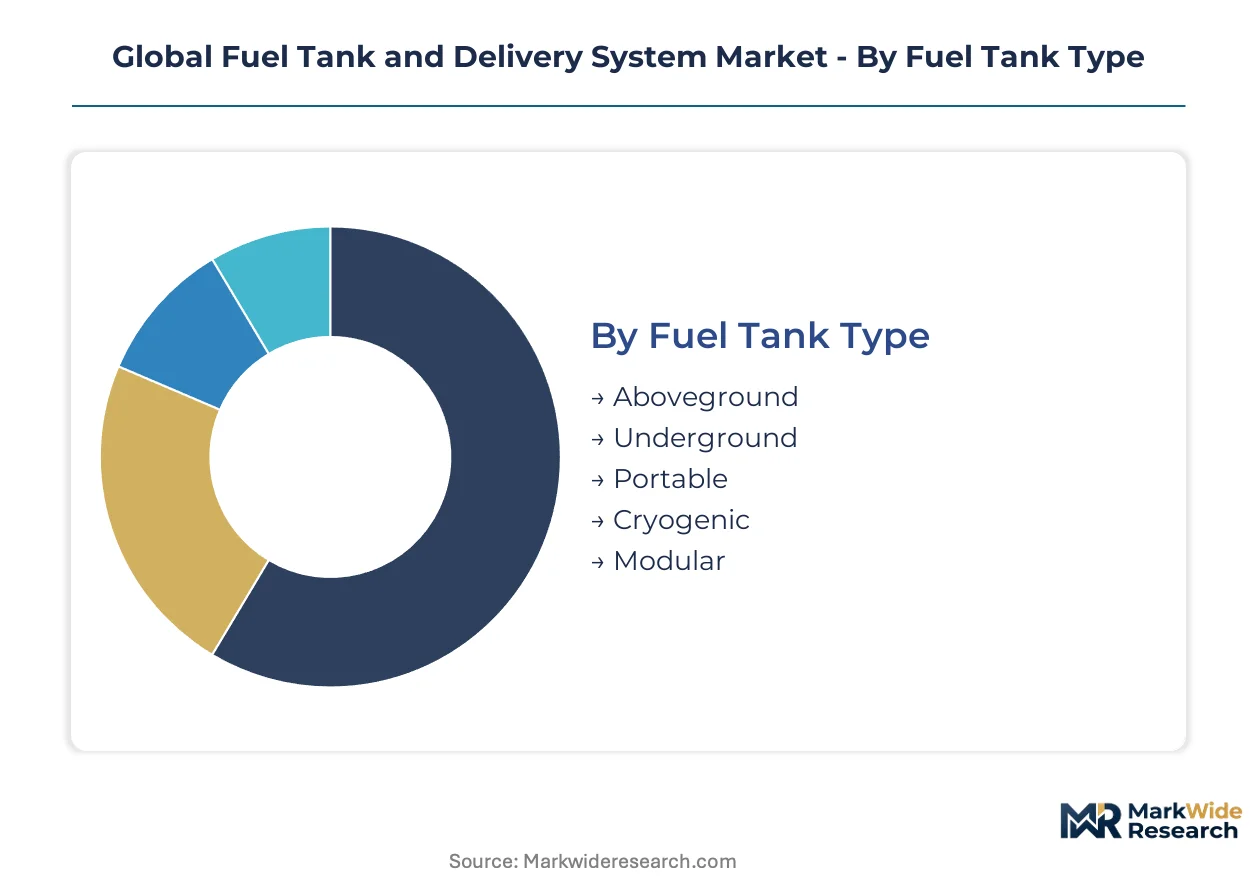
The Fuel Tank and Delivery System market segments address the varied operational demands and technological requirements across diverse industries. Understanding these distinctions helps manufacturers tailor product development and strategic market entry. Each segment represents a unique set of design considerations, material specifications, and regulatory compliance needs for fuel storage and supply.
Fuel Tank Type:
The spectrum of fuel tank types addresses diverse operational environments and storage requirements, from stationary industrial applications to mobile emergency support.
- Aboveground:These tanks store fuel on the surface, commonly used for industrial facilities, power generation units, and large agricultural operations in regions like India. Design emphasizes accessibility for maintenance and robust construction against environmental exposure.
- Modular:Comprising standardized, often interconnected units, modular tanks offer flexible capacity expansion and easier transportability. Demand for these systems is growing in distributed power generation and temporary construction sites across Europe.
- Underground:Designed for long-term, concealed storage, underground tanks minimize land footprint and reduce fire risk. Strict environmental regulations, such as those from the US EPA, govern their installation and leak detection.
- Portable:Smaller, mobile fuel containers designed for easy transport and use with compact equipment.
- Cryogenic:Specialized tanks engineered to store liquefied gases at extremely low temperatures, primarily used in aerospace and advanced industrial applications.
Established volume favors Aboveground tanks; emerging adoption favors Modular designs.
Delivery System Technology:
Delivery system technologies range from cost-effective passive methods to advanced, precision-engineered solutions demanding higher investment.
- Electric Pumps:These systems use electric motors to deliver fuel consistently and precisely, enabling advanced engine control and emissions management. They are now standard in modern automotive and agricultural machinery, displacing older mechanical designs.
- Pressure Feed:Fuel is delivered under constant pressure to the engine, ensuring reliable flow even under varying load conditions. This technology is critical for heavy-duty construction equipment and marine vessels requiring consistent power output.
- Mechanical Pumps:Driven directly by the engine, mechanical pumps offer a simpler and more robust solution for many industrial engines.
- Gravity Feed:Relies on gravity to transfer fuel from a higher tank to a lower engine, suitable for simple, low-pressure applications where cost is a primary concern.
- Vacuum Feed:Utilizes engine vacuum to draw fuel, typically found in smaller engines or specific industrial setups where a pump might be impractical.
Technological advancement continues to favor electric pumps, while gravity feed systems retain their utility in simpler applications.
Application Sector:
Application sectors differentiate by the volume and intensity of fuel system usage, influencing design and material durability.
- Agricultural Machinery:Fuel systems for agricultural equipment endure harsh operating conditions and require robust construction with enhanced filtration. Modernization initiatives in countries like Brazil and China are driving demand for advanced, efficient systems.
- Power Generation:Stationary and mobile power generation units require reliable fuel delivery for continuous operation, often using larger tanks and high-capacity pumps. The expansion of data centers and backup power solutions globally fuels this segment.
- Construction Equipment:Heavy construction machinery demands durable fuel systems capable of operating in dusty, rugged environments.
- Marine Vessels:Fuel systems for marine applications must resist corrosion and comply with strict maritime safety regulations, such as those from the International Maritime Organization.
- Aviation:Highly specialized and regulated fuel systems for aircraft prioritize lightweight materials, safety, and performance under extreme conditions.
Infrastructure expansion fuels demand in construction equipment, while modernization efforts boost agricultural machinery.
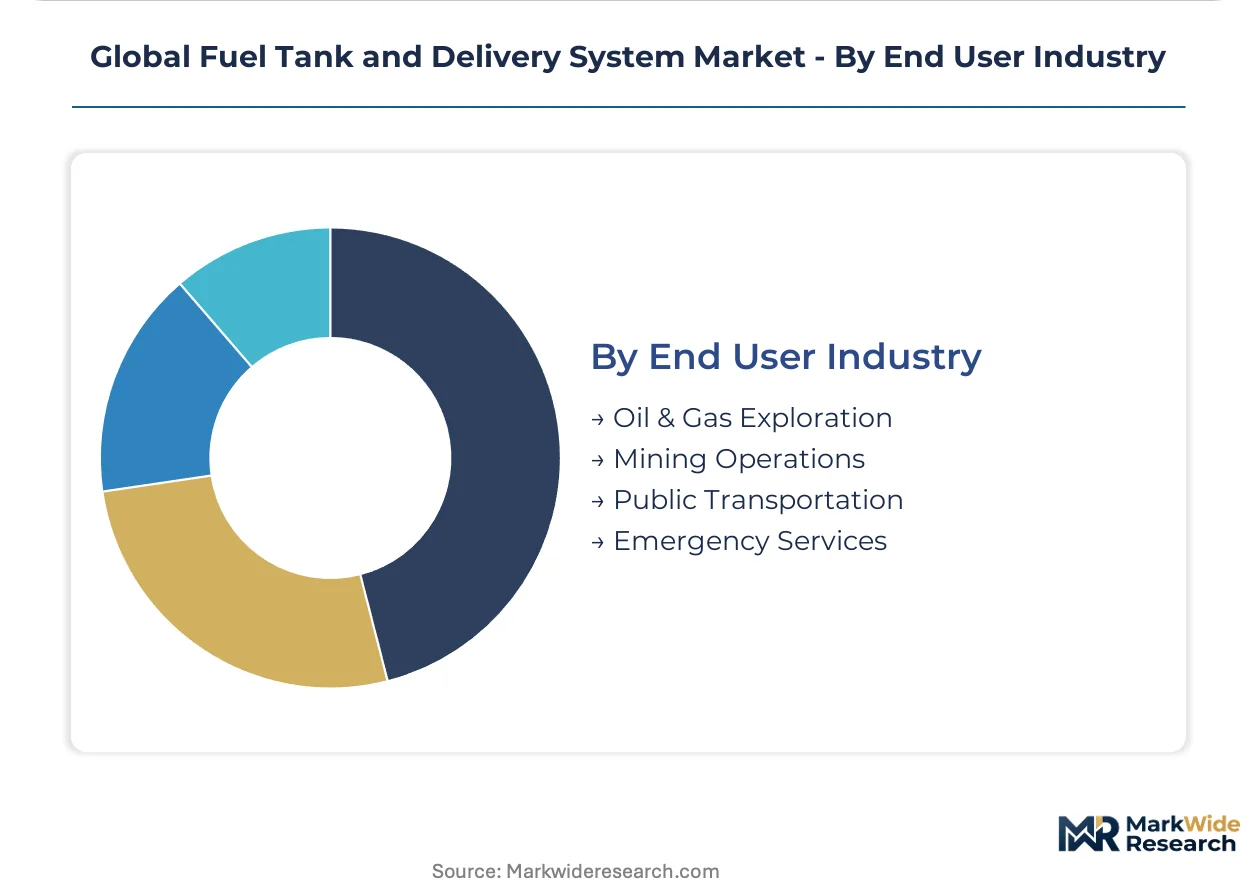
End User Industry:
End user industries categorize fuel system needs based on operational criticality, environmental exposure, and regulatory compliance demands.
- Mining Operations:This industry requires extremely rugged and high-capacity fuel systems for heavy-duty earth-moving equipment, often operating in remote and challenging environments. New emissions rules for non-road mobile machinery impact this sector.
- Oil & Gas Exploration:Fuel systems in this sector support drilling rigs, transport vehicles, and power units in remote and hazardous locations. Reliability and safety standards are paramount, often exceeding general industrial requirements.
- Public Transportation:Fuel systems for buses, trains, and other public transport vehicles emphasize efficiency, low emissions, and long operational life.
- Emergency Services:Critical applications for ambulances, fire trucks, and rescue vehicles demand highly reliable fuel delivery systems for immediate and uninterrupted operation.
Harsh operational environments in mining operations drive demand for rugged systems, whereas public transportation prioritizes reliability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in the global market for fuel tank and delivery systems varies significantly by region. Developing economies like India and China are seeing substantial demand from infrastructure and agricultural sectors. Meanwhile, mature markets in Europe and North America prioritize advanced emissions control and lightweight materials for automotive applications.
India
Infrastructure and industrial projects in India are accelerating demand for robust fuel systems in construction and agricultural machinery. The country's PLI scheme for automotive components encourages domestic manufacturing and technological upgrades. Major industrial hubs like Pune and Chennai are seeing increased production of heavy equipment and associated fuel system components.
United States
The United States market is largely driven by stringent environmental regulations, particularly the US EPA's evaporative emissions standards. This compels manufacturers to adopt advanced multi-layer polymer composites for fuel tanks. Automotive production centers in Michigan and Ohio are focal points for integrating these low-permeation systems into new vehicle platforms.
Germany
Germany's automotive and industrial machinery sectors demand high-precision fuel delivery systems and advanced tank materials. Europe's REACH regulations directly influence material selection for polymer composites and EVOH barriers. The Stuttgart and Munich regions, with their strong engineering base, are centers for innovation in fuel system design and manufacturing.
China
Agricultural modernization initiatives and rapid infrastructure development in China are boosting demand for efficient fuel delivery systems. The country's dual carbon goals are driving the adoption of more fuel-efficient and emissions-compliant machinery. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are expanding production of fuel systems for domestic and export markets.
Brazil
Brazil's agricultural sector modernization, supported by government programs, creates significant demand for advanced fuel systems in farm machinery. Environmental regulations from IBAMA influence the design of robust and emissions-compliant fuel tanks for off-highway vehicles. The São Paulo and Minas Gerais states are key regions for agricultural equipment manufacturing and fuel system suppliers.
Global Fuel Tank and Delivery System Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for fuel tank and delivery systems. The market is moderately concentrated, with larger, diversified industrial conglomerates alongside specialized component manufacturers. Two primary strategic archetypes emerge: integrated system providers and niche material science innovators. Dominant competitive moves include strategic partnerships for technology co-development and targeted geographic expansion into high-growth developing markets.
Specialists in complete system integration, such as Magna International Inc., offer comprehensive solutions for automotive and industrial clients, streamlining OEM assembly processes. Continental AG leverages its extensive material science expertise, particularly in advanced polymer solutions for evaporative emissions control. DENSO Corporation occupies a position as a precision engineering leader, anchoring its offering in high-pressure electric fuel pumps and injectors for advanced engine architectures.
| Leading Market Players |
|---|
| DENSO Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Magneti Marelli S.p.A |
| Magna International Inc |
| TI Automotive |
| Keihin Corporation |
| Toyoda Gosei |
| Delphi Automotive Plc |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta's specialized co-extrusion blow molding capacity for polymer fuel tanks directly influences global pricing dynamics for advanced fuel delivery systems. This concentration of manufacturing capability shapes competitive pricing across end-user industries.
Pricing Analysis
Cost-plus contract structures, often indexed to polymer resin prices and energy costs, govern the pricing of advanced fuel tank systems. Price differentiation stems from the customization level required for OEM integration and material compliance with specific regulations like US EPA standards. Pricing softness reflects higher input costs for specialized polymers and EVOH barrier materials. Agricultural machinery OEMs exhibit high price sensitivity, while aviation and mining applications prioritize performance and reliability.
Supply Chain Analysis
Supply chain volatility, particularly concerning specialized resins and barrier polymers, dominates the procurement landscape for fuel tank manufacturers. Geographic concentration centers on China, Germany, and Japan for advanced component production and material sourcing. Key dependencies include EVOH barrier materials and high-precision electric pump components. Distribution runs primarily through direct supply agreements with original equipment manufacturers across automotive and industrial sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuel tank and delivery system market is in an early-cycle expansion phase, driven by the accelerating adoption of multi-layer polymer composites for emissions control. Infrastructure and agricultural modernization initiatives provide significant tailwinds.
For Market Incumbents: Harden core competencies in material science and systems integration to counter emerging threats from new material technologies and localized manufacturing initiatives. Incumbents must invest in next-generation polymer co-extrusion capabilities and secure long-term supply agreements for critical barrier materials like EVOH. Deepening R&D into sustainable polymer solutions offers a strategic lever against future regulatory shifts. Expanding localized production capacity in high-growth developing economies can mitigate supply chain risks.
For New Entrants and Emerging Players: Establish a beachhead in niche applications within the non-road mobile machinery sector, leveraging agile design and rapid prototyping capabilities. Focus on underserved segments like modular tank systems for distributed power generation and specialized equipment in mining operations. Offering integrated smart systems with advanced diagnostics and vapor leak detection provides a compelling value proposition. Target geographies with less entrenched incumbents and rapidly expanding infrastructure projects, such as India.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven technology upgrade play because environmental mandates continue to compel material and system innovation. Investors should seek mid-cap specialists possessing strong intellectual property in polymer science or precision engineering for fuel pumps and injectors. Acquisition targets with established OEM relationships and validated low-permeation solutions are attractive. The signal to watch is increased investment by major OEMs in platform redesigns specifically to integrate advanced fuel system architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Polymer Co-extrusion | Enhances compliance with stricter evaporative emissions standards like US EPA regulations. |
| Develop Integrated Smart Fuel Modules | Offers OEMs enhanced diagnostics and safety features, simplifying vehicle assembly. |
| Expand Manufacturing in Developing Economies | Addresses growing demand for robust systems in India's agricultural and construction sectors. |
| Strategic Partnerships for Sensor Technology | Integrates real-time monitoring capabilities for fuel level, pressure, and leak detection. |
| Certify Solutions for Non-Road Mobile Machinery | Captures demand from mining and forestry sectors facing new emissions rules. |
Research Approach
Operator-level perspectives from fuel system engineers, OEM procurement leads, material science researchers, and regulatory compliance officers anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary research, including US EPA reports, Europe's REACH documentation, and automotive industry production databases. Bottom-up and top-down approaches validated market sizing and segmentation across all regions.
Scenario-bracketing around optimistic and conservative adoption rates for advanced polymer composites informed the market projections across the analysis window. The analytical framework modeled segmentation dimensions including fuel tank type, delivery system technology, application sector, and end user industry, alongside material composition. Compound annual growth rates were derived from historical growth patterns and projected technological shifts. Key forecast inputs included regulatory enforcement timelines and specialized polymer raw material price forecasts.
Stress conditions across raw material price volatility and regulatory implementation speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, but unforeseen global supply chain disruptions or rapid shifts in energy policy could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Exhaust Manifolds and Downpipes Market