
 2 Wheeler Fuel Tank Market | 2026-2036
2 Wheeler Fuel Tank Market Size, Share, and Industry Trends Forecast 2026-2036
2 Wheeler Fuel Tank Market Outlook
The divergence between premium metal fuel tanks and commodity-grade plastic alternatives is realigning procurement strategies across motorcycle OEMs. Honda Motor Co., Ltd. leverages its in-house stamping capacity to sustain alloy tank output for performance models. Yamaha Motor Co., Ltd. anchors Southeast Asian supply through integrated plastic injection molding lines. Bajaj Auto competes aggressively on cost-optimized steel tank volumes for domestic commuter segments.
A two-wheeler fuel tank is a sealed reservoir, typically fabricated from stamped steel, blow-molded HDPE, or spun aluminum, designed to store gasoline or ethanol-blended fuels while meeting permeation and crash-resistance standards; its primary purpose is to secure fuel supply to the carburetor or fuel injection system across varying vibration and temperature profiles. Plastic tanks now lead unit volume in mass-market scooters and entry motorcycles due to weight reduction mandates, while steel tanks retain margin concentration in premium and retro-styled segments where surface finish durability matters. The OEM channel commands the largest value share as factory-fit specifications tighten, though aftermarket providers are gaining traction in crash-replacement and custom build niches.
The US EPA and California Air Resources Board enforce evaporative emission standards that dictate tank permeation limits and sealing technologies for models sold in North America. India's BIS certification and the Automotive Research Association of India test protocols shape domestic tank specifications, particularly for ethanol-blend compatibility. Stakeholders must monitor how evolving emission thresholds in multiple jurisdictions will force material transitions and retooling investments without eroding cost structures.
Market Dynamics
The transition from stamped steel to blow-molded HDPE tanks is compressing material cost structures while forcing OEMs to retool stamping lines and requalify permeation performance under tightening evaporative emission protocols.
Growth Catalysts
- India's BIS fuel permeability standards:The Automotive Research Association of India's test protocols mandate ethanol-blend compatibility, accelerating HDPE tank adoption across domestic motorcycle platforms.
- Scooter electrification deferrals:Persistent cost gaps between internal combustion and electric powertrains sustain gasoline tank demand in Southeast Asian commuter segments.
- Weight reduction mandates:Plastic tank technology cuts unit mass by 30-50% versus steel equivalents, directly supporting OEM fleet efficiency targets.
Market Restraints
- Steel price volatility:Cold-rolled coil input costs fluctuate with energy-intensive smelting economics, squeezing margin on premium alloy tank programs.
- Blow molding equipment concentration:High-tonnage extrusion machinery suppliers cluster in Germany and Japan, creating capex bottlenecks for tier-2 tank fabricators.
- Permeation floor limits:California Air Resources Board evaporative emission thresholds impose material performance ceilings that resist commodity resin substitution.
Strategic Opportunities
- Ethanol-compatible barrier layers:Co-extruded HDPE with EVOH lining addresses India's E20 blend roadmap while opening retrofit potential for existing plastic tank fleets.
- Aftermarket crash replacement:Insurance-channel tank procurement bypasses OEM captive supply, rewarding independent molders with certified permeation testing.
- Indonesia's domestic content incentives:Local sourcing requirements for two-wheeler assembly create captive demand for regional blow molding capacity expansion.
Industry Challenges
- Multi-material welding expertise:Hybrid tank designs combining plastic shells with metal filler necks require process engineers skilled in vibration and hot-plate joining.
- Homologation timeline compression:Simultaneous BIS, EPA, and UN ECE R34 certification cycles strain validation laboratory capacity and delay program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2 Wheeler Fuel Tank Market |
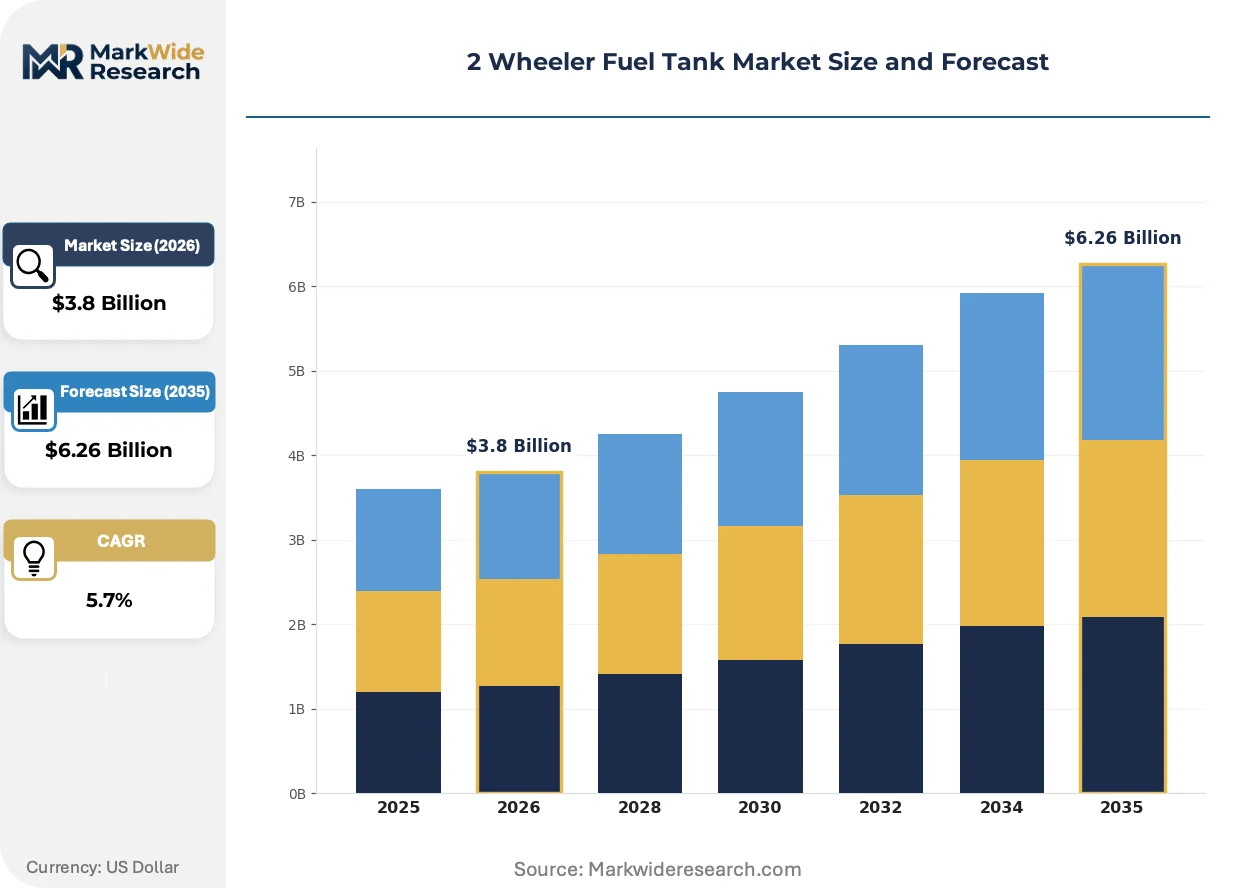
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Tanks, Plastic Tanks, Aluminum Tanks, Composite Tanks Manufacturing Stage: Injection Molding, Blow Molding, Metal Stamping, Welding Capacity: 10 Liters, 15 Liters, 20 Liters, 25 Liters End User: OEMs, Aftermarket Providers, Custom Builders, Dealerships |
| Companies Covered | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Bajaj Auto, Suzuki Motor Corporation, Royal Enfield, Harley-Davidson, Lumax Industries, Piaggio Vehicles, Goshi Giken Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2 Wheeler Fuel Tank Market Strategic Shifts
Material science advances and emission compliance automation are compressing traditional tank fabrication methods while opening modular design architectures that separate structural shells from permeation barriers.
Six-layer co-extruded HDPE with ethylene vinyl alcohol barrier cores is consolidating the mass-market scooter segment as the default fuel containment architecture. Indian and Vietnamese OEMs have standardized on this construction for 100-125cc commuter platforms. The technology is consolidating supplier tiers by eliminating secondary surface coating steps and collapsing the value chain into integrated blow molding cell outputs.
California Air Resources Board's evaporative emission enforcement is tightening permeation test protocols for 50-state motorcycle sales. Manufacturers must now validate tank systems across temperature cycling and vibration aging matrices. The premium and touring motorcycle segments bear the heaviest compliance burden, absorbing incremental validation costs through extended model cycles rather than annual refreshes.
Fleet procurement by ride-hailing aggregators is concentrating tank specification power away from individual OEMs toward platform owners with standardized durability requirements. Ola and Uber fleet managers in Indian metropolitan markets now dictate 150,000-kilometer tank lifecycle guarantees. Mumbai and Bangalore serve as the primary testing grounds for these negotiated performance contracts before national rollout.
2 Wheeler Fuel Tank Market Segmentation
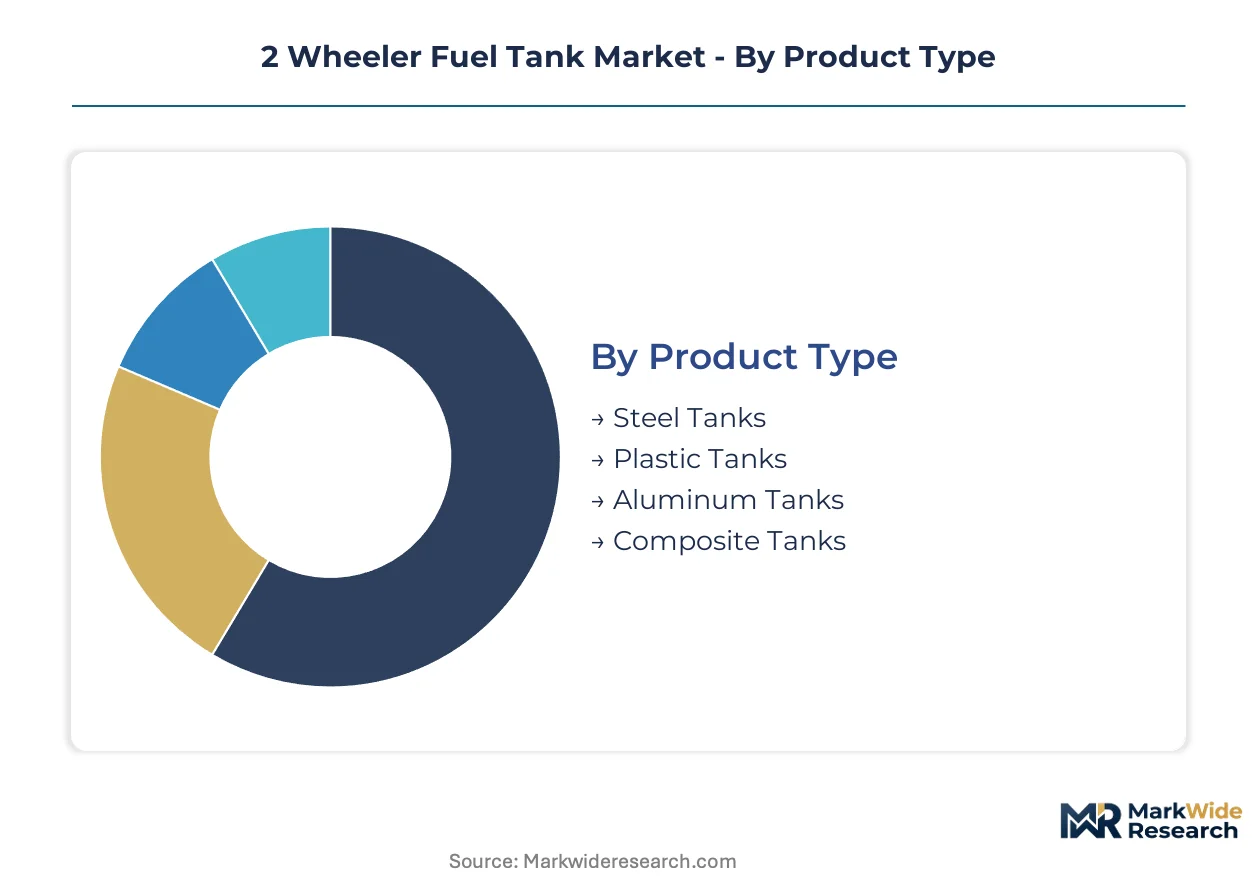
Two-wheeler fuel tank segmentation reveals how certification burdens, manufacturing economics, and end-use durability requirements split procurement across incompatible technical specifications. OEMs navigate divergent validation timelines for plastic versus metal architectures while aftermarket channels exploit regulatory gaps in crash-replacement segments.
Product Type:
Steel tanks carry UN ECE R34 and EPA evaporative emission certifications that plastic alternatives satisfy through alternative permeation testing protocols; aluminum and composite constructions occupy narrower homologation pathways with manufacturer-specific approvals.
- Steel Tanks:Cold-rolled and stamped alloy constructions dominate premium motorcycle segments where surface finish durability and crash integrity outweigh mass penalties. India's BIS certification for ethanol-blend compatibility has forced steel fabricators to upgrade coating systems for E20 fuel exposure, concentrating demand in retro-styled and touring platforms where OEMs retain in-house stamping capacity.
- Plastic Tanks:Six-layer co-extruded HDPE with EVOH barrier cores has become the default architecture for 100-125cc commuter scooters across India and Vietnam. The construction eliminates secondary coating steps and collapses supplier tiers into integrated blow molding outputs, though California Air Resources Board permeation floors resist commodity resin substitution in 50-state programs.
- Aluminum Tanks:Spun and welded alloys serve performance motorcycles where weight reduction intersects with premium surface aesthetics.
- Composite Tanks:Fiber-reinforced polymer constructions occupy racing and limited-production niches requiring custom homologation.
Leading the category by volume: Plastic Tanks. Growing fastest: Steel Tanks in ethanol-compatible coating variants.
Manufacturing Stage:
Process selection locks fabricators into distinct capital intensity tiers and geographic supplier clusters that shape regional competitiveness.
- Injection Molding:High-pressure thermoplastic forming dominates small-capacity scooter tanks and auxiliary fuel containers where dimensional precision matters more than permeation barrier integration.
- Blow Molding:Extrusion and stretch blow processes command the mass-market two-wheeler segment through continuous EVOH barrier co-extrusion. Equipment suppliers cluster in Germany and Japan, creating capex bottlenecks for tier-2 fabricators seeking to serve India's domestic OEM expansion.
- Metal Stamping:Progressive die and deep-draw operations sustain captive steel tank production at integrated motorcycle manufacturers.
- Welding:Automated seam and spot welding processes finish stamped shells and attach filler necks in hybrid plastic-metal designs.
Volume concentrates in Blow Molding. Margin expansion is steepest in Metal Stamping for premium alloy programs.
Capacity:
Tank volume specifications track platform segmentation between urban scooters and highway-capable motorcycles, with fuel efficiency regulations indirectly constraining maximum capacities.
- 10 Liters:Compact scooters and entry motorcycles in dense Asian urban markets where refueling infrastructure density reduces range anxiety.
- 15 Liters:Mid-size commuter motorcycles balancing weight distribution with 300-kilometer range targets.
- 20 Liters:Touring and adventure motorcycles requiring extended highway range without auxiliary fuel cells.
- 25 Liters:Heavy cruiser and touring platforms where fuel mass represents acceptable trade-off against stop frequency.
15-liter configurations anchor production volumes. 20-liter demand is climbing fastest in India's expanding middle-weight motorcycle segment.
End User:
Channel structure determines specification authority, warranty liability, and the stringency of permeation testing that tank fabricators must maintain.
- OEMs:Factory-fit specifications tighten validation requirements as motorcycle manufacturers consolidate supply around certified tier-1 molders with in-house ARAI and EPA testing laboratories. Ola and Uber fleet procurement in Mumbai and Bangalore now dictates 150,000-kilometer lifecycle guarantees that concentrate specification power away from individual OEMs toward platform owners.
- Aftermarket Providers:Insurance-channel crash replacement bypasses OEM captive supply, rewarding independent molders with certified permeation testing. The segment gains traction where regional repair density supports rapid tank substitution without full vehicle homologation delays.
- Custom Builders:Low-volume fabrication for modified motorcycles operates outside standard certification cycles with jurisdiction-dependent exemptions.
- Dealerships:Authorized service networks handle warranty-sanctioned replacements with OEM-sourced components.
OEMs command value share. Aftermarket Providers are expanding most quickly in India's insurance-integrated repair networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chakan industrial corridor near Pune anchors two-wheeler fuel tank fabrication across India, with integrated stamping and blow molding clusters serving domestic OEM demand and export programs to Southeast Asia and Africa.
India
Domestic motorcycle production exceeding 20 million units annually sustains the world's largest fuel tank procurement base. BIS certification for E20 ethanol compatibility redirects material specifications toward barrier-layer HDPE and upgraded steel coating systems. Tamil Nadu's Sriperumbudur-Oragadam belt hosts concentrated blow molding capacity expansion serving Honda and Yamaha assembly plants.
China
Export-oriented scooter manufacturing for African and Latin American markets sustains commodity-grade plastic tank volumes despite domestic electrification headwinds. MIIT fuel system standards enforce permeation testing protocols that favor established molders with captive laboratory certification. Chongqing's motorcycle industrial cluster retains metal stamping dominance for internal combustion platforms while coastal provinces shift capacity toward electric vehicle battery enclosures.
Indonesia
Government domestic content incentives require 40% local sourcing for two-wheeler assembly, stimulating regional blow molding investment. The country's national industrial regulator enforces fuel permeability benchmarks aligned with ASEAN harmonized standards. Bekasi and Karawang industrial zones outside Jakarta concentrate new HDPE extrusion capacity serving Suzuki and Yamaha joint venture facilities.
Vietnam
Motorcycle fleet density exceeding 70 million units sustains replacement tank demand alongside OEM factory-fit procurement. The Ministry of Transport's emission compliance deadlines accelerate plastic tank adoption across 110-125cc commuter segments. Ho Chi Minh City's Thu Duc industrial park anchors supplier parks for Honda Vietnam and Piaggio operations with integrated permeation testing laboratories.
Thailand
Regional export hub status for Japanese OEMs sustains premium alloy tank stamping for middle-weight and touring motorcycles. The Thailand Industrial Standards Institute mandates evaporative emission testing that exceeds baseline ASEAN requirements. Rayong province's Eastern Economic Corridor hosts concentrated supplier parks serving Yamaha and Kawasaki assembly with dedicated validation facilities.
2 Wheeler Fuel Tank Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification tiers, with barrier-layer HDPE specialists commanding pricing power over standard resin molders. The market structures around three distinct archetypes: integrated OEM captive fabricators, independent tier-1 suppliers with multi-client certification, and regional aftermarket specialists serving insurance-channel replacement. Dominant competitive moves include backward integration into blow molding equipment partnerships and geographic expansion into Indonesia's domestic content zones.
Among Japan-based motor corporations, Honda Motor Co., Ltd. and Yamaha Motor Co., Ltd. occupy positions as integrated OEM fabricators with captive stamping and molding capacity. Bajaj Auto represents the India-centric volume archetype with cost-optimized steel tank programs for domestic commuter segments. Lumax Industries sits within the independent tier-1 supplier category, exemplifying multi-client certification capabilities across plastic and metal architectures.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| Bajaj Auto |
| Suzuki Motor Corporation |
| Royal Enfield |
| Harley-Davidson |
| Lumax Industries |
| Piaggio Vehicles |
| Goshi Giken Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
OEM captive fabricators in India and Southeast Asia command pricing power through integrated blow molding and stamping capacity, locking tier-2 independent molders into commodity resin competition. Fleet procurement by ride-hailing aggregators now dictates lifecycle guarantees that compress margin recovery timelines across supplier tiers.
Pricing Analysis
Lifecycle-based pricing anchors premium tank procurement, with Ola and Uber fleet managers in Mumbai and Bangalore negotiating 150,000-kilometer durability guarantees that reset value benchmarks. Three-tier pricing structure across premium alloy, barrier-layer HDPE, and commodity resin tiers separates OEM factory-fit specifications from aftermarket crash replacement and custom build segments. Cost compression in standard resin grades is intensifying because Indonesian domestic content incentives are stimulating regional capacity additions. Aftermarket providers serving insurance-channel replacement exhibit highest price sensitivity, while integrated OEM captive fabricators retain lowest sensitivity through specification lock-in.
Supply Chain Analysis
High-tonnage extrusion blow molding equipment rests on German and Japanese machinery producers, creating capex bottlenecks for tier-2 fabricators seeking to serve India's domestic OEM expansion. Cold-rolled steel coil feeds from Indian integrated steel mills and Chinese export-oriented producers, while EVOH barrier resin draws from Asian petrochemical complexes. Single-source vulnerability concentrates in blow molding machinery supply, where equipment lead times strain program launch schedules. Distribution runs through OEM captive supply chains for factory-fit volumes, with independent molders accessing aftermarket channels via certified permeation testing laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from BIS ethanol-blend certification timelines and CARB permeation enforcement is forcing weaker resin molders without barrier-layer capability toward exit or acquisition.
For Market Incumbents: Cement barrier-layer HDPE dominance through backward integration into EVOH co-extrusion technology partnerships, eliminating secondary coating dependencies. Expand blow molding capacity in Indonesia's Bekasi-Karawang zones to capture domestic content incentives before joint venture facilities lock in preferred supplier status. Electrification deferrals in Southeast Asian commuter segments sustain gasoline tank demand, but California Air Resources Board permeation floors resist commodity resin substitution—position premium alloy stamping for touring segments where validation costs amortize across extended model cycles. For New Entrants and Emerging Players: E-commerce aftermarket platforms offer the lowest barrier route to India's insurance-integrated crash replacement networks, bypassing OEM homologation delays. Target Vietnam's Thu Duc industrial park supplier adjacencies, where Honda Vietnam and Piaggio operations concentrate demand for certified permeation testing capabilities. Pursue ethanol-compatible barrier layer retrofit kits for existing plastic tank fleets as India's E20 blend roadmap accelerates material transition requirements. For Investors and Strategic Acquirers: The window for entry favors independent tier-1 suppliers with multi-client ARAI and EPA certification laboratories, positioned between integrated OEM captives and regional aftermarket specialists. Acquisition targets should demonstrate validated six-layer co-extrusion capability and geographic exposure to India's Chakan corridor or Indonesia's domestic content zones. Watch Ola and Uber fleet procurement contract terms as the signal for specification power consolidation away from individual OEMs toward platform owners.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Layer Co-Extrusion Capacity Expansion | Captures India's E20 ethanol compatibility mandate while eliminating secondary coating steps. |
| Indonesia Domestic Content Zone Entry | Locks in 40% local sourcing requirements for Suzuki and Yamaha joint venture assembly. |
| ARAI Certification Laboratory Investment | Accelerates BIS homologation timelines for tier-2 fabricators competing for OEM supply. |
| Aftermarket Insurance Channel Integration | Bypasses OEM captive supply through certified permeation testing for crash replacement. |
| Hybrid Plastic-Metal Welding Process Development | Addresses multi-material joining expertise gaps in vibration and hot-plate joining. |
Study Parameters
Multi-period observation of BIS certification timelines, CARB permeation enforcement actions, and OEM platform standardization patterns anchored the trend analysis, supplemented by interviews with tier-1 tank fabricator procurement heads, ARAI validation laboratory directors, and fleet operations managers at Indian ride-hailing aggregators. Secondary validation drew from EPA evaporative emission rulemakings, Automotive Research Association of India test protocol publications, and motorcycle production databases. Bottom-up volume estimates from individual OEM platform specifications triangulated against top-down market sizing from regional two-wheeler assembly data.
Input-output matrices modeled tank demand across material type, manufacturing process, capacity segment, and end-user channel dimensions throughout the forecast period. CAGRs derived from production volume trajectories, platform electrification deferral rates, and ethanol-blend adoption curves across Indian and Southeast Asian markets. Forecast inputs incorporated BIS E20 roadmap implementation pace, Indonesian domestic content incentive enforcement, and California Air Resources Board permeation threshold evolution.
Inputs from ARAI certification records and OEM supplier qualification databases were available through the study window; gaps in real-time tier-2 fabricator capacity utilization data introduce uncertainty bands around aftermarket volume projections. Forecasts reflect documented assumptions regarding ethanol-blend compatibility timelines and electrification substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Child Seats Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Engine Components Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Navigation Light Market
Vehicle Components
Suction Road Sweeper Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Automotive Pyrofuse Market