
 Hybrid Train Market | 2026-2036
Hybrid Train Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Train Market Intelligence
Performance-based maintenance contracts is broadening revenue streams beyond rolling stock sales. Alstom SA leverages its hydrogen fuel cell expertise to anchor European intercity deployments. Siemens AG sustains technology leadership through integrated energy storage and smart traction control architectures. CRRC Corporation Limited dominates manufacturing scale across Asia-Pacific commuter corridors.
A hybrid train combines multiple propulsion sources—typically diesel engines paired with electric motors, batteries, or hydrogen fuel cells—to optimize energy efficiency and reduce emissions across varying route electrification profiles. These systems employ regenerative braking to recover kinetic energy and store it in onboard battery packs or supercapacitors for auxiliary power or traction assist. Battery-electric configurations now lead municipal transit deployments where catenary infrastructure remains incomplete, while hydrogen fuel cell variants command premium positioning in intercity rail segments requiring extended range without overhead lines. Dual power units serve freight operators navigating mixed electrification territories, with energy storage systems representing the fastest-growing technology layer as cell density improves.
The EU Green Deal and F-Gas Regulation shape European procurement by mandating progressive carbon intensity reductions across passenger and freight networks. In Japan, METI rail efficiency standards and the country's dual carbon goals accelerate hydrogen fuel cell adoption on regional lines. The US EPA locomotive emissions tiers and Federal Railroad Administration safety certifications govern market access for North American operators. Stakeholders must monitor regulatory divergence between battery-centric European frameworks and hydrogen-forward Asian policies when allocating R&D and production capacity.
Market Dynamics
Dual-mode propulsion architectures are forcing a recalibration of fleet procurement timelines as rail operators weigh battery density improvements against hydrogen infrastructure readiness. The tension between electrification mandates and route-specific technical constraints is compressing supplier qualification windows.
Growth Catalysts
- EU Green Deal rail decarbonization mandates:Intercity operators in Germany and France face binding carbon intensity reduction targets that accelerate hybrid fleet replacement cycles.
- Battery-electric propulsion systems:Municipal transit authorities in partially electrified corridors now specify onboard energy storage as baseline requirement rather than upgrade option.
- Japan METI rail efficiency standards:Regional line operators must demonstrate measurable energy recovery rates, driving regenerative braking adoption.
Market Restraints
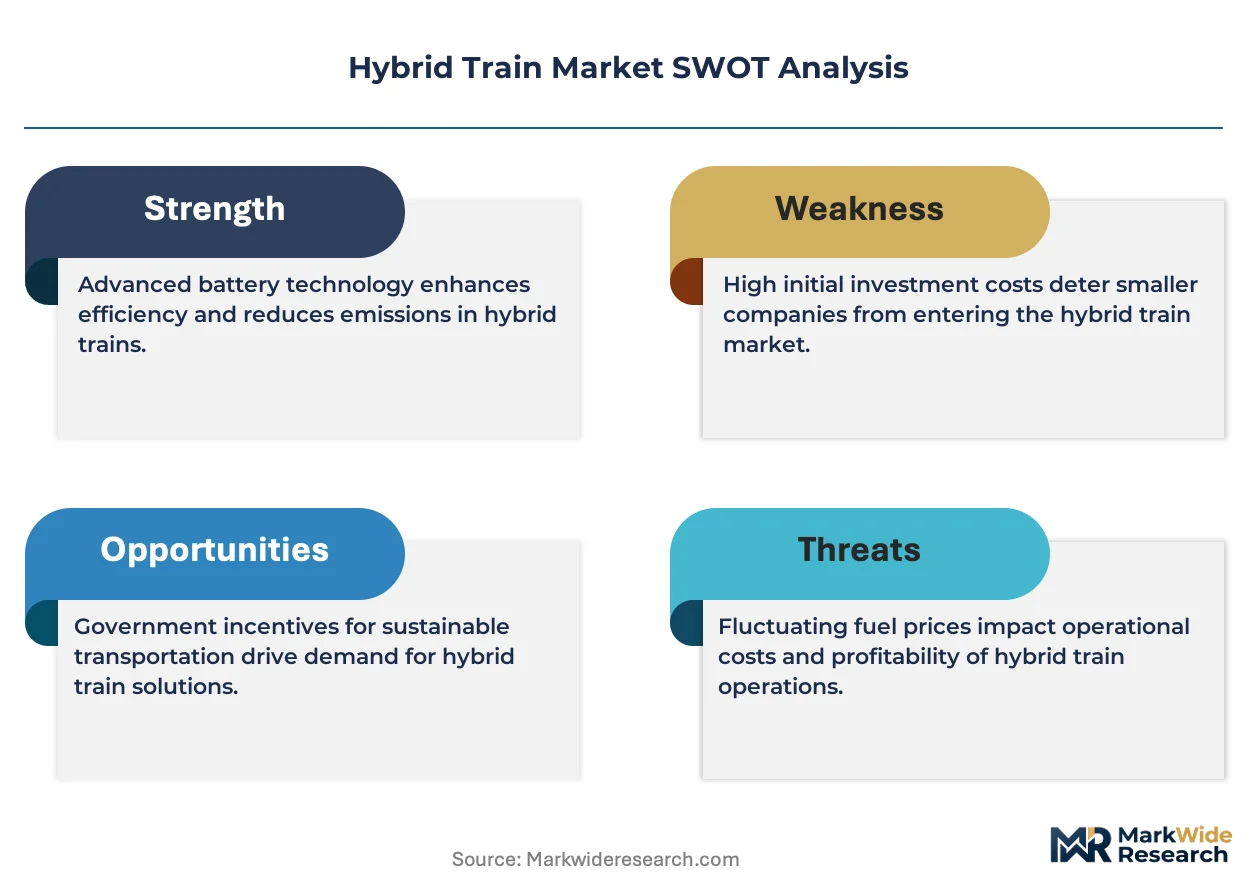
- Lithium-ion cell supply concentration:Cathode material processing capacity clusters in East Asia, exposing European and North American train builders to input cost volatility and logistics bottlenecks.
- Hydrogen fuel cell stack costs:Platinum group metal loading requirements keep proton exchange membrane systems priced above diesel-electric equivalents for medium-haul routes.
- Catenary infrastructure gaps:Mixed electrification territories force operators to maintain dual maintenance competencies, inflating total cost of ownership.
Strategic Opportunities
- India's suburban rail electrification gaps:Battery-electric multiple units offer deployment pathways where overhead line completion lags behind fleet renewal schedules.
- Performance-based maintenance contracts:Availability-guarantee structures allow OEMs to capture recurring revenue streams beyond rolling stock delivery.
- EU F-Gas Regulation phase-down:Refrigerant restrictions in auxiliary HVAC systems create retrofit demand for trains operating beyond design life.
Industry Challenges
- Systems integration engineering talent:Shortage of specialists capable of optimizing power electronics, thermal management, and energy storage control in unified architectures.
- Multi-jurisdiction type certification:Divergent safety validation protocols between national rail authorities extend product launch timelines.
- Legacy fleet interoperability:Mixed-traffic lines require hybrid trains to maintain signaling and coupling compatibility with decades-old rolling stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Train Market |
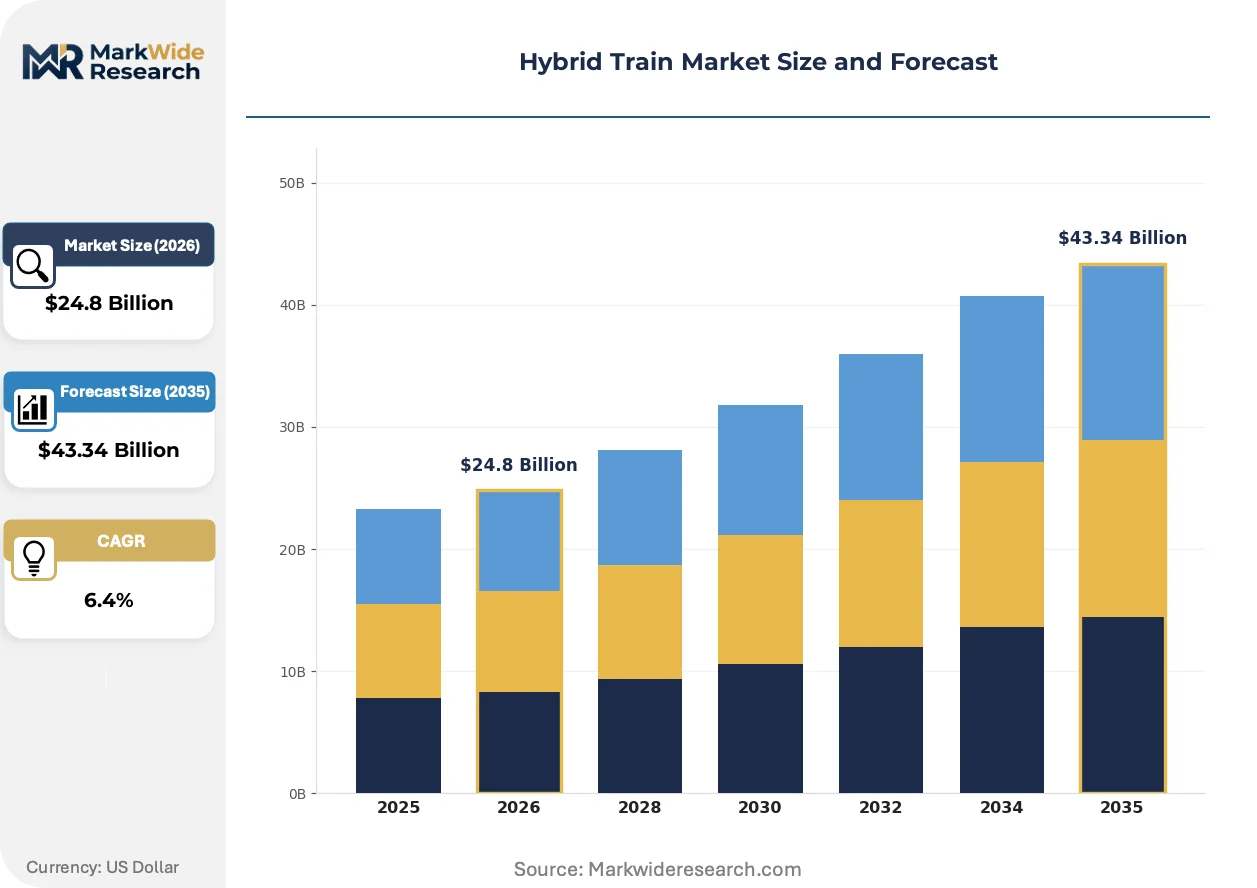
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric-Diesel, Battery-Electric, Hydrogen Fuel Cell, Dual Power End User: Municipal Transit, Freight Operators, Passenger Railways, Commuter Services Technology: Regenerative Braking, Energy Storage Systems, Turbocharged Engines, Smart Traction Control Deployment: Urban Rail, Intercity Rail, Regional Transit, Freight Networks |
| Companies Covered | CRRC Corporation Limited, Alstom SA, Siemens AG, Hitachi Rail, Wabtec Corporation, Stadler Rail AG, Bombardier, Hyundai Rotem Company, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Train Market Strategic Shifts & Innovations
Solid-state battery chemistries and hydrogen fuel cell scaling are rewriting the technical assumptions underlying fleet procurement decisions. These shifts are compressing the window for incumbent propulsion suppliers to demonstrate next-generation performance.
Solid-state lithium-metal cells with ceramic electrolyte separators are rewriting energy density benchmarks for rail applications. Japanese and South Korean battery suppliers are sampling prototype packs to regional train builders for 2027 platform integration. The technology is rewriting route feasibility calculations by extending battery-electric range into intercity segments previously reserved for diesel or hydrogen.
The EU F-Gas Regulation mandates progressive reduction in hydrofluorocarbon use across transport refrigeration and auxiliary climate systems. Train HVAC suppliers must redesign thermal management architectures around natural refrigerants or low-global-warming-potential synthetic alternatives. Intercity operators in France and Germany are specifying compliant systems in new procurements, with retrofit obligations emerging for in-service fleets.
Availability-based service agreements are displacing traditional time-and-material maintenance for energy storage and traction systems. Fleet operators in Germany and Switzerland now contract guaranteed uptime percentages rather than scheduled component replacements. This shift concentrates risk with OEMs and accelerates predictive analytics deployment across regional maintenance depots.
Hybrid Train Market Segmentation
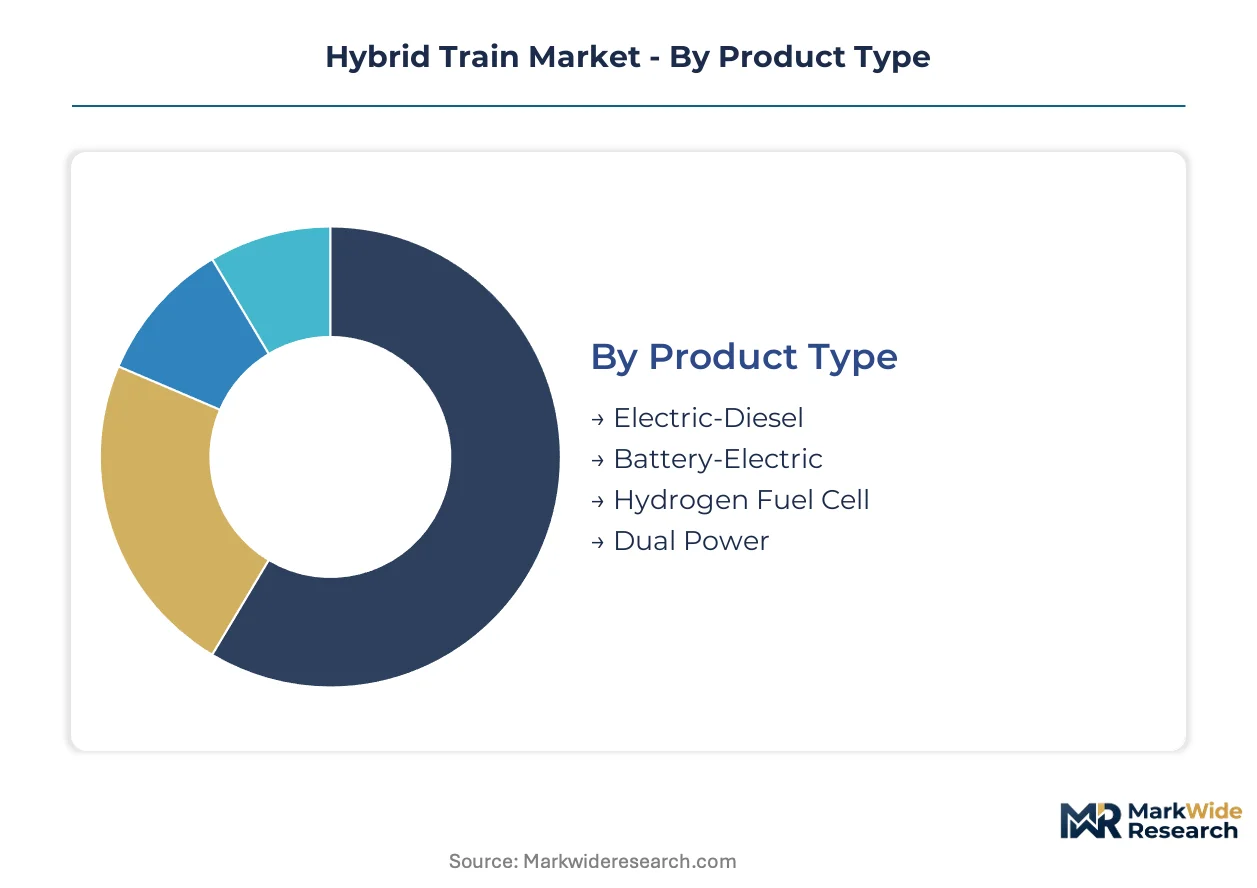
Hybrid train procurement decisions fragment across four distinct axes: propulsion architecture, operator type, enabling technology, and route deployment profile. Each axis carries divergent margin structures and qualification requirements that reshape supplier competitive positioning.
Product Type:
Supply concentration clusters around battery-electric and hydrogen fuel cell architectures as tier-one OEMs consolidate R&D spend on zero-emission platforms.
- Battery-Electric:Lithium-ion packs with silicon-anode chemistries deliver 800V traction architectures. German intercity operators and Japan's regional lines specify these for partially electrified corridors where catenary gaps exceed 50km, constrained by cell thermal management in extreme climates.
- Hydrogen Fuel Cell:Proton exchange membrane stacks paired with carbon-fiber hydrogen tanks enable 1,000km+ range without overhead lines. South Korea's Korail and French SNCF pilot these on non-electrified intercity routes, though platinum loading keeps stack costs elevated versus diesel baselines.
- Electric-Diesel:Dual-mode locomotives switch between pantograph and onboard diesel generation.
- Dual Power:Configurations blending battery buffers with prime movers for freight flexibility.
Today's leader: Battery-Electric. Tomorrow's challenger: Hydrogen Fuel Cell.
End User:
Application requirements diverge sharply between scheduled passenger services and freight operators with variable duty cycles.
- Passenger Railways:Intercity operators prioritize ride quality and HVAC efficiency alongside propulsion metrics. SNCF and Deutsche Bahn specify regenerative braking integration with station energy recovery systems, driven by EU Green Deal carbon accounting requirements.
- Municipal Transit:Urban operators face stop-start duty cycles that maximize regenerative braking returns. Battery-electric multiple units dominate procurement in Indian suburban corridors and Southeast Asian metro extensions where electrification lags fleet renewal.
- Freight Operators:Heavy-haul requirements prioritize traction power over energy recovery.
- Commuter Services:Mixed-traffic lines demand interoperability with legacy rolling stock.
Passenger Railways anchor current procurement volume. Municipal Transit offers the steepest expansion trajectory as Asian cities accelerate fleet replacement.
Technology:
Cost tier differentiation separates premium smart traction architectures from baseline regenerative braking retrofits.
- Energy Storage Systems:Solid-state lithium-metal cells with ceramic electrolytes are sampling to Japanese and South Korean train builders for platform integration. These systems extend battery-electric range into intercity segments previously reserved for diesel or hydrogen, rewriting route feasibility calculations.
- Smart Traction Control:AI-optimized power electronics manage wheel slip and energy distribution across mixed electrification territories. Siemens and Alstom embed these in premium intercity offerings, capturing margin through software-defined performance guarantees.
- Regenerative Braking:Kinetic energy recovery systems now baseline for municipal procurements.
- Turbocharged Engines:Downsized diesel prime movers for dual-mode configurations.
Smart Traction Control commands pricing premiums today. Energy Storage Systems will determine competitive position as solid-state cells reach rail qualification.
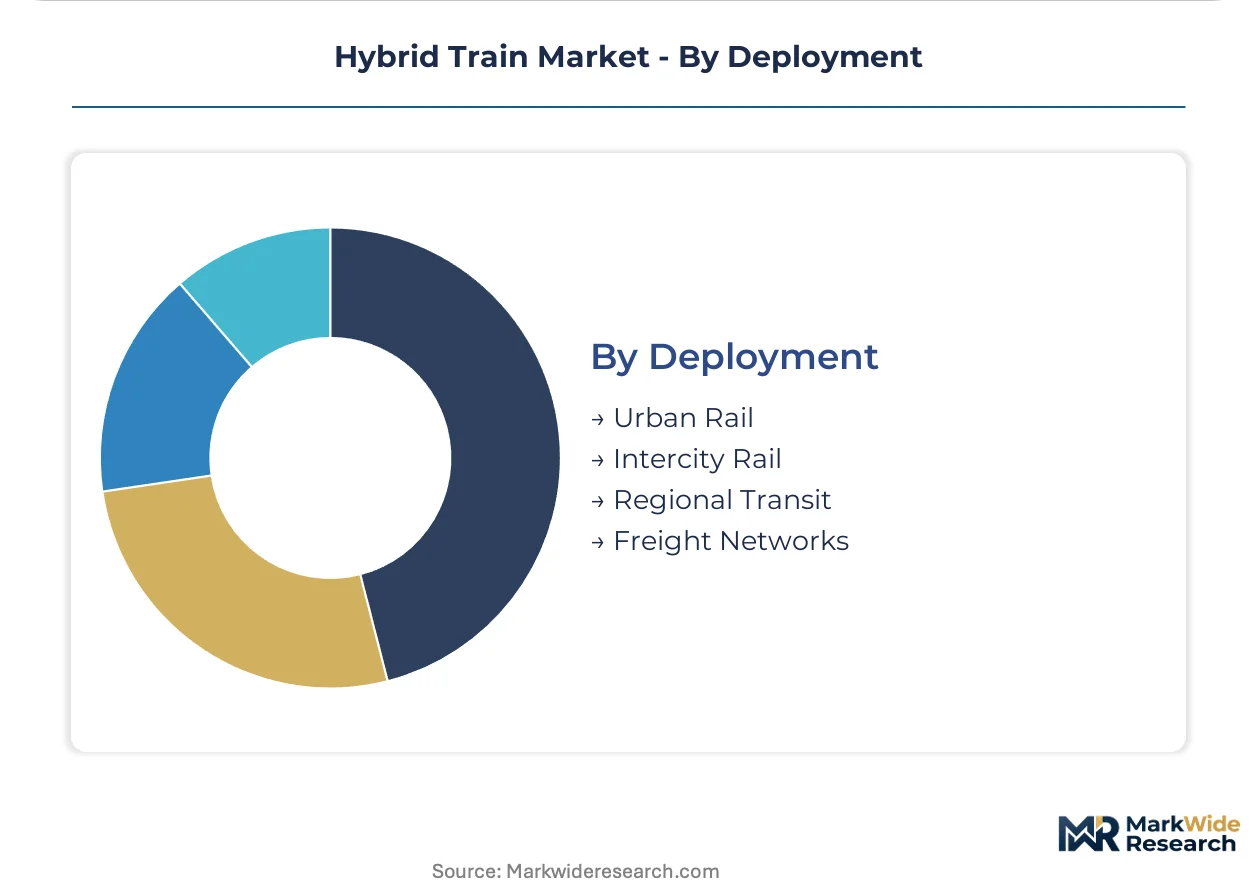
Deployment:
Geography dictates propulsion mix with urban density correlating to electrification completeness.
- Urban Rail:Metro and light rail systems in partially electrified corridors specify battery-electric multiple units as baseline. India's suburban networks and Southeast Asian metro extensions drive volume where overhead line completion trails fleet schedules.
- Intercity Rail:Long-distance routes without catenary infrastructure favor hydrogen fuel cell or dual-mode configurations. French and German operators pilot hydrogen on 200km+ segments, constrained by refueling station buildout timelines.
- Regional Transit:Medium-haul corridors with intermittent electrification.
- Freight Networks:Mixed-traffic lines requiring compatibility with legacy diesel locomotives.
Urban Rail concentrates near-term volume. Intercity Rail represents the longest-duration revenue opportunity as hydrogen infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is accelerating production migration toward jurisdictions with lower compliance costs for hydrogen fuel cell certification and battery pack assembly. Manufacturers are relocating final assembly to exploit gaps between EU F-Gas enforcement timelines and Asian subsidy programs.
Germany
Deutsche Bahn's fleet renewal program drives demand for dual-mode locomotives on partially electrified intercity corridors. The EU Green Deal mandates binding carbon intensity reductions that compress procurement timelines. Siemens Mobility anchors manufacturing in Munich and Nuremberg, supplying battery-electric multiple units to regional operators.
Japan
East Japan Railway Company pilots hydrogen fuel cell trains on 200km non-electrified segments in Hokkaido. METI rail efficiency standards require measurable energy recovery rates that favor regenerative braking integration. Kawasaki Heavy Industries and Hitachi Rail concentrate development in Kobe and Hitachi City, advancing solid-state battery sampling for 2027 platforms.
South Korea
Korail's intercity hydrogen corridor program targets 1,000km range without overhead lines. The national hydrogen economy roadmap subsidizes fuel cell stack localization to reduce platinum group metal dependency. Hyundai Rotem dominates manufacturing in Changwon, supplying proton exchange membrane systems to domestic and export markets.
China
CRRC Corporation leverages manufacturing scale across suburban rail electrification gaps in tier-two cities. The dual carbon goals accelerate battery-electric multiple unit deployment where catenary completion lags fleet schedules. Production concentrates in Changchun and Qingdao, with silicon-anode cell integration advancing for 800V traction architectures.
United States
California commuter rail operators specify battery-electric configurations for corridor services between San Jose and Gilroy. EPA locomotive emissions tiers and FRA safety certifications govern market access for North American deployments. Wabtec Corporation anchors final assembly in Erie, Pennsylvania, supplying freight and passenger hybrid platforms.
Hybrid Train Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium positioning in intercity deployments while component suppliers capture volume in municipal transit retrofits. The vendor base organizes around three tiers: full-system integrators with traction control software capabilities, battery pack assemblers with cell sourcing relationships, and hydrogen fuel cell stack specialists with membrane electrode assembly expertise. Dominant competitive moves include strategic partnerships for energy storage system qualification and geographic expansion through availability-based maintenance contract anchoring.
Among European full-system integrators, Alstom SA and Siemens AG exemplify the premium-tier archetype through integrated smart traction architectures. CRRC Corporation Limited occupies the scale-driven position, leveraging captive manufacturing depth across Asia-Pacific commuter corridors. These three anchors represent divergent strategic postures: technology leadership through fuel cell expertise, software-defined performance guarantees, and cost-optimized volume production respectively.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom SA |
| Siemens AG |
| Hitachi Rail |
| Wabtec Corporation |
| Stadler Rail AG |
| Bombardier |
| Hyundai Rotem Company |
| Kawasaki Heavy Industries |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon intensity mandates are compressing procurement timelines for battery-electric and hydrogen fuel cell trains, forcing suppliers to absorb qualification costs upfront while OEMs negotiate long-term availability contracts that lock in margin structures before cell chemistry transitions mature.
Pricing Analysis
Distributor margins on replacement battery packs and fuel cell stacks typically run 12-18 percent above direct OEM supply. Three-tier pricing structure across premium smart traction architectures, standard regenerative braking retrofits, and economy-grade dual-mode conversions captures divergent buyer technical requirements. Cost compression in battery-electric configurations is intensifying because silicon-anode cell suppliers are competing for platform slots at Korean and Japanese train builders. Municipal transit authorities exhibit highest price sensitivity due to fixed subsidy envelopes, while intercity operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Platinum group metal feedstock for proton exchange membrane stacks rests on South African and Russian mining concentration, creating geopolitical exposure for hydrogen fuel cell cost trajectories. Cathode active material processing clusters in China, South Korea, and Japan, with European and North American train builders dependent on long-haul logistics for lithium-nickel-manganese-cobalt oxide inputs. Single-source vulnerability in ceramic electrolyte separators for solid-state prototypes threatens 2027 platform readiness timelines. Distribution runs through regional maintenance depots under availability-based contracts rather than traditional parts wholesaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid train market functions as a regulatory compounder where EU F-Gas refrigerant phase-downs and METI efficiency standards create successive procurement waves that outpace pure technology substitution cycles.
For Market Incumbents: Deploy predictive maintenance analytics as a retention lever against emerging battery-as-a-service entrants. Siemens and Alstom should anchor backward integration into silicon-anode cell qualification partnerships before solid-state platforms commoditize traction system differentiation. Capacity expansion in Changwon and Kobe manufacturing clusters defends share against CRRC's cost-optimized volume push into Southeast Asian municipal transit. For New Entrants and Emerging Players: The 40-60 percent price gap between hydrogen fuel cell intercity platforms and battery-electric multiple units opens white-space at the mid-tier dual-mode segment. India's suburban electrification gaps offer the most penetrable geography, with state rail operators prioritizing rapid deployment over brand heritage. A service-leasing model bundling rolling stock with energy infrastructure buildout bypasses capital-constrained procurement committees. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane electrode assembly specialists possessing platinum loading reduction IP, as stack cost parity with diesel determines hydrogen adoption velocity. Five-to-ten-year viability hinges on refueling station network density maturing alongside fleet deployment. Watch Korail's intercity hydrogen corridor utilization rates as the inflection signal for regional line economics.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Platform Integration | Japanese and South Korean suppliers sampling ceramic electrolyte packs to train builders rewrite range feasibility for intercity segments. |
| Hydrogen Refueling Infrastructure Partnership | French SNCF and German Deutsche Bahn station buildout commitments de-risk fuel cell stack procurement at Hyundai Rotem and Alstom. |
| Availability-Based Maintenance Contract Expansion | Siemens and Stadler capture recurring revenue streams by guaranteeing uptime percentages rather than scheduled component replacement. |
| Silicon-Anode Cell Backward Integration | CRRC's captive supply relationships in Changchun and Qingdao insulate against cathode material cost volatility from East Asian processors. |
| EU F-Gas Compliant HVAC Retrofit Program | Natural refrigerant system redesigns create aftermarket demand for trains operating beyond original design life in France and Germany. |
Research Approach
Multiple input streams — regulatory filing analysis, supply chain documentation, and fleet procurement databases — were reconciled against primary interviews with rolling stock procurement directors, rail operator maintenance heads, and energy storage system engineers. Secondary validation drew from EU transport authority decarbonization reports, METI rail efficiency standard disclosures, and customs records for lithium-ion cell trade flows. Bottom-up unit deployment modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Data-stream reconciliation anchored the analytical framework across propulsion architecture, operator type, and deployment geography dimensions. CAGRs were derived from segmented growth rate aggregation weighted by procurement pipeline visibility. Forecast inputs incorporated hydrogen infrastructure buildout timelines, solid-state battery qualification milestones, and EU Green Deal enforcement intensity variations by member state.
Caveats apply where platinum group metal price spikes, ceramic electrolyte separator supply interruptions, or F-Gas Regulation enforcement delays could materially shift the outlook. A small set of named triggers — Korail corridor utilization, Deutsche Bahn dual-mode order pacing, and Chinese silicon-anode production ramp — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
India Hybrid Vehicles Market