
 Automotive Air Flow Sensors Market | 2026-2036
Automotive Air Flow Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Flow Sensors Market Analysis
Multi-source procurement for MEMS-based sensing elements is pivoting toward captive foundry arrangements as chip supply volatility persists. Robert Bosch GmbH leverages its Reutlingen semiconductor campus to secure wafer supply for mass air flow modules. Continental AG anchors European OEM programs through integrated sensor-to-ECU architectures. Denso Corporation dominates Asian hybrid vehicle platforms with temperature-compensated thermal sensing designs.
Automotive air flow sensors measure intake air volume, density, and temperature to optimize fuel injection timing and combustion efficiency in internal combustion and hybrid powertrains. Thermal sensing technology, specifically hot-wire and hot-film anemometry, detects mass flow rates with response times under 15 milliseconds for real-time engine control. Mass air flow sensors command the largest installed base due to universal fitment in gasoline direct-injection engines, while differential pressure variants are displacing legacy speed sensors in turbocharged applications where boost monitoring precision directly affects emissions compliance. Ultrasonic measurement remains niche but extends into heavy-duty commercial segments where pitot tube durability fails under particulate loading.
EPA tailpipe standards and Euro 7 proposals from the European Commission are forcing recertification of engine management systems, which expands replacement and retrofit sensor demand. NHTSA corporate average fuel economy rules and China's MIIT dual carbon goals create parallel compliance obligations that sustain OEM specification upgrades. Stakeholders must monitor regulatory divergence between California Air Resources Board waivers and federal standard rollbacks, as this tension determines whether sensor suppliers maintain single global SKU strategies or fragment into region-specific product lines.
Market Dynamics
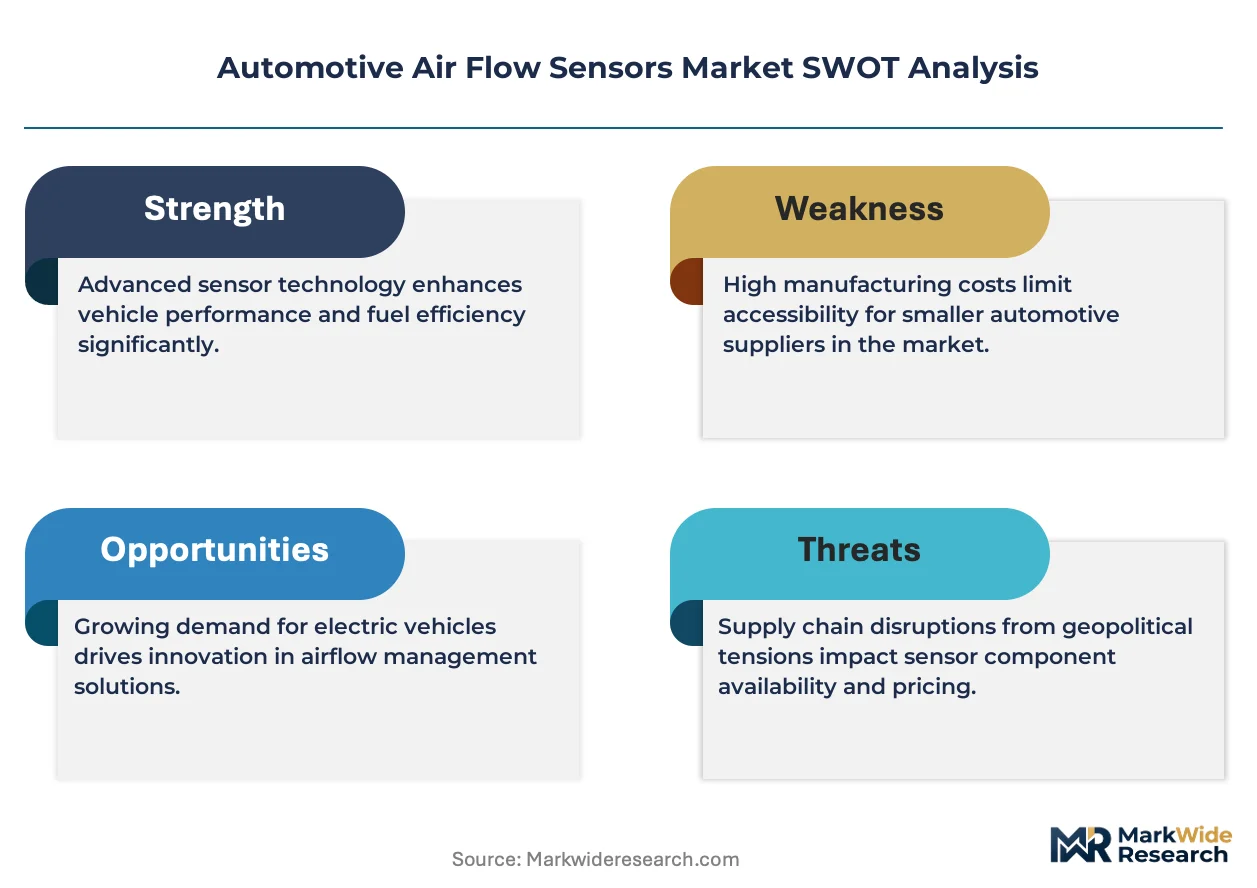
MEMS semiconductor supply concentration is forcing tier-1 sensor suppliers into captive foundry investments and multi-year wafer allocation contracts to secure thermal sensing element availability.
Growth Catalysts
- Euro 7 emission thresholds:The European Commission's proposed particulate and NOx limits are mandating recalibration of engine management systems across gasoline direct-injection platforms.
- Hybrid powertrain expansion:Temperature-compensated thermal sensing designs are proliferating in Asian hybrid vehicle programs where precise air-fuel ratio control optimizes combustion across electric-boost modes.
- Reutlingen semiconductor cluster:German captive foundry capacity is anchoring European supply security for hot-wire anemometry modules serving both domestic OEMs and export programs.
Market Restraints
- Silicon wafer input volatility:200mm MEMS substrate pricing fluctuations are compressing gross margins for non-vertically integrated sensor assemblers.
- Single-source Bosch Reutlingen dependency:European OEMs face concentration risk as one campus supplies the majority of regional hot-film sensing element demand.
- Thermal drift limitations:Hot-wire designs require periodic recalibration in heavy-duty commercial segments where particulate loading accelerates sensor degradation.
Strategic Opportunities
- Indian commercial vehicle retrofit:BS-VI compliance deadlines are expanding aftermarket sensor replacement demand in heavy-duty diesel applications.
- Ultrasonic-piezoelectric convergence:Heavy-duty OEMs are piloting pitot-replacement ultrasonic arrays in mining and construction equipment where thermal methods fail.
- California Air Resources Board waivers:State-level emissions autonomy is creating specification divergence that rewards flexible SKU architectures over global single-design strategies.
Industry Challenges
- MEMS process engineering talent scarcity:Foundry operators face recruitment gaps for thermal anemometry-specific wafer fabrication expertise.
- Dual certification timeline compression:Simultaneous EPA and Euro 7 homologation requirements are straining validation laboratory capacity.
- Legacy MAP sensor integration friction:Turbocharged powertrain upgrades require complex signal conditioning to reconcile differential pressure and mass air flow architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Flow Sensors Market |
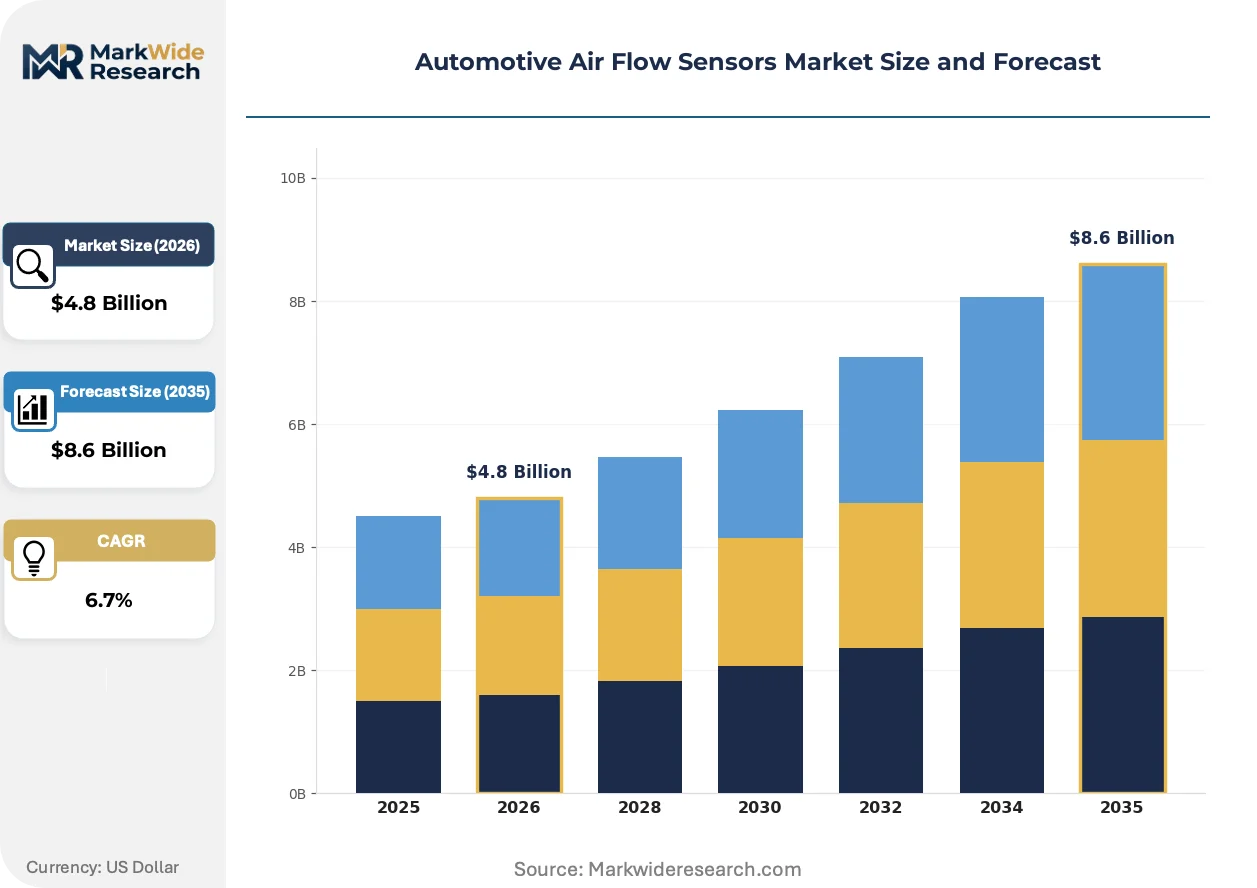
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Air Flow Sensor, Differential Pressure Sensor, Speed Sensor, Temperature Sensor Technology: Thermal Sensing, Pneumatic Measurement, Pitot Tube, Ultrasonic Measurement End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Automotive Workshops Installation: Under-the-Hood, Inline, Dashboard Mounted, Integrated |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Continental AG, BorgWarner Inc., Hitachi Automotive Systems Ltd., HELLA GmbH & Co. KGaA, Sensata Technologies Inc., Valeo Group, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Flow Sensors Market Emerging Trajectories
Sensor architecture is bifurcating between integrated module-to-ECU designs for new vehicle platforms and standalone replacement units for the expanding aftermarket retrofit segment.
Hot-film MEMS technology is electrifying mass air flow measurement through platinum-thin-film deposition on ceramic substrates that delivers sub-15-millisecond response times. OEMs are specifying these modules for gasoline direct-injection engines where real-time fuel trim precision determines emissions compliance. The technology is electrifying competitive positioning by compressing the performance gap between premium and standard sensor tiers.
EPA tailpipe standards and Euro 7 proposals are forcing synchronized recertification campaigns across engine management system suppliers. The industrial consequence is expanded validation service demand and extended product development cycles. Turbocharged powertrain segments are responding with differential pressure sensor upgrades that displace legacy speed-density calculation methods.
Buyer concentration among platform-sharing OEM consortia is compressing specification negotiation leverage for tier-2 sensor suppliers. Long-term supply agreements with volume guarantees are displacing spot procurement in the European and North American passenger vehicle channels. This pattern is most visible in Germany where Bosch, Continental, and Valeo anchor integrated sensor-to-ECU architectures for shared modular powertrain programs.
Automotive Air Flow Sensors Market Segmentation
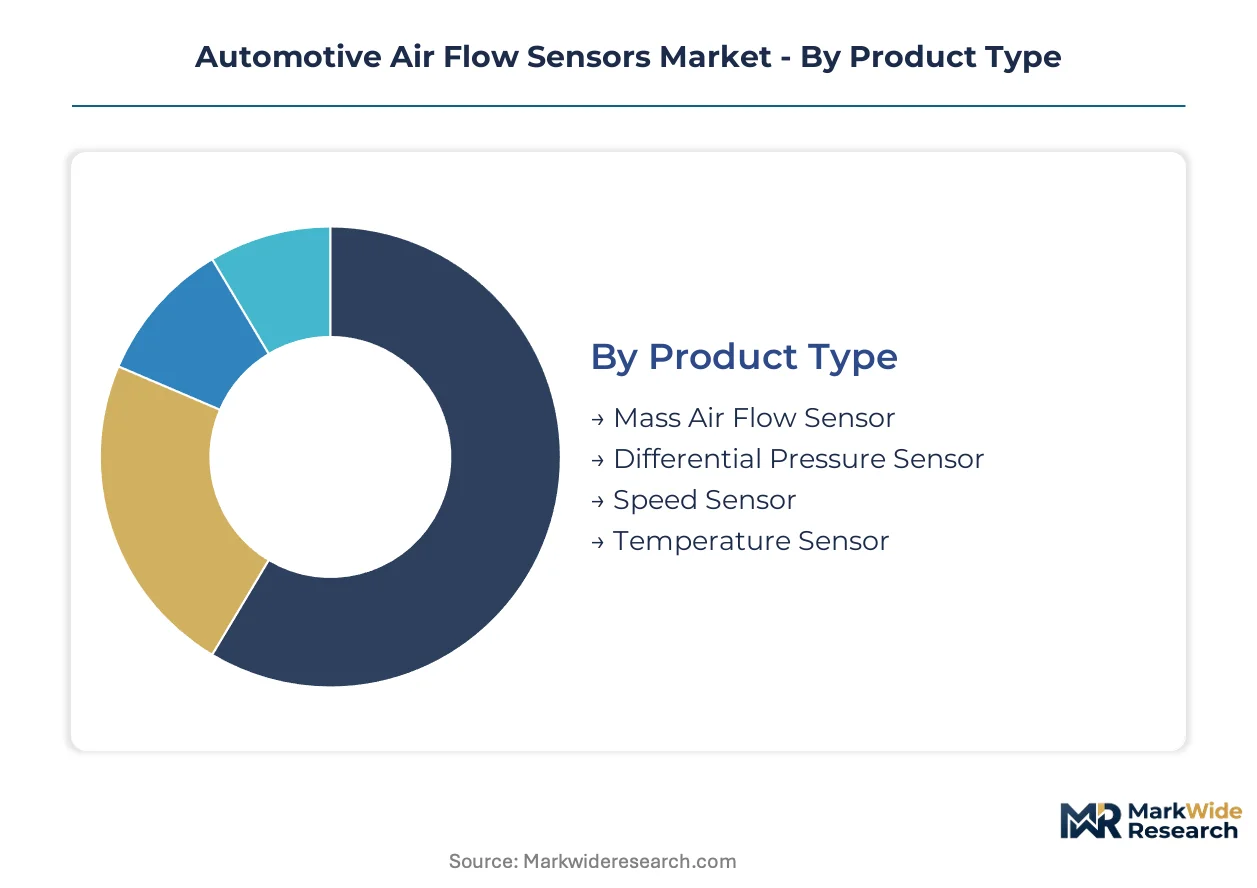
Powertrain electrification and emission recertification cycles are fragmenting sensor specifications across vehicle platforms. Suppliers must architect product lines that span integrated OEM modules, aftermarket retrofit units, and hybrid-specific calibration variants.
Product Type:
Replacement cycles diverge sharply between gasoline direct-injection platforms requiring precision mass air flow modules and commercial diesel segments tolerating longer service intervals for differential pressure variants.
- Mass Air Flow Sensor:Hot-wire and hot-film anemometry elements measure intake air mass with sub-15-millisecond response times for real-time fuel trim. Gasoline direct-injection engines in German passenger vehicle programs specify these modules universally as Euro 7 thresholds tighten combustion precision requirements.
- Differential Pressure Sensor:MEMS-based diaphragm architectures detect boost pressure across turbocharger circuits. Turbocharged powertrains in Asian hybrid platforms are displacing legacy speed-density calculations with these sensors to optimize air-fuel ratios during electric-boost transitions.
- Speed Sensor:Inductive and Hall-effect designs monitor crankshaft and camshaft rotational velocity for engine timing synchronization. Legacy fitments persist in cost-optimized commercial vehicle segments where MAP sensor integration remains incomplete.
- Temperature Sensor:Thermistor and RTD elements compensate air density calculations for thermal drift. Heavy-duty diesel applications in Indian BS-VI retrofit programs demand these as companion elements to mass air flow modules.
Mass Air Flow Sensor sits at the top of the volume ranking, with Differential Pressure Sensor climbing the fastest.
Technology:
Foundry capacity allocation favors thermal sensing architectures with captive wafer supply, while ultrasonic methods attract development investment for particulate-heavy operating environments.
- Thermal Sensing:Platinum-thin-film deposition on ceramic substrates enables hot-wire and hot-film mass flow detection. Bosch's Reutlingen campus anchors European supply security for these elements serving both domestic OEMs and export powertrain programs.
- Pneumatic Measurement:Diaphragm-based pressure differential detection relies on machined aluminum housings and silicone oil fill. Commercial vehicle segments in cost-sensitive geographies specify these for intake manifold absolute pressure monitoring where MEMS integration is uneconomical.
- Pitot Tube:Stainless steel probe geometries measure dynamic pressure for airflow velocity calculation. Mining and construction equipment OEMs are phasing these out due to particulate clogging and thermal degradation under sustained load.
- Ultrasonic Measurement:Piezoelectric transducer arrays emit high-frequency pulses for time-of-flight airflow detection. Heavy-duty OEMs pilot these in severe-service applications where thermal methods fail and pitot durability collapses.
Thermal Sensing commands the dominant share of wafer allocation, while Ultrasonic Measurement expands most quickly in severe-service niches.
End User:
Procurement concentration among platform-sharing OEM consortia is compressing specification leverage for component suppliers while fragmenting aftermarket demand across retrofit compliance deadlines.
- OEMs:Integrated sensor-to-ECU architectures with multi-year volume guarantees dominate passenger vehicle channel procurement. German OEM consortia specify these modules for shared modular powertrain programs spanning multiple nameplates.
- Aftermarket Providers:Standalone replacement units with plug-and-play calibration target emission recertification-driven replacement cycles. Indian BS-VI compliance deadlines are expanding demand for heavy-duty diesel sensor retrofits through these channels.
- Vehicle Assemblers:Contract manufacturing arrangements for regional market entry require localized sensor sourcing with domestic certification. Assembly operations in emerging markets source these from tier-1 suppliers with regional validation laboratory partnerships.
- Automotive Workshops:Diagnostic-linked sensor replacement with OBD-II verification protocols serves maintenance-driven demand. Euro 7 recalibration requirements are extending service bay sensor replacement frequency for gasoline direct-injection platforms.
OEMs anchor procurement volume, with Aftermarket Providers gaining share fastest on regulatory retrofit cycles.
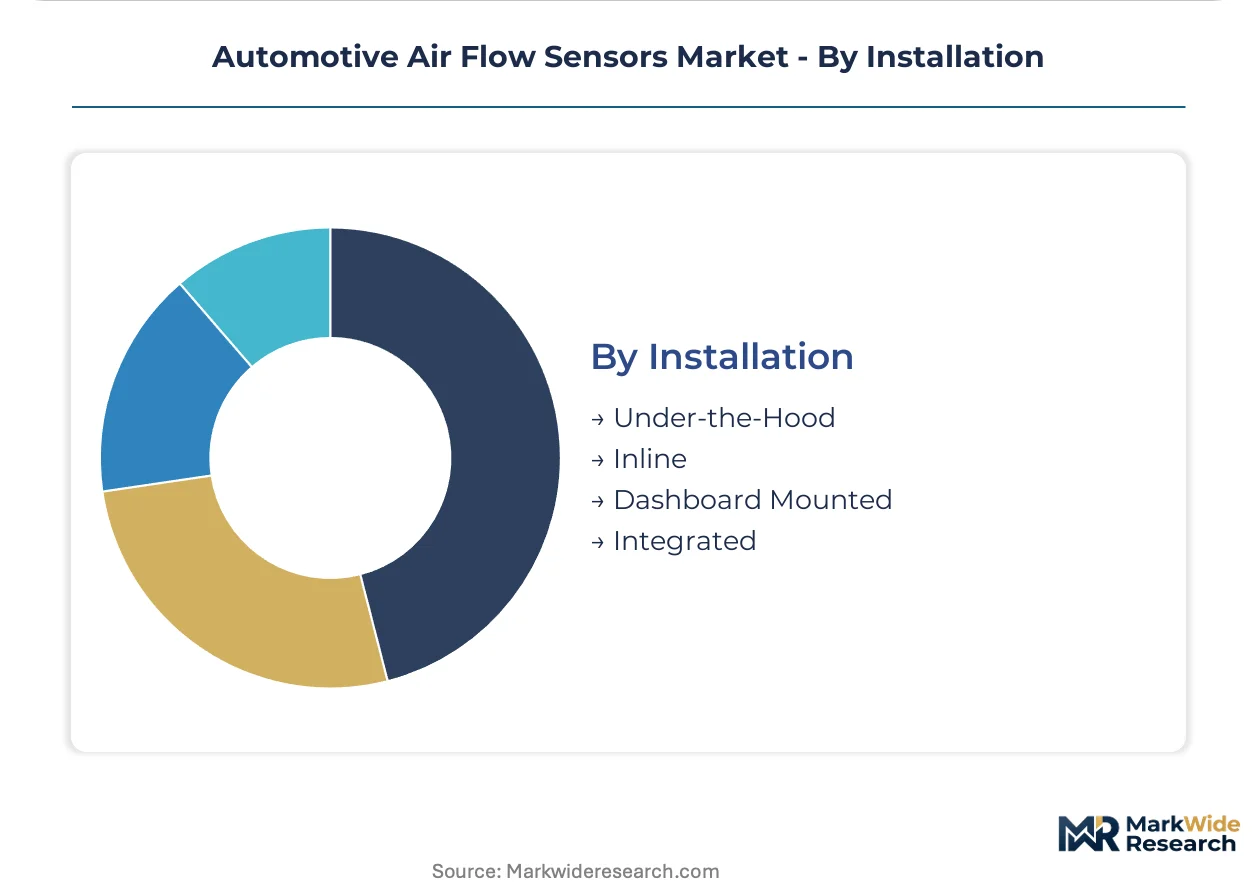
Installation:
Packaging density constraints in electrified powertrains are compressing sensor form factors while thermal management requirements dictate placement proximity to intake manifolds.
- Under-the-Hood:Engine bay mounting exposes sensors to thermal cycling, vibration, and fluid contamination. All gasoline direct-injection platforms require this placement for intake air temperature compensation accuracy.
- Inline:Duct-integrated housings with flanged connections simplify service replacement in commercial vehicle segments. Turbocharged diesel applications specify these for boost pressure monitoring with minimal flow restriction.
- Dashboard Mounted:Cabin air quality sensors with mass flow elements for HVAC control occupy this position. Electric vehicle platforms specify these for battery thermal management air circulation monitoring.
- Integrated:Module-to-ECU architectures with molded interconnect systems eliminate wiring harness junctions. New vehicle platforms from German OEM consortia specify these for assembly automation and warranty cost reduction.
Under-the-Hood retains the largest installed base, with Integrated mounting expanding most rapidly on new platform specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reutlingen anchors European sensor fabrication through Bosch's captive semiconductor campus, while Asian hybrid vehicle programs drive thermal sensing demand across multiple manufacturing clusters.
Germany
Gasoline direct-injection engine recalibration for Euro 7 compliance sustains mass air flow sensor demand from domestic OEMs. The KBA enforces type-approval protocols that compress homologation timelines for engine management suppliers. Stuttgart-Reutlingen corridor hosts Bosch and Continental integrated sensor-to-ECU production serving export powertrain programs.
United States
EPA tailpipe standards and California Air Resources Board waivers create dual certification obligations for sensor suppliers. NHTSA corporate average fuel economy rules sustain OEM specification upgrades for precision air-fuel ratio control. Southeast Michigan clusters around Detroit anchor validation laboratory capacity for simultaneous EPA and state-level homologation.
China
MIIT dual carbon goals and domestic hybrid platform expansion accelerate temperature-compensated thermal sensing procurement. GB standards for particulate emissions tighten combustion precision requirements across gasoline direct-injection fleets. Yangtze River Delta manufacturing bases concentrate domestic sensor assembly for both OEM fitment and aftermarket retrofit channels.
Japan
Thermal sensing designs dominate Asian hybrid vehicle platforms where electric-boost transitions demand sub-15-millisecond response times. METI carbon neutrality roadmaps align with OEM electrification programs specifying precision mass air flow modules. Kanto-Tokyo corridor houses Denso Corporation development centers for temperature-compensated sensor architectures.
India
BS-VI compliance deadlines expand aftermarket sensor replacement demand in heavy-duty diesel commercial vehicles. The CEA coordinates with automotive regulators on emission enforcement timelines that drive retrofit procurement. Maharashtra and Tamil Nadu assembly corridors source localized sensor modules for domestic OEM programs and export manufacturing.
Automotive Air Flow Sensors Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue ultrasonic-piezoelectric convergence for severe-service niches. The supplier base concentrates around integrated module-to-ECU architectures and captive semiconductor fabrication. Three archetypes dominate: vertically integrated German conglomerates with foundry ownership, Asian specialists in hybrid-optimized thermal designs, and diversified electronics suppliers leveraging MEMS scale. Competitive moves center on multi-year wafer allocation contracts and regional validation laboratory partnerships.
Within the integrated-tier archetype, Robert Bosch GmbH exemplifies captive foundry strategy through Reutlingen campus ownership. Denso Corporation occupies a position as Asian hybrid platform anchor. Continental AG represents European OEM consortium integration. These three entities sit within distinct geographic manufacturing clusters while sharing structural reliance on thermal sensing element supply security.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Continental AG |
| BorgWarner Inc. |
| Hitachi Automotive Systems Ltd. |
| HELLA GmbH & Co. KGaA |
| Sensata Technologies Inc. |
| Valeo Group |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
Platinum group metal price indices cascade through hot-film MEMS fabrication costs into three-tier pricing stratification across premium, standard, and economy sensor tiers. German OEM consortia absorb premium-tier premiums for integrated module-to-ECU architectures, while aftermarket channels face compressed margins on standalone replacement units.
Pricing Analysis
Input-cost pass-through from 200mm MEMS wafer pricing volatility stratifies sensor tiers by response-time performance and calibration precision. Premium modules with sub-15-millisecond thermal response command price premiums from gasoline direct-injection platforms facing Euro 7 recertification deadlines. Standard-tier pricing faces compression from silicon substrate cost fluctuations, while economy-tier differential pressure sensors for commercial diesel segments exhibit highest buyer price sensitivity. Certification-grade differentiation—specifically KBA type-approval versus non-validated aftermarket units—drives price spreads between OEM-fitment and retrofit channels.
Supply Chain Analysis
Container freight rate volatility from Asia-Europe corridors adds cost layers to ceramic substrate and platinum-thin-film precursor shipments. Manufacturing concentrates in Germany, China, and Japan, with Bosch's Reutlingen campus anchoring European thermal sensing element supply. Raw material dependencies center on high-purity platinum, aluminum oxide ceramic substrates, and specialized silicone oil fill materials. Single-source vulnerability at the Reutlingen foundry creates regional concentration risk for European OEM programs. Distribution runs through tier-1 supplier direct contracts for OEM channels and fragmented wholesale networks for aftermarket retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in captive foundry ownership and premium-tier integrated architectures, driven by MEMS supply scarcity and emission recertification urgency.
For Market Incumbents: Anticipate ultrasonic-piezoelectric convergence threats in severe-service mining and construction segments by accelerating hot-film durability R&D investments. Lock in multi-year wafer allocation contracts with foundry partners to defend supply security against emerging Asian hybrid-platform specialists. Prioritize backward integration into MEMS fabrication where scale permits, or deepen strategic partnerships with Reutlingen-equivalent facilities in alternate geographies. For New Entrants and Emerging Players: Aftermarket distributors in Indian BS-VI retrofit corridors offer the most penetrable channel for heavy-duty diesel sensor replacement demand. Target ultrasonic measurement pilot programs at mining OEMs seeking pitot-tube alternatives where thermal degradation accelerates sensor failure. Pursue validation laboratory partnerships in Southeast Michigan or Stuttgart-Reutlingen corridors to compress EPA-Euro 7 dual certification timelines for new platform entry. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-2 sensor assemblers possessing regional validation partnerships but lacking captive foundry supply. Long-term viability favors acquisition targets with demonstrated MEMS process engineering talent and existing multi-year OEM volume guarantees. Monitor California Air Resources Board waiver divergence from federal EPA standards as the critical signal for SKU architecture fragmentation versus global single-design consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Investment | Bosch's Reutlingen campus secures wafer supply for European OEM export programs. |
| Ultrasonic-Piezoelectric Development | Heavy-duty OEM pilot programs in mining segments bypass thermal sensor degradation limits. |
| Dual Certification Laboratory Expansion | Simultaneous EPA and Euro 7 homologation capacity reduces time-to-market for new sensor architectures. |
| Aftermarket Channel Partnership | Indian BS-VI compliance deadlines expand retrofit sensor replacement through localized distribution. |
| Integrated Module-to-ECU Architecture | German OEM consortia specify molded interconnect systems for assembly automation and warranty reduction. |
Methodological Framework
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each regional cluster combining OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and emission validation laboratory directors. Secondary sources include vehicle production databases, KBA type-approval registries, EPA certification filings, and MIIT dual carbon policy documentation. Bottom-up sensor shipment triangulation against top-down powertrain production estimates validates volume assumptions.
Granularity-level modeling disaggregates the analysis window by propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from segment-level shipment trajectories weighted by average selling price evolution across thermal, pneumatic, pitot, and ultrasonic technology tiers. Forecast inputs incorporate Euro 7 implementation timing, BS-VI enforcement deadlines, and hybrid platform penetration curves without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEMS foundry capacity expansion, regulatory divergence between California Air Resources Board and federal EPA standards, and ultrasonic technology cost-down curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Child Seats Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Cross Roller Bearings Market