
 Locomotive Drive Shaft Market | 2026-2036
Locomotive Drive Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Drive Shaft Market Foresight
Railway aftermarket distribution is rewriting procurement patterns for locomotive drive shafts. CRRC leverages captive forging capacity to dominate domestic replacement cycles in Asia. Timken sustains technical leadership through precision bearing integration with hollow shaft architectures. Amsted Rail anchors North American freight demand through direct service contracts with Class I railroads.
A locomotive drive shaft transmits torque from the traction motor to the wheelset, typically manufactured from alloy steel forgings heat-treated to withstand torsional loads exceeding 50,000 Nm and rotational speeds up to 3,500 rpm. Flexible shafts capture expanding share in electric locomotives where motor-to-axle misalignment demands greater angular accommodation. Steel retains volume dominance across freight applications, though carbon fiber penetrates premium passenger segments where unsprung mass reduction yields measurable energy savings. OEM procurement concentrates in forging-stage contracts, while aftermarket demand flows through machining and assembly channels.
FRA safety standards govern material fatigue testing and inspection intervals for US freight operators, while China's GB/T rail vehicle component specifications mandate dimensional tolerances for domestic suppliers. The EU's F-Gas Regulation indirectly shapes demand by accelerating electric locomotive deployment, which requires redesigned drive shaft geometries. Stakeholders must track how emerging hydrogen locomotive platforms alter torque transmission requirements and shaft specification thresholds.
Market Dynamics
Freight operators in North America face FRA-mandated reliability thresholds that force systematic replacement of aging drive shaft assemblies before failure, while China's GB/T specifications lock domestic suppliers into dimensional tolerances that reshape competitive entry.
Growth Catalysts
- Composite material substitution:Carbon fiber shafts cut unsprung mass in high-speed passenger applications, delivering measurable energy savings that rail operators quantify in lifecycle cost models.
- FRA safety mandates:US freight reliability standards compress replacement cycles for legacy assemblies, channeling aftermarket demand through certified machining and assembly channels.
- Electric locomotive deployment:The EU's F-Gas Regulation accelerates diesel-to-electric conversions, requiring redesigned shaft geometries that accommodate higher torque densities and motor-to-axle misalignment.
Market Restraints
- Alloy steel price volatility:Nickel and chromium input costs swing with commodity cycles, squeezing forging-stage margins for shaft manufacturers locked into long-term OEM contracts.
- Captive supply concentration:CRRC's domestic forging dominance in China limits third-party access to replacement cycles in the world's largest installed base.
- Technical substitution ceiling:Carbon fiber remains cost-prohibitive for freight applications where impact resistance and repairability outweigh mass reduction benefits.
Strategic Opportunities
- Hydrogen locomotive platforms:Emerging fuel-cell traction systems demand new torque transmission architectures with higher torsional stiffness thresholds and adapted bearing interfaces.
- Flexible shaft architectures:Angular accommodation requirements in electric drivetrains open design space for multi-segment shafts with integrated elastomeric couplings.
- Aftermarket channel consolidation:Direct service contracts with Class I railroads bypass traditional distribution, capturing higher-margin replacement volume through predictive maintenance integration.
Industry Challenges
- Precision forging talent scarcity:Heat-treatment expertise for 50,000 Nm-rated shafts concentrates in aging workforces across US and European supplier bases.
- Certification timeline compression:FRA fatigue testing protocols and China's GB/T dimensional audits extend qualification periods for new shaft designs, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Drive Shaft Market |
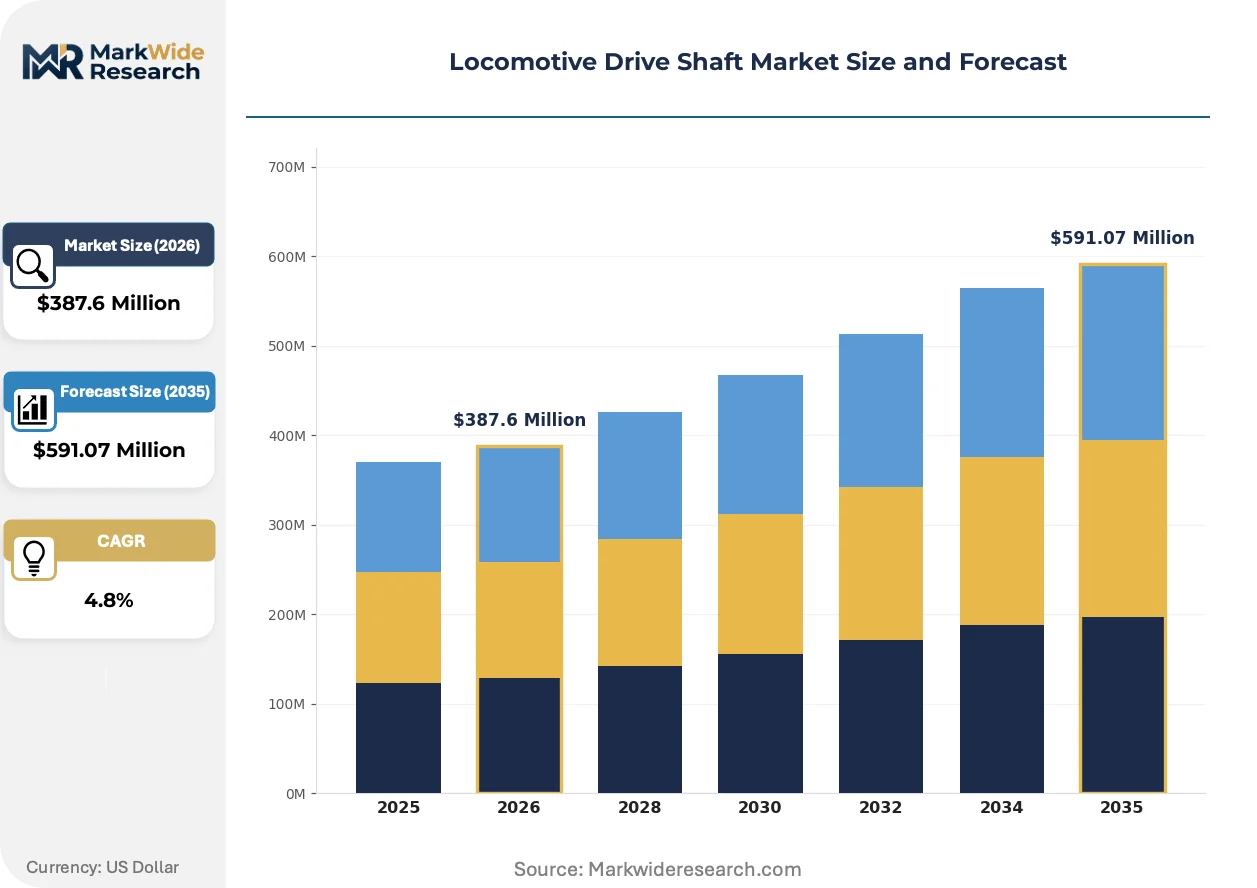
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Shafts, Flexible Shafts, Coupling Shafts, Hollow Shafts Material: Steel, Aluminum, Composite, Carbon Fiber End User: Freight Transport, Passenger Rail, Maintenance Providers, OEMs Manufacturing Stage: Forging, Casting, Machining, Assembly |
| Companies Covered | CRRC, Amsted Rail, Timken, Siemens, Bombardier Transportation, Bharat Forge, Tata Motors, American Axle & Manufacturing, Schaeffler Technologies AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Drive Shaft Market Shifts & Advancements
Digital twin integration is virtualizing how drive shaft performance gets validated before physical prototyping, compressing development cycles while FRA and EU regulatory pressures force material and geometry redesigns simultaneously.
Hollow shaft architectures with integrated bearing races are virtualizing traditional assembly sequences by consolidating multiple components into monolithic forged-and-machined units. Premium passenger operators in Japan and France adopt these designs aggressively. The technology is virtualizing supplier roles by merging forging, heat treatment, and precision finishing into single-source accountability.
The EU's F-Gas Regulation bans hydrofluorocarbon refrigerants in cooling systems, indirectly accelerating electric locomotive procurement that requires redesigned drive shaft geometries. Shaft suppliers must now certify torsional fatigue performance under higher duty cycles. German and French rail OEMs are requalifying supplier bases to meet combined mechanical and environmental compliance thresholds.
Aftermarket procurement now favors lifecycle service agreements over transactional component purchases. North American Class I railroads bundle shaft replacement with predictive monitoring, displacing spot-buy patterns. This shift concentrates supplier relationships around data-sharing capabilities and fleet-specific engineering support rather than catalog sales.
Locomotive Drive Shaft Market Segmentation
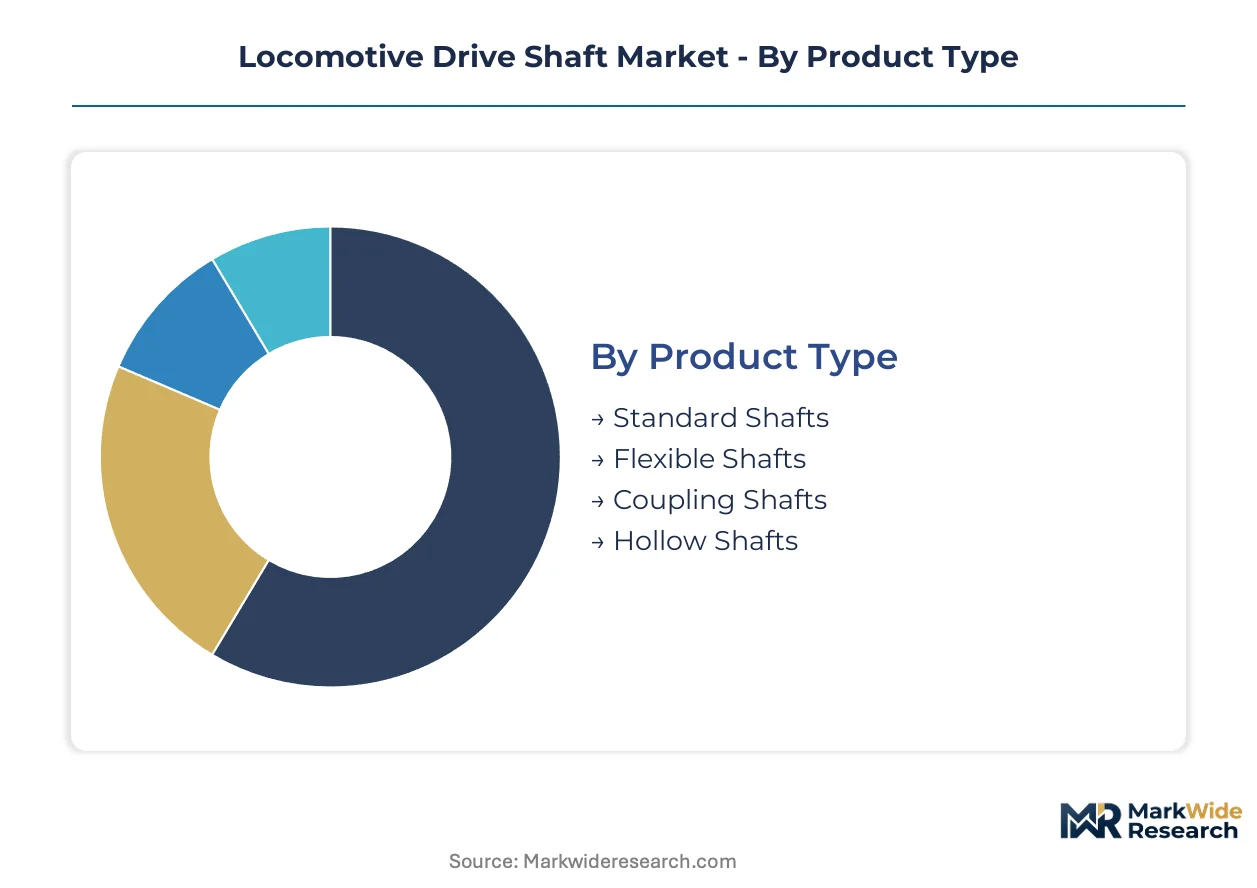
Drive shaft specification varies sharply across traction architectures and duty cycles. Procurement patterns split between OEM forging contracts and aftermarket machining channels. Material selection and end-use requirements create distinct competitive arenas with diverging margin profiles.
Product Type:
Application demands torque capacity, angular accommodation, and mass targets.
- Flexible Shafts:Multi-segment designs with elastomeric couplings accommodate motor-to-axle misalignment in electric locomotives. CRRC and European OEMs specify these for high-torque-density drivetrains where rigid shafts fail. The EU's F-Gas Regulation accelerates diesel-to-electric conversions, expanding specification volume.
- Hollow Shafts:Monolithic forged-and-machined units integrate bearing races directly, eliminating separate assembly steps. Japanese and French high-speed operators specify these for unsprung mass reduction. Heat-treatment expertise for 50,000 Nm ratings concentrates in aging supplier workforces.
- Standard Shafts:Solid alloy steel forgings dominate North American freight replacement cycles under FRA fatigue testing protocols.
- Coupling Shafts:Rigid designs with bolted flange connections serve legacy diesel-electric architectures in emerging markets.
Standard shafts command the established base. The steepest expansion runs through flexible shaft architectures.
Material:
Cost-performance tradeoffs split procurement between proven metallurgy and advanced composites.
- Steel:Alloy forgings heat-treated to withstand torsional loads exceeding 50,000 Nm anchor freight applications. Nickel and chromium input cost volatility squeezes forging-stage margins for manufacturers locked into long-term OEM contracts.
- Carbon Fiber:Wound composite shafts cut unsprung mass by 60-70% versus steel equivalents. Premium passenger operators in Japan and France quantify lifecycle energy savings to justify 4-5x material cost premiums.
- Aluminum:Intermediate density suits regional passenger services where impact resistance requirements moderate.
- Composite:Glass-fiber reinforced polymers penetrate mid-speed applications as a cost-reduced alternative to carbon fiber.
Steel retains volume dominance across freight fleets. Carbon fiber gains share fastest in premium passenger procurement.
End User:
Customer type dictates contract structure, service integration, and technical support intensity.
- Freight Transport:North American Class I railroads bundle shaft replacement with predictive monitoring through direct service agreements. FRA-mandated reliability thresholds compress replacement cycles, channeling demand through certified machining channels.
- Maintenance Providers:Independent shops capture spot-buy volume in deregulated aftermarket segments. Procurement favors lifecycle service agreements over transactional component purchases.
- Passenger Rail:State-owned operators in France and Japan specify hollow shaft architectures with integrated condition monitoring.
- OEMs:Locomotive builders concentrate forging-stage contracts with captive suppliers, particularly CRRC's domestic procurement in China.
Freight operators anchor aftermarket revenue. Passenger rail shows the steepest specification upgrade trajectory.
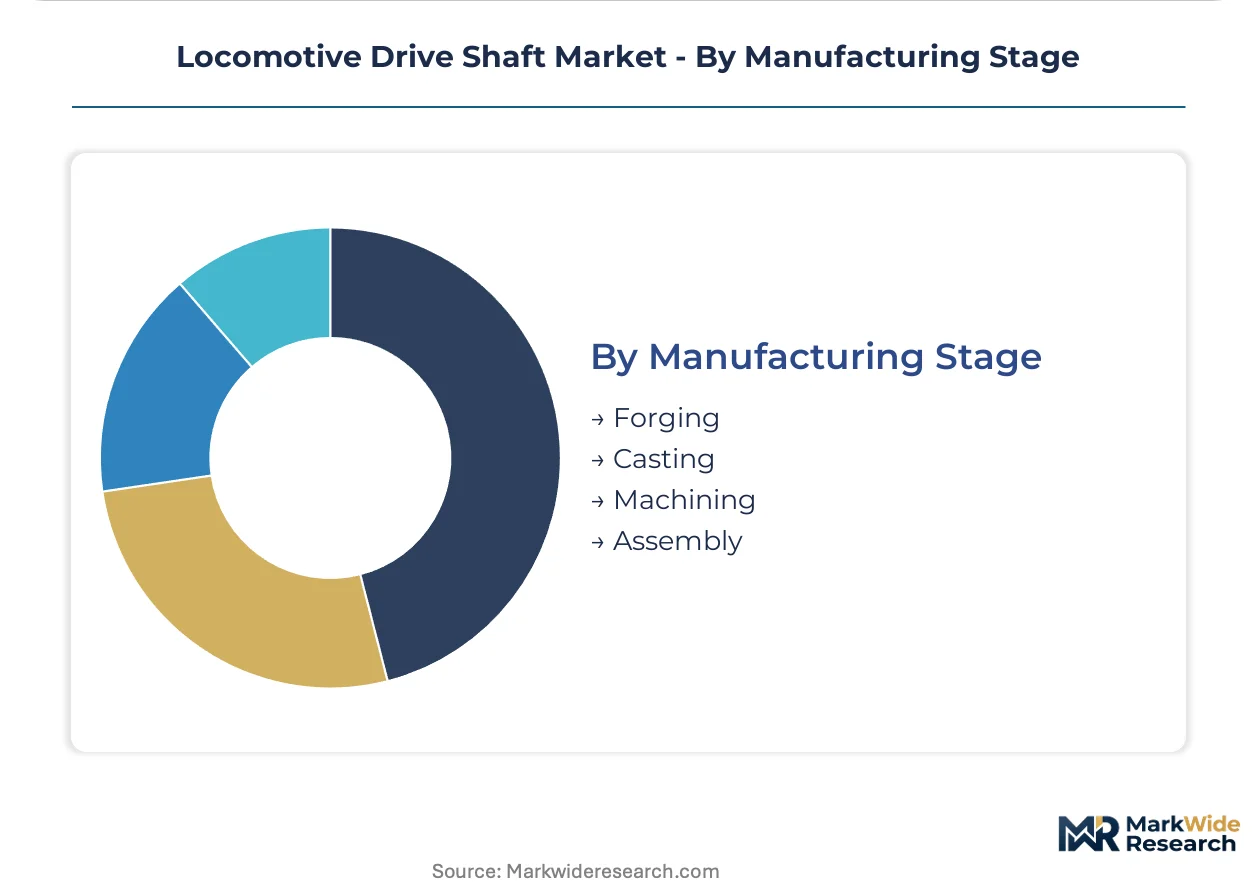
Manufacturing Stage:
Supply chain position determines margin capture and customer access.
- Forging:Heat-treatment and forming of alloy steel billets constitutes the highest-value upstream stage. CRRC leverages captive forging capacity to dominate domestic replacement cycles in China.
- Assembly:Final integration of shafts with bearings, couplings, and protective housings serves aftermarket channels. Timken sustains technical leadership through precision bearing integration with hollow shaft architectures.
- Machining:Precision finishing of forged blanks to GB/T dimensional tolerances reshapes competitive entry in China.
- Casting:Limited to specialized applications requiring complex internal geometries unsuited to forging.
Forging captures the value concentration. Assembly stages expand most quickly through predictive maintenance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FRA's reliability mandates anchor North American demand patterns. China's GB/T specifications lock domestic suppliers into dimensional tolerances that reshape competitive entry. Germany's KBA and France's rail safety regulators drive specification upgrades across European high-speed corridors.
United States
Class I railroads bundle shaft replacement with predictive monitoring through direct service agreements. FRA-mandated fatigue testing protocols compress replacement cycles for legacy assemblies. Chicago and Omaha anchor machining and assembly channels serving the freight aftermarket.
China
CRRC's captive forging capacity dominates domestic procurement volumes and replacement cycles. GB/T rail vehicle component specifications mandate dimensional tolerances that limit third-party supplier access. The Yangtze River Delta concentrates heat-treatment expertise for high-torque-density drivetrains.
Germany
The KBA enforces torsional fatigue performance standards under combined mechanical and environmental compliance thresholds. The EU's F-Gas Regulation accelerates diesel-to-electric conversions requiring redesigned shaft geometries. Bavaria and Baden-Württemberg host requalified supplier bases serving Siemens and Alstom.
Japan
METI drives specification upgrades for hollow shaft architectures with integrated condition monitoring. JIS standards govern precision finishing tolerances for premium passenger applications. The Nagoya industrial corridor concentrates forging-stage contracts for Shinkansen operators.
India
Bharat Forge and Tata Motors leverage domestic alloy steel forging capacity for emerging market diesel-electric platforms. The Railway Board's procurement specifications favor cost-optimized designs over mass-reduction architectures. Pune and Jamshedpur anchor supplier clusters serving regional freight operators.
Locomotive Drive Shaft Market Competitive Landscape
Integrated rail OEMs and specialized component fabricators split the market along captive-versus-independent supply lines. CRRC's vertical control over forging and machining stages creates a closed loop for China's domestic installed base. Three archetypes dominate: state-linked rolling stock builders with captive supply, precision forging specialists serving aftermarket channels, and bearing-integrated subsystem assemblers. Competitive moves concentrate on direct service contract capture with Class I railroads and backward integration into heat-treatment capacity.
Within the state-linked builder tier, CRRC exemplifies captive supply concentration through in-house forging and domestic procurement lock-in. Among precision forging specialists, Bharat Forge occupies a position serving cost-sensitive emerging market demand. At the bearing-integrated end, Timken and Schaeffler Technologies AG & Co. KG represent the convergence of hollow shaft architectures with precision bearing integration, anchoring technical leadership in high-speed passenger specifications.
| Leading Market Players |
|---|
| CRRC |
| Amsted Rail |
| Timken |
| Siemens |
| Bombardier Transportation |
| Bharat Forge |
| Tata Motors |
| American Axle & Manufacturing |
| Schaeffler Technologies AG & Co. KG |
| Others |
Supply & Pricing Matrix
The Chicago-Omaha freight corridor anchors North American aftermarket cost dynamics where FRA-mandated reliability standards compress replacement cycles and amplify price differentiation between certified machining channels and spot-buy alternatives. Supply concentration in China's Yangtze River Delta feeds raw material cost volatility into forging-stage margins while downstream buyers in North America and Europe negotiate lifecycle service bundles that reshape traditional component pricing.
Pricing Analysis
The customization-premium spread separates configured-to-order hollow shaft architectures from standard solid alloy steel forgings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FRA fatigue testing protocols versus uncertified spot-buy alternatives. Cost compression in standard shafts is intensifying because nickel and chromium input volatility squeezes forging-stage margins for manufacturers locked into long-term OEM contracts. Freight operators show highest price sensitivity due to volume scale and direct service contract leverage, while passenger rail operators in Japan and France absorb carbon fiber premiums for unsprung mass reduction.
Supply Chain Analysis
Supplier-financing facilities extended by CRRC and Amsted Rail reshape working capital requirements for machining and assembly channel partners. Geographic supply concentration centers on China, Germany, and the United States where heat-treatment expertise for 50,000 Nm-rated shafts concentrates in aging workforces. Raw material dependencies draw from alloy steel billets, precision bearings, and elastomeric coupling compounds. Single-source vulnerability runs through CRRC's captive forging dominance limiting third-party access to China's replacement cycles. Distribution runs through direct service contracts with Class I railroads displacing traditional aftermarket distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance integration and lifecycle service agreements expand faster than standalone hardware transactions. Aftermarket channel consolidation favors suppliers with data-sharing capabilities and fleet-specific engineering support over catalog-based competitors.
For Market Incumbents: Harden technical leadership through precision bearing integration with hollow shaft architectures as Timken has demonstrated. Deepen backward integration into heat-treatment capacity to defend against precision forging talent scarcity across US and European supplier bases. Capture direct service contracts with Class I railroads before independent maintenance providers consolidate spot-buy volume.
For New Entrants and Emerging Players: India's emerging market diesel-electric platforms present underpenetrated demand where Bharat Forge and Tata Motors have established cost-optimized positioning. Target independent maintenance providers in deregulated aftermarket segments with lifecycle service agreement offerings. Enter through machining-stage specialization serving GB/T dimensional tolerance requirements for Chinese domestic suppliers seeking third-party finishing capacity.
For Investors and Strategic Acquirers: The EU's F-Gas Regulation reshapes the acquisition landscape by accelerating electric locomotive deployment requiring redesigned shaft geometries. Five-to-ten year viability favors precision forging specialists with heat-treatment expertise and bearing-integrated subsystem assemblers serving high-speed passenger specifications. Monitor hydrogen locomotive platform development timelines as the signal for torque transmission architecture inflection. Macroeconomic, regulatory, or technological deviation would prompt revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Capacity | Captures margin concentration upstream while addressing precision forging talent scarcity in US and European supplier bases. |
| Direct Service Contract Capture | Bypasses traditional distribution channels to secure higher-margin replacement volume through predictive maintenance integration with Class I railroads. |
| Hydrogen Locomotive Platform Development | Positions suppliers for emerging fuel-cell traction systems demanding new torque transmission architectures with adapted bearing interfaces. |
| Flexible Shaft Architecture Certification | Opens design space for multi-segment shafts with elastomeric couplings serving EU F-Gas Regulation-accelerated electric conversions. |
| Aftermarket Channel Consolidation | Concentrates supplier relationships around data-sharing capabilities and fleet-specific engineering support rather than transactional catalog sales. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with rail industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews included maintenance directors at North American Class I railroads, OEM procurement teams at CRRC and Siemens, aftermarket service heads at Timken and Amsted Rail, and plant engineers at Bharat Forge facilities. Secondary sources encompassed FRA safety filings, China's GB/T rail vehicle component specifications, EU F-Gas Regulation compliance disclosures, customs trade data for alloy steel forgings, and SEC filings from listed rail component suppliers. Bottom-up segmentation modeling triangulated against top-down market sizing from industry association production data.
Forecast inputs considered traction architecture transitions, material substitution trajectories, and regulatory compliance timelines across the analysis window. Segmentation dimensions modeled include product type, material grade, end-user category, and manufacturing stage position. CAGRs derived from installed base replacement cycle analysis, OEM procurement volume projections, and aftermarket channel shift assumptions. Electric locomotive deployment rates under EU environmental regulations and hydrogen platform development milestones served as industry-specific demand drivers.
Practitioners should monitor alloy steel commodity price volatility, FRA fatigue testing protocol amendments, and CRRC domestic procurement policy shifts for early signals of forecast deviation. The analysis reflects assumptions about replacement cycle compression, certification timeline stability, and competitive entry barriers in China's GB/T-governed market. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Navigation Light Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Idler Arm Market
Vehicle Components
Snowplows Market
Vehicle Components
EGR Valve Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Car Radiator Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Bicycle Frames Market