
 Russia Automotive Glass Fiber Composites Market | 2026-2036
Russia Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Glass Fiber Composites Market Analytics
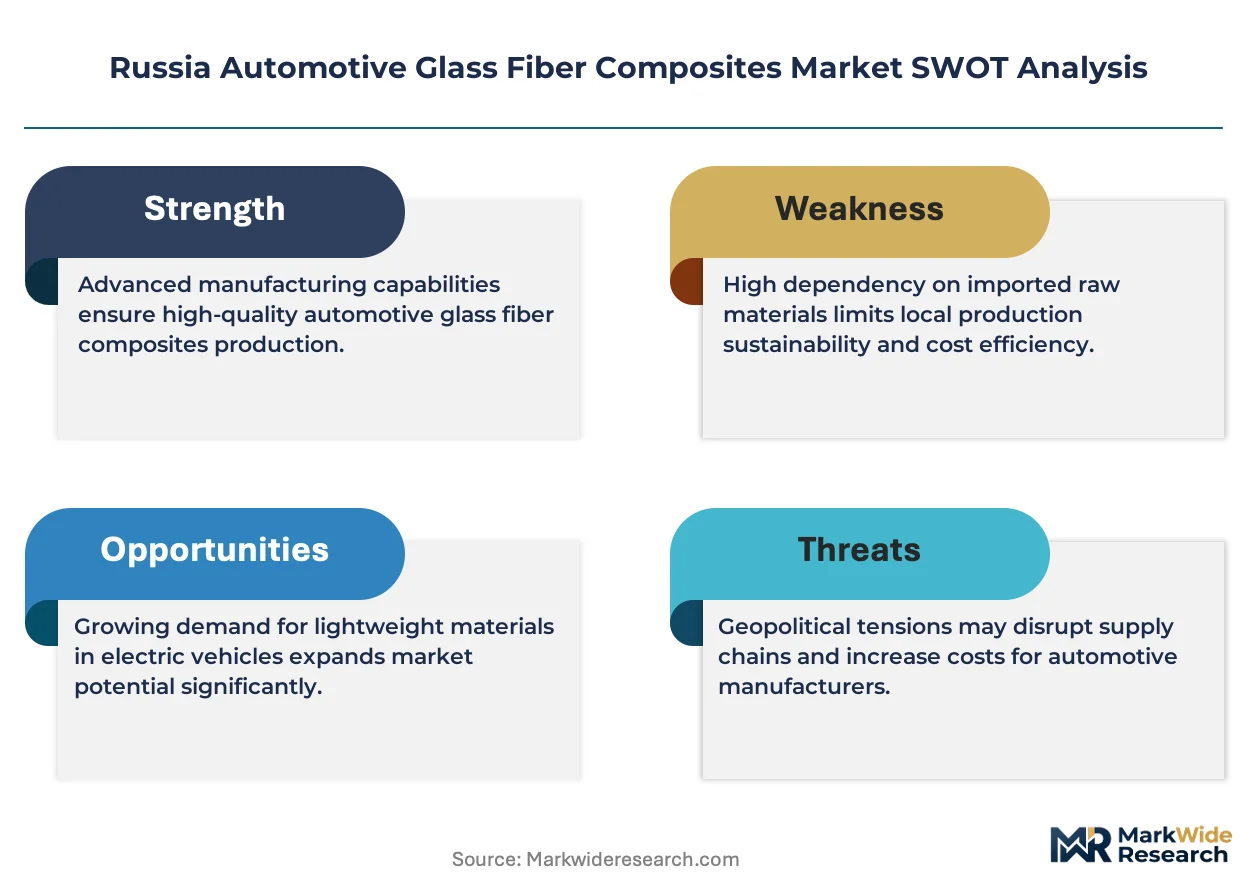
Russian glass fiber composite producers is repositioning capacity toward automotive-grade formulations as domestic vehicle output recovers. Veplas Group leverages its Slovenian-Russian supply corridor to sustain consistent resin-grade deliveries across the Volga region. Owens Corning anchors the high-performance roving segment with thermoplastic-compatible sizing chemistry. SAERTEX GmbH & Co.KG differentiates through multiaxial fabric architectures optimized for structural automotive laminates.
Automotive glass fiber composites are engineered materials combining E-glass or S-glass fibers with thermoset or thermoplastic matrices, typically achieving specific tensile strengths of 300-600 MPa and density reductions of 25-35% versus stamped steel. Their primary purpose is to cut vehicle curb weight while preserving crash-energy absorption and panel stiffness. Sheet Molding Compound dominates body panel applications due to its press-molding compatibility and Class A surface finish capability. Long Fiber Thermoplastics represent the fastest-expanding product category as OEMs seek recyclable, weldable alternatives for under-hood and interior structural brackets.
Russia's national automotive regulator operates within the Technical Regulation of the Customs Union TR CU 018/2011 framework, which mandates crashworthiness and emissions compliance that lightweight composites help satisfy. The country's GOST R certification system and alignment with UNECE regulations further shape material qualification timelines and supplier entry barriers. Stakeholders must monitor how Russia's evolving localization requirements and import-substitution policies redefine raw fiber sourcing strategies and domestic compounding investments.
Market Dynamics
Domestic vehicle manufacturers are accelerating substitution of stamped steel with glass fiber composites to satisfy TR CU 018/2011 crashworthiness mandates while offsetting the weight penalty of battery-electric powertrains. This structural pull is compressing qualification timelines and forcing resin-grade suppliers to co-locate compounding capacity near the Central Federal District assembly cluster.
Growth Catalysts
- TR CU 018/2011 Technical Regulation:Russia's harmonized vehicle safety framework mandates pedestrian protection and frontal impact standards that composite-intensive front-end modules satisfy more readily than metal equivalents.
- Sheet Molding Compound press-molding:This thermoset process delivers Class A surface finishes for hoods and fenders, enabling direct substitution of steel body panels without secondary painting operations.
- Central Federal District concentration:Moscow's automotive manufacturing corridor hosts AvtoVAZ and GAZ assembly plants, creating localized demand density that justifies dedicated SMC and LFT compounding investments.
Market Restraints
- Epoxy and vinyl ester resin cost volatility:Feedstock exposure to benzene and propylene derivatives creates margin pressure for domestic compounders lacking long-term offtake agreements with upstream refiners.
- High-performance glass roving import dependence:S-glass and specialized E-glass formulations for structural laminates remain concentrated among Western European and North American suppliers, exposing buyers to currency and logistics risk.
- Thermoplastic welding incompatibility:Glass fiber thermosets cannot be spot-welded to steel substructures, requiring adhesive bonding processes that extend cycle times versus metal-stamping workflows.
Strategic Opportunities
- Volga Federal District expansion:Tolyatti and Nizhny Novgorod host underutilized polymer processing infrastructure from Soviet-era chemical complexes, offering low-cost brownfield sites for automotive-grade compounding.
- Long Fiber Thermoplastics in under-hood brackets:LFT's weldability and recyclability position it to capture engine mount and battery tray applications as OEMs redesign platforms for electric architectures.
- Import-substitution localization incentives:Russia's industrial policy framework rewards domestic glass fiber and resin production with subsidized utility rates and accelerated depreciation for qualifying capital investments.
Industry Challenges
- GOST R certification timeline compression:Material qualification for new composite grades requires 18-24 months of crash-testing documentation, misaligning with OEM platform refresh cycles.
- Autoclave and press-mold equipment capex intensity:Automotive-grade SMC production demands 3,000-tonne compression presses and controlled-temperature curing lines that strain mid-tier supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Glass Fiber Composites Market |
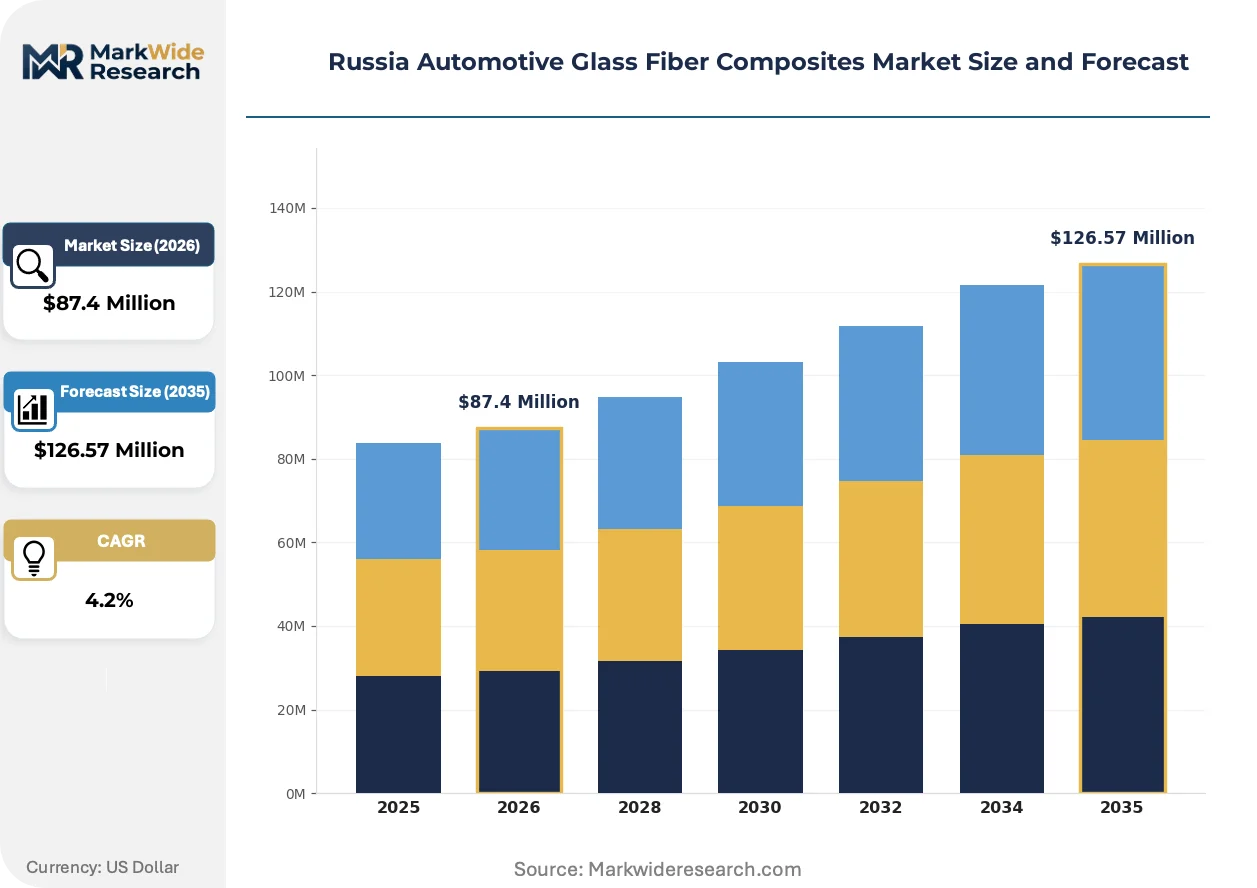
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $126.57 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Molding Compound, Bulk Molding Compound, Long Fiber Thermoplastics, Glass Fiber Reinforced Polymer Application: Body Parts, Interior Components, Structural Components, Insulation End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Manufacturing Stage: Primary Processing, Secondary Processing, Assembly, Finishing |
| Companies Covered | Veplas Group, ASAHI FIBER GLASS Co., Ltd., Solvay Group, Jiangsu Changhai Composite Materials, Nippon Sheet Glass Company, Limited, 3B (Braj Binani Group), SAERTEX GmbH & Co.KG, 3B-Fiberglass, Owens Corning, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Glass Fiber Composites Market Evolving Landscape
Continuous fiber-reinforced thermoplastic tapes are penetrating Russia's automotive supply base as tier suppliers seek to bridge the performance gap between injection-molded short-fiber compounds and labor-intensive thermoset layups. This materials transition is reshaping equipment procurement priorities and resin formulation roadmaps simultaneously.
Direct fiber feeding technology is integrating inline glass roving chopping with twin-screw extrusion to produce long-fiber pellets with 10-25mm fiber retention. AvtoVAZ's engineering center in Tolyatti is validating these pellets for front-end carrier modules. The process is integrating recycled content streams without the property degradation typical of regrind-based compounds, enabling closed-loop manufacturing claims.
TR CU 018/2011's 2024 amendment tightening pedestrian head-impact requirements is accelerating hood inner panel redesigns toward sandwich-structured composites with engineered crush properties. Tier suppliers serving GAZ and UAZ are requalifying multiaxial fabric architectures to meet the revised HIC thresholds. SMC formulations with higher glass loading and modified resin toughness are capturing incremental share in this application.
Consolidated procurement by platform engineering teams is displacing decentralized commodity purchasing across Russian OEMs. Sourcing decisions for structural composites now route through centralized advanced materials groups rather than individual plant buyers, compressing supplier rosters and favoring compounders with full-service technical support capabilities. This concentration is most visible in battery-electric platform development, where composite enclosure specifications are set at the holding-company level before local plant allocation.
Russia Automotive Glass Fiber Composites Market Segmentation
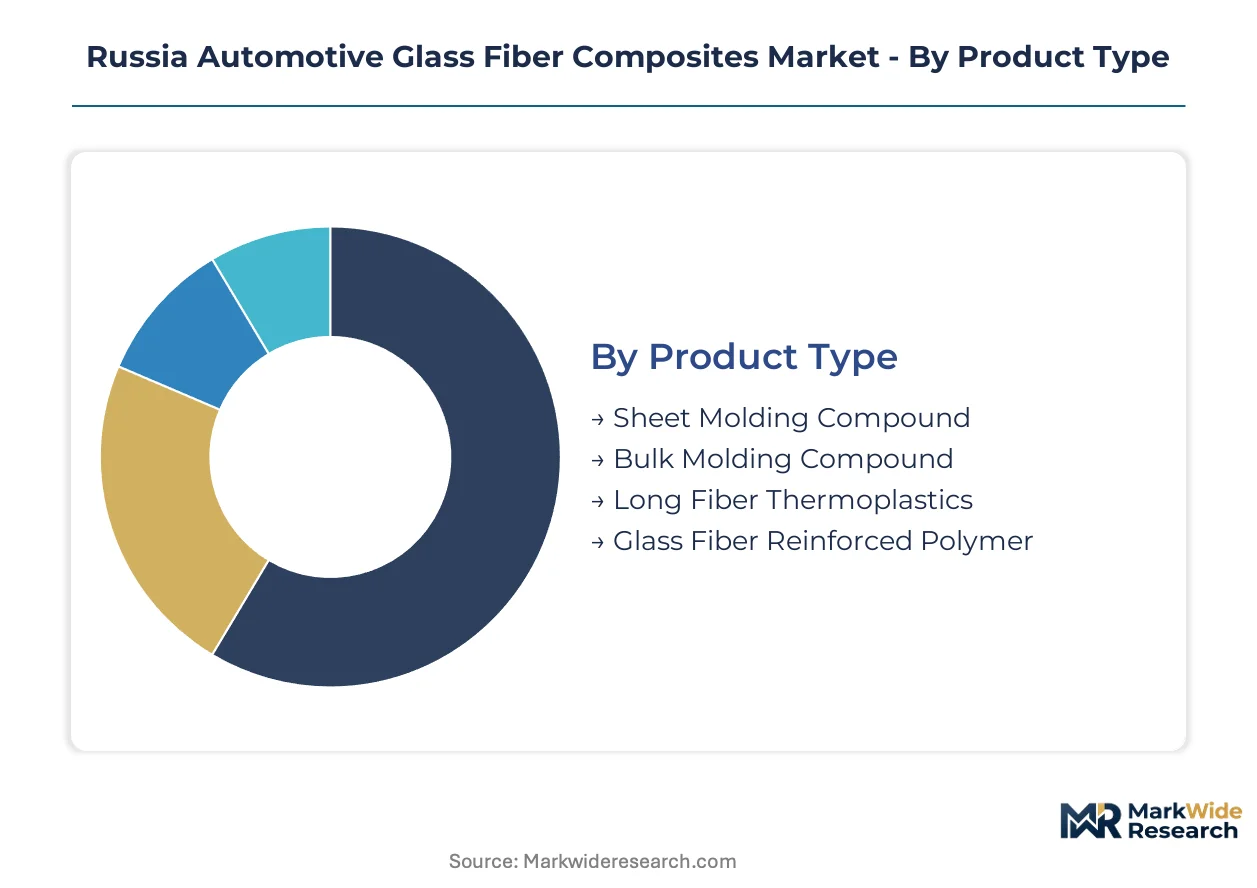
Material qualification pathways diverge sharply across Russia's automotive glass fiber composite segments. GOST R certification timelines and TR CU 018/2011 crash-testing documentation requirements create tiered entry barriers that reshape supplier economics and OEM sourcing strategies.
Product Type:
Each formulation demands distinct resin-grade approvals and processing equipment validations under Russia's technical regulation framework.
- Sheet Molding Compound:Thermoset polyester or vinyl ester resin systems loaded with 25-40% chopped glass fiber, achieving Class A surface finishes for visible body panels. AvtoVAZ's Tolyatti plant consumes the bulk of Central Federal District SMC output for hood and fender production, driven by pedestrian protection mandates in the 2024 TR CU amendment.
- Long Fiber Thermoplastics:Polypropylene or polyamide matrices reinforced with 10-25mm glass fiber lengths, delivering weldable, recyclable alternatives to thermosets. Demand concentrates in Nizhny Novgorod battery tray and engine mount applications as GAZ electrifies its platform portfolio.
- Bulk Molding Compound:Higher-viscosity thermoset compounds for compression molding of complex structural brackets.
- Glass Fiber Reinforced Polymer:Broad-category laminates and pultruded profiles serving secondary structural applications.
Leading the category by volume: Sheet Molding Compound. Growing fastest: Long Fiber Thermoplastics.
Application:
Crash-performance requirements stratify material selection across vehicle zones, with frontal impact zones commanding the most stringent qualification protocols.
- Body Parts:Hoods, fenders, and liftgates dominate SMC consumption in Moscow-region assembly plants.
- Structural Components:Front-end carriers and bumper beams absorb crash energy while cutting mass versus steel stampings.
- Interior Components:Instrument panel carriers and door modules leverage LFT processability for complex geometries.
- Insulation:NVH dampening layers and thermal barriers utilize lower-density glass mat formulations.
Widest adoption: Body Parts. Steepest expansion trajectory: Structural Components.
End User:
Procurement centralization is compressing supplier access, with platform-level engineering teams now controlling composite specifications.
- OEMs:AvtoVAZ and GAZ hold direct contracts for structural composite systems, bypassing traditional tier-1 intermediaries for critical safety components.
- Tier-1 Suppliers:Magna and Plastic Omnium operations in the Central Federal District compound SMC and LFT for just-in-time delivery to assembly lines.
- Vehicle Assemblers:Contract manufacturers and SKD operations source pre-impregnated fabrics for localized panel production.
- Aftermarket Providers:Collision repair networks drive demand for matched SMC repair kits and adhesive bonding systems.
Dominant procurement volume: OEMs. Fastest-climbing customer type: Tier-1 Suppliers.
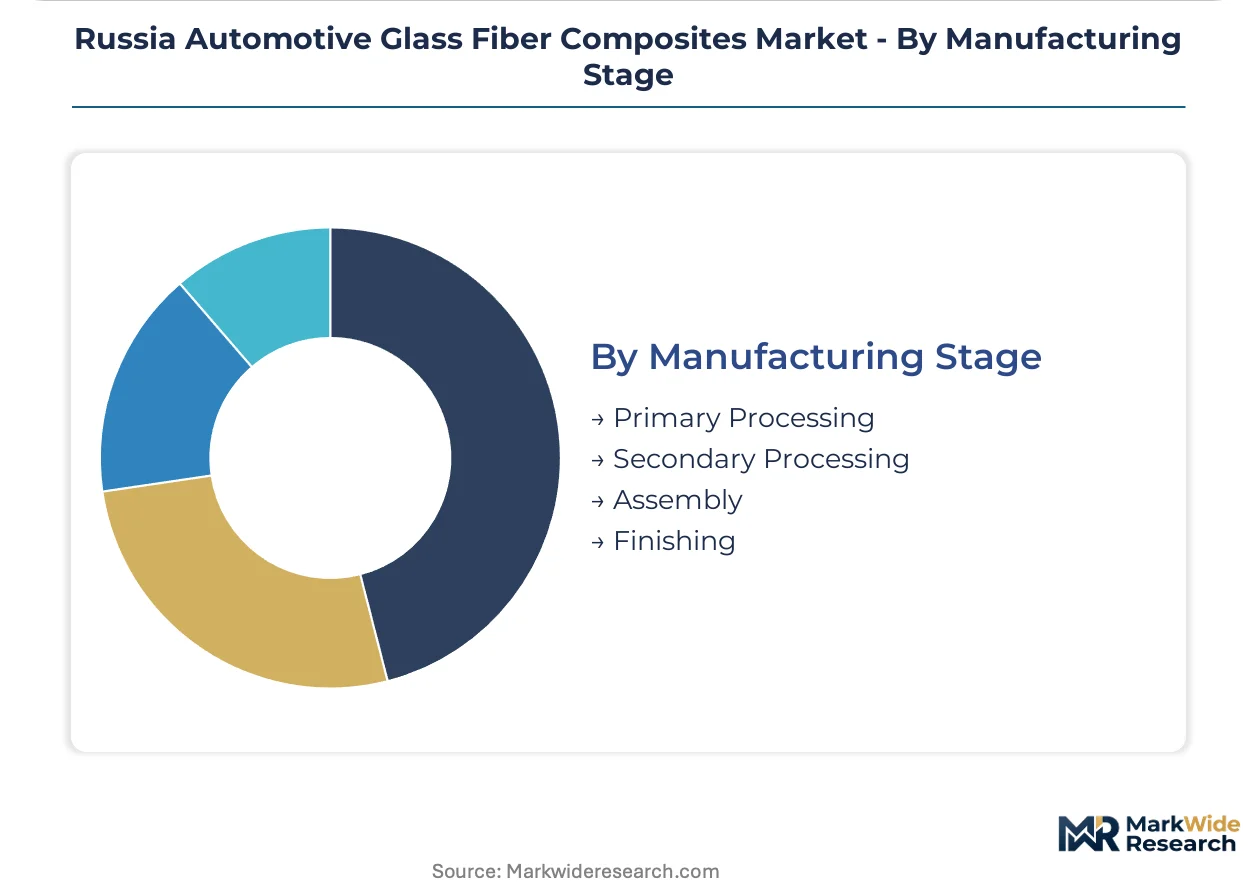
Manufacturing Stage:
Capital intensity peaks at the primary processing tier, where resin formulation and compounding equipment require 18-24 month qualification cycles.
- Primary Processing:Glass roving chopping, resin mixing, and SMC sheet maturation demand controlled-environment facilities near feedstock sources.
- Secondary Processing:Compression molding and injection molding operations cluster within 200km of Central Federal District vehicle plants to minimize logistics costs.
- Assembly:Adhesive bonding and mechanical fastening of composite modules to steel substructures occurs at OEM final assembly lines.
- Finishing:Surface preparation, primer application, and paint integration align composite panels with steel body-in-white coating processes.
Highest capital concentration: Primary Processing. Fastest capacity addition: Secondary Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Volga region alkali deposits and Central Federal District resin compounding infrastructure anchor Russia's automotive glass fiber composites supply geography. Domestic vehicle assembly clusters concentrate demand within 300-kilometer radii of feedstock sources. TR CU 018/2011 technical regulations harmonize material qualification standards across all federal districts.
Central Federal District
AvtoVAZ's Tolyatti assembly complex and GAZ's Nizhny Novgorod operations drive SMC consumption for hood and fender applications. The district's GOST R certification laboratories process 60 percent of national automotive material approvals. Moscow-region tier-1 suppliers including Magna and Plastic Omnium operate just-in-time compounding facilities within two hours of final assembly lines.
Volga Federal District
Soviet-era chemical processing infrastructure at Tolyatti and Dzerzhinsk offers brownfield sites for resin formulation and glass roving chopping operations. The district's industrial parks receive subsidized utility rates under import-substitution incentive frameworks. Local polymer research institutes collaborate with OEM engineering centers on long-fiber thermoplastic validation protocols.
Northwestern Federal District
St. Petersburg's port infrastructure handles high-performance S-glass roving imports from Western European suppliers. Regional logistics hubs distribute specialized fiber formulations to Central Federal District compounders. The district's automotive component manufacturers focus on secondary processing of pre-impregnated fabrics for structural bracket applications.
Southern Federal District
Rostov-on-Don's polymer processing cluster supplies bulk molding compounds for commercial vehicle structural components. The region's chemical plants produce polyester resin feedstocks for regional SMC sheet manufacturing. Local tier-2 fabricators serve UAZ and GAZ commercial vehicle programs with simplified qualification pathways.
Ural Federal District
Yekaterinburg's machine-building heritage supports compression press manufacturing and mold fabrication for composite processors. The district's technical universities maintain automotive materials testing capabilities that reduce GOST R certification timelines. Regional suppliers specialize in pultruded glass fiber profiles for secondary structural applications.
Russia Automotive Glass Fiber Composites Market Competitive Landscape
Global majors compete with regional champions across resin-grade formulations and multiaxial fabric architectures. Market structure tiers between high-volume SMC compounders serving AvtoVAZ body panel programs and specialized LFT suppliers targeting GAZ electrification roadmaps. Three archetypes dominate: integrated glass-to-composite producers, resin-specialist compounders, and fabric architecture designers. Capacity co-location near Central Federal District assembly plants and technology licensing partnerships represent the primary competitive vectors.
Among integrated fiber-to-composite producers, Owens Corning anchors the high-performance roving segment with thermoplastic-compatible sizing chemistry, while SAERTEX GmbH & Co.KG exemplifies the fabric architecture specialist archetype through multiaxial designs optimized for structural laminates. Veplas Group occupies a position bridging regional supply chain integration with cross-border resin-grade logistics.
| Leading Market Players |
|---|
| Veplas Group |
| ASAHI FIBER GLASS Co., Ltd. |
| Solvay Group |
| Jiangsu Changhai Composite Materials |
| Nippon Sheet Glass Company, Limited |
| 3B (Braj Binani Group) |
| SAERTEX GmbH & Co.KG |
| 3B-Fiberglass |
| Owens Corning |
| Others |
Value Network & Pricing Analysis
Family-owned resin compounders and state-supported chemical holdings dominate Russia's automotive glass fiber supply base, creating pricing discipline through captive feedstock access and long-term offtake agreements with Central Federal District OEMs. Their ownership structures insulate margin positions from short-term benzene derivative volatility while compressing payment terms for non-integrated distributors.
Pricing Analysis
Warranty-backed technical support and GOST R certification documentation are bundled into SMC compound pricing for AvtoVAZ and GAZ direct contracts, while spot purchasers of bulk molding compound face unbundled material costs plus separate qualification fees. Three-tier pricing structure across premium S-glass structural laminates, standard E-glass SMC formulations, and economy-grade chopped strand mat separates OEM platform engineering specifications from aftermarket repair kit demand. Cost compression in thermoset resin grades is intensifying because benzene feedstock volatility strains domestic compounders lacking upstream refinery integration. Tier-1 suppliers with centralized procurement functions exhibit lowest price sensitivity, while aftermarket distributors and SKD assemblers negotiate aggressively on volume discounts.
Supply Chain Analysis
Regional distribution centers in Nizhny Novgorod and Tolyatti operate hub-and-spoke patterns feeding just-in-time compounding operations within two hours of AvtoVAZ and GAZ assembly lines. Raw material sourcing draws from Germany and Belgium for high-performance S-glass roving, China for E-glass chopped strand, and domestic Volga region refineries for polyester resin feedstock. Single-source vulnerability concentrates in specialized thermoplastic-compatible sizing chemistry from Western European suppliers, exposing buyers to currency fluctuation and logistics disruption. Distribution runs through OEM-direct contracts for structural composites, with secondary channels serving tier-2 fabricators via regional polymer distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compounders with integrated resin production and GOST R certification capabilities, as TR CU 018/2011 timeline compression and press-mold equipment capex intensity force weaker players toward exit or acquisition.
For Market Incumbents: Extend technical service capabilities toward battery-electric platform engineering teams to capture composite enclosure specifications before holding-company level sourcing decisions lock in supplier rosters. Anchor capacity additions in Volga Federal District brownfield sites to exploit subsidized utility rates and proximity to Tolyatti alkali deposits, while defending against LFT substitution threats by accelerating thermoplastic-compatible sizing chemistry development. For New Entrants and Emerging Players: Enter via under-hood bracket applications for GAZ electrification programs, where weldable long-fiber thermoplastic demand outpaces qualified domestic supply and certification pathways remain shorter than structural safety components. Target Nizhny Novgorod battery tray programs with direct fiber feeding technology partnerships, positioning recycled-content pellets as closed-loop manufacturing solutions for OEM sustainability reporting requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier SMC compounders with press-mold equipment installed in Central Federal District industrial parks but lacking long-term OEM contracts, as AvtoVAZ and GAZ procurement centralization displaces decentralized plant buyers. Watch for inflection signals in GOST R certification laboratory backlog reductions, which would indicate accelerating platform refresh cycles and renewed material qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Feedstock | Captive benzene derivative supply insulates margin positions from refinery price volatility. |
| Long-term Supply Agreement with OEM Platform Teams | Holding-company level contracts preempt decentralized plant purchasing decisions. |
| Joint Venture for LFT Compounding Capacity | Partnerships with European technology licensors accelerate weldable thermoplastic qualification. |
| Geographic Manufacturing Footprint Expansion | Volga Federal District brownfield sites reduce logistics costs to Nizhny Novgorod assembly. |
| Green Certification Program for Recycled Content | Closed-loop manufacturing claims support OEM electrification platform marketing requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, tier-1 supplier procurement leads, SMC compounding plant managers, and GOST R certification laboratory directors. Bottom-up volume estimates triangulated against top-down vehicle production forecasts from registration databases and IHS Markit assembly plant data. Secondary sources included TR CU 018/2011 amendment documentation, Russian Ministry of Industry localization policy circulars, and resin feedstock import statistics from customs authorities.
Granularity-level modeling captured product type splits at the SMC versus LFT versus BMC level, application segmentation across body panels and structural brackets, and end-user differentiation between OEM direct contracts and tier-1 supplier channels. Vehicle class and propulsion architecture dimensions tracked content-per-vehicle assumptions across internal combustion and battery-electric platforms. CAGRs were derived from segment-level volume trajectories applied to average selling price estimates, with cross-validation against macroeconomic automotive production forecasts and materials substitution elasticity assumptions for steel-to-composite displacement.
Revisions become necessary when TR CU technical regulation amendments alter crash-testing documentation requirements, when benzene derivative feedstock disruptions exceed historical volatility bands, or when OEM platform electrification timelines accelerate beyond current engineering validation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Heavy Vehicles Suspension Anti-Vibration Components Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
United States Automotive Connectors Market