
 Global Undercarriage Components Market | 2026-2036
Global Undercarriage Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Undercarriage Components Market Outlook
Market Context
Capital-intensity divergence between integrated foundry operators and assembly-focused distributors is bifurcating competitive returns across the undercarriage supply base. Caterpillar Inc. leverages captive steel casting capacity to control idler and roller cost positions across North American mines. Komatsu Ltd. anchors its aftermarket revenue through proprietary KOMTRAX-linked wear monitoring that preempts failure-driven downtime. ThyssenKrupp AG competes on forged alloy expertise, supplying high-load bushings to European OEMs that reject standard cast alternatives.
Technical Definition and Segment Structure
Global undercarriage components encompass the track-propulsion subsystem of tracked heavy equipment, comprising track rollers, sprockets, idlers, and bushings—typically fabricated from through-hardened steel or boron-modified alloys and heat-treated to 50-55 HRC to withstand cyclic impact loads in abrasive terrain. These assemblies translate engine torque to ground traction while distributing machine weight across uneven surfaces, making them consumable determinants of equipment uptime in construction, mining, and forestry operations. Track rollers and idlers command the deepest replacement demand pools due to direct ground contact and sealed-lubrication failure modes, whereas sprocket sales concentrate in mining applications where tooth engagement stresses accelerate wear. Alloy material grades are displacing conventional carbon steel in high-hour contracts, particularly for bulldozer and large excavator fleets where downtime costs dwarf premium component pricing.
Regulatory Frame and Outlook
EPA Tier 4 Final and EU Stage V emissions frameworks are compressing undercarriage design envelopes, forcing mass reduction through hollow-profile idlers and reduced-section bushings without sacrificing fatigue life. China's MIIT equipment certification and India's CEA construction machinery standards are tightening dimensional tolerances for imported track systems, raising compliance costs for non-integrated suppliers. Japan's METI energy-efficiency benchmarks for off-road equipment are propagating through Komatsu and Hitachi supply chains, favoring low-friction seal technologies. Stakeholders must monitor how alloy price volatility and regional carbon-border adjustments reshape make-versus-buy decisions for forged versus cast component sourcing.
Market Dynamics
Mass reduction mandates under EPA Tier 4 Final and EU Stage V are compressing undercarriage design envelopes, forcing hollow-profile geometries and boron-modified alloys that trade weight for fatigue resistance without sacrificing load capacity.
Growth Catalysts
- Mining fleet replacement cycles:Australian and Chilean operators are extending track roller and idler replacement intervals on large excavators, creating sustained aftermarket demand pools for hardened steel components.
- EPA Tier 4 Final compliance:Emissions frameworks are accelerating adoption of lighter alloy designs across North American construction equipment, pulling forward R&D investment in hollow-profile idlers.
- China's equipment rebuild sector:Domestic demand concentrates in construction machinery refurbishment, driving consumption of replacement track systems and sealed-lubrication assemblies.
Market Restraints
- Alloy price volatility:Boron and molybdenum input costs swing unpredictably, squeezing margins for non-integrated foundry operators lacking captive steel casting capacity.
- Supply concentration in integrated OEMs:Captive casting operations at major equipment manufacturers lock out independent distributors from high-volume mining contracts.
- EU Stage V certification friction:Dimensional tolerance requirements for imported track systems raise compliance costs for Asian suppliers serving European rebuild markets.
Strategic Opportunities
- India's CEA construction machinery standards:Tightening certification requirements create entry barriers that favor suppliers with pre-certified alloy grades and heat-treatment documentation.
- Telematics-linked wear monitoring:Integration of IoT sensors with undercarriage components enables predictive maintenance contracts, shifting revenue from part sales to uptime guarantees.
- Japan's METI energy-efficiency benchmarks:Low-friction seal technologies favored in domestic supply chains offer export potential to Southeast Asian equipment assemblers.
Industry Challenges
- Heat-treatment skill scarcity:Through-hardening to 50-55 HRC requires specialized furnace operators, creating bottlenecks for foundries scaling boron-modified alloy production.
- Legacy equipment compatibility:Retrofitting hollow-profile idlers to older excavator frames demands custom adapter fabrication, complicating inventory planning for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Undercarriage Components Market |
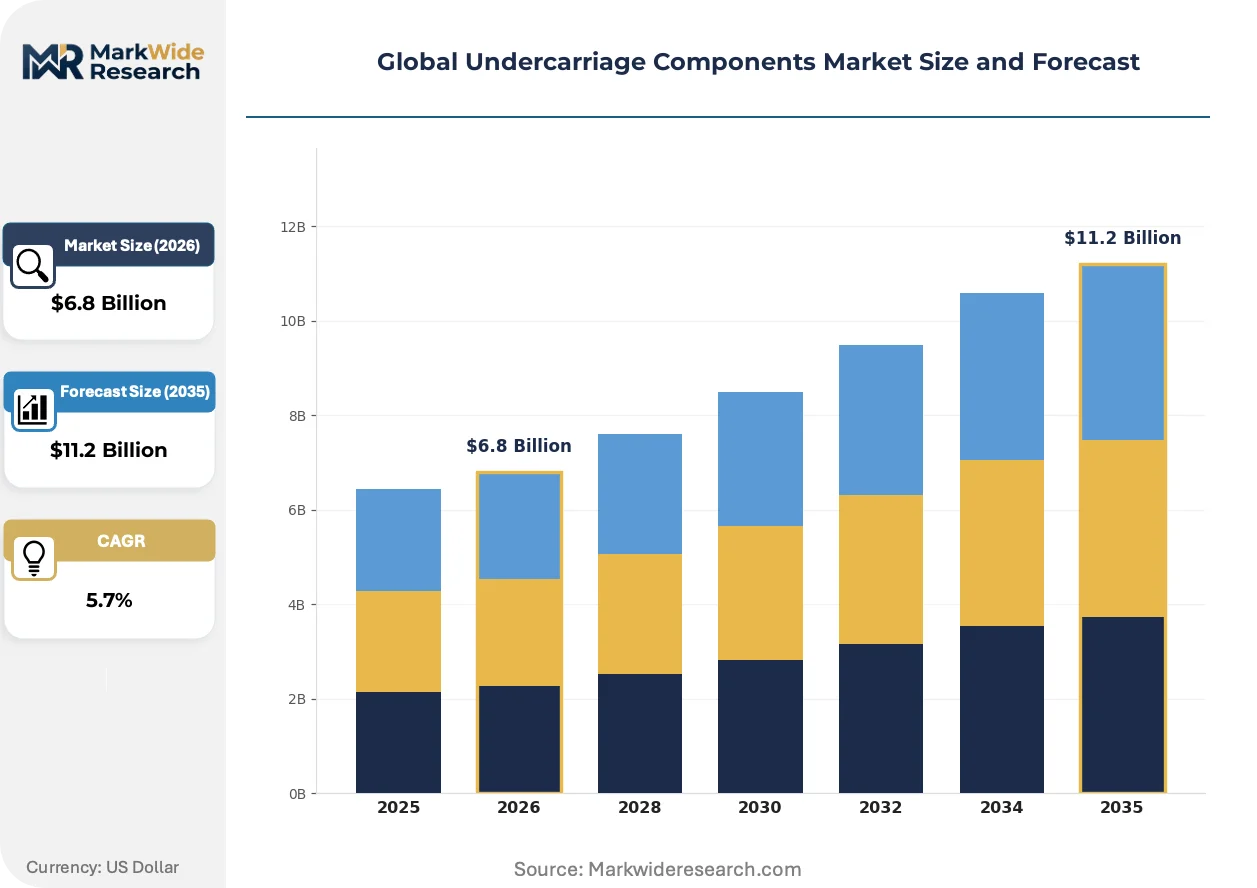
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Track Rollers, Sprockets, Idlers, Bushings Material: Steel, Rubber, Composite, Alloy End User: Construction, Mining, Agriculture, Forestry Application: Excavators, Bulldozers, Loaders, Harvesters |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, John Deere, Hitachi Construction Machinery Co., Ltd., ThyssenKrupp AG, Liebherr Group, JCB Ltd., Doosan Infracore Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Undercarriage Components Market Strategic Shifts
Digital wear tracking and advanced metallurgy are converging to transform how fleet operators manage consumable undercarriage assets, shifting competitive advantage from manufacturing scale to predictive service capabilities.
Boron-modified alloy grades with enhanced through-hardening properties are displacing conventional carbon steel in high-hour mining contracts. Australian and Chilean excavator fleets now specify these materials for track rollers operating beyond 8,000 hours. The technology is displacing standard cast alternatives in premium segments where downtime costs exceed component price differentials by an order of magnitude.
EU Stage V emissions frameworks now mandate mass reduction in undercarriage subsystems without compromising fatigue life. European OEMs have responded with reduced-section bushings and hollow-profile idlers that cut weight 12-18 percent. Komatsu and Hitachi supply chains propagate these designs through METI-linked energy-efficiency requirements, pressuring Asian suppliers to adopt equivalent geometries for export eligibility.
Equipment-as-a-service procurement models now unbundle undercarriage replacement from capital equipment purchases. Mining contractors in Western Australia negotiate uptime-based contracts where suppliers bear wear-risk. This model concentrates in high-utilization fleets where telematics enable accurate hour-based pricing, compressing traditional distributor margins on spot replacement sales.
Global Undercarriage Components Market Segmentation
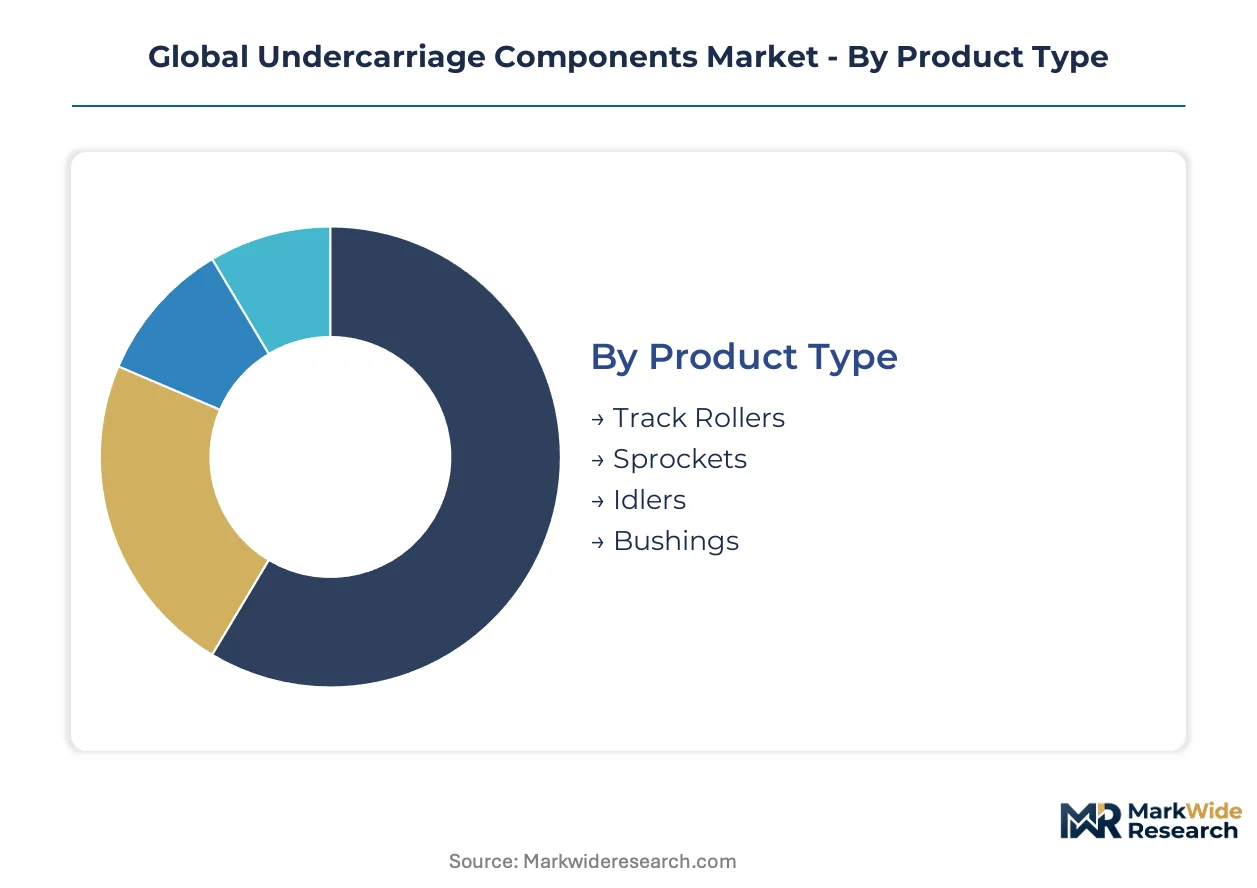
Undercarriage component procurement channels diverge sharply by segment: mining contractors negotiate direct with OEMs for alloy-grade track systems, while construction rebuilders source through distributors for standard steel replacements. Material certification requirements and end-use duty cycles determine whether components flow through captive foundry networks or independent aftermarket channels.
Product Type:
Channel concentration varies by component wear rate and technical complexity. Track rollers and idlers move heavily through distributor networks due to predictable replacement schedules, while sprockets and specialized bushings often ship direct from integrated foundries to mining fleet operators.
- Track Rollers:These ground-contact assemblies endure continuous abrasive loading and sealed-lubrication thermal cycling. Australian and Chilean mining fleets now specify boron-modified alloy grades for units operating beyond 8,000 hours, driving premium channel migration toward certified foundry-direct procurement.
- Idlers:Hollow-profile designs under EU Stage V mass mandates have fragmented supply chains—European OEMs source from integrated casting operations while Asian rebuild markets rely on licensed fabricators with heat-treatment documentation. China's construction equipment rebuild sector consumes the largest replacement volumes.
- Sprockets:Tooth-engagement stress concentrates demand in mining applications.
- Bushings:Forged alloy grades command premium positioning in high-load contracts.
By volume, track rollers lead. By growth pace, hollow-profile idlers are climbing the fastest.
Material:
Cost tier stratification separates captive alloy production from commodity steel sourcing. Integrated OEMs control boron-modified alloy supply chains, while independent distributors compete on carbon steel price points for construction aftermarket rebuilds.
- Steel:Conventional carbon grades dominate construction equipment refurbishment in price-sensitive markets. Indian CEA certification requirements are tightening dimensional tolerances, favoring suppliers with documented heat-treatment traceability over spot-market commodity sources.
- Alloy:Boron-modified formulations with 50-55 HRC through-hardening properties command 3-4x price multiples in mining contracts where hour-based uptime penalties dwarf component costs. EPA Tier 4 Final mass reduction mandates are accelerating hollow-profile geometries in this tier.
- Rubber:Track pad applications in forestry and soft-terrain construction.
- Composite:Emerging weight-reduction trials in European OEM R&D programs.
Steel retains volume leadership. Alloy grades are gaining share fastest in high-hour mining segments.
End User:
Customer type determines contract structure and service bundling intensity. Mining operators negotiate outcome-based uptime guarantees, while construction and agriculture segments transact through spot replacement and scheduled maintenance programs.
- Mining:Fleet-scale procurement centralizes around telematics-linked wear monitoring and predictive replacement contracts. Western Australian contractors now unbundle undercarriage lifecycle costs from capital equipment purchases, shifting supplier risk from component sales to hour-based performance guarantees.
- Construction:Equipment rebuild demand concentrates in China's domestic refurbishment sector, where track system replacements follow MIIT certification cycles. Distributor networks dominate channel flow for standard-grade steel components.
- Agriculture:Seasonal utilization patterns favor spot replacement through regional parts networks.
- Forestry:Soft-terrain specialization drives rubber-track hybrid demand in Nordic and Pacific Northwest markets.
Mining commands highest revenue per unit. Construction delivers steepest volume expansion.
Application:
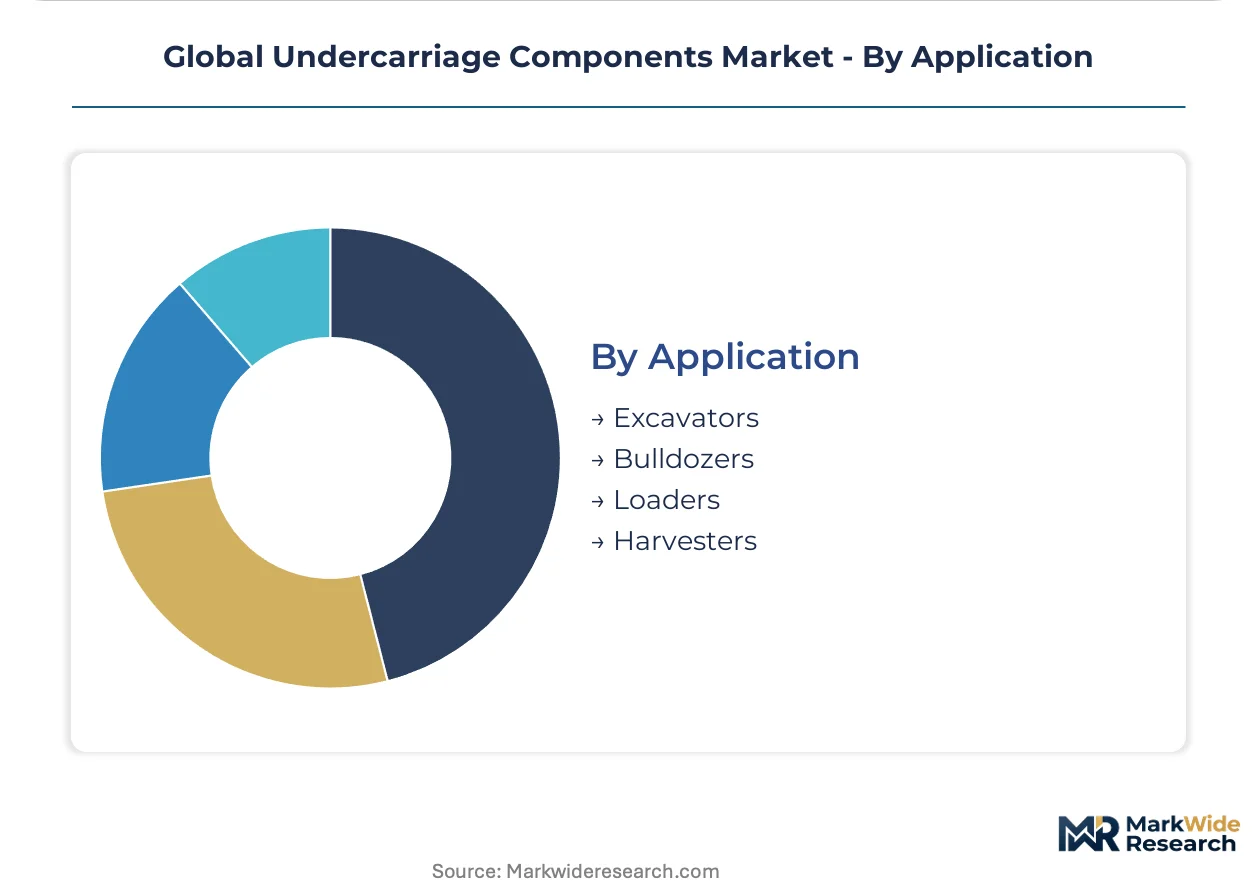
Equipment duty cycles and frame compatibility requirements shape procurement patterns. Large excavator fleets standardize on alloy-grade components through OEM captive supply, while bulldozer and loader rebuilds flow through aftermarket distributors with adapter fabrication capabilities.
- Excavators:Large-class units in Australian and Chilean mining operations specify premium alloy track rollers and idlers with 8,000+ hour design life. Legacy frame compatibility challenges complicate hollow-profile retrofits, creating adapter fabrication revenue streams for specialized distributors.
- Bulldozers:High ground-pressure applications prioritize sprocket durability in abrasive terrain. Komatsu and Caterpillar supply chains propagate forged alloy bushing specifications through METI-linked and EPA Tier 4 Final compliance programs respectively.
- Loaders:Construction-focused replacement cycles align with China's equipment rebuild sector timing.
- Harvesters:Forestry applications favor rubber-track configurations for soil protection.
Excavators anchor alloy-grade premium volume. Bulldozer hollow-profile retrofits are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Australian mining operators while Chinese rebuild markets compress margins through distributor fragmentation. Chilean copper belt demand anchors premium alloy specifications. European OEMs extract compliance premiums through hollow-profile geometries mandated under emissions frameworks.
United States
EPA Tier 4 Final compliance drives hollow-profile idler adoption across construction equipment OEMs. The Department of Energy's off-road equipment efficiency benchmarks push low-friction seal technologies through domestic supply chains. Texas and Arizona mining operations standardize on boron-modified alloy track rollers with 8,000-hour design life.
China
MIIT equipment certification cycles synchronize replacement demand across the construction machinery rebuild sector. The country's national standards body tightens dimensional tolerances for imported track systems, raising compliance documentation requirements. Yangtze River Delta foundry clusters dominate domestic alloy-grade component fabrication for excavator refurbishment.
Germany
EU Stage V mass reduction mandates accelerate reduced-section bushing designs through European OEM supply chains. The KBA enforces construction machinery type-approval standards that propagate through Komatsu and Liebherr procurement networks. Bavaria's industrial belt concentrates forged alloy expertise for high-load mining applications.
Australia
Western Australian iron ore and lithium operations unbundle undercarriage lifecycle costs through uptime-based supplier contracts. The country's national mining safety regulator mandates wear-monitoring documentation for large excavator fleets. Perth-based fleet management firms centralize telematics-linked predictive replacement procurement.
Chile
Copper belt mining operations extend track roller replacement intervals, sustaining aftermarket demand for hardened steel components. The country's national mining regulator encloses emissions compliance within equipment certification renewals. Antofagasta and Calama maintenance depots specify premium alloy grades for 12,000-hour duty cycles.
Global Undercarriage Components Market Competitive Environment
Concentration sits with integrated OEM foundry operations that control captive steel casting capacity. Tiered competition separates alloy-grade mining specialists from carbon steel construction distributors. Strategic archetypes include telematics-linked service integrators, forged alloy specialists, and hollow-profile geometry licensors. Dominant competitive moves encompass backward integration into heat-treatment operations and predictive maintenance contract unbundling.
Among Japanese equipment manufacturers, Komatsu Ltd. and Hitachi Construction Machinery Co., Ltd. exemplify the telematics-integrated service archetype through METI-linked supply chain propagation. German-based ThyssenKrupp AG occupies a position within the forged alloy specialist tier. Caterpillar Inc. anchors the integrated foundry archetype with captive casting operations controlling North American mining contract access.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| John Deere |
| Hitachi Construction Machinery Co., Ltd. |
| ThyssenKrupp AG |
| Liebherr Group |
| JCB Ltd. |
| Doosan Infracore Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Boron-modified alloy substitution for conventional carbon steel simultaneously concentrates procurement power with integrated foundry operators in Germany and Japan while compressing spot-market margins for commodity-grade distributors serving price-sensitive construction rebuild channels. This material transition reshapes supply geography toward captive casting networks and forces pricing stratification across certification tiers.
Pricing Analysis
Configured-to-order pricing for hollow-profile idlers and heat-treated alloy rollers commands 3-4x multiples over standard carbon steel equivalents. Price differentiation hinges on MIIT certification documentation and EPA Tier 4 Final compliance verification. Cost compression in commodity steel tiers is intensifying because Yangtze River Delta fabricators compete on spot-market boron sourcing. Mining fleet operators exhibit lowest price sensitivity, while China's construction equipment rebuild sector transacts on near-term replacement cost minimization.
Supply Chain Analysis
Yangtze River Delta foundry clusters and Germany's Bavarian industrial belt anchor global alloy-grade component fabrication. Raw material flows draw from Australian iron ore, Chilean copper concentrate, and Chinese boron reserves. Single-source vulnerability concentrates in integrated OEM captive casting operations that lock out independent distributors from Western Australian mining contracts. Distribution runs through telematics-linked service integrators for predictive maintenance contracts and regional parts networks for spot replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough in mining capital expenditure, with Australian and Chilean fleet replacement cycles now pulling forward aftermarket demand for hardened steel components.
For Market Incumbents: Consolidate heat-treatment capacity in Yangtze River Delta clusters to capture China's equipment rebuild sector volume. Deepen captive boron-modified alloy supply chains to defend against forged alloy specialists threatening European OEM relationships. Komatsu-linked telematics integration represents the critical defensive lever for predictive maintenance contract retention.
For New Entrants and Emerging Players: Lead with hollow-profile idler retrofits for legacy excavator frames in India's CEA-certified construction aftermarket. Target distributor networks in price-sensitive carbon steel tiers where integrated OEMs maintain minimal presence. Pursue licensed fabricator partnerships with documented heat-treatment traceability as the primary go-to-market pathway.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European hollow-profile geometry licensors seeking exit liquidity amid EU Stage V compliance saturation. Long-term viability favors telematics-integrated service platforms over commodity casting operations across the 5-10 year holding window. Monitor Western Australian uptime-based contract penetration rates as the inflection signal for predictive maintenance model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Operations | Captive 50-55 HRC furnace capacity secures boron-modified alloy supply for Australian mining contracts. |
| Predictive Maintenance Contract Unbundling | KOMTRAX-linked wear monitoring shifts supplier revenue from part sales to hour-based uptime guarantees. |
| Hollow-Profile Geometry Licensing | EU Stage V mass reduction mandates propagate reduced-section designs through Komatsu and Hitachi supply chains. |
| MIIT Certification Documentation Investment | Traceable heat-treatment records create entry barriers favoring pre-certified suppliers in China's rebuild sector. |
| Low-Friction Seal Technology Export | METI energy-efficiency benchmarks propagate Japanese designs to Southeast Asian equipment assemblers. |
Study Parameters
Desk research of customs trade data, foundry capacity registries, and mining fleet procurement databases preceded structured interviews with maintenance directors at Australian iron ore operations, OEM procurement teams at Komatsu and Caterpillar, aftermarket service heads at regional distributors, and heat-treatment furnace operators in Yangtze River Delta clusters. Secondary validation drew from EPA compliance filings, MIIT equipment certification records, and EU Stage V type-approval documentation. Bottom-up volume estimates triangulated against top-down market sizing across component categories.
Variance decomposition across product type, material grade, end-user segment, and equipment application dimensions structured the analytical framework over the projection horizon. CAGRs derived from replacement cycle modeling, fleet utilization assumptions, and alloy adoption curve penetration. Industry-specific forecast inputs incorporated telematics-linked predictive maintenance contract penetration rates and hollow-profile idler retrofit adoption timelines for legacy excavator frames.
Forecasts assume regulatory continuity in EPA Tier 4 Final, EU Stage V, and MIIT certification regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as boron price volatility and regional carbon-border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Engine Mounting Brackets Market