
 Snowplows Market | 2026-2036
Snowplows Market Size, Share, and Industry Trends Forecast 2026-2036
Snowplows Market Analytics
The snowplows customer base is broadening beyond traditional municipal fleets to encompass regional contractors and large commercial property managers. Douglas Dynamics sustains its position through extensive dealer networks across North American snow belts. BOSS Snowplow differentiates via proprietary hydraulic systems and contractor-focused product lines. The Toro Company leverages its landscaping equipment ecosystem to cross-sell walk-behind and ATV-mounted units to existing grounds maintenance clients.
Snowplows are heavy-duty blade or blower attachments designed to clear accumulated snow from paved surfaces, typically constructed from hardened steel or polyethylene moldboards with trip-edge mechanisms to absorb impacts. Truck-mounted configurations dominate municipal and highway applications due to higher blade widths and horsepower compatibility, while walk-behind and ATV variants serve constrained residential driveways and commercial parking lots where maneuverability outweighs throughput. Electric actuation technology is gaining share in light-duty segments as battery systems improve cold-weather performance, though hydraulic systems retain primacy in heavy commercial and roadways applications where force requirements exceed electric motor outputs.
EPA emission regulations for off-road diesel equipment and NHTSA lighting standards for vehicle-mounted implements shape product design and compliance costs across the United States. State-level procurement specifications in Minnesota, Wisconsin, and New York require corrosion-resistant coatings and specific blade geometries that filter supplier eligibility. Stakeholders must monitor electrification timelines and regional fleet electrification mandates to calibrate R&D investment between hydraulic refinement and electric platform development.
Market Dynamics
Electrification of hydraulic actuation systems is the central structural force reshaping snowplow manufacturing, as EPA emission standards and state-level fleet mandates force engineering trade-offs between torque density and battery cold-weather performance.
Growth Catalysts
- Minnesota procurement specifications:State-level corrosion-resistant coating mandates and blade geometry standards in Minnesota, Wisconsin, and New York filter supplier eligibility and lock in replacement cycles for qualified vendors.
- Electric actuator penetration:Battery system improvements in cold-weather performance enable electric actuation to capture share in light-duty walk-behind and ATV-mounted segments previously dominated by hydraulics.
- Municipal fleet modernization:Northern climate municipalities are accelerating replacement schedules for aging truck-mounted highway fleets, concentrating demand in the Upper Midwest and Northeast United States.
Market Restraints
- Hardened steel input volatility:Blade moldboard material costs fluctuate with scrap metal and alloy pricing, compressing margins for manufacturers without long-term supply agreements.
- Hydraulic torque ceiling:Electric motor outputs currently fail to match hydraulic force requirements in heavy commercial and roadway applications, segmenting technology adoption by duty class.
- NHTSA lighting compliance:Federal vehicle-mounted implement standards add certification layers and redesign costs that disproportionately burden smaller regional fabricators.
Strategic Opportunities
- Commercial property manager segment:Large retail and logistics facility operators are internalizing snow removal operations, creating direct procurement channels bypassing traditional municipal dealer networks.
- Cross-selling integration:Landscaping equipment ecosystems enable bundled walk-behind and ATV-mounted unit sales to existing grounds maintenance client bases.
- Regional contractor expansion:Mid-size snow removal contractors are upgrading from used municipal surplus to new purpose-built equipment, opening financing and leasing service revenue streams.
Industry Challenges
- Electrification talent scarcity:The shortage of power electronics engineers with cold-weather battery management expertise slows platform development timelines for hybrid and fully electric systems.
- Legacy hydraulic integration:Retrofit compatibility requirements for existing truck fleets complicate electric actuator design, forcing dual-platform engineering investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snowplows Market |
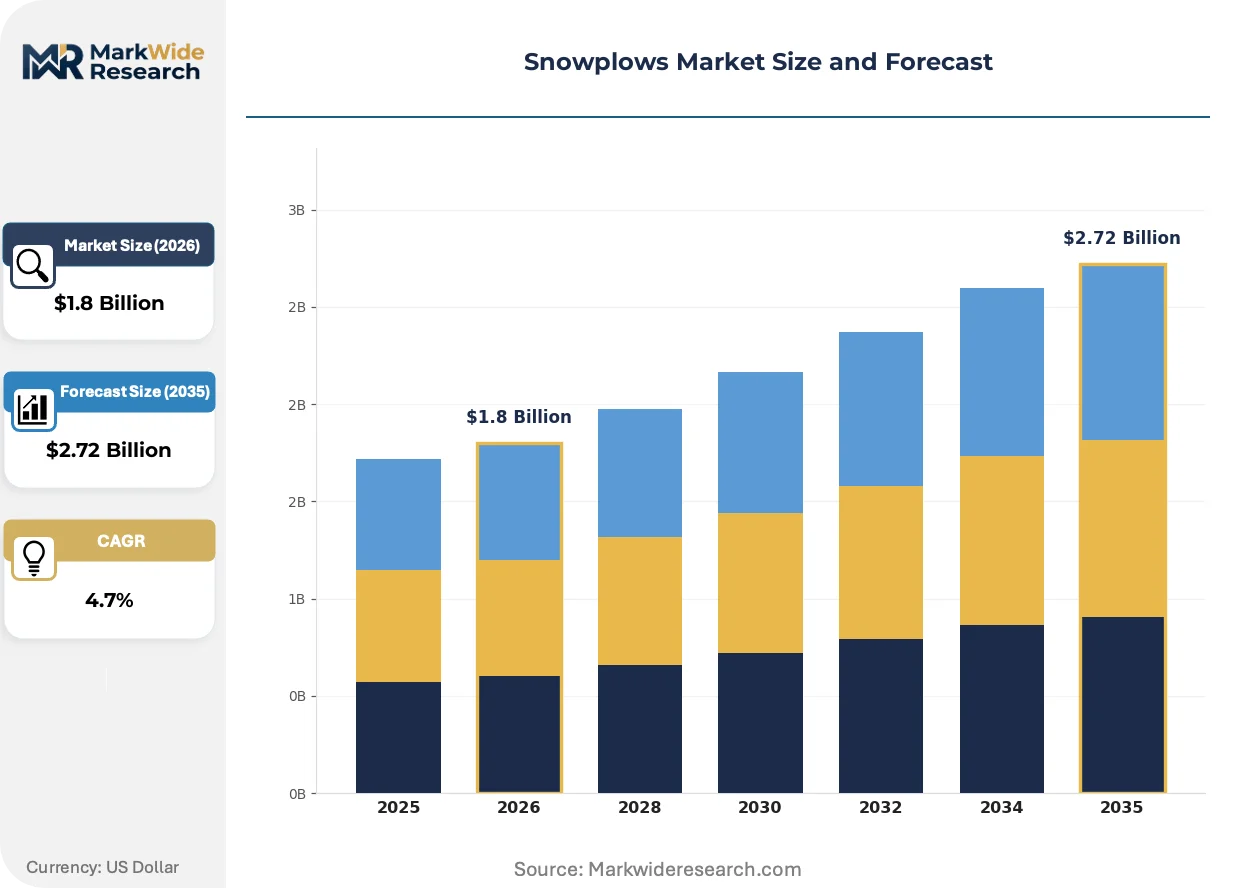
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck-Mounted, Walk-Behind, ATV, Snow Blower End User: Municipalities, Contractors, Homeowners, Snow Removal Services Technology: Hydraulic, Electric, Manual, Mechanical Application: Roadways, Driveways, Parking Lots, Commercial Properties |
| Companies Covered | The Toro Company, Douglas Dynamics, BOSS Snowplow, Meyer Products LLC, Fisher Engineering, Western Products, Arctic Snow and Ice Control, Hiniker Company, Buyers Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snowplows Market Evolving Landscape
Active thermal management and smart blade control systems are converging to reshape equipment performance expectations. Manufacturers are racing to embed sensors and automation into traditional mechanical platforms.
Polyethylene moldboards with integrated heating elements are overtaking conventional steel blades in commercial parking lot applications. Property managers operating in freeze-thaw cycles are specifying these units to reduce salt corrosion and surface damage. The technology is compressing replacement intervals for traditional steel while commanding premium positioning in contractor-focused product lines.
EPA Tier 4 Final emission standards for off-road diesel equipment are forcing engine redesigns and after-treatment additions in heavy truck-mounted configurations. The regulatory burden falls most heavily on highway department procurement, where horsepower requirements preclude smaller displacement engines. Fleet managers are responding with extended equipment life cycles and remanufacturing programs to defer new purchase compliance costs.
Direct purchasing from manufacturers is displacing traditional dealer intermediaries among large commercial contractors with multi-site snow removal obligations. These buyers are negotiating volume pricing and dedicated service agreements that bypass regional distribution markups. The pattern is most visible in the Upper Midwest, where consolidated landscaping companies operate across state lines with centralized procurement functions.
Snowplows Market Segmentation
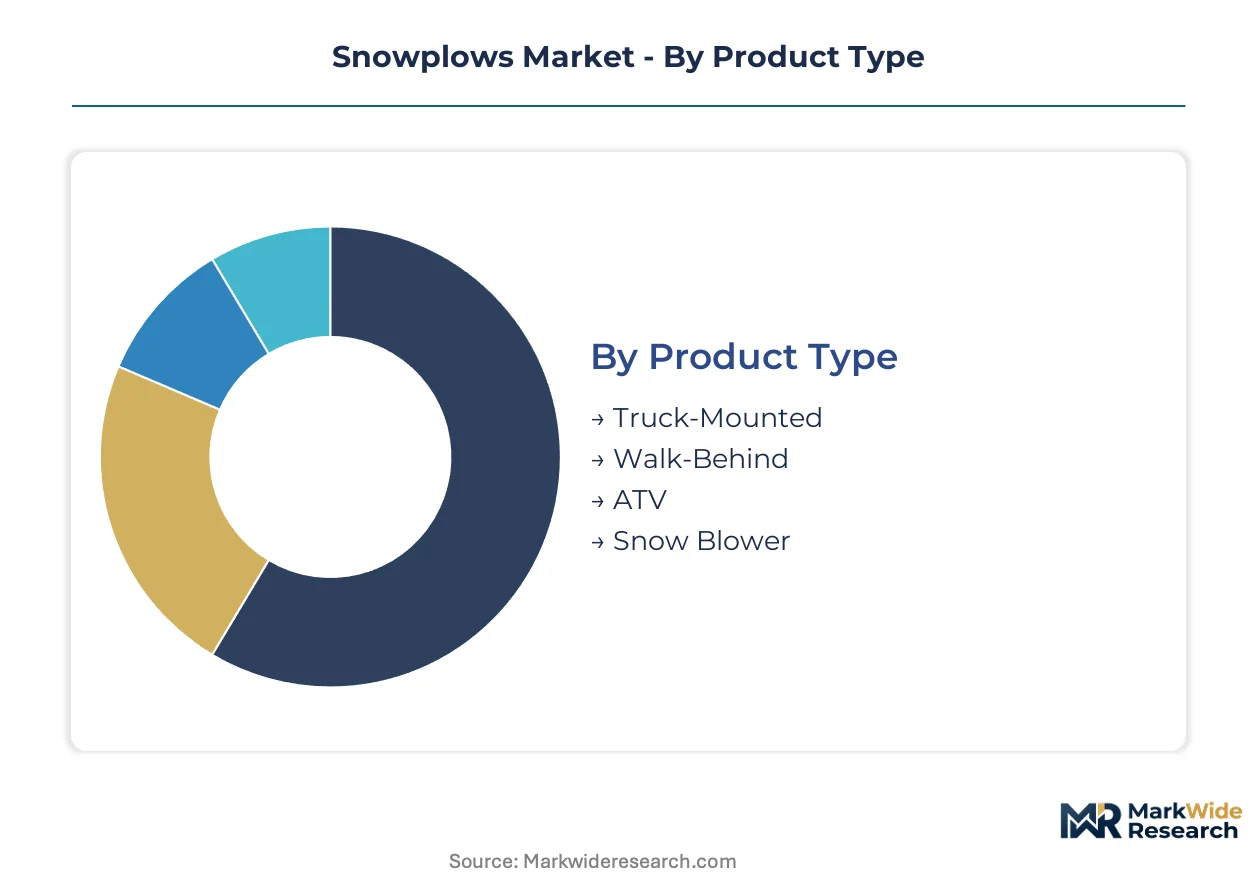
Snowplow procurement patterns diverge sharply across duty classes and operator scale, with municipal highway departments prioritizing blade width and horsepower compatibility while commercial property managers optimize for maneuverability and surface protection. Understanding these segment boundaries enables manufacturers to calibrate R&D investment between hydraulic refinement and electric platform development.
Product Type:
Volume concentration sits with truck-mounted configurations, while premium positioning clusters in specialized walk-behind and ATV variants serving constrained access environments.
- Truck-Mounted:Heavy-duty blade attachments engineered for highway and arterial road clearing, typically featuring hardened steel moldboards with trip-edge mechanisms and hydraulic lift systems. Municipal fleet modernization programs in Minnesota, Wisconsin, and New York concentrate replacement demand here, driven by state procurement specifications for corrosion-resistant coatings and specific blade geometries.
- Walk-Behind:Self-propelled or push units with polyethylene or steel blades designed for residential driveways and narrow commercial pathways. Electric actuation penetration is climbing the fastest in this segment as battery cold-weather performance improvements enable displacement of legacy hydraulic systems.
- ATV:Compact blade or pull-behind blower attachments compatible with all-terrain vehicle platforms. Regional contractors in the Upper Midwest favor these units for estate driveways and small commercial lots where truck access proves impractical.
- Snow Blower:Auger-driven discharge machines for deep snow removal, ranging from single-stage electric residential units to three-stage commercial configurations. Homeowners in heavy snowfall belts drive seasonal replacement cycles for walk-behind blowers.
Today's leader: Truck-Mounted. Tomorrow's challenger: Walk-Behind.
End User:
Customer scale determines procurement channel structure, with large operators consolidating direct manufacturer relationships while fragmented buyers remain captive to dealer networks.
- Municipalities:City, county, and state highway departments operating centralized snow removal fleets with standardized equipment specifications. EPA Tier 4 Final emission standards force engine redesigns and after-treatment additions in heavy configurations, compressing margins and extending replacement intervals.
- Contractors:Regional and mid-size snow removal businesses serving commercial and residential accounts. These operators are upgrading from used municipal surplus to new purpose-built equipment, opening financing and leasing service revenue streams for manufacturers.
- Homeowners:Individual property owners purchasing walk-behind or small ATV-mounted units for personal driveway clearing. Price sensitivity dominates here, with seasonal retail distribution through hardware and farm supply channels.
- Snow Removal Services:Dedicated winter-only operations and landscaping companies with cross-seasonal equipment utilization. Cross-selling integration from landscaping equipment ecosystems enables bundled unit sales to existing grounds maintenance client bases.
Municipalities anchor current volume. Contractors represent the steepest expansion trajectory.
Technology:
Application force requirements segment adoption, with heavy commercial and roadway duty classes resisting electrification due to torque density limitations.
- Hydraulic:Fluid-power actuation systems delivering high force output for heavy blade lifting and angling operations. Retains primacy in truck-mounted highway applications where force requirements exceed current electric motor outputs.
- Electric:Battery-powered actuator systems with integrated power electronics and thermal management. Active thermal management and smart blade control systems are converging to reshape performance expectations in light-duty walk-behind and ATV segments.
- Manual:Human-powered push or pull mechanisms for small residential units. Concentrated in entry-price walk-behind segments where capital constraints outweigh labor cost considerations.
- Mechanical:PTO-driven or engine-direct power transmission without hydraulic intermediary. Agricultural and utility vehicle conversions favor this architecture for simplicity and field serviceability.
Hydraulic systems defend installed base. Electric platforms gain share fastest.
Application:
Surface type and traffic volume dictate blade material selection and operating speed requirements, with freeze-thaw environments driving specification divergence.
- Roadways:Highway, arterial, and collector street clearing requiring high blade widths and continuous operation capability. NHTSA lighting standards for vehicle-mounted implements add certification layers and redesign costs.
- Driveways:Residential and estate access clearing where maneuverability constraints favor compact equipment. Polyethylene moldboards with integrated heating elements are overtaking conventional steel blades here to reduce salt corrosion and surface damage.
- Parking Lots:Commercial and retail facility surface clearing with obstacle-dense environments. Large retail and logistics facility operators are internalizing snow removal operations, creating direct procurement channels bypassing traditional municipal dealer networks.
- Commercial Properties:Industrial campuses, logistics facilities, and mixed-use developments with specialized access requirements. Direct purchasing from manufacturers is displacing traditional dealer intermediaries among large operators with multi-site obligations.
Roadways command equipment value. Commercial Properties expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's municipal fleet electrification timelines outpace Germany's regulatory pressure, while both confront torque-density limitations in heavy-duty configurations. Snowfall severity and state procurement specifications concentrate replacement demand in specific northern corridors.
United States
Minnesota, Wisconsin, and New York procurement specifications mandate corrosion-resistant coatings and blade geometries that filter supplier eligibility. EPA Tier 4 Final emission standards force engine redesigns in heavy truck-mounted configurations. The Upper Midwest corridor anchors replacement cycles, with municipalities accelerating modernization of aging highway fleets.
Canada
Provincial highway departments in Ontario and Quebec operate centralized fleets with standardized specifications for blade width and horsepower compatibility. Environment Canada cold-weather performance guidelines influence electric actuator adoption timelines in light-duty segments. The Prairie Provinces concentrate contractor demand for ATV-mounted units serving estate driveways and agricultural access roads.
Germany
Federal motor vehicle regulations through KBA impose lighting and mounting standards for vehicle-mounted implements that add certification complexity. The country's national environmental regulator enforces emission standards for off-road diesel equipment that parallel EPA Tier 4 Final requirements. Bavaria and North Rhine-Westphalia concentrate municipal procurement through centralized state purchasing cooperatives.
Sweden
Swedish Transport Administration specifications for highway maintenance equipment emphasize continuous operation capability in sub-zero conditions. The country's national environmental protection agency monitors idling restrictions that accelerate hydraulic-to-electric transitions in urban applications. Stockholm and Gothenburg metropolitan regions drive specification adoption for polyethylene moldboards with integrated heating elements.
Japan
METI industrial standards for construction and maintenance machinery shape product design requirements for export-oriented manufacturers. Heavy snowfall corridors in Hokkaido and the Sea of Japan side of Honshu concentrate municipal fleet investment. The Kanto region around Tokyo serves as the primary distribution hub for walk-behind and compact units serving residential driveway applications.
Snowplows Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: full-line landscaping equipment manufacturers leveraging cross-selling ecosystems, dedicated snow and ice management specialists with deep dealer networks, and regional metal fabricators serving price-sensitive contractor segments. Consolidation pressure operates through acquisition of regional fabricators by national platforms and strategic partnerships between electric drivetrain suppliers and legacy hydraulic manufacturers.
Among dedicated specialists, Douglas Dynamics and BOSS Snowplow occupy positions within the premium-tier dealer-network segment, while The Toro Company represents the diversified conglomerate archetype with cross-seasonal equipment ecosystems. These three anchors illustrate the competitive tension between focused snow-and-ice expertise and bundled landscaping equipment portfolios.
| Leading Market Players |
|---|
| The Toro Company |
| Douglas Dynamics |
| BOSS Snowplow |
| Meyer Products LLC |
| Fisher Engineering |
| Western Products |
| Arctic Snow and Ice Control |
| Hiniker Company |
| Buyers Products Company |
| Others |
Value Network & Pricing Analysis
Scrap steel index volatility cascades through hardened steel moldboard fabrication into tiered equipment pricing, with alloy surcharges compressing margins for manufacturers lacking long-term supply agreements while polyethylene alternatives capture premium positioning in freeze-thaw environments.
Pricing Analysis
Capacity additions in Wisconsin and Minnesota are reshaping price floors for corrosion-resistant coating tiers, with state procurement specifications mandating specific blade geometries that filter supplier eligibility. Three-tier pricing structure across premium, standard, and economy levels separates municipal fleet contractors with volume-scale negotiations from regional fabricators serving price-sensitive seasonal operators. Pricing pressure stems from EPA Tier 4 Final after-treatment costs in heavy highway configurations, with commercial property managers showing least sensitivity due to surface-damage avoidance priorities.
Supply Chain Analysis
Dual-sourcing requirements from Minnesota and New York highway departments mandate multi-supplier qualification for blade geometry compliance, forcing fabricators to maintain redundant coating capacity. Hardened steel feedstock draws from domestic mills in Pennsylvania and Ohio, with hydraulic actuator components anchored in Michigan and Indiana manufacturing clusters. Single-source vulnerability concentrates in specialized polyethylene resin grades for heated moldboards. Distribution runs through dealer networks in the Upper Midwest, with direct manufacturer channels displacing intermediaries among large multi-site contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The snowplows market represents a late-cycle quality story as commercial property managers prioritize surface-protection specifications over capital cost minimization, elevating polyethylene moldboard penetration and integrated heating element demand.
For Market Incumbents: Anchor dealer network control in Minnesota, Wisconsin, and New York procurement corridors where state specifications lock in replacement cycles for qualified vendors. Defend against electric actuator entrants by accelerating hydraulic refinement for heavy highway torque requirements while capturing polyethylene moldboard premium tiers through integrated heating technology. Certification investment in corrosion-resistant coatings preserves municipal eligibility against regional fabricator price competition.
For New Entrants and Emerging Players: Mid-size regional contractors upgrading from municipal surplus equipment present the most penetrable buyer archetype, with financing and leasing service gaps opening white-space opportunities. Target ATV-mounted segments in the Prairie Provinces and Upper Midwest estate driveway applications where truck access constraints favor compact equipment. Direct procurement channel development bypassing traditional dealer networks offers the strongest go-to-market angle for large commercial property managers with multi-site obligations.
For Investors and Strategic Acquirers: Asymmetric upside sits with electric drivetrain suppliers possessing cold-weather battery management expertise, as torque-density limitations in heavy configurations create extended technology transition windows. Long-term viability favors platforms with dual hydraulic-electric engineering capabilities serving segmented duty classes. Monitor Environment Canada and EPA electrification timeline acceleration as the critical inflection signal for platform investment reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Platform Development | Cold-weather battery thermal management advances displace hydraulics in walk-behind segments. |
| Polyethylene Moldboard Manufacturing Scale-Up | Integrated heating elements capture premium positioning from commercial property managers. |
| Dealer Network Consolidation | Upper Midwest corridor control secures Minnesota and Wisconsin procurement specification access. |
| Financing and Leasing Service Launch | Contractor upgrade cycles from municipal surplus create recurring revenue streams. |
| Corrosion-Resistant Coating Certification | EPA and state-level mandates filter supplier eligibility and lock replacement cycles. |
Research Methodology
Bottom-up municipal fleet and contractor demand modeling reconciled against top-down steel input and manufacturing capacity tracking forms the analytical core of this study. Primary interviews with highway department procurement officers, regional snow removal contractors, commercial property managers, dealer network principals, and aftermarket service heads combined with secondary validation from EPA emission filings, state procurement databases, NHTSA certification records, and trade customs data. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of replacement cycles and technology adoption patterns informs the projection framework across the analysis window. Segmentation dimensions include product type, end-user scale, actuation technology, and application surface requirements, with regional procurement specification clusters as an industry-specific overlay. CAGRs derive from equipment life-cycle modeling and fleet modernization program tracking, incorporating snowfall severity indices and regulatory compliance cost trajectories as forecast inputs.
Underlying measurement precision varies by segment; truck-mounted highway configurations carry tighter precision than fragmented walk-behind residential channels due to centralized procurement data availability. Forecasts reflect assumptions about EPA enforcement continuity, state-level idling restriction propagation, and battery cold-weather performance improvement curves. Deviation in municipal fleet electrification mandate timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Idler Arm Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Forklift Seats Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Sideloaders Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Mining Vehicle AC Kits Market