
 RV Battery Market | 2026-2036
RV Battery Market Size, Share, and Industry Trends Forecast 2026-2036
RV Battery Market Insights
China's lithium-ion cell manufacturing expansion is reconfiguring upstream supply dynamics for RV battery assemblers worldwide. East Penn Manufacturing leverages its Pennsylvania-based lead-acid foundry network to sustain domestic production scale. RELiON Battery specializes in lithium iron phosphate chemistry for premium RV retrofit installations. Trojan Battery Company dominates the deep-cycle flooded battery segment through dealer channel control across North American campground networks.
RV batteries store and discharge electrical energy to power onboard lighting, climate control, refrigeration, and inverter loads when shore power or generator input is unavailable. Lithium-ion variants typically deliver 3,000-5,000 cycles at 80% depth of discharge versus 400-600 cycles for comparable lead-acid designs, enabling extended off-grid autonomy. The battery type dimension shows lithium-ion capturing margin pools from premium motorcoach and fifth-wheel buyers while lead-acid retains volume in entry-level towable trailers. Installation type patterns reveal built-in lithium systems commanding higher value per unit as OEMs integrate battery management electronics at the factory level.
US EPA hazardous waste rules and DOT shipping classifications govern lead-acid battery recycling logistics and cross-state transport compliance costs. China's GB standards for lithium cell safety testing create export certification requirements for cells entering North American assembly plants. Stakeholders must monitor NHTSA proposals for onboard energy storage in recreational vehicles as electrified chassis architectures emerge from motorcoach OEMs.
Market Dynamics
Full-time remote-work RVers are forcing battery chemistry trade-offs between lithium-ion cycle life and lead-acid upfront cost, compressing replacement timelines and reshaping installer service models.
Growth Catalysts
- US Inflation Reduction Act:Clean energy tax credits reduce lithium system payback periods for motorcoach owners, accelerating retrofit demand in southwestern desert corridors.
- Remote-work travelers:Extended off-grid camping requirements among digital nomads multiply daily amp-hour consumption, driving deep-cycle capacity upgrades.
- Cell manufacturing expansion:China's lithium-ion foundry scale is lowering pack costs for North American assemblers, easing price barriers for premium fifth-wheel buyers.
Market Restraints
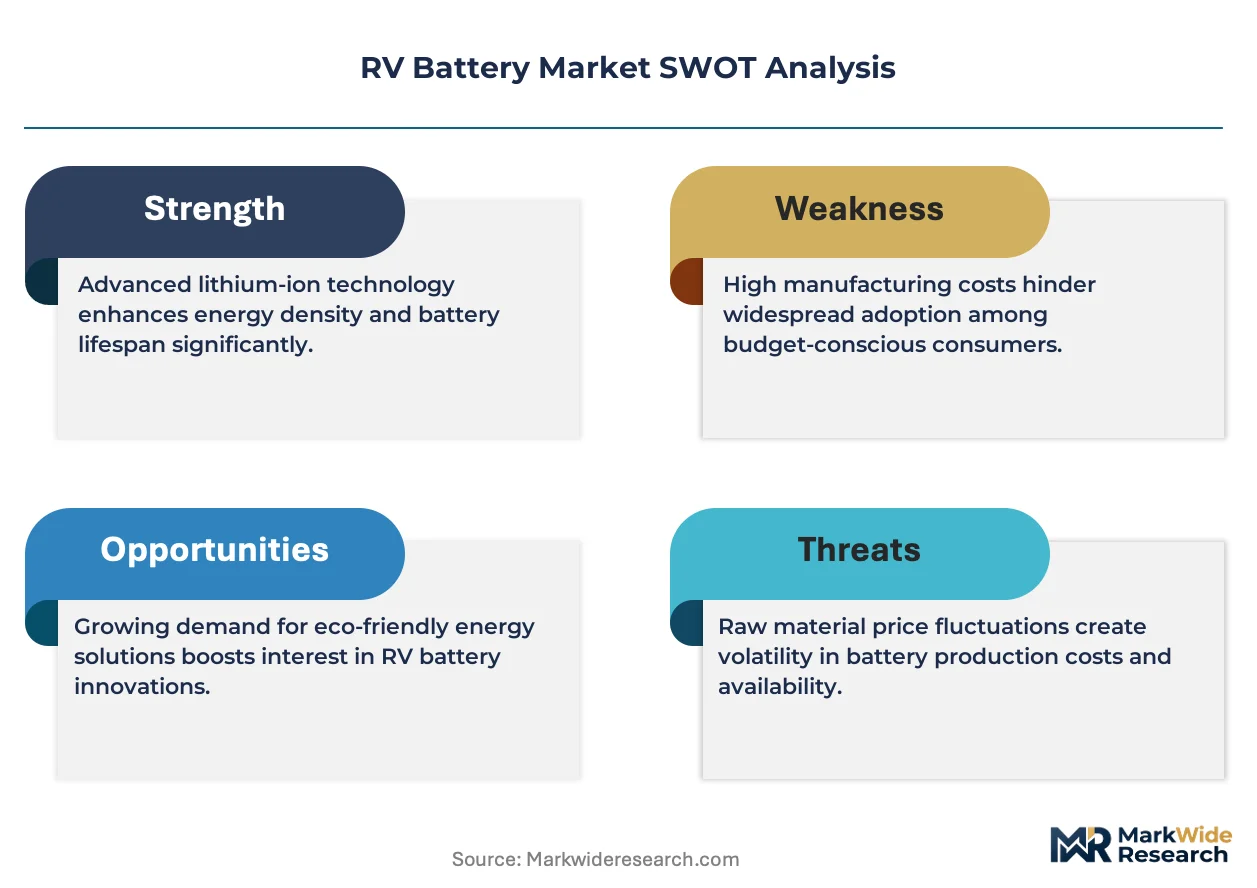
- Lithium carbonate volatility:Raw material price swings constrain margin predictability for battery management system integrators.
- Lead-acid recycling logistics:US EPA hazardous waste rules and DOT shipping classifications inflate cross-state transport compliance costs for flooded battery returns.
- Thermal runaway containment:Cell-level safety testing under China's GB standards creates export certification bottlenecks for cells entering US assembly plants.
Strategic Opportunities
- Electrified chassis architectures:Motorcoach OEMs integrating high-voltage energy storage create factory-install partnerships for lithium system suppliers.
- Dealer network retrofit channels:Independent RV service centers represent underpenetrated distribution for drop-in lithium replacements.
- Boondocking culture maturation:Arizona and New Mexico desert camping clusters concentrate demand for solar-battery hybrid configurations.
Industry Challenges
- Battery management system firmware:Integration complexity with legacy inverter-charger hardware requires specialized technician training.
- NHTSA energy storage proposals:Evolving onboard battery safety standards for recreational vehicles extend product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RV Battery Market |
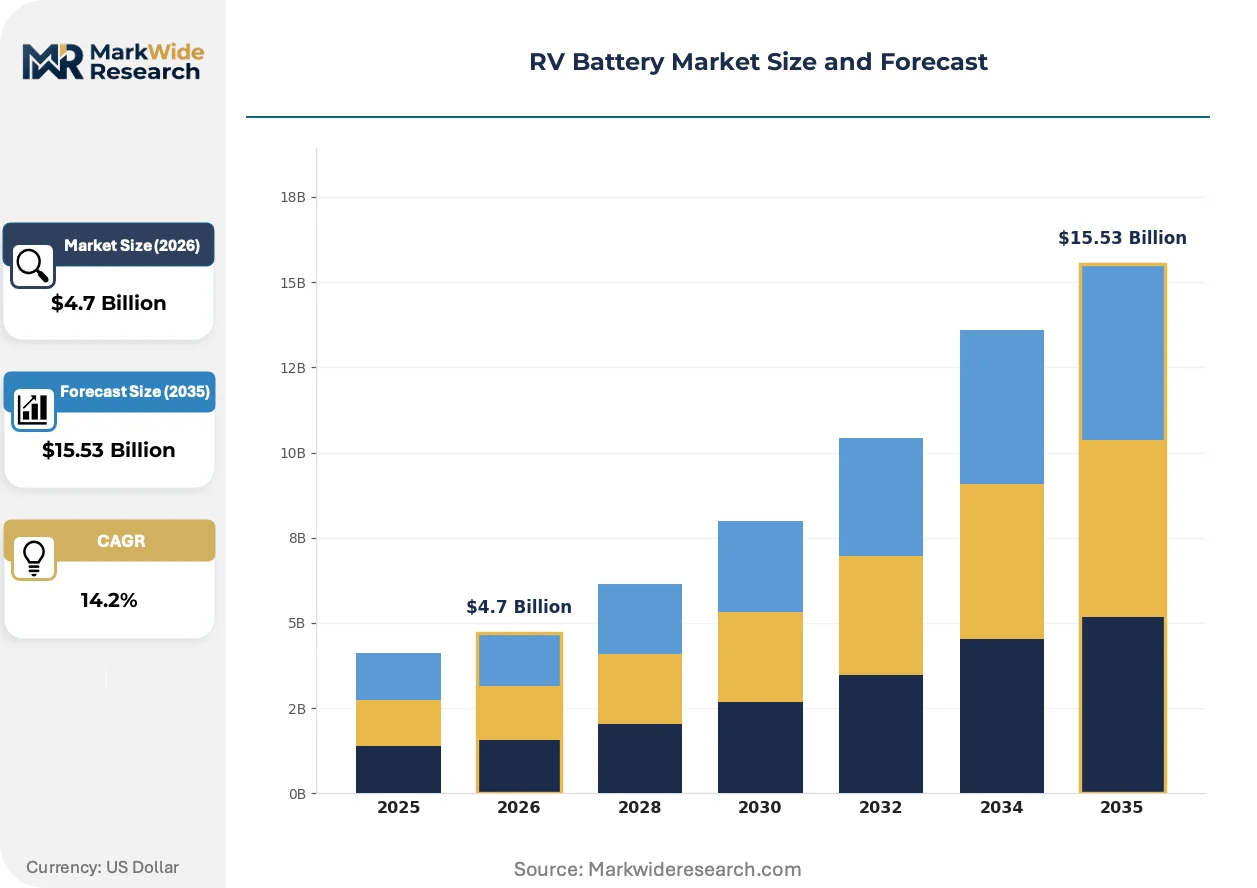
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead-Acid, Lithium-Ion, Gel Batteries, Absorbent Glass Mat Application: Recreational Vehicles, Camping, Off-Grid Power, Marine Uses Capacity: 100Ah, 200Ah, 250Ah, 300Ah Installation Type: Built-In, Portable, Fixed, Removable |
| Companies Covered | East Penn Manufacturing, Exide Technologies, EnerSys, Crown Battery Manufacturing Company, Clarios, RELiON Battery, Trojan Battery Company, Battle Born Batteries, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RV Battery Market Trends and Innovations
Intelligent battery management systems are compressing the information asymmetry between RV owners and power systems, enabling predictive maintenance and remote diagnostics.
Smart battery monitoring with Bluetooth-enabled state-of-charge telemetry is digitizing owner awareness of consumption patterns. Full-time remote workers adopting motorcoach residences demand real-time visibility into remaining autonomy. This capability is digitizing the service relationship between owners and mobile technicians.
The US Inflation Reduction Act's domestic content bonuses are redirecting lithium cell procurement toward North American assembly plants. Battery pack manufacturers face sourcing recalibration to capture clean energy credits. Premium fifth-wheel and motorcoach segments are responding fastest through OEM pre-certification programs.
Buyer preference for factory-integrated lithium systems is displacing aftermarket retrofit as the default upgrade path. Entry-level towable trailer dealers face margin compression as buyers defer to OEM-installed options. This shift concentrates most visibly in southwestern US markets where extended off-grid camping is normative.
RV Battery Market Segmentation
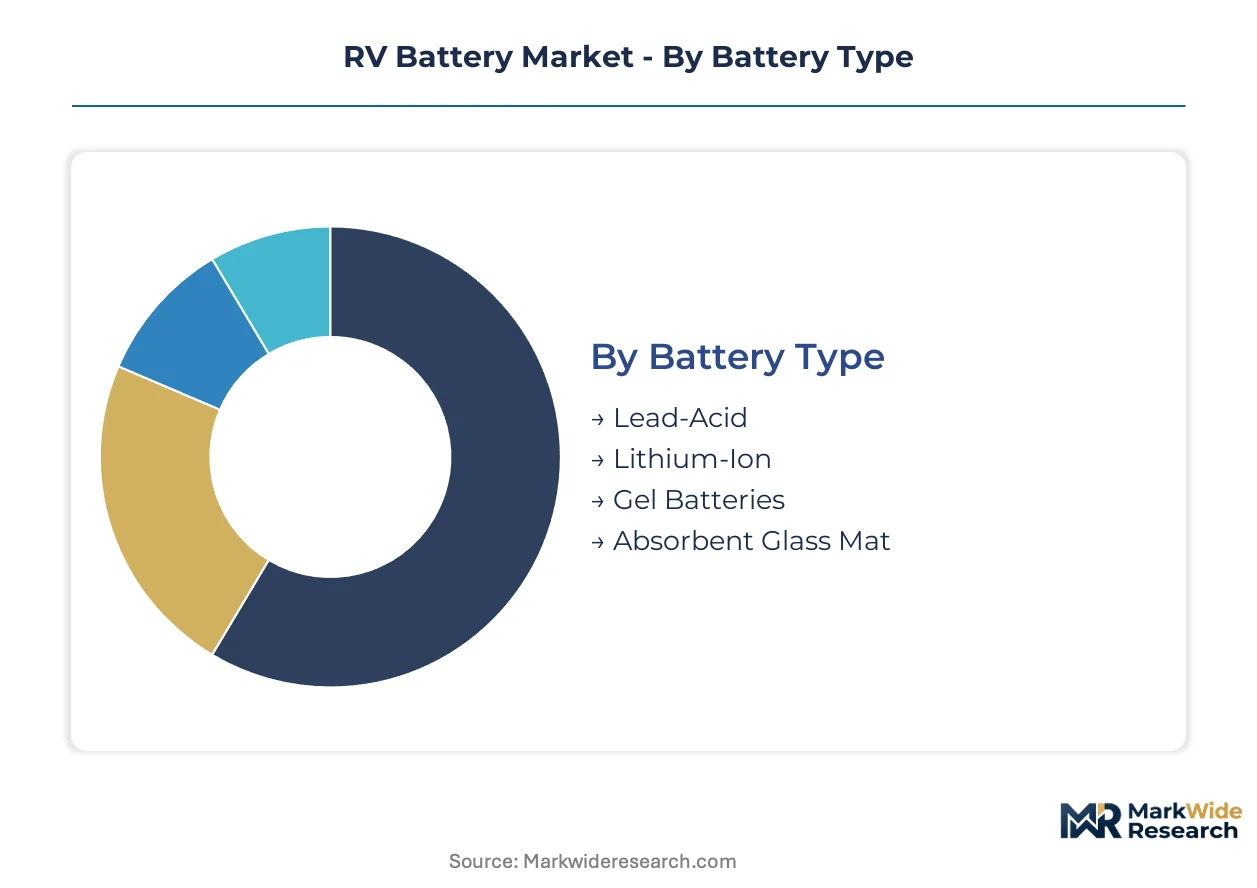
RV battery segmentation reveals how chemistry choices, application intensity, and installation constraints fragment procurement decisions across motorcoach OEMs and aftermarket retrofitters. Understanding these dimensions exposes where margin pools concentrate and which technical specifications command price premiums in desert boondocking corridors versus dealer lot defaults.
Battery Type:
Cost tier stratification separates entry-level towable buyers from premium motorcoach owners seeking extended cycle life and reduced weight penalties.
- Lithium-Ion:Lithium iron phosphate cells deliver 3,000-5,000 cycles at 80% depth of discharge with one-third the mass of lead-acid equivalents. Arizona and New Mexico full-time remote workers are driving factory-install partnerships as OEMs integrate battery management electronics at production.
- Lead-Acid:Flooded deep-cycle designs dominate entry-level towable trailers through dealer channel control and sub-$200 replacement accessibility. EPA hazardous waste rules and DOT shipping classifications inflate cross-state recycling logistics, compressing margins for independent service centers.
- Gel Batteries:Valve-regulated lead-acid with silica-thickened electrolyte resists vibration damage in rough-terrain fifth-wheel applications.
- Absorbent Glass Mat:Spiral-wound AGM construction enables faster recharge acceptance from solar arrays in weekend camper configurations.
Lead-acid commands the established base. The steepest expansion runs through lithium-ion as Inflation Reduction Act credits compress payback periods.
Application:
End-use intensity determines daily amp-hour consumption patterns and drives chemistry trade-offs between upfront capital and lifecycle economics.
- Recreational Vehicles:Factory-integrated lithium systems in premium motorcoaches and fifth-wheels are displacing aftermarket retrofit as the default upgrade path, with OEM pre-certification programs capturing clean energy credits fastest.
- Off-Grid Power:Extended desert camping among digital nomads multiplies daily consumption, forcing deep-cycle capacity upgrades above 300Ah and solar-battery hybrid configurations.
- Camping:Weekend-use towable trailers sustain lead-acid volume through price-sensitive dealer lot procurement.
- Marine Uses:Salt-air corrosion resistance requirements favor sealed AGM and gel constructions in coastal RV-marine crossover applications.
Recreational vehicles anchor volume concentration. Off-grid power is climbing the fastest as remote-work culture matures in southwestern US corridors.
Capacity:
Volume segmentation maps directly to autonomy duration and solar array sizing in self-contained camping configurations.
- 300Ah:Maximum factory-integrated lithium configurations enable 72+ hour autonomy without generator support for full-time motorcoach residents.
- 200Ah:The practical ceiling for most fifth-wheel retrofit installations balances weight distribution against refrigerator and climate loads.
- 250Ah:Emerging standard for solar-hybrid desert camping where panel output must replenish overnight consumption.
- 100Ah:Entry-level towable baseline sufficient for LED lighting and water pump cycles without inverter loads.
200Ah configurations hold the current installed base. 300Ah systems are gaining share fastest among factory-order premium segments.
Installation Type:
Customer type and margin structure diverge sharply between OEM-integrated systems and owner-initiated upgrades.
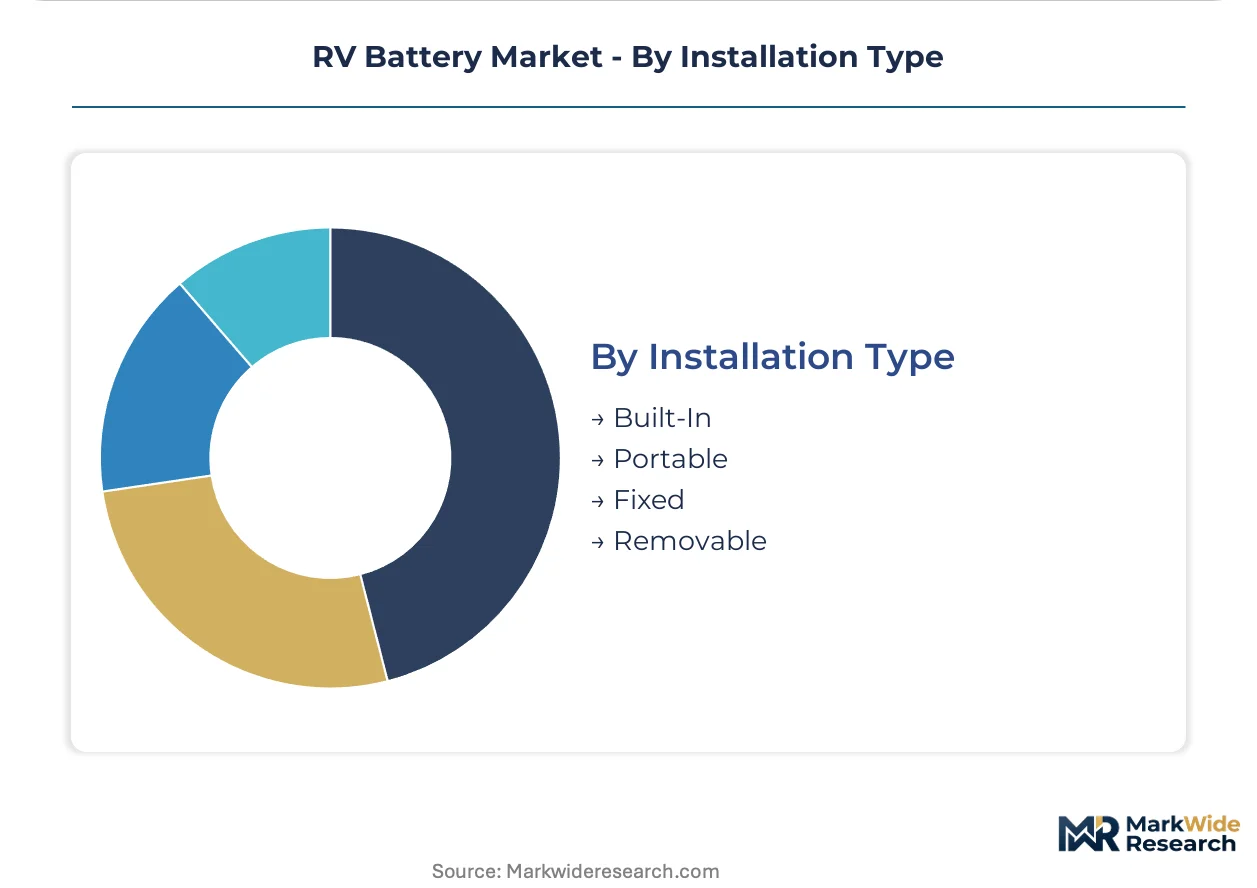
- Built-In:Factory-installed lithium systems with integrated battery management electronics command highest value per unit and lock in OEM service relationships through warranty terms.
- Portable:Drop-in lithium replacements for existing battery boxes represent underpenetrated distribution opportunity through independent RV service centers.
- Fixed:Hard-mounted lead-acid banks in basement compartments dominate entry-level towable production for cost minimization.
- Removable:Dual-purpose battery trays enabling shore-power supplement or emergency vehicle starting in multi-use motorcoach configurations.
Fixed installations retain volume leadership. Built-in systems are expanding most quickly as OEM electrified chassis architectures emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States desert corridors consume RV batteries for extended off-grid autonomy, while European markets prioritize compact lithium systems for seasonal touring. Asian procurement concentrates on cell manufacturing scale rather than end-use deployment.
United States
Southwestern boondocking clusters in Arizona and New Mexico drive 300Ah lithium system demand among full-time remote workers. The Inflation Reduction Act's domestic content bonuses redirect cell procurement toward North American assembly plants. Elkhart, Indiana anchors motorcoach OEM integration of factory-installed battery management electronics.
Germany
Seasonal caravan touring favors lightweight lithium iron phosphate retrofits for Alpine mobility constraints. REACH regulations govern chemical substance registration in battery electrolyte formulations. Baden-Württemberg industrial zones host precision battery management system firmware development for European OEM partnerships.
China
Cell manufacturing expansion feeds global RV battery pack assembly rather than domestic recreational vehicle end-use. GB standards for lithium cell safety testing create export certification requirements for North American-bound production. Guangdong Province foundries dominate cylindrical cell output for international battery assemblers.
Canada
Remote wilderness camping in British Columbia and Alberta sustains deep-cycle capacity requirements for extended off-grid operation. Transport Canada proposals for onboard energy storage in recreational vehicles align with NHTSA regulatory developments. Ontario-based distributors manage cross-border logistics for US motorcoach OEM supply chains.
Australia
Remote outback touring multiplies solar-battery hybrid configurations for self-sufficient caravan configurations. The country's national energy regulator oversees grid-interconnection standards for mobile energy storage systems. Queensland and Western Australia camping corridors concentrate demand for ruggedized AGM and gel constructions in harsh climate conditions.
RV Battery Market Competitive Landscape
Capability concentration sits with lithium chemistry specialists; scale advantage sits with legacy lead-acid foundry networks. The market structures around three tiers: integrated motorcoach OEM suppliers, independent aftermarket retrofitters, and cell-level component providers. Strategic archetypes include Pennsylvania-based lead-acid manufacturers sustaining domestic production scale, lithium iron phosphate specialists targeting premium retrofit installations, and deep-cycle flooded battery incumbents controlling campground dealer channels. Dominant competitive moves encompass factory-install partnerships with electrified chassis OEMs and dealer network expansion for drop-in lithium replacements.
Among established lead-acid manufacturers, East Penn Manufacturing and Exide Technologies exemplify scale-driven domestic production archetypes. Trojan Battery Company occupies a position within the deep-cycle flooded segment through historical dealer channel relationships. RELiON Battery and Battle Born Batteries represent the lithium iron phosphate specialization tier targeting premium motorcoach and fifth-wheel retrofit demand. Johnson Controls and Clarios anchor diversified industrial battery portfolios extending into recreational vehicle applications.
| Leading Market Players |
|---|
| East Penn Manufacturing |
| Exide Technologies |
| EnerSys |
| Crown Battery Manufacturing Company |
| Clarios |
| RELiON Battery |
| Trojan Battery Company |
| Battle Born Batteries |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price volatility determines both the spread between premium lithium-ion and economy lead-acid tiers and the geographic configuration of cell sourcing for North American pack assemblers. Raw material swings compress margins for battery management system integrators while redirecting procurement toward vertically integrated foundries.
Pricing Analysis
Price spreads between Arizona desert corridor installations and Midwest dealer lot transactions reflect delivery cost differentials and installation complexity premiums. Three-tier pricing structure across premium factory-integrated lithium, standard aftermarket drop-in replacements, and economy flooded lead-acid separates full-time remote workers from weekend campers. Cost compression in entry-level towable segments is intensifying because OEM pre-certification programs capture Inflation Reduction Act credits faster than independent retrofitters. Entry-level towable buyers exhibit highest price sensitivity; premium motorcoach owners prioritize cycle life over upfront capital.
Supply Chain Analysis
China's GB standards for lithium cell safety testing restrict technology flows to North American assembly plants, creating export certification bottlenecks that reshape procurement timelines. Cell manufacturing concentrates in China, South Korea, and Japan; pack assembly and battery management system integration centers on US and Mexican facilities. Raw material dependencies span lithium carbonate from South American brine operations, copper current collectors from Chilean smelters, and electrolyte salts from Chinese chemical processors. Single-source vulnerability runs through cylindrical cell supply from Guangdong Province foundries. Distribution runs through Elkhart, Indiana OEM integration hubs and independent RV service center networks across southwestern camping corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among full-time remote-work motorcoach owners who demand factory-integrated systems, fragmenting price negotiation leverage across independent retrofit channels.
For Market Incumbents: Pre-empt emerging lithium iron phosphate specialists by locking exclusive factory-install partnerships with electrified chassis OEMs before NHTSA safety standards finalize. Secure backward integration into North American cell assembly to capture Inflation Reduction Act domestic content bonuses and defend margin position against Chinese foundry cost advantages. For New Entrants and Emerging Players: Independent RV service centers in Arizona and New Mexico represent the most penetrable entry point for drop-in lithium replacements, as dealer network retrofit channels remain underpenetrated by established brands. Target solar-battery hybrid configurations for desert boondocking clusters through technician certification programs that address battery management system firmware complexity. For Investors and Strategic Acquirers: The market sits at a chemistry-transition phase that favors lithium iron phosphate specialists with OEM pre-certification capabilities over legacy lead-acid scale players. Long-term viability over the next decade hinges on factory-install partnership depth rather than aftermarket brand recognition. Watch NHTSA onboard energy storage proposals as the signal for regulatory inflection that would accelerate electrified chassis adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Install Partnership | Locks OEM service relationships through warranty terms and captures clean energy credits fastest. |
| Domestic Cell Assembly Scale-Up | Positions pack manufacturers to qualify for Inflation Reduction Act domestic content bonuses. |
| Technician Certification Program | Addresses battery management system firmware complexity that fragments independent service center capability. |
| Solar-Battery Hybrid Configuration | Targets Arizona and New Mexico desert camping clusters with specialized autonomy solutions. |
| Electrified Chassis Integration | Aligns with motorcoach OEM high-voltage energy storage architectures emerging from NHTSA developments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with RV dealership operations managers, battery pack procurement leads at motorcoach OEMs, independent service center technicians, and campground network distribution heads. Secondary validation drew from NHTSA regulatory filings, EPA hazardous waste rule dockets, China GB standards documentation, and customs trade data for lithium cell imports. Bottom-up installation forecasts triangulated against top-down motorcoach production estimates.
Calibration against historical replacement cycle data and chemistry adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include battery chemistry tier, installation type, application intensity, and regional camping corridor concentration. CAGRs derived from installed base turnover rates and factory-install penetration assumptions. Industry-specific inputs incorporated Inflation Reduction Act credit eligibility timelines and NHTSA proposal comment period developments.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, cross-border tariff regimes, or remote-work normalization rates would shift the trajectory. Forecasts reflect documented assumptions about cell cost decline curves and OEM electrification commitments. Material shifts in NHTSA final rule language or China export certification processing delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Towing Equipment Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Bicycle Frames Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Navigation Light Market
Vehicle Components
EGR Coolers Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Bicycle Chain Tensioner Market