
 Micro Mobility Market | 2026-2036
Micro Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Mobility Market Intelligence
The availability of a flexible gig economy workforce for battery swapping and vehicle rebalancing is redrawing the operational landscape for shared fleet operators. Lime Micromobility leverages its advanced software platform to optimize fleet deployment and manage demand surges in major urban centers. Bird Global, Inc. competes on securing exclusive city-level permits and building strong brand recognition among consumers. Concurrently, NIU Technologies differentiates through its focus on hardware design and manufacturing, supplying both consumers and fleet operators.
Micro mobility encompasses a category of lightweight, single-occupant vehicles, including e-scooters and e-bikes, designed for short-distance urban travel. These devices typically operate at speeds below 45 km/h and provide a solution for first- and last-mile transportation gaps. E-scooters currently constitute the largest vehicle type segment due to their convenience and minimal physical footprint. While rental services remain the dominant service type for public use, direct ownership and subscription models are gaining favor among professionals seeking consistent access.
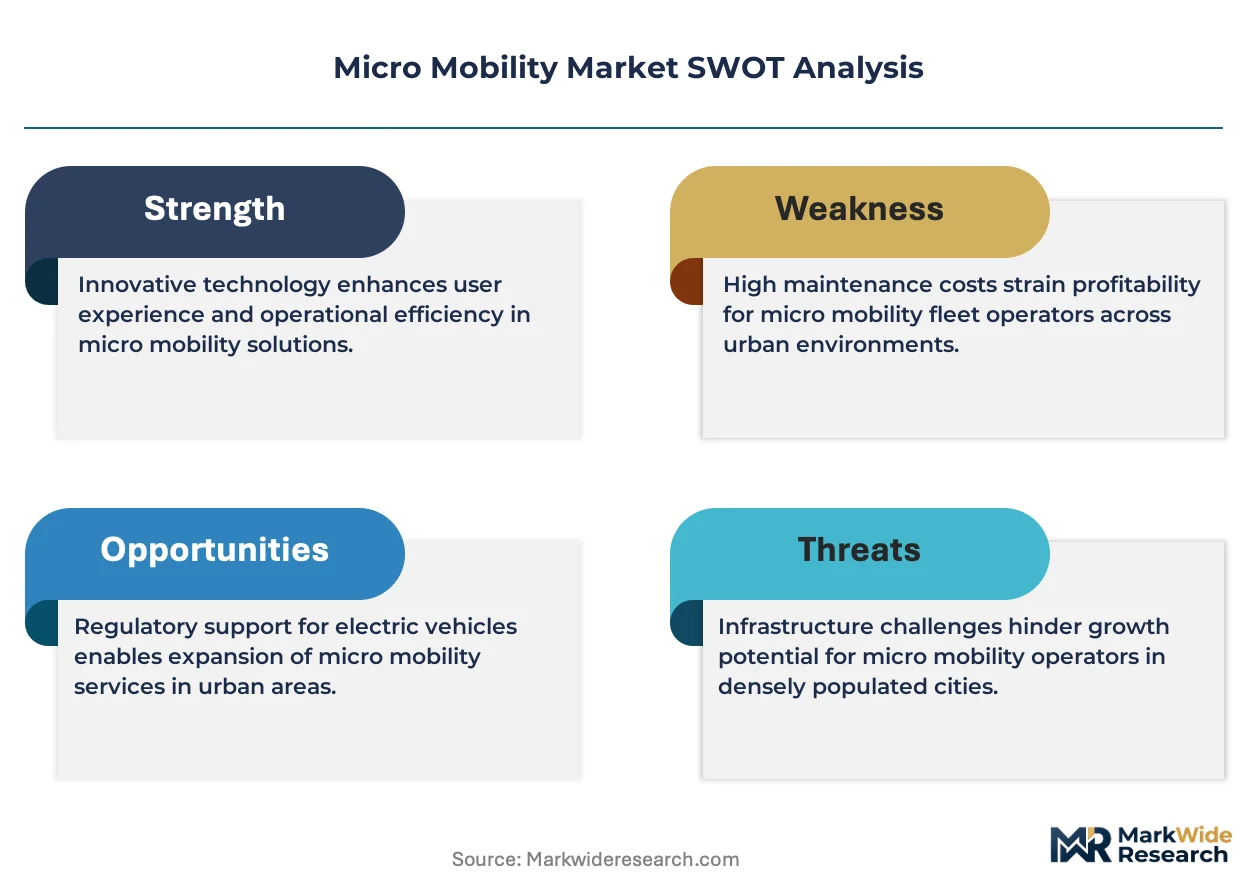
Regulatory frameworks from bodies like the US Department of Transportation and Germany's Kraftfahrt-Bundesamt (KBA) establish critical safety standards and vehicle type-approvals. City-specific ordinances, such as those implemented in Paris and Singapore, directly govern operational zones, fleet caps, and parking rules, which determines market access. Operator success depends on navigating this complex patchwork of local regulations while maintaining fleet profitability and ensuring public safety.
Market Dynamics
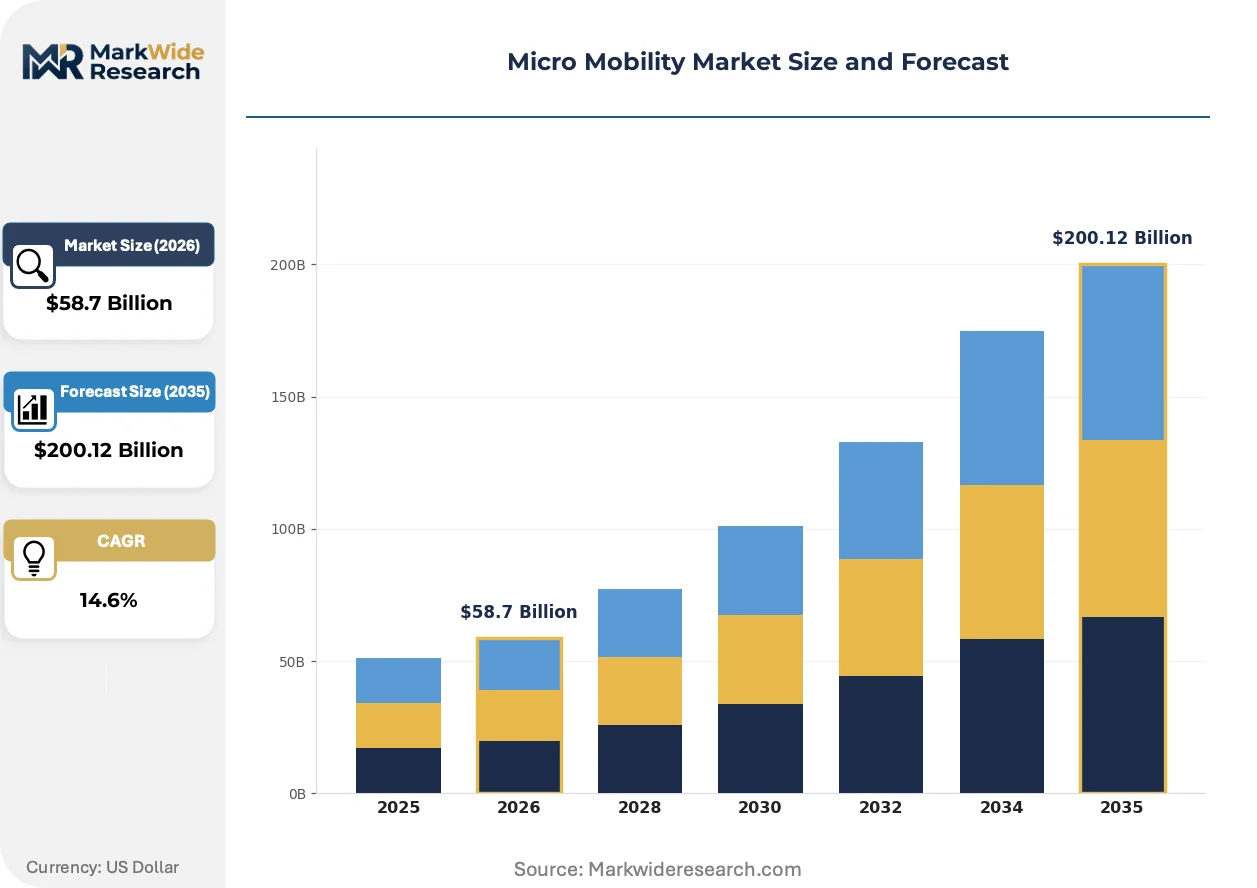
The central dynamic shaping the micro mobility market is the conflict between accelerating consumer demand for last-mile solutions in congested cities and the fragmented, often restrictive, regulatory frameworks imposed by municipal governments trying to manage public space and safety.
Growth Catalysts
- Policy Mandates for Decarbonization:The implementation of the EU Green Deal and similar low-emission zone policies in urban centers creates a direct incentive for commuters to adopt electric micro mobility vehicles as alternatives to personal cars for short-distance travel.
- Urban Infrastructure Development:Investment in dedicated and protected lanes for e-bikes and e-scooters in high-density cities across China and Europe improves rider safety and encourages modal shift, making micro mobility a more viable and integrated part of the urban transport fabric.
- Battery Technology Advancement:Continuous improvements in lithium-ion battery energy density and reductions in manufacturing cost lower the total cost of ownership for both consumers and fleet operators, making vehicle acquisition and battery swapping operations more economically feasible.
Market Restraints
- Fragmented Regulatory Approvals:The lack of standardized regulations, with each city like Paris or Singapore imposing unique fleet caps, operational zones, and parking rules, creates significant operational complexity and cost for operators attempting to scale across multiple geographies.
- Limited Vehicle Lifespan:Shared vehicles are subject to intensive use, vandalism, and exposure to the elements, resulting in a short operational lifespan that pressures operator profitability through high capital expenditure cycles for fleet replacement and maintenance.
- Public Space and Parking Conflicts:Improperly parked scooters and bikes can obstruct pedestrian pathways, leading to public backlash and stricter municipal regulations. This social friction and lack of dedicated parking infrastructure constrain organic fleet expansion in dense areas.
Strategic Opportunities
- Expansion into Emerging Markets:Untapped demand exists in densely populated urban centers in Latin America and Southeast Asia, where traffic congestion is severe and public transit systems are often overburdened, presenting a significant white-space opportunity for shared fleet operators.
- Subscription-Based Service Models:Developing subscription services for professionals offers a recurring revenue stream and caters to users who need consistent, reliable access to a vehicle without the upfront cost and maintenance responsibilities of direct ownership.
- Integration with Public Transit Systems:Partnering with municipal transit authorities to integrate micro mobility services into a unified Mobility-as-a-Service (MaaS) platform provides a seamless first- and last-mile solution that enhances the utility of the entire public transportation network.
Industry Challenges
- Operational Profitability at Scale:Achieving positive unit economics remains a primary challenge, with high costs associated with daily battery swapping, vehicle rebalancing to meet demand, and repairs for a constantly depreciating asset base pressuring operator margins.
- Ensuring Rider and Public Safety:Operators face the challenge of managing liability and insurance costs related to accidents, while also investing in rider education and technology-based safety features to mitigate risks and maintain a positive public perception.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Mobility Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $200.12 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: E-Bikes, E-Scooters, Electric Skateboards, Hoverboards Charging Method: Plug-in Charging, Inductive Charging, Solar Charging, Battery Swap User Demographic: Students, Professionals, Tourists, Daily Commuters Service Type: Rental Services, Subscription Models, Ownership, Fleet Services |
| Companies Covered | Tier Mobility, Helbiz, Lime Micromobility, Segway-Ninebot, Bolt Technology, Bird Global, Inc., Dott, NIU Technologies, Voi Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Mobility Market Strategic Shifts & Innovations
Software and data analytics are reshaping the operational core of micro mobility. The competitive landscape is shifting from a focus on hardware and market presence to an emphasis on platform intelligence for optimizing fleet efficiency and profitability.
Advanced telematics units and embedded IoT sensors provide real-time location tracking, component diagnostics, and battery health monitoring. Shared fleet operators are rapidly adopting this technology to gain granular control over their assets. This integration of powerful computing into vehicle systems is miniaturizing the external hardware required for fleet management, shifting value from the physical scooter to the underlying data platform.
Regulatory frameworks like Germany's Kraftfahrt-Bundesamt (KBA) type-approval process are setting higher standards for vehicle safety and build quality. This forces manufacturers to incorporate specific braking, lighting, and speed-limiting technologies, increasing upfront vehicle costs. The e-scooter segment is most affected, as operators must procure KBA-certified models to gain market access in German cities, influencing hardware design globally.
A shift away from purely transactional, per-minute rentals toward monthly subscription services is gaining traction among daily commuters. This model offers users reliable access to a personal-use device, bypassing the availability concerns of public-use fleets. This behavioral change is most pronounced in dense urban centers across the United States and Europe where consistent last-mile transportation is a priority for professionals.
Micro Mobility Market Segmentation
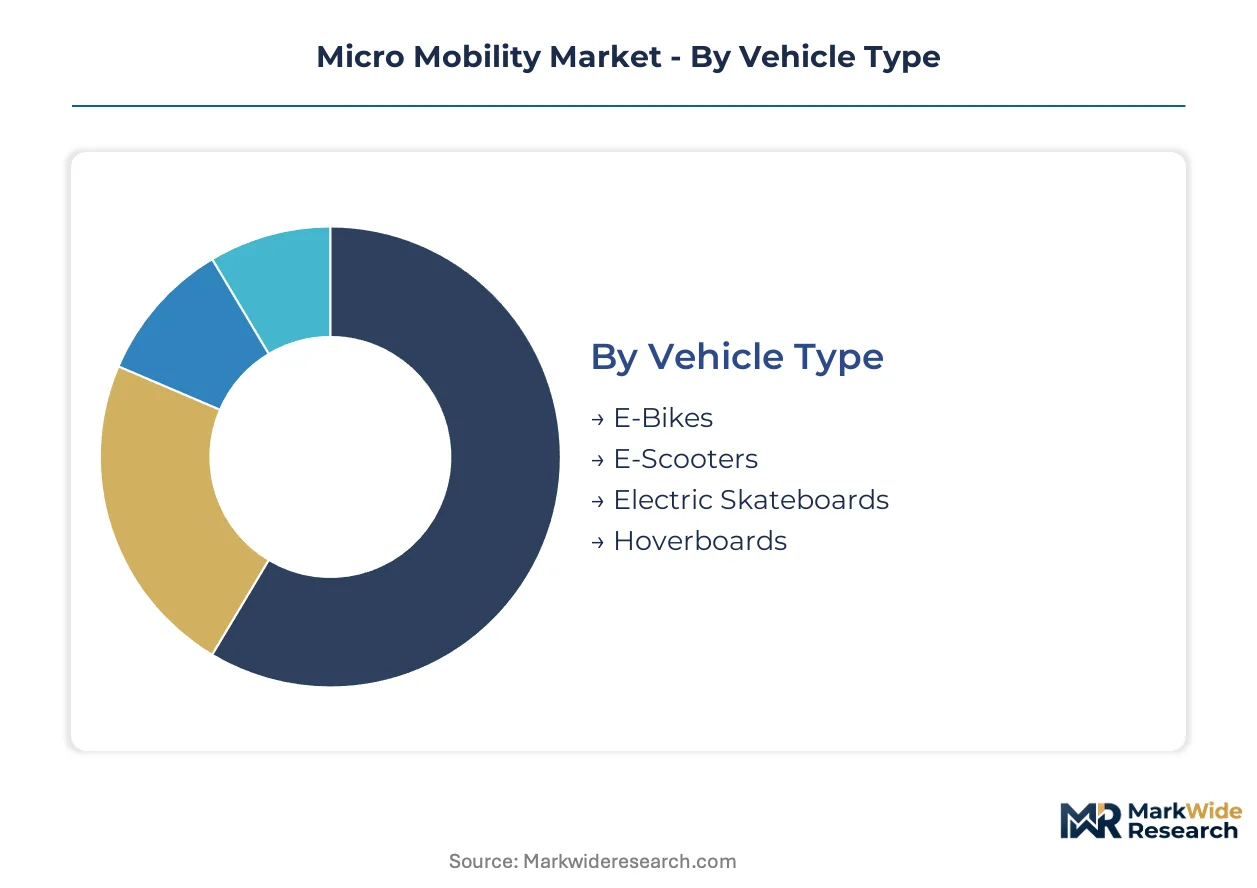
The micro mobility market's segmentation reveals the diverse operational models and user preferences shaping urban transport solutions. Understanding these distinct categories allows operators and policymakers to tailor strategies for efficient deployment and sustainable growth across metropolitan areas.
Vehicle Type:
The vehicle type segment faces significant substitution pressure from traditional public transport and personal vehicles for short-distance travel.
- E-Scooters:These lightweight, stand-up electric vehicles typically operate at speeds below 45 km/h, offering agile navigation in congested urban environments. Demand concentrates in high-density metropolitan areas like Paris and New York, driven by their convenience for last-mile gaps.
- E-Bikes:Electric bicycles provide pedal-assist functionality, extending range and reducing physical exertion compared to conventional bicycles. Their adoption accelerates in cities with dedicated cycling infrastructure, such as Copenhagen and Amsterdam, supporting longer urban commutes.
- Electric Skateboards:These compact, motorized boards offer personal transport for enthusiasts and niche recreational users in urban settings.
- Hoverboards:Self-balancing two-wheeled devices primarily serve recreational purposes, attracting younger demographics in leisure zones.
E-Scooters anchor the volume base while E-Bikes gain share at the steepest rate.
Charging Method:
Charging methods directly influence operational efficiency and the total cost of ownership for fleet operators.
- Battery Swap:This method involves replacing depleted battery packs with fully charged ones, minimizing vehicle downtime and optimizing fleet availability. It is crucial for shared fleet operators in cities like Berlin and Shanghai, where rapid rebalancing and high utilization are essential for profitability.
- Plug-in Charging:Vehicles are directly connected to an electrical outlet for recharging, a common practice for privately owned micro mobility devices. This method dominates in residential areas and workplaces across the United States, offering straightforward user convenience for personal devices.
- Inductive Charging:Wireless power transfer recharges batteries through electromagnetic fields, offering potential for automated charging infrastructure in public spaces.
- Solar Charging:Integrated solar panels on vehicles or charging stations provide supplementary power, extending range or reducing grid dependency in sunny regions.
Battery Swap drives operational efficiency, contrasting with Plug-in Charging's direct user convenience.
User Demographic:
User demographic segments exhibit varying levels of demand elasticity and distinct usage patterns across urban environments.
- Daily Commuters:This demographic relies on micro mobility for routine first- and last-mile connections to public transit or direct office commutes. Their demand is consistent in major urban centers like London and Tokyo, driven by the need to avoid traffic congestion.
- Professionals:Professionals seek reliable, consistent access to micro mobility for business meetings, client visits, or regular commutes within city limits. This segment shows high engagement with subscription models in dense business districts across Europe and the US, valuing guaranteed availability.
- Students:Students utilize micro mobility for campus travel and short trips, prioritizing affordability and convenience for their daily routines.
- Tourists:Tourists use micro mobility for sightseeing and recreational exploration, with demand peaking in leisure districts and during holiday seasons.
The demand from Daily Commuters remains consistent, while Tourists exhibit higher seasonal variations.
Service Type:
Service type offerings dictate the revenue models and margin structures for micro mobility providers.
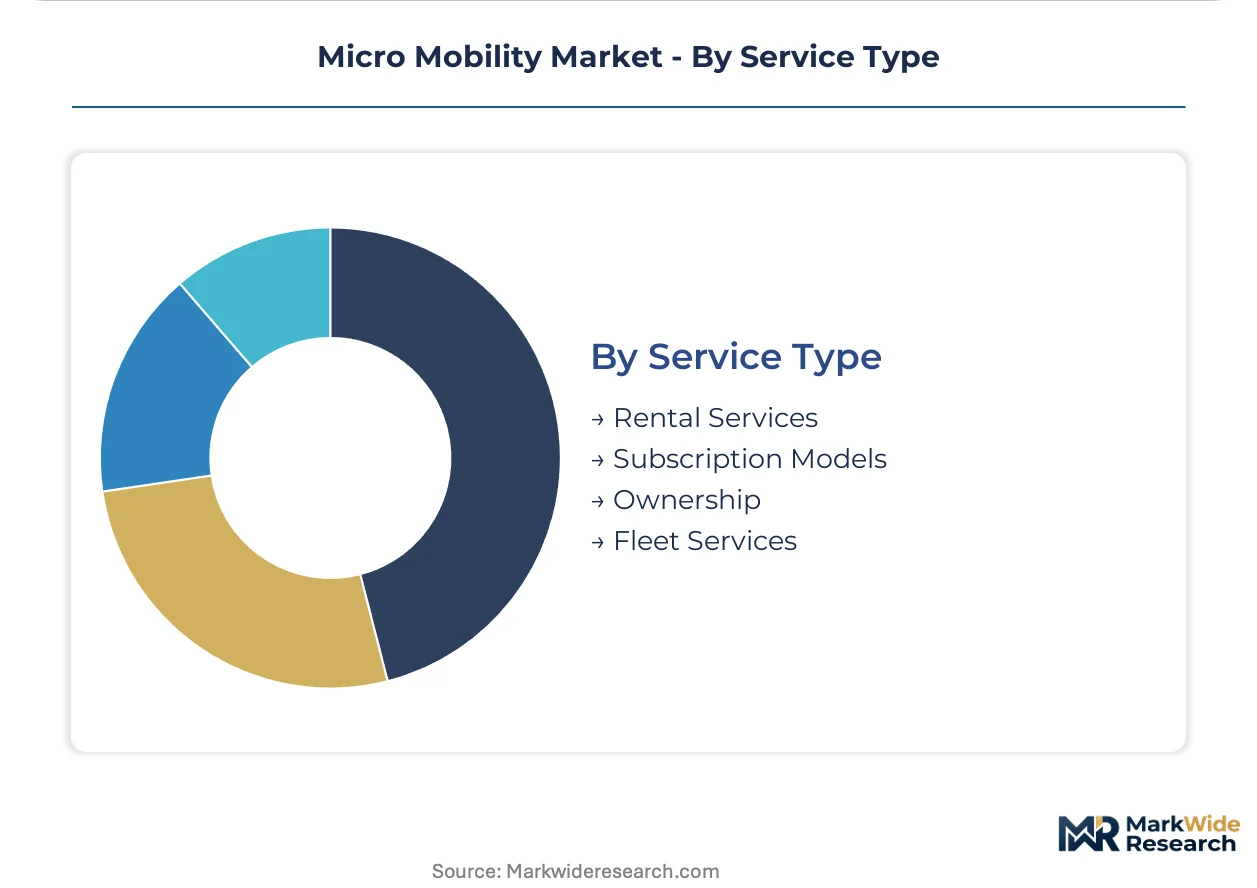
- Rental Services:These services provide on-demand access to vehicles for short durations, typically billed per minute or per ride, without long-term commitment. Rental services remain dominant in cities globally, including Singapore and Sydney, offering flexible public access to shared fleets.
- Subscription Models:Users pay a recurring fee for unlimited or tiered access to a personal micro mobility device, often for a month or longer. This model appeals to professionals in cities like New York and Berlin, who prioritize consistent vehicle availability over sporadic use.
- Ownership:Direct purchase of micro mobility vehicles provides users with complete control and eliminates recurring rental fees for personal use.
- Fleet Services:Businesses or organizations acquire fleets of micro mobility devices for internal use, employee transport, or specific logistical operations.
Rental Services represent the traditional market entry point, but Subscription Models offer enhanced revenue predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for micro mobility vehicles differs significantly across urban landscapes globally. In some developed markets, subscription models gain traction among professionals seeking consistent access, while emerging economies prioritize rental services for broad accessibility. This geographic variation influences infrastructure investment and regulatory approaches, shaping regional market dynamics.
United States
Demand for e-scooters and e-bikes is high among daily commuters and professionals seeking efficient last-mile solutions. The US Department of Transportation establishes safety guidelines for vehicle types, impacting operator deployment strategies. Major urban centers like New York City and San Francisco see high usage, leading to city-specific parking rules and operational zones.
Germany
Policy mandates for decarbonization, including the EU Green Deal, drive micro mobility adoption in German cities. Germany's Kraftfahrt-Bundesamt (KBA) enforces stringent type-approval processes for e-scooters, ensuring high safety standards. Berlin and Munich actively invest in dedicated cycling infrastructure, integrating micro mobility into public transport networks.
China
Rapid urbanization and severe traffic congestion fuel last-mile micro mobility demand across Chinese metropolitan areas. Local city governments implement operational zones and fleet caps to manage public space and ensure safety. Shanghai and Beijing represent major growth hubs, with significant investment in shared fleet services and hardware manufacturing.
France
Paris experiences strong demand for micro mobility, particularly for short-distance urban travel and tourism, despite stringent local regulations. City-specific ordinances in Paris directly govern fleet caps, operational zones, and parking rules. Lyon and Marseille are also seeing increased e-bike and e-scooter usage, supported by municipal initiatives for sustainable transport.
Singapore
High population density and efficient public transit systems create first- and last-mile demand for micro mobility in Singapore. Singapore's Land Transport Authority (LTA) sets strict regulations for device usage, parking, and operator licensing. The city-state actively integrates micro mobility into its smart city transportation network to enhance urban connectivity.
Micro Mobility Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that focuses on niche hardware or regional operations. The market structure exhibits a tiered consolidation, with a few large operators dominating shared fleet services across multiple geographies. Strategic archetypes include platform-centric providers optimizing fleet deployment, hardware manufacturers supplying both consumers and operators, and regional specialists adapting to local regulations. Companies frequently engage in strategic partnerships with city governments and invest in technology licensing for advanced software platforms.
Within the platform-centric tier, Lime Micromobility and Bird Global, Inc. exemplify operators leveraging advanced software for fleet deployment and demand management. These companies anchor significant market share in major urban centers globally, often competing for exclusive city-level permits and building strong brand recognition. NIU Technologies, a Chinese company, sits within the hardware manufacturing archetype, differentiating through its focus on vehicle design and production. This approach serves both direct consumers and shared fleet operators, providing a distinct market position by emphasizing hardware quality and innovation.
| Leading Market Players |
|---|
| Tier Mobility |
| Helbiz |
| Lime Micromobility |
| Segway-Ninebot |
| Bolt Technology |
| Bird Global, Inc. |
| Dott |
| NIU Technologies |
| Voi Technology |
| Others |
Cost & Logistics Intelligence
Scale economies in fleet management and battery logistics are central to micro mobility operations. This operational scale influences both supply chain efficiency and the competitive price floor for services.
Pricing Analysis
Transactional models dominate rental services, billing users per minute or per ride for on-demand access. Subscription models, conversely, offer professionals recurring monthly fees for consistent vehicle access. Price differentiation stems from geographic delivery costs across various cities and specific vehicle quality certifications like Germany's KBA approval. Pricing softness reflects intense competition among operators for city-level permits and user adoption. Students exhibit high price sensitivity, prioritizing affordability, while professionals value consistent availability over minimal cost.
Supply Chain Analysis
Inventory management for shared fleets requires precise rebalancing and rapid battery swapping cycles. China concentrates the manufacturing of e-scooters and e-bikes, with key components also sourced from Taiwan and South Korea. Lithium-ion battery cells, electric motors, and advanced telematics units are critical inputs across the sector. Single-source vulnerability for specialized components presents a significant supply chain risk. Distribution runs through a mix of direct sales to consumers, bulk procurement by fleet operators, and regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micro mobility market is in an early-cycle expansion phase, driven by accelerating adoption among daily commuters in congested urban areas. Policy mandates for decarbonization further catalyze this penetration.
For Market Incumbents: Consolidate market share by securing exclusive city-level permits and expanding integrated Mobility-as-a-Service (MaaS) partnerships with public transit. Invest in advanced software platforms for predictive rebalancing and enhanced asset utilization to counter margin pressure from limited vehicle lifespan. Prioritize R&D in battery technology and modular vehicle design to reduce capital expenditure cycles.
For New Entrants and Emerging Players: Unmet demand for reliable, personal-use micro mobility in suburban corridors presents a clear service-layer gap. Target subscription-based models for professionals in dense business districts across Europe and the US, emphasizing guaranteed vehicle availability. A strong go-to-market angle involves integrating with corporate wellness programs or university campus transportation solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators successfully scaling subscription services for professionals, indicating long-term viability over the next 5-10 years. Seek acquisition targets with proprietary software platforms for fleet optimization and strong city-level regulatory relationships. The signal to watch is sustained positive unit economics across multiple metropolitan areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Fleet to Emerging Markets | Accesses untapped demand in urban centers with severe congestion and overburdened public transit. |
| Develop Advanced Telematics | Enhances real-time asset tracking, diagnostics, and predictive maintenance for operational efficiency. |
| Form Public Transit Partnerships | Integrates micro mobility into MaaS platforms, offering seamless first- and last-mile solutions. |
| Invest in Battery Swapping Infrastructure | Minimizes vehicle downtime and optimizes fleet availability, crucial for operator profitability. |
| Secure City-Specific Permits | Establishes market access and operational zones, crucial for scaling shared fleet services. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings of this study. Interviews were conducted with fleet operators, urban planners, battery technology specialists, and regulatory affairs managers. Secondary sources included academic journals, government reports from the US Department of Transportation and Germany's Kraftfahrt-Bundesamt (KBA), and industry association publications. A bottom-up and top-down triangulation approach ensured data consistency.
Sensitivity analysis was applied to key market variables to model various growth scenarios over the projection horizon. The analytical framework incorporates segmentation dimensions such as vehicle type, charging method, user demographic, and service type, alongside regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected adoption rates. Urban population density and infrastructure investment serve as critical forecast inputs.
Underlying assumptions cover current regulatory stability and technological advancement rates, with deviation risk concentrated in unforeseen policy shifts or rapid competitive disruption. Forecasts reflect these assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
Electric Kick Scooters Market