
 Monk Fruit Sugar Market | 2026-2036
Monk Fruit Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Monk Fruit Sugar Market Intelligence
China is reconfiguring raw material supply chains for monk fruit extracts through expanded cultivation in Guilin and surrounding prefectures. GLG Life Tech Corp leverages backward integration into monk fruit farming to secure extract consistency. Tate & Lyle sustains formulation partnerships with multinational beverage brands seeking clean-label positioning. Guilin Layn Natural Ingredients Corp anchors regional processing capacity with proprietary extraction infrastructure.
Monk fruit sugar refers to sweeteners derived from Siraitia grosvenorii fruit, containing mogrosides that deliver 150-300 times the sweetness intensity of sucrose with negligible caloric content. The extraction process isolates mogroside V as the primary functional compound for commercial applications. Powder formats dominate current volume flows due to handling efficiency in industrial food manufacturing. Liquid extract applications in ready-to-drink beverages represent the fastest-expanding segment as brands reformulate to reduce added sugars. Bakery product adoption remains nascent, constrained by heat-stability limitations during high-temperature processing cycles.
FDA GRAS determinations shape United States market access requirements for novel sweetener ingredients, while China's NMPA and SAMR oversee food additive safety assessments and GB standard compliance for domestic and export-bound production. The European Food Safety Authority evaluates novel food applications under centralized EU procedures, creating divergent approval timelines across jurisdictions. Stakeholders must monitor evolving threshold definitions for added-sugar labeling and front-of-pack warning systems that directly influence reformulation incentives.
Market Dynamics
Clean-label reformulation mandates across beverage and packaged food sectors are compressing monk fruit extract adoption timelines, as manufacturers race to replace synthetic sweeteners before front-of-pack warning systems activate.
Growth Catalysts
- US FDA GRAS pathway:Self-affirmed GRAS determinations for mogroside V enable rapid commercialization without pre-market approval delays, accelerating formulation shifts in carbonated drinks and sports nutrition.
- Beverage sector clean-label mandates:Major soft drink producers are stripping artificial sweeteners from flagship lines, creating immediate procurement demand for natural high-intensity alternatives with negligible caloric impact.
- Guilin cultivation cluster expansion:Dedicated monk fruit farming zones in Guangxi Zhuang Autonomous Region are stabilizing raw material throughput for extract processors serving export markets.
Market Restraints
- Mogroside V extraction yield volatility:Batch-to-batch potency variation in Siraitia grosvenorii fruit complicates standardization for industrial buyers requiring consistent sweetness equivalence.
- EU novel food authorization timelines:EFSA centralized assessment procedures for monk fruit extracts extend market entry delays by 18-36 months versus US regulatory pathways.
- Stevia extract price competition:Established rebiana supply chains and economies of scale in stevia processing constrain monk fruit premium pricing power in commodity sweetener tenders.
Strategic Opportunities
- Bakery heat-stability gap:Encapsulation technology partnerships with industrial ingredient houses could unlock high-temperature applications currently blocked by mogroside thermal degradation.
- China domestic functional food expansion:NMPA health food registration pathways for monk fruit-sweetened formulations target aging-population diabetes management segments.
- Direct-to-manufacturer liquid extract channels:Bulk tanker delivery systems bypassing powder reconstitution are capturing ready-to-drink beverage contracts from traditional distributor networks.
Industry Challenges
- Extraction chemistry specialization shortage:Industrial-scale isolation of high-purity mogroside V requires chromatography expertise concentrated among a limited pool of natural products chemists in Guangdong and Zhejiang provinces.
- Dual-carbon compliance retrofit costs:China's MEE emissions standards for solvent-based extraction facilities are forcing capital expenditure cycles for regional processors dependent on ethanol recovery systems.
- Organic certification traceability gaps:Smallholder farming fragmentation across Guilin prefecture complicates USDA Organic and EU Organic supply chain documentation for export-bound extracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monk Fruit Sugar Market |
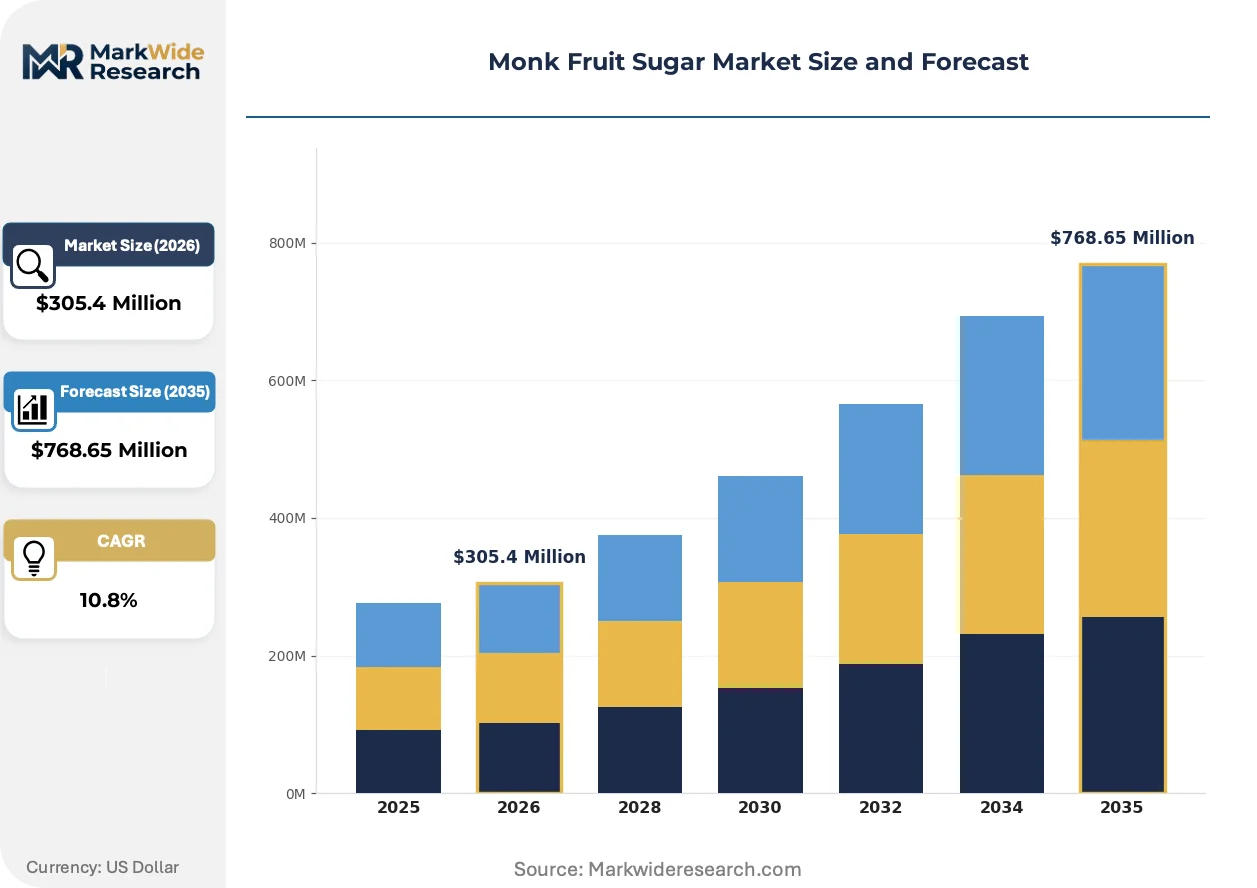
| Market Size in 2026 | $305.4 Million |
| Market Size in 2035 | $768.65 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder, Granulated, Tablets Application: Beverages, Bakery Products, Sauces, Snacks End User: Food Manufacturers, Restaurants, Retail Consumers, Healthcare Providers Packaging Type: Bulk Packaging, Retail Packaging, Sachets, Tubs |
| Companies Covered | Archer Daniels Midland Company, Tate & Lyle, GLG Life Tech Corp, Monk Fruit Corp, Steviva Brands, Guilin Layn Natural Ingredients Corp, Cargill, Apura Ingredients, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monk Fruit Sugar Market Strategic Shifts & Innovations
Monk fruit extract processing is undergoing rapid technological substitution as continuous extraction systems displace batch methods, while regulatory jurisdictions compete to establish dominant safety assessment frameworks for novel natural sweeteners.
Membrane filtration technology is virtualizing traditional solvent-based mogroside isolation by enabling aqueous extraction with reduced ethanol dependence. European flavor houses and North American beverage co-manufacturers are piloting these systems at 500-liter scale. The shift is compressing extraction facility permitting timelines in jurisdictions with strict volatile organic compound regulations.
China's SAMR is tightening GB 2760 food additive standard enforcement for monk fruit extract purity markers, requiring third-party laboratory verification of mogroside V content claims. Domestic producers are consolidating testing capabilities to avoid shipment rejections at port. Export-oriented extractors in Guilin are prioritizing ISO 17025-accredited laboratory partnerships over in-house quality systems.
Ingredient procurement by multinational food manufacturers is rotating toward long-term offtake agreements with backward-integrated farming operations. CPG procurement teams are bypassing trading houses to secure multi-year volume commitments directly with Guangxi-based processors. This pattern concentrates contract flows through three to five vertically structured suppliers with captive cultivation acreage.
Monk Fruit Sugar Market Segmentation
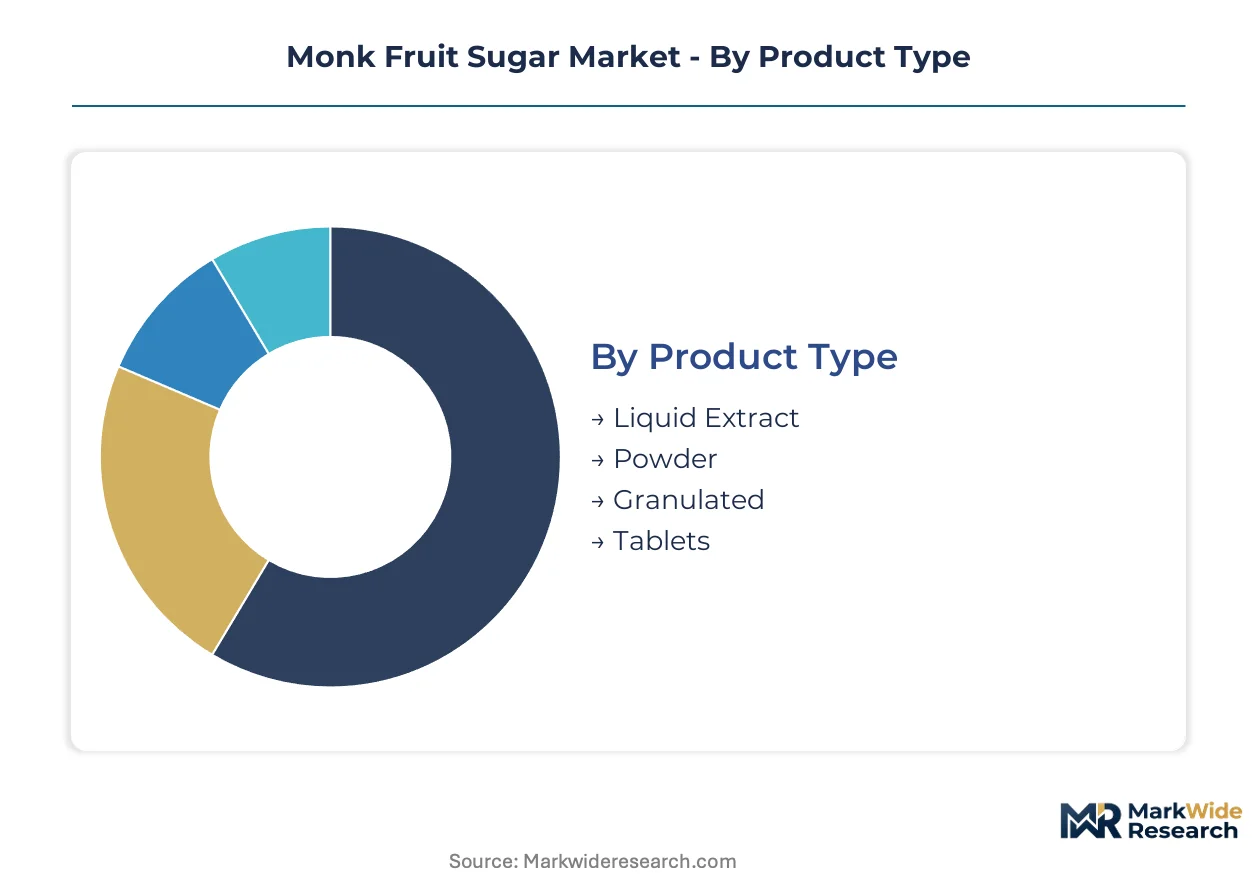
Monk fruit sugar markets fragment across four functional dimensions that determine pricing power, regulatory exposure, and channel strategy. Product form dictates extraction investment and shelf stability. Application verticals separate high-volume beverage contracts from specialized healthcare formulations. End-user concentration shapes direct sales versus distributor economics.
Product Type:
Mature powder formats coexist with emerging liquid delivery systems that bypass reconstitution steps in beverage manufacturing.
- Powder:Spray-dried mogroside V concentrates dominate industrial procurement for baked goods and dry mixes. Food manufacturers in the United States specify powder for handling efficiency in high-speed blending operations and extended ambient storage.
- Liquid Extract:Aqueous solutions with standardized sweetness equivalence enable direct dosing in ready-to-drink production lines. Beverage co-manufacturers in North America are shifting procurement toward bulk tanker deliveries to eliminate powder rehydration.
- Granulated:Crystalline blends with bulking agents serve tabletop sweetener retail positioning. European private-label brands specify granulated formats for consumer familiarity in sugar-replacement messaging.
- Tablets:Compressed single-serve units target foodservice portion control and on-the-go consumption. Coffee chain operators in East Asia pilot tablet dispensers for consistent sweetness dosing.
Powder handles the majority of throughput; liquid extract is the fastest mover on share.
Application:
Cost tier separation distinguishes commodity beverage volumes from premium healthcare positioning.
- Beverages:Carbonated soft drinks, sports nutrition, and functional waters absorb the largest extract volumes. FDA GRAS-enabled reformulation by multinational brands drives procurement scale for high-purity mogroside V.
- Bakery Products:Heat-stability limitations constrain penetration in high-temperature processing. Encapsulation technology partnerships with industrial ingredient houses could unlock cookies and pastry applications currently blocked by thermal degradation.
- Sauces:Condiment manufacturers leverage monk fruit for clean-label ketchup and dressing lines. Reduced-sugar claims on front-of-pack labels trigger reformulation mandates in United States retail channels.
- Snacks:Protein bars and dried fruit coatings represent emerging adoption. Snack producers target reduced-added-sugar certifications for shelf placement advantages in health-focused retail segments.
Beverages absorb the dominant volume share; bakery applications are climbing the fastest despite technical barriers.
End User:
Customer type concentration determines contract structure, with food manufacturers demanding multi-year offtakes and healthcare providers requiring batch documentation.
- Food Manufacturers:CPG procurement teams negotiate direct supply agreements with Guangxi-based processors. Backward-integrated suppliers with captive cultivation acreage capture long-term volume commitments bypassing trading houses.
- Restaurants:Foodservice distributors specify liquid concentrates for fountain beverage systems. Chain operators in North America test monk fruit-sweetened menu items for clean-label consumer appeal.
- Retail Consumers:Grocery and e-commerce channels move granulated and sachet formats. Private-label penetration in United States mass retail compresses branded pricing power.
- Healthcare Providers:Clinical nutrition and diabetes management programs prescribe monk fruit for glycemic control. NMPA health food registration pathways in China target aging-population therapeutic segments.
Food manufacturers command the largest contract values; healthcare providers are expanding most quickly on regulatory tailwinds.
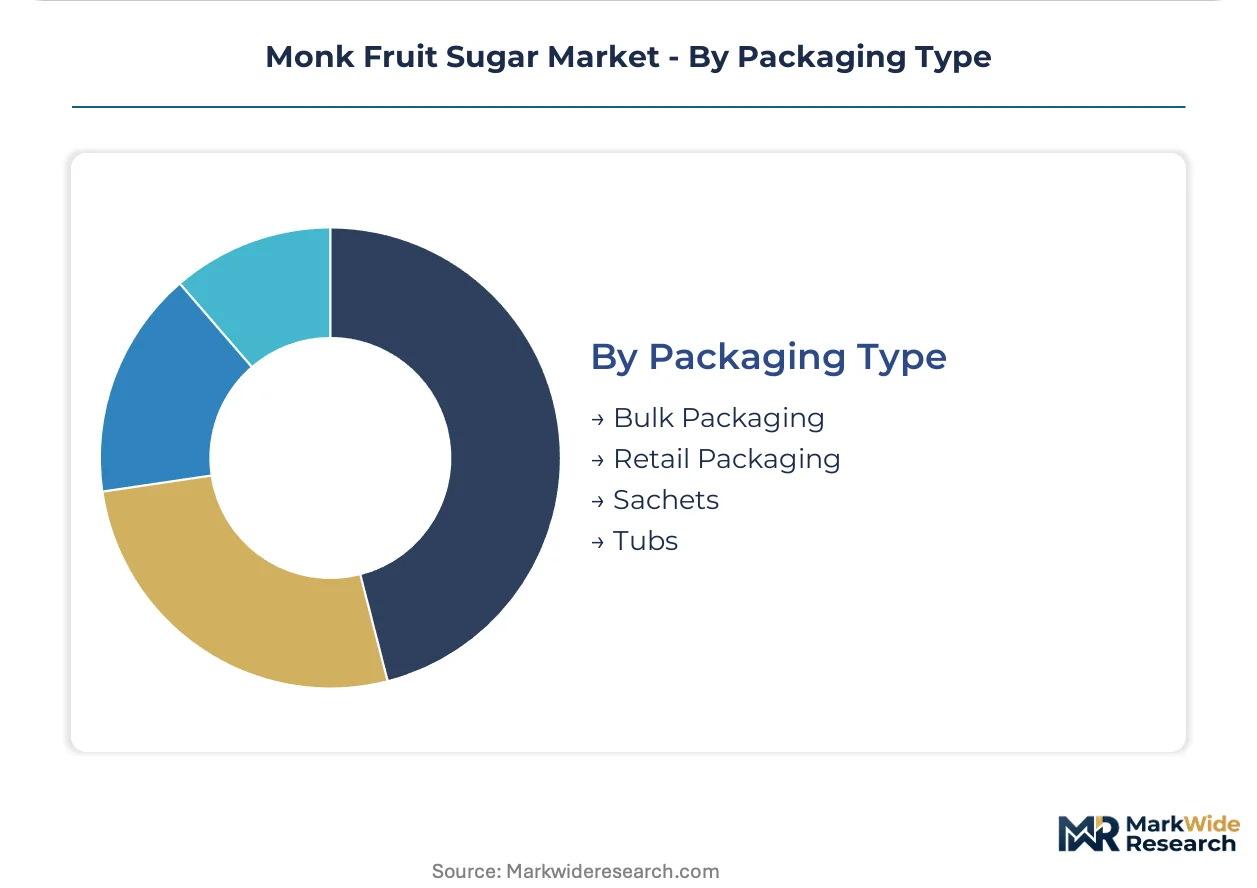
Packaging Type:
Supply concentration in bulk formats reflects industrial demand dominance, while retail packaging fragments across format experimentation.
- Bulk Packaging:Drum and intermediate bulk container shipments serve food manufacturing scale. Direct-to-manufacturer tanker systems for liquid extract are capturing ready-to-drink contracts from traditional distributor networks.
- Retail Packaging:Branded canisters and stand-up pouches target household tabletop substitution. United States natural products retailers allocate shelf space based on organic certification status.
- Sachets:Single-serve stick packs dominate foodservice and hospitality channels. Portion-controlled dosing aligns with front-of-pack sugar reduction mandates in European jurisdictions.
- Tubs:Multi-serve containers serve bakery and foodservice kitchen applications. Commercial bakers in North America specify tubs for recipe-scale measuring efficiency.
Bulk packaging moves the highest tonnage; sachets are gaining share fastest on foodservice portion-control demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific monk fruit extract flows into North American beverage manufacturing, while Rotterdam's liquid bulk terminals handle European distribution for natural sweetener imports.
United States
FDA GRAS determinations for mogroside V accelerate clean-label reformulation across carbonated soft drinks and sports nutrition categories. The Food Safety Modernization Act mandates foreign supplier verification programs for imported extracts. Los Angeles-area beverage co-manufacturers pilot bulk tanker delivery systems to eliminate powder reconstitution steps.
China
NMPA novel food ingredient pathways streamline domestic market entry for monk fruit extract producers targeting functional food applications. SAMR enforces tightening GB 2760 purity standards requiring third-party laboratory verification. Guilin prefecture cultivation clusters in Guangxi Zhuang Autonomous Region stabilize raw material throughput for export-oriented processors.
Germany
EFSA novel food authorization timelines extend market entry delays for monk fruit extracts versus US regulatory pathways. The EU Green Deal drives solvent emission compliance costs for extraction facility operators. Hamburg port logistics clusters coordinate bulk ingredient distribution across continental beverage manufacturing networks.
Japan
METI functional food labeling standards create procurement demand for high-purity mogroside formulations in aging-population diabetes management segments. PMDA oversight of food additive safety assessments shapes import documentation requirements. Kanto region beverage formulators integrate monk fruit into reduced-sugar product lines for domestic retail channels.
Australia
TGA novel food assessments govern monk fruit extract import permissions for food manufacturing applications. Food Standards Australia New Zealand mandates additive labeling disclosure thresholds influencing reformulation incentives. Melbourne and Sydney metropolitan food technology clusters pilot encapsulation partnerships to address heat-stability limitations in bakery applications.
Monk Fruit Sugar Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in extraction chemistry and cultivation. The supplier base concentrates around backward-integrated agricultural processors with captive farming operations and formulation-focused ingredient houses serving multinational beverage contracts. Two archetypes dominate: vertically structured extractors controlling Guangxi cultivation zones, and technology-licensing specialists partnering with industrial flavor houses. Capacity expansion in membrane filtration infrastructure and long-term offtake agreements with CPG procurement teams represent the principal competitive vectors reshaping supply relationships.
Within the vertically integrated tier, GLG Life Tech Corp and Guilin Layn Natural Ingredients Corp occupy positions anchored in Guangxi Zhuang Autonomous Region cultivation infrastructure. Tate & Lyle exemplifies the formulation partnership archetype, sustaining supply relationships with multinational beverage brands seeking clean-label positioning. These three entities represent distinct strategic postures: upstream agricultural control versus downstream formulation integration.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Tate & Lyle |
| GLG Life Tech Corp |
| Monk Fruit Corp |
| Steviva Brands |
| Guilin Layn Natural Ingredients Corp |
| Cargill |
| Apura Ingredients |
| Firmenich SA |
| Others |
Cost & Logistics Intelligence
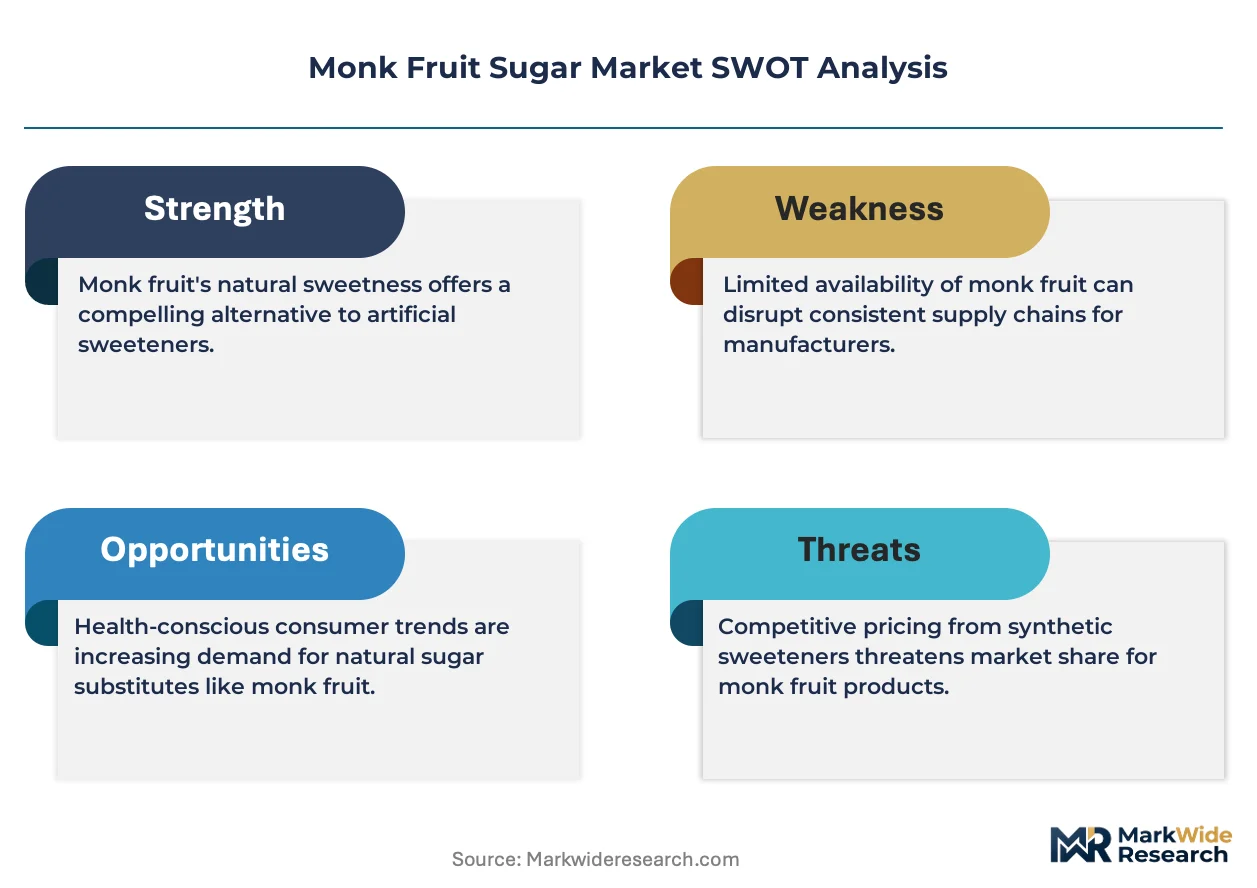
Single-source dependency on Guilin prefecture cultivation zones determines both premium-mid-economy pricing differentiation and supply chain resilience for extract processors serving FDA-regulated markets. Mogroside V potency variability across harvest batches compresses margins at standard-grade tiers while reinforcing premium capture for ISO 17025-certified suppliers with chromatography standardization capabilities.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade extracts from beverage-grade concentrates, with pricing stratifying across premium, standard, and economy tiers based on mogroside V purity certification and organic traceability documentation. Price differentiation hinges on backward integration depth and SAMR compliance verification, with cost compression in standard tiers intensifying due to stevia rebiana substitution pressure. Food manufacturers with multi-year offtake agreements exhibit lowest price sensitivity, while private-label retail channels face acute margin pressure from commodity sweetener alternatives.
Supply Chain Analysis
Upstream feedstock from Siraitia grosvenorii orchards centers on Guangxi Zhuang Autonomous Region cultivation clusters, with secondary sourcing from Hunan and Fujian provinces expanding to buffer climate volatility. Raw material flows draw from smallholder farming networks, ethanol-based extraction chemistry, and membrane filtration equipment imports. Single-source vulnerability concentrates in Guilin processing infrastructure, where MEE emissions compliance retrofits threaten capacity continuity. Distribution runs through Rotterdam and Long Beach liquid bulk terminals for European and North American beverage co-manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monk fruit extract incumbents face substitution defense imperatives against stevia supply chain maturation and synthetic sweetener cost advantages in commodity tenders.
For Market Incumbents: Pre-empt margin erosion by deepening captive cultivation acreage in Guangxi and securing NMPA health food registrations before domestic functional food competition intensifies. Lock in multi-year liquid extract offtakes with North American beverage co-manufacturers piloting bulk tanker delivery systems. For New Entrants and Emerging Players: Build out encapsulation technology partnerships targeting bakery heat-stability gaps currently blocking mogroside thermal degradation solutions. White-space concentration exists in EU novel food authorization preparation services and direct-to-manufacturer liquid extract channels bypassing traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated processors with SAMR-certified laboratory infrastructure over trading-house-dependent intermediaries. Acquisition screening should prioritize Guilin-based extractors with captive farming operations and ISO 17025 partnerships. Watch EFSA novel food authorization timelines as inflection signal for European market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | GLG Life Tech and Guilin Layn secure mogroside V consistency through captive Guangxi farming zones. |
| Membrane Filtration Technology Adoption | Aqueous extraction systems reduce ethanol dependence and compress MEE permitting timelines for regional processors. |
| Long-term Offtake Agreement Structuring | CPG procurement teams bypass trading houses to secure multi-year volume commitments with vertically structured suppliers. |
| Encapsulation R&D Partnership | Industrial ingredient houses pilot thermal protection systems to unlock high-temperature bakery applications. |
| NMPA Health Food Registration Pathway | Domestic functional food expansion targets aging-population diabetes management segments in China. |
Research Approach
Cross-validation between executive interviews at Guangxi-based extract processors and FDA GRAS notification databases anchors the qualitative findings. Primary fieldwork engaged natural products chemists, CPG procurement directors, beverage co-manufacturer formulation leads, and SAMR regulatory consultants. Secondary triangulation drew from NMPA novel food ingredient filings, EFSA novel food application registers, customs trade data for monk fruit extract HS codes, and SEC 10-K disclosures from listed ingredient houses. Bottom-up volume modeling and top-down value reconciliation tested segment-level assumptions.
Calibration against historical adoption curves for stevia and erythritol informs projection elasticity across the analysis window. Segmentation modeling incorporated product form, application vertical, end-user concentration, and packaging format dimensions with regional regulatory cluster overlays. CAGR derivation weighted capacity expansion announcements, cultivation acreage satellite verification, and front-of-pack warning system implementation schedules. Forecast inputs included NMPA approval velocity, EFSA assessment queue depth, and beverage manufacturer reformulation commitment disclosure patterns.
Stress conditions across EFSA authorization delays, Guilin climate volatility, and stevia price competition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory pathway timelines and cultivation yield stability. Cross-checking against customs export volume data from Guangxi Zhuang Autonomous Region is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Floral Nectar Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Global Brown Sugar Market
Sweeteners
India Food Sweetener Market
Sweeteners
Smoked Sugar Market
Sweeteners
Sugar Syrups Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Natural Sweetener Blends Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Sodium Saccharin Market