
 Floral Nectar Market | 2026-2036
Floral Nectar Market Size, Share, and Industry Trends Forecast 2026-2036
Floral Nectar Market Foresight
France is narrowing its position as the primary European hub for floral nectar distillation and formulation. Monin leverages decades of botanical extraction expertise to supply premium beverage channels across Western Europe. Croda International anchors its cosmetics-grade nectar portfolio through controlled supply partnerships with Provence-based lavender growers. SILAB competes in the high-purity segment through proprietary cold-processing protocols that preserve volatile aromatic compounds.
Floral nectar comprises the concentrated liquid extracted from flower blossoms, typically containing fructose, glucose, sucrose, and trace phenolic compounds at concentrations ranging from 60 to 80 percent dissolved solids depending on source species and processing method. Manufacturers deploy it as a natural sweetener, flavor carrier, and functional ingredient across food, cosmetic, and pharmaceutical applications. The food and beverage segment dominates volume consumption, particularly in premium mixology and functional beverage formulations where wildflower and acacia varieties command price premiums. The cosmetics and personal care segment represents the fastest-growing application area, as heather and eucalyptus nectar variants gain traction in microbiome-friendly skincare formulations where gentle preservation properties replace synthetic alternatives.
EU REACH and EFSA novel food frameworks govern ingredient safety assessments and labeling requirements for floral nectar entering European food and cosmetic supply chains. The FDA GRAS self-affirmation pathway and USDA organic certification shape market access dynamics for suppliers targeting United States buyers, with additional state-level raw honey and nectar regulations in California and Florida creating compliance complexity. Stakeholders must monitor evolving pollinator health policies and pesticide residue thresholds, as these environmental regulations directly constrain raw material availability and extraction site licensing across major producing regions.
Market Dynamics
Clean-label disclosure mandates across multiple jurisdictions are compressing formulation timelines for floral nectar suppliers, forcing simultaneous compliance with EU REACH substance restrictions and USDA organic certification standards while maintaining aromatic compound stability.
Growth Catalysts
- EU REACH substance restrictions:Tightening disclosure requirements for phenolic compounds are accelerating investment in traceable Provence lavender supply chains by cosmetics formulators seeking preservative alternatives.
- Craft cocktail channel expansion:Premium beverage programs in Western Europe are standardizing wildflower and acacia nectar as base sweeteners, creating dedicated procurement contracts with extraction specialists.
- Microbiome-friendly skincare:Heather and eucalyptus nectar variants are replacing synthetic preservatives in gentle preservation systems, with France-based cosmetics houses leading formulation adoption.
Market Restraints
- Pollinator health policies:Pesticide residue thresholds in France and California are constraining raw material availability and extraction site licensing across major producing regions.
- Input cost volatility:Weather-dependent lavender blossom yields create concentrated supply risk in Provence production clusters, compressing margin stability for distillation specialists.
- Substitution threat from agave and maple:Established alternative natural sweeteners with longer shelf stability and lower price volatility compete for beverage formulation slots.
Strategic Opportunities
- Pharmaceutical-grade extraction:Cold-processing protocols preserving volatile aromatic compounds open high-purity segments for therapeutic applications beyond current cosmetic and food uses.
- USDA organic certification tailwind:United States state-level raw honey and nectar regulations in California and Florida create compliance complexity that rewards pre-certified suppliers with preferred supplier status.
- Direct-to-brand distribution:Bypassing traditional ingredient distributors through controlled supply partnerships allows extraction specialists to capture margin and secure volume commitments.
Industry Challenges
- Dual certification timelines:Simultaneous EU EFSA novel food assessments and FDA GRAS self-affirmation pathways extend market entry timelines by 18-24 months for new nectar variants.
- Cold-chain integrity requirements:Preservation of volatile aromatic compounds demands specialized temperature-controlled logistics, raising working capital intensity for inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floral Nectar Market |
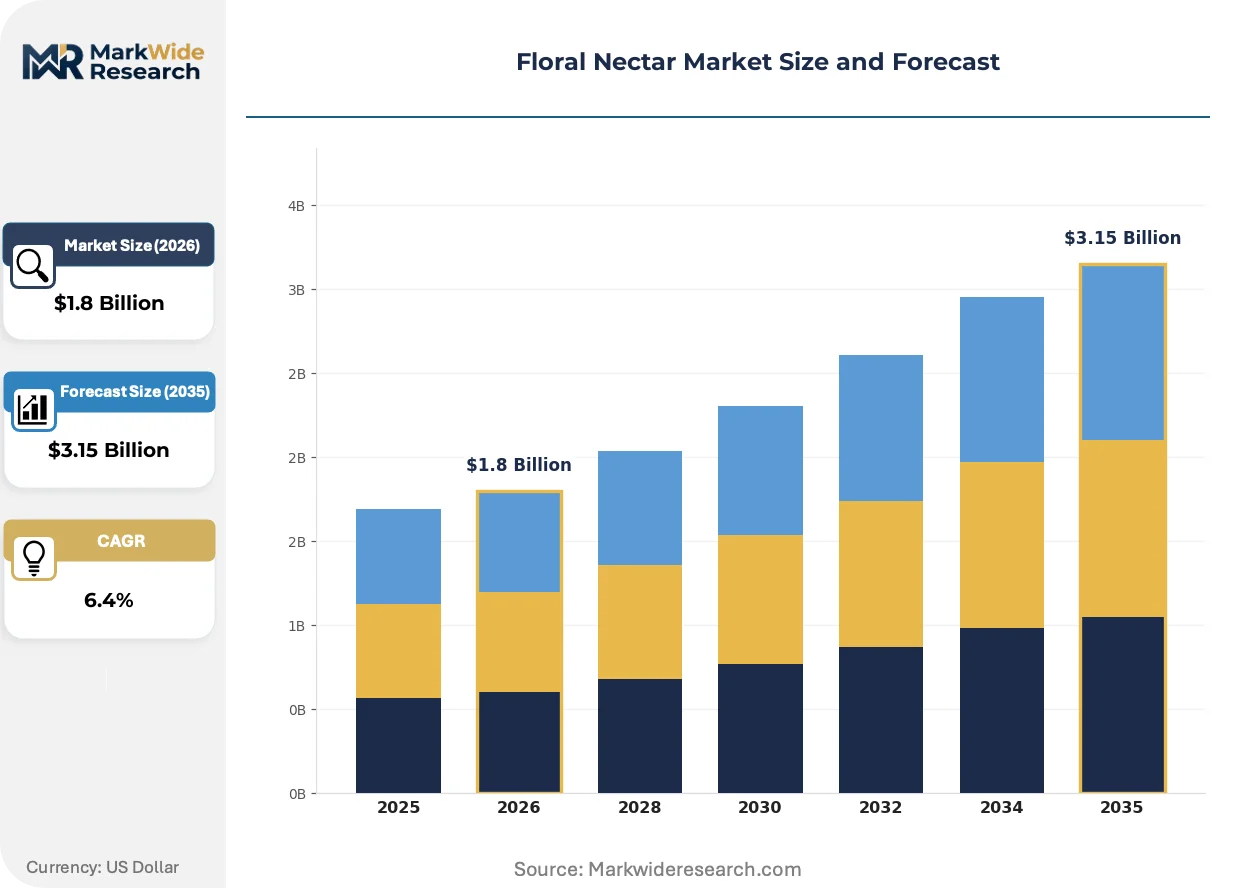
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Flower Type: Wildflower, Clover, Heather, Eucalyptus, Acacia Extraction Method: Cold Pressing, Centrifugation, Solvent Extraction, Supercritical CO2, Ultrasonic Extraction End Use Industry: Food & Beverage, Cosmetics & Personal Care, Pharmaceuticals, Fragrance Manufacturing, Nutraceuticals Packaging Type: Glass Bottles, Plastic Jars, Sachets, Bulk Containers, Tins |
| Companies Covered | Wild Hibiscus Flower Co., Croda International, Monin, Uncle Harry's Natural Products, SILAB, Archer Daniels Midland Company, Beenature, Decleor, TERRA NOVA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floral Nectar Market Shifts & Advancements
Extraction technology evolution and regulatory harmonization pressures are compressing traditional processing timelines while opening premium positioning opportunities for suppliers with verified supply chain control.
Enzymatic cold-extraction protocols are collapsing the traditional heat-degradation tradeoff between yield and aromatic preservation. Premium cosmetics formulators in France are adopting these systems at accelerated pace, enabling high-purity heather nectar production that previously required prohibitively expensive small-batch distillation.
EFSA novel food framework updates are forcing pre-market safety dossiers for traditional floral nectar varieties previously grandfathered under general food law. This regulatory friction most affects acacia and wildflower suppliers targeting cross-border European distribution, with French extraction houses responding by consolidating controlled supply partnerships under single regulatory submissions.
Ingredient buyers are consolidating supplier relationships around vertically integrated extraction specialists with captive Provence lavender cultivation. This procurement concentration displaces spot-market purchasing in premium beverage channels, with craft cocktail programs in France and adjacent markets now requiring batch-level traceability documentation as a standard qualification threshold.
Floral Nectar Market Segmentation
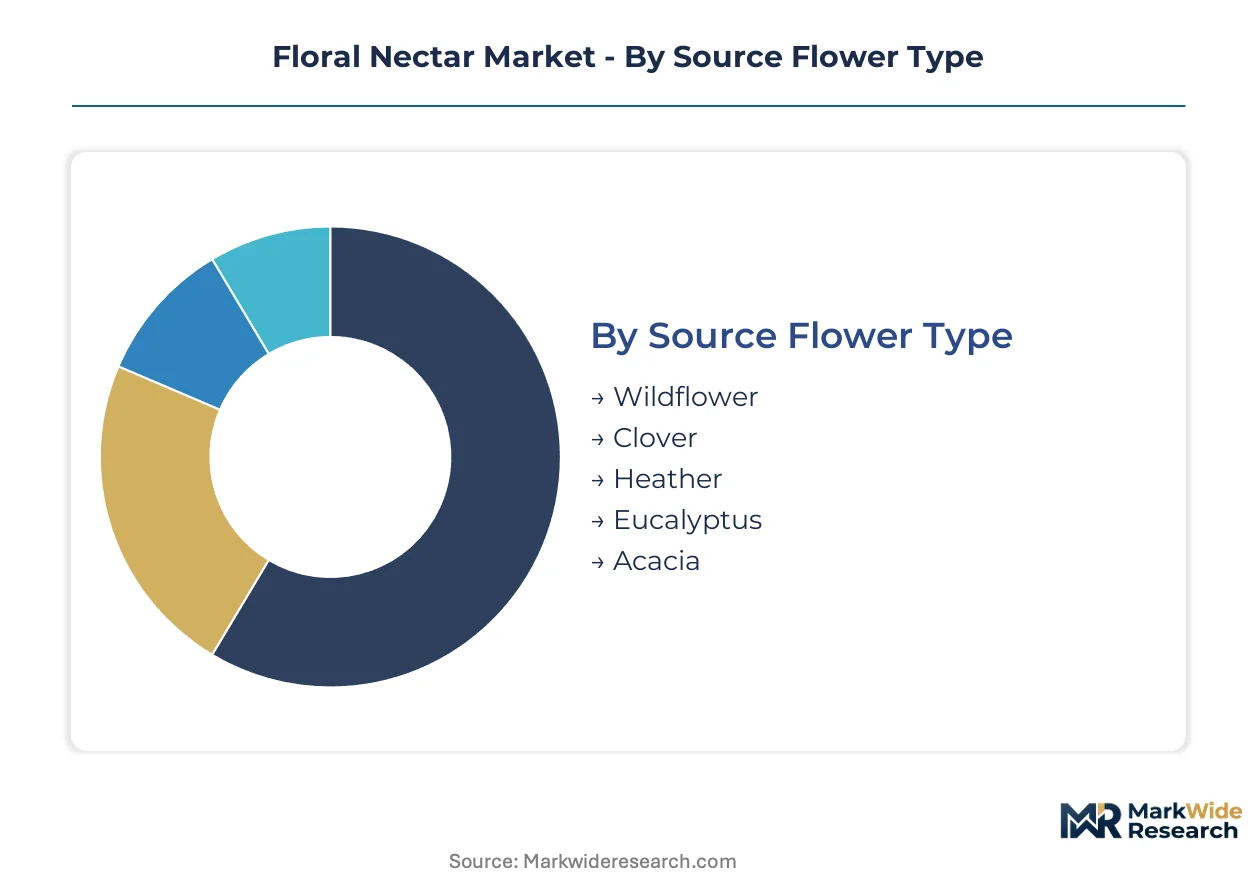
Floral nectar procurement patterns diverge sharply across source species, extraction protocols, and end-use specifications. Understanding these segment boundaries clarifies where margin pools concentrate and which technical requirements lock in supplier relationships.
Source Flower Type:
Inventory velocity varies dramatically by blossom seasonality, with Mediterranean lavender and heather turning over fastest during concentrated harvest windows while acacia and eucalyptus sustain longer procurement cycles.
- Wildflower:Blended nectar draws from multiple blossom species, delivering complex aromatic profiles prized by craft cocktail formulators seeking differentiation. Demand clusters in French beverage channels where batch-level traceability documentation has become a standard procurement threshold.
- Acacia:High fructose concentration produces exceptionally stable nectar with low crystallization tendency, making it preferred for extended-shelf-life applications. Cosmetics houses in Provence specify acacia for microbiome-friendly preservation systems where gentle activity replaces synthetic alternatives.
- Clover:Mild flavor profile suits mass-market food applications with price-sensitive formulation targets.
- Heather:Distinctive phenolic signature commands premium positioning in therapeutic-grade extracts.
- Eucalyptus:Antimicrobial properties drive pharmaceutical and respiratory wellness applications.
Acacia dominates installed base through volume scalability. Wildflower is where expansion concentrates as traceability premiums reshape beverage procurement.
Extraction Method:
Capital intensity and yield preservation tradeoffs separate these approaches, with cold-based methods commanding equipment premiums that solvent systems offset through throughput advantages.
- Cold Pressing:Mechanical pressure at ambient temperatures preserves volatile aromatic compounds without thermal degradation. French extraction specialists deploy this for heather nectar destined for high-purity cosmetic formulations where phenolic integrity determines preservation efficacy.
- Supercritical CO2:Carbon dioxide in supercritical state selectively extracts target compounds while leaving polar contaminants behind. European nutraceutical buyers specify this method for pharmaceutical-grade acacia extracts requiring residue-free certification under EFSA novel food frameworks.
- Centrifugation:High-speed separation suits high-volume clover and wildflower processing with moderate purity requirements.
- Solvent Extraction:Ethanol-based systems maximize yield for fragrance manufacturing with less stringent food-grade constraints.
- Ultrasonic Extraction:Cavitation-assisted protocols reduce processing time for small-batch artisanal production.
Solvent extraction still handles the largest throughput volumes. Supercritical CO2 is climbing the fastest as residue-free certification becomes a non-negotiable threshold.
End Use Industry:
Specification stringency and certification burden vary enormously, with pharmaceutical and nutraceutical channels imposing documentation requirements that food and fragrance buyers rarely match.
- Cosmetics & Personal Care:Microbiome-friendly formulations drive heather and eucalyptus nectar adoption as gentle preservation agents. French cosmetics houses lead this transition, consolidating supplier relationships around vertically integrated Provence lavender specialists with captive cultivation and cold-processing capabilities.
- Food & Beverage:Premium mixology and functional drink segments standardize wildflower and acacia nectar as base sweeteners. Western European craft cocktail programs now require batch-level traceability documentation, displacing spot-market purchasing with dedicated procurement contracts.
- Pharmaceuticals:Therapeutic-grade specifications demand pharmaceutical-grade extraction protocols with full analytical dossiers.
- Fragrance Manufacturing:Aromatic compound concentration takes priority over food safety certification, opening solvent-extracted supply sources.
- Nutraceuticals:Functional health positioning requires novel food safety assessments under EFSA frameworks for cross-border European distribution.
Food and beverage commands the largest volume position. Cosmetics and personal care represents the steepest expansion trajectory as clean-label preservation systems displace synthetic alternatives.
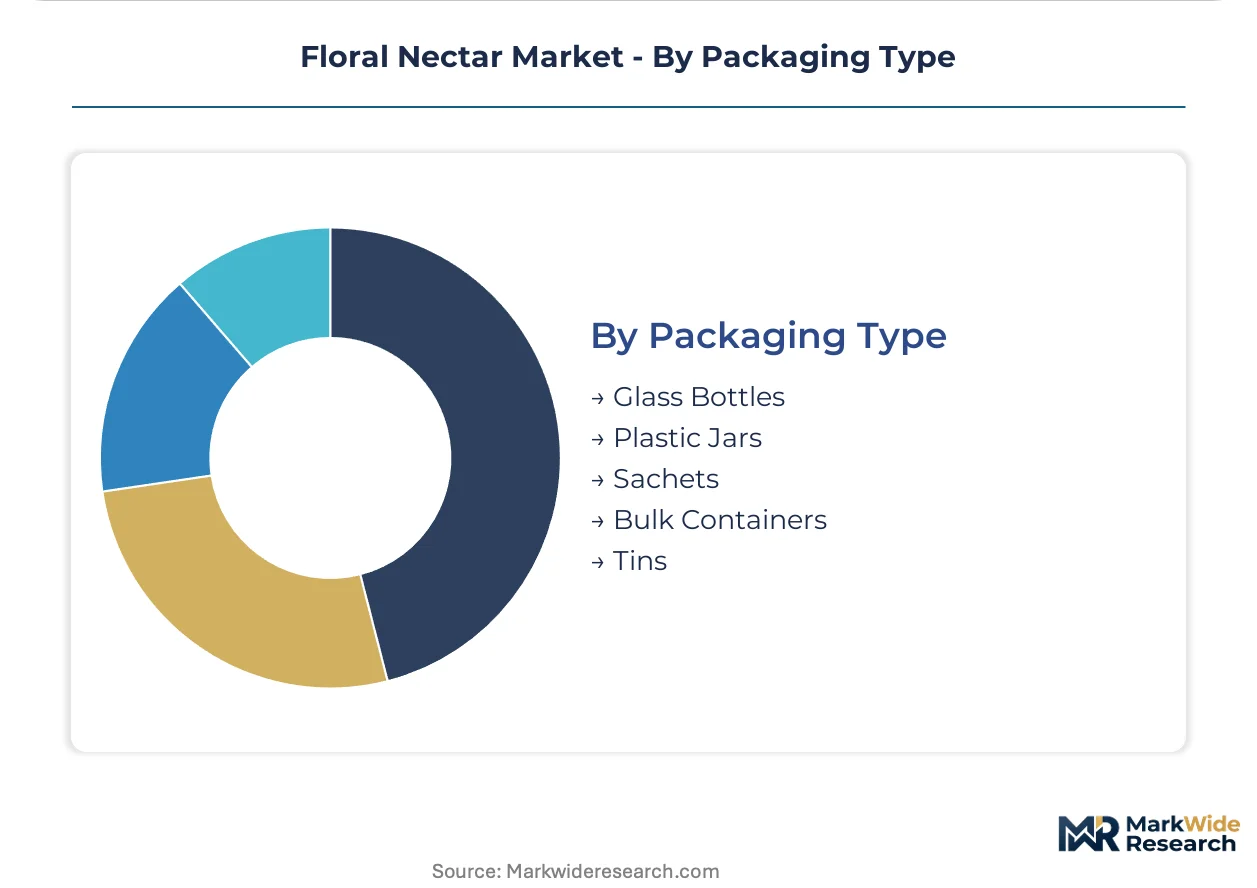
Packaging Type:
Unit economics and channel access separate these formats, with bulk containers serving industrial processors while premium retail positioning demands individual-unit presentation.
- Glass Bottles:Inert material properties and premium aesthetic support direct-to-consumer positioning in specialty food and cosmetic channels. French extraction houses favor amber glass for light-sensitive heather nectar retail distribution.
- Bulk Containers:Stainless steel totes and drums minimize per-unit packaging cost for industrial food and cosmetic manufacturers with captive formulation facilities. This format dominates procurement volumes for acacia nectar destined for beverage production at scale.
- Plastic Jars:Lightweight shatter resistance suits mass-market food retail with cost-driven positioning.
- Sachets:Single-serve convenience formats target hospitality and travel retail channels.
- Tins:Heritage aesthetic supports gift-market positioning for premium wildflower varieties.
Bulk containers dominate industrial procurement scale. Glass bottles is where premium positioning investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments and REACH substance restrictions in France anchor European regulatory gravity for floral nectar supply chains. Procurement concentration in Provence lavender clusters and expanding craft cocktail channels in Western Europe define current demand geography.
France
Provence-based lavender and acacia nectar production clusters serve domestic cosmetics houses and export-oriented food processors. ANSM and EFSA frameworks govern cosmetic-grade and novel food safety dossiers respectively. Grasse and surrounding Alpes-Maritimes facilities concentrate cold-processing extraction capacity for high-purity heather nectar.
United States
USDA organic certification tailwinds and state-level raw honey regulations in California and Florida shape procurement complexity for premium beverage brands. FDA GRAS self-affirmation pathways extend market entry timelines for new nectar variants. Pacific Northwest wildflower extraction specialists supply craft cocktail programs with batch-level traceability documentation.
Germany
EFSA novel food framework compliance and REACH substance restrictions drive importer consolidation around pre-certified French suppliers. Baden-Württemberg cosmetics formulators specify residue-free acacia extracts for microbiome-friendly skincare lines. Bavarian beverage distributors standardize wildflower nectar procurement for premium mixology channels.
Italy
Lombardy and Piedmont cosmetics manufacturers adopt heather nectar variants for gentle preservation systems replacing synthetic alternatives. EFSA regulatory submissions for traditional varieties previously grandfathered under general food law create compliance friction. Tuscan wildflower extraction specialists serve domestic craft cocktail expansion.
United Kingdom
London-based premium beverage programs and Southeast England cosmetics formulators drive import demand for traceable Provence supply. Post-Brexit UK REACH divergence from EU frameworks creates dual certification burdens for cross-channel suppliers. British organic certification bodies tighten disclosure requirements for phenolic compound content.
Floral Nectar Market Competitive Landscape
Capability concentration sits with vertically integrated extraction specialists; scale advantage sits with diversified ingredient conglomerates. The market structures around three tiers: captive cultivation operators with Provence lavender holdings, cold-processing technology specialists, and broad-line natural ingredient distributors. Strategic moves center on controlled supply partnerships securing batch-level traceability and enzymatic cold-extraction capacity expansion preserving volatile aromatic compounds.
Within the premium extraction tier, SILAB and Croda International exemplify capability-focused positioning through proprietary processing protocols and controlled supply partnerships with regional growers. Monin occupies a distinct position bridging beverage formulation expertise with botanical extraction heritage. Wild Hibiscus Flower Co. and Beenature represent specialized originators focused on single-source floral varieties. Archer Daniels Midland Company anchors the scale-driven segment with diversified natural sweetener portfolios spanning multiple geographies.
| Leading Market Players |
|---|
| Wild Hibiscus Flower Co. |
| Croda International |
| Monin |
| Uncle Harry's Natural Products |
| SILAB |
| Archer Daniels Midland Company |
| Beenature |
| Decleor |
| TERRA NOVA |
| Others |
Supply & Pricing Matrix
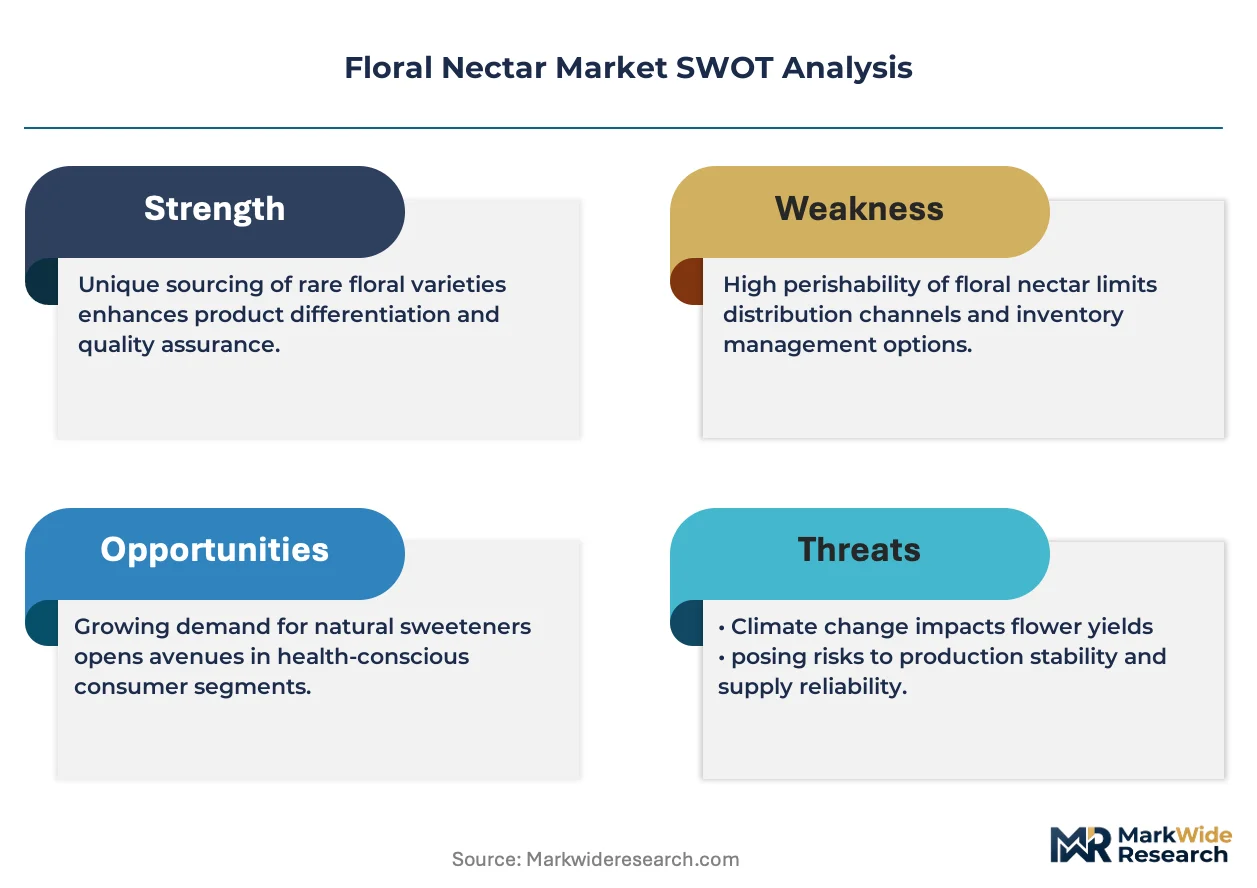
Pollinator health policy volatility in France and California simultaneously compresses raw material availability and widens price spreads between certified and uncertified nectar tiers, forcing buyers to absorb premium sourcing costs or accept degraded aromatic compound profiles. This regulatory chokepoint locks in a three-tier pricing structure across premium, standard, and economy levels while concentrating extraction capacity around vertically integrated Provence operators with captive lavender cultivation.
Pricing Analysis
Provence-sourced heather nectar commands substantial premiums over Bulgarian or Spanish alternatives due to ANSM cosmetic-grade certification and batch-level traceability documentation. Price differentiation rests on cold-processing certification and organic tier status, with EFSA novel food dossier completion adding further cost layers. Pricing pressure stems from substitution threat as agave and maple sweeteners capture beverage formulation slots. Mass-market food processors exhibit highest price sensitivity; premium cosmetics houses demonstrate lowest.
Supply Chain Analysis
Extended payment terms from French cosmetics houses now stretch sixty to ninety days, forcing extraction specialists to secure supply-chain finance facilities against receivables. Raw material sourcing concentrates in France, Bulgaria, and Spain for lavender and heather; acacia supply draws from Hungary and Romania. Single-source vulnerability runs through Provence harvest windows vulnerable to weather shock. Distribution runs through controlled supply partnerships with batch-level documentation rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic cold-extraction breakthroughs are collapsing yield-aroma tradeoffs and opening therapeutic-grade segments previously inaccessible to mid-scale operators, creating a high-growth disruption window. EFSA novel food framework expansion accelerates this inflection by grandfathering traditional varieties into pre-market safety dossier requirements.
For Market Incumbents: Build regulatory dossier moats by consolidating controlled supply partnerships under single EFSA submissions for acacia and wildflower variants. Expand captive Provence lavender cultivation to offset weather-dependent yield volatility. Cold-processing capacity additions in Grasse extraction clusters defend margin position against emerging ultrasonic extraction specialists. For New Entrants and Emerging Players: Pursue pharmaceutical-grade extraction white-space by deploying supercritical CO2 protocols for residue-free acacia certification. Target Pacific Northwest wildflower supply to serve USDA organic-certified craft cocktail programs in California and Florida. Direct-to-brand distribution bypasses entrenched ingredient distributors and captures margin. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated extraction specialists with captive cultivation and cold-processing capabilities. Five-to-ten year viability hinges on regulatory dossier completion rates and pollinator health policy stability. Watch EFSA novel food assessment timelines as the inflection signal indicating which suppliers secure cross-border European distribution lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Cold-Extraction Scale-Up | Preservation of volatile aromatic compounds opens therapeutic-grade segments beyond cosmetic and food uses. |
| EFSA Novel Food Dossier Consolidation | Single regulatory submissions for controlled supply partnerships accelerate cross-border European market access. |
| Captive Provence Cultivation Expansion | In-house lavender production mitigates weather-dependent yield volatility and secures batch-level traceability. |
| Direct-to-Brand Distribution Bypass | Elimination of traditional ingredient distributors captures margin and secures volume commitments from premium beverage brands. |
| USDA Organic Pre-Certification Investment | Preferred supplier status rewards compliance complexity in California and Florida state-level nectar regulations. |
Research Methodology
Initial hypotheses were tested against primary input from extraction specialists, cosmetics formulators, beverage procurement managers, and regulatory affairs leads and refined through secondary validation. Primary fieldwork encompassed structured interviews with Provence-based lavender growers, cold-processing equipment operators, and EFSA submission consultants. Secondary sources included EFSA novel food register entries, ANSM cosmetic ingredient filings, USDA organic certification databases, and French customs trade records. Bottom-up volume modeling triangulated against top-down market sizing across source flower type and extraction method dimensions.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling spanning source flower species, extraction protocol, end-use industry, and geographic certification cluster. CAGRs derived from weighted average growth trajectories across these segments. Forecast inputs incorporated pollinator health policy evolution, enzymatic extraction technology diffusion rates, and craft cocktail channel expansion velocity in Western European metropolitan markets.
Macroeconomic conditions sit as an overlay; deviation in EU agricultural subsidy levels, organic certification fee structures, or freight cost volatility would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA assessment timeline stability and lavender blossom yield patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Organic Palm Sugar Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Glucose Syrup Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Africa Stevia Market
Sweeteners
Mannitol Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Sucrose Acetate Isobutyrate Market