
 Smoked Sugar Market | 2026-2036
Smoked Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Sugar Market Analytics
Artisanal smokehouse labor pools across Central Europe is collapsing, constraining batch consistency for traditional cold-smoked sugar producers and forcing equipment upgrades. Kerry Group plc leverages proprietary pyrolysis reactor technology to sustain premium positioning in North American food service channels. Besmoke Ltd. anchors British supply through direct relationships with heritage malt houses, while ProFagus GmbH dominates continental European industrial volumes via backward integration into beechwood sourcing.
Smoked sugar denotes crystalline sucrose or alternative sweeteners exposed to controlled wood smoke pyrolysis, typically achieving phenolic compound concentrations between 200 and 800 ppm depending on duration and wood species. The ingredient imparts umami depth and color fixation in commercial food manufacturing where open-flame smoking proves impractical. Dark Smoked Sugar leads product type revenue through concentrated penetration of barbecue sauce and dry rub formulations, while Bourbon Smoked Sugar registers the fastest trajectory as American craft distilling co-marketing expands. Grade stratification shows Specialty grade commanding margin premiums in direct-to-consumer channels, whereas Industrial grade occupies high-throughput bakery and beverage applications where cost efficiency governs procurement.
EFSA maintains stringent evaluation protocols for smoke flavoring primary products under Regulation (EC) No 2065/2003, directly conditioning market access for European producers. FDA GRAS self-determination pathways govern United States commercialization, though FSMA preventive controls impose documented hazard analysis for pyrolysis-derived ingredients. USDA organic certification requirements for smoke-derived substances further segment grade-based pricing structures. Stakeholders must monitor evolving maximum residue levels for polycyclic aromatic hydrocarbons as both jurisdictions advance analytical detection capabilities.
Market Dynamics
Artisanal smokehouse labor pools across Central Europe are collapsing, constraining batch consistency for traditional cold-smoked sugar producers and forcing capital-intensive equipment upgrades toward automated pyrolysis systems.
Growth Catalysts
- EFSA Flavoring Protocols:Tightening purity benchmarks for pyrolysis-derived food ingredients are accelerating R&D investment in contaminant filtration technologies across European specialty food manufacturing.
- Barbecue Sauce Formulations:Artisanal barbecue sauce producers in the United States represent a rapidly expanding end-use segment demanding consistent smoke phenolic profiles at industrial scale.
- Bourbon Distilling Co-Marketing:American craft distilling partnerships are creating premium positioning for barrel-aged smoke variants in direct-to-consumer channels.
Market Restraints
- Beechwood Supply Concentration:Backward integration into beechwood sourcing dominates continental European industrial volumes, creating captive supply bottlenecks for independent processors.
- PAH Detection Thresholds:Advancing analytical capabilities for polycyclic aromatic hydrocarbons are compressing acceptable residue windows and raising compliance costs.
- Liquid Smoke Substitution:Spray-dried smoke condensates offer lower per-unit phenolic dosing costs in high-throughput bakery applications.
Strategic Opportunities
- USDA Organic Certification:Smoke-derived substance requirements for organic labeling create margin premiums in direct-to-consumer channels for compliant producers.
- Germany's Specialty Corridor:Hamburg and Lower Saxony manufacturing clusters present concentrated demand aggregation points for regional supply contracts.
- FSMA Preventive Controls:Documented hazard analysis requirements for pyrolysis-derived ingredients favor suppliers with established food safety management systems.
Industry Challenges
- Pyrolysis Reactor Calibration:Maintaining phenolic compound concentrations between 200 and 800 ppm requires skilled technicians scarce in contracting regional labor markets.
- Grade Stratification Complexity:Specialty grade margin premiums in direct-to-consumer channels demand separate production runs incompatible with industrial-grade throughput economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Sugar Market |
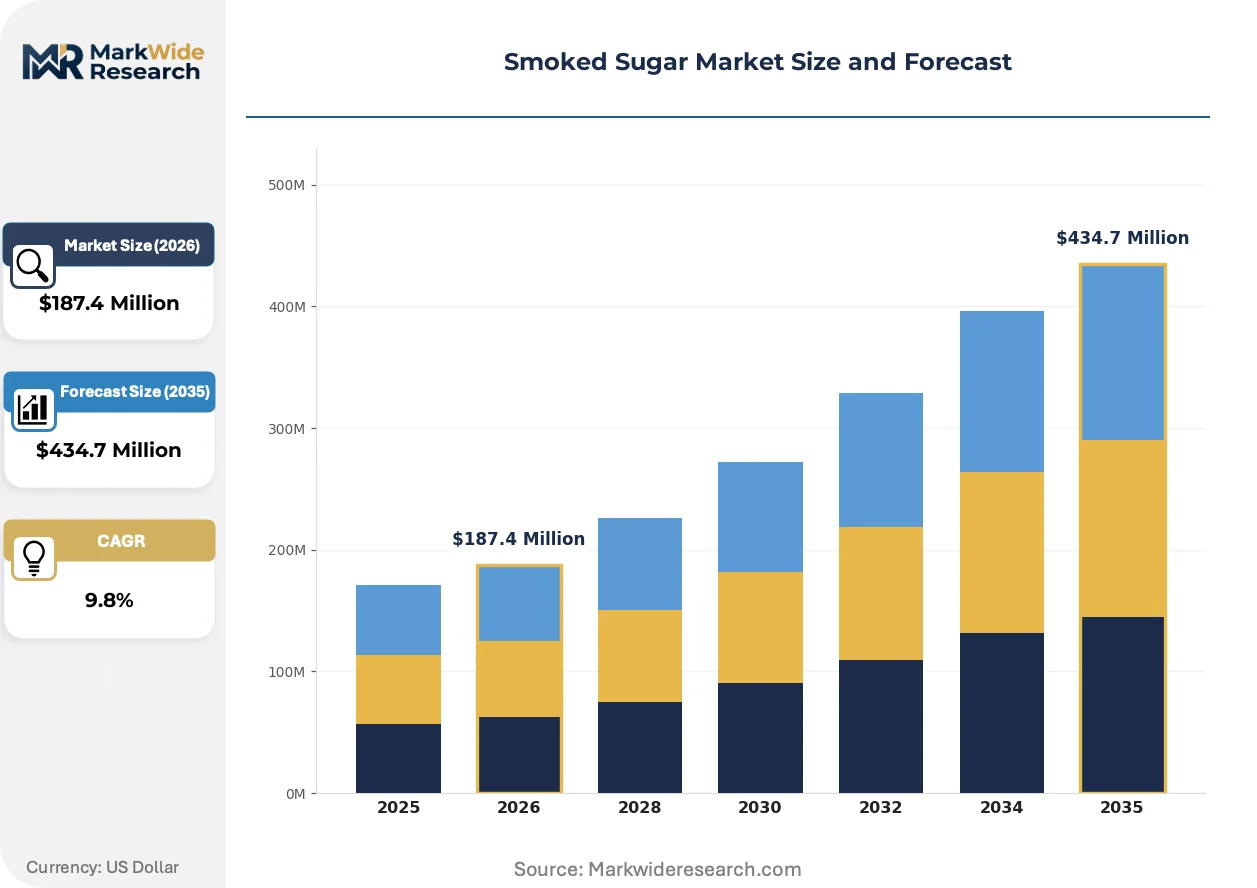
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Smoked Sugar, Dark Smoked Sugar, Maple Smoked Sugar, Bourbon Smoked Sugar Application: Food Seasoning, Baking, Beverage Flavoring, Sauces Grade: Organic, Non-Organic, Specialty, Industrial Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Kerry Group plc, Red Arrow International LLC, Besmoke Ltd., ProFagus GmbH, B&G Foods, Inc., Henning Gesellschaft für Nahrungsmitteltechnik mbH, Cargill Incorporated, The Archer Daniels Midland Company, The Sausage Maker, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Sugar Market Evolving Landscape
Smoke generation technology is bifurcating between heritage cold-smoking methods and controlled pyrolysis reactors, reshaping capital deployment patterns and competitive positioning across ingredient supply tiers.
Continuous pyrolysis reactor systems are replacing batch smokehouse operations in North American food service channels. Large-scale sauce manufacturers are adopting these systems to achieve phenolic consistency previously unattainable with traditional methods. The technology is bifurcating the market into premium heritage-positioned suppliers and efficiency-optimized industrial processors.
EFSA maintains stringent evaluation protocols for smoke flavoring primary products under Regulation (EC) No 2065/2003. These protocols directly condition market access for European producers by mandating toxicological data packages for each wood species and pyrolysis condition. German and Dutch specialty food manufacturers are responding by consolidating supplier qualification programs around pre-approved primary product categories.
Direct-to-consumer channels are displacing traditional food service distribution for premium smoked sugar variants. Specialty grade producers are building subscription and e-commerce infrastructure to capture margin premiums previously allocated to distributors. This channel rotation is most visible in United States craft food retail and United Kingdom heritage ingredient marketplaces.
Smoked Sugar Market Segmentation
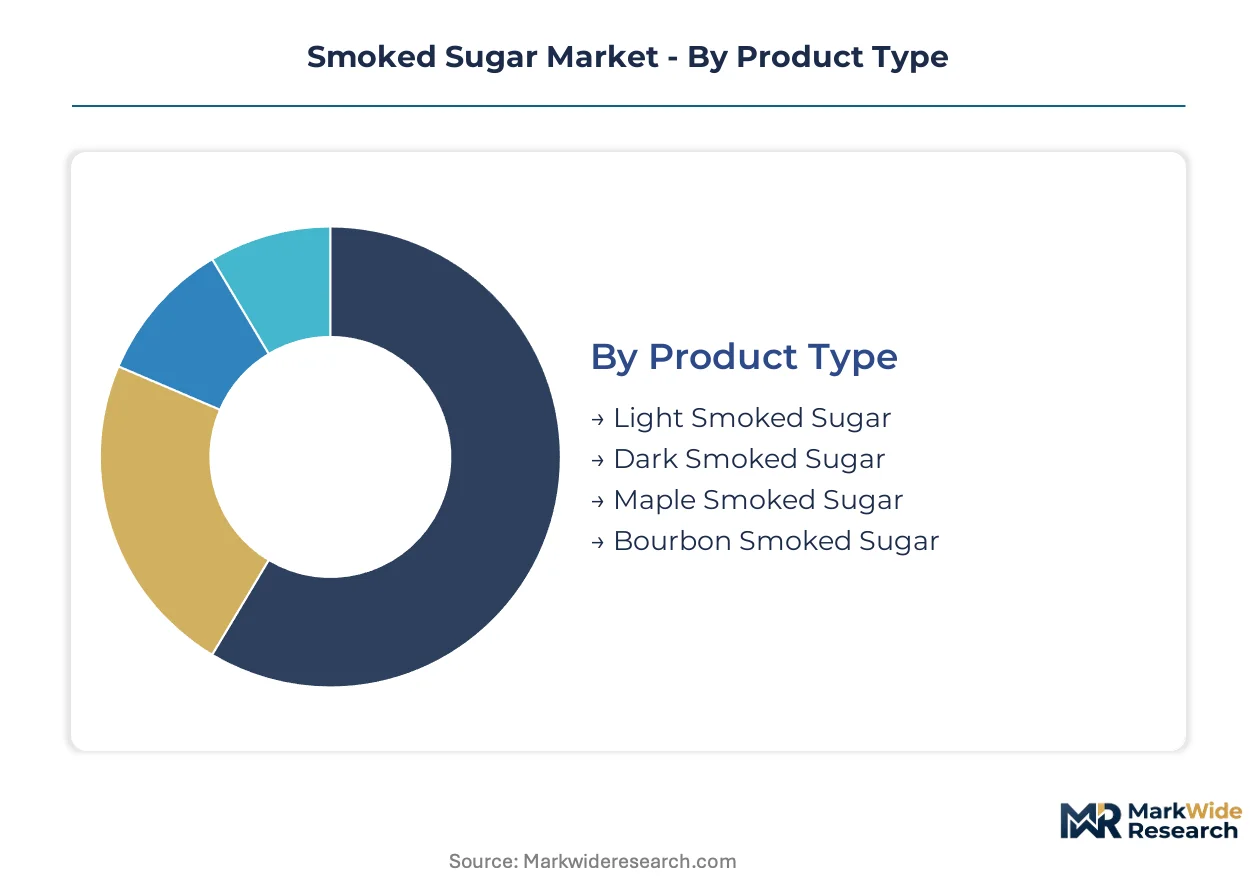
Grade stratification in smoked sugar reflects divergent regulatory pathways and procurement economics. Product type differentiation tracks wood species sourcing and phenolic concentration targets. Application segmentation reveals channel-specific formulation requirements that reshape supplier qualification criteria.
Grade:
EFSA smoke flavoring protocols under Regulation (EC) No 2065/2003 and USDA organic certification requirements create divergent compliance burdens that segment pricing tiers and customer access.
- Specialty:Achieves phenolic concentrations between 200 and 800 ppm through controlled pyrolysis reactor calibration. Direct-to-consumer channels in Germany's Hamburg and Lower Saxony manufacturing corridor concentrate procurement for barbecue sauce and dry rub formulations requiring batch consistency documentation.
- Industrial:Optimized for high-throughput bakery and beverage applications where cost efficiency governs procurement. Food service channels in the United States absorb volumes through Kerry Group plc's proprietary pyrolysis reactor distribution networks.
- Organic:USDA certification requirements for smoke-derived substances impose documented hazard analysis under FSMA preventive controls. Premium positioning in American craft distilling co-marketing partnerships commands margin separation from conventional grades.
- Non-Organic:Standard pyrolysis sourcing without certification documentation serves mass-market sauce manufacturers and commercial bakeries prioritizing per-unit phenolic dosing costs over provenance claims.
Established volume favors Industrial; emerging adoption favors Specialty.
Product Type:
Wood species selection and smoke duration parameters create distinct phenolic profiles that align with regional cuisine preferences and co-branding opportunities.
- Dark Smoked Sugar:Concentrated penetration of barbecue sauce and dry rub formulations generates revenue concentration through extended pyrolysis exposure. United States artisanal barbecue sauce producers represent the dominant demand aggregation point for this variant's umami depth and color fixation properties.
- Bourbon Smoked Sugar:American craft distilling partnerships create premium positioning for barrel-aged smoke variants. The segment gains share fastest through direct-to-consumer subscription infrastructure displacing traditional food service distribution.
- Light Smoked Sugar:Subtle phenolic presence suits beverage flavoring applications where smoke intensity must complement rather than dominate base ingredients.
- Maple Smoked Sugar:Heritage malt house relationships in the United Kingdom anchor supply for premium baking applications requiring regional provenance signaling.
Dark Smoked Sugar commands current volume concentration; Bourbon Smoked Sugar exhibits the steepest expansion trajectory.
Application:
End-use formulation requirements determine phenolic dosing precision and supplier technical support intensity.
- Sauces:Barbecue sauce manufacturers demand consistent smoke phenolic profiles at industrial scale, driving adoption of continuous pyrolysis reactor systems over batch smokehouse operations.
- Food Seasoning:Dry rub formulations require precise particle size distribution and moisture content control for uniform coating adhesion.
- Baking:High-throughput applications face substitution pressure from spray-dried smoke condensates offering lower per-unit phenolic dosing costs.
- Beverage Flavoring:Distilling partnerships and craft cocktail ingredient markets concentrate demand for certified organic variants with documented contaminant filtration.
Sauces anchor industrial procurement scale; Beverage Flavoring concentrates premium grade adoption.
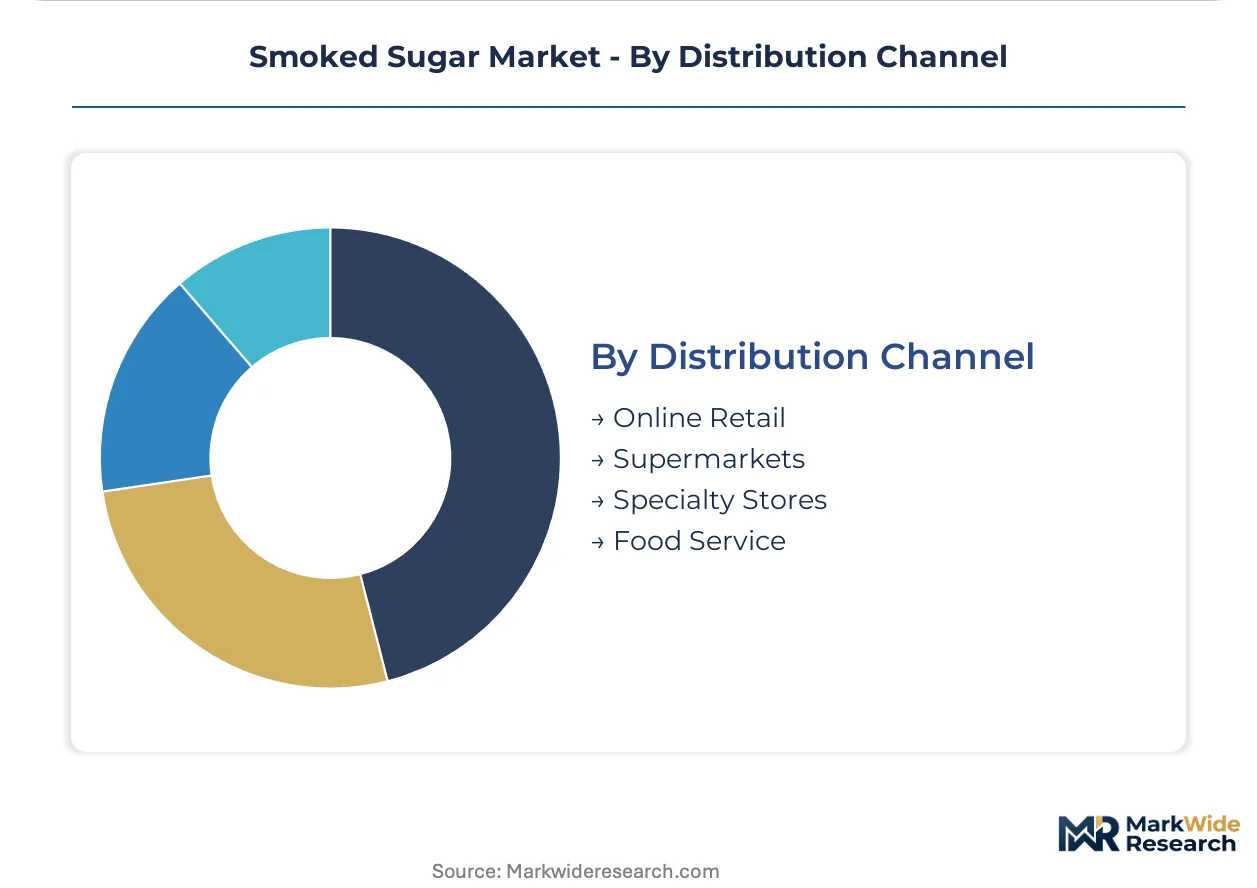
Distribution Channel:
Channel selection determines margin capture and customer relationship depth for grade-tiered product positioning.
- Food Service:Large-scale sauce manufacturers and commercial bakeries consolidate procurement through established supplier qualification programs, favoring Industrial grade throughput economics.
- Specialty Stores:Heritage ingredient marketplaces in the United Kingdom and United States craft food retail concentrate demand for Specialty grade provenance documentation.
- Online Retail:Subscription and e-commerce infrastructure enables margin capture previously allocated to distributors, most visible in premium variant direct-to-consumer growth.
- Supermarkets:Mass retail placement requires FSMA-compliant hazard analysis documentation and competitive per-unit pricing against liquid smoke substitutes.
Food Service dominates volume throughput; Online Retail concentrates emerging premium adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German specialty food manufacturing corridors while North American producers absorb higher compliance costs for FSMA documentation. This asymmetry reshapes capital allocation toward European efficiency investments.
United States
Artisanal barbecue sauce manufacturers in Kansas City and Austin drive demand for consistent phenolic profiles. FDA GRAS self-determination pathways govern commercialization, though FSMA preventive controls impose documented hazard analysis requirements. The Southeast manufacturing belt around North Carolina anchors industrial-scale adoption of continuous pyrolysis systems.
Germany
Hamburg and Lower Saxony specialty food corridors concentrate procurement for premium-grade variants. EFSA maintains stringent evaluation protocols for smoke flavoring primary products under Regulation (EC) No 2065/2003. Bavarian heritage smokehouses face labor pool collapse, forcing automated equipment upgrades.
United Kingdom
Heritage ingredient marketplaces in London and the Midlands sustain demand for provenance-documented variants. EFSA protocols condition market access for pyrolysis-derived food ingredients. Scottish and Welsh malt house relationships anchor supply chains for regional smoke variants.
France
Premium baking applications in Paris and Lyon concentrate procurement for subtle phenolic profiles. EFSA flavoring substance evaluation protocols tighten purity benchmarks annually. The Auvergne-Rhône-Alpes region hosts consolidating supplier qualification programs around pre-approved primary product categories.
Canada
Craft distilling partnerships in British Columbia and Ontario create co-marketing opportunities for barrel-aged variants. Health Canada and PMRA regulate smoke-derived food additives through food safety frameworks. Toronto's specialty food retail corridor drives direct-to-consumer channel expansion.
Smoked Sugar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Proprietary pyrolysis reactor specialists command premium positioning in food service channels, while backward-integrated beechwood processors dominate industrial volumes through captive supply economics. Three archetypes define the landscape: heritage smokehouse operators, automated reactor technology licensors, and diversified ingredient conglomerates. M&A activity targets regional flavor houses, while capacity expansion concentrates in German and North American manufacturing corridors.
Among Ireland-based diversified nutrition groups, Kerry Group plc represents the technology-licensing archetype with proprietary reactor positioning. Besmoke Ltd. and ProFagus GmbH exemplify geographic specialization patterns—British heritage malt house relationships versus German beechwood integration—each anchoring distinct supply tier economics. These three entities illustrate how regional sourcing advantages translate into segmented competitive positioning without overlapping customer targets.
| Leading Market Players |
|---|
| Kerry Group plc |
| Red Arrow International LLC |
| Besmoke Ltd. |
| ProFagus GmbH |
| B&G Foods, Inc. |
| Henning Gesellschaft für Nahrungsmitteltechnik mbH |
| Cargill Incorporated |
| The Archer Daniels Midland Company |
| The Sausage Maker, Inc. |
| Others |
Value Network & Pricing Analysis
Sixty-day beechwood curing cycles concentrate pricing power with German processors holding captive supply, while American distributors absorb FSMA documentation costs that compress margins on industrial-grade volumes. Specialty-grade producers command customization premiums through EFSA-certified pyrolysis reactor calibration, yet liquid smoke substitutes exert downward pressure on standard phenolic dosing contracts.
Pricing Analysis
The customization-premium spread between configured-to-order Specialty grade and standard Industrial grade spans subscription-based direct-to-consumer channels versus per-unit transactional food service procurement. Price differentiation hinges on USDA organic certification tier and volume scale, with craft distilling partnerships showing least price sensitivity and mass-market sauce manufacturers most. Cost compression in Industrial grade is intensifying because spray-dried smoke condensates undercut per-unit phenolic dosing economics.
Supply Chain Analysis
Germany and the United States anchor pyrolysis reactor manufacturing and heritage smokehouse operations respectively, with British malt house relationships sustaining regional variant supply. Raw material dependencies center on beechwood sourcing, phenolic compound filtration media, and calibrated reactor components. Single-source vulnerability concentrates in Bavarian labor pools collapsing toward automated equipment transitions. Distribution runs through consolidated supplier qualification programs serving Hamburg-Lower Saxony manufacturing clusters and Kansas City-Austin barbecue sauce corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
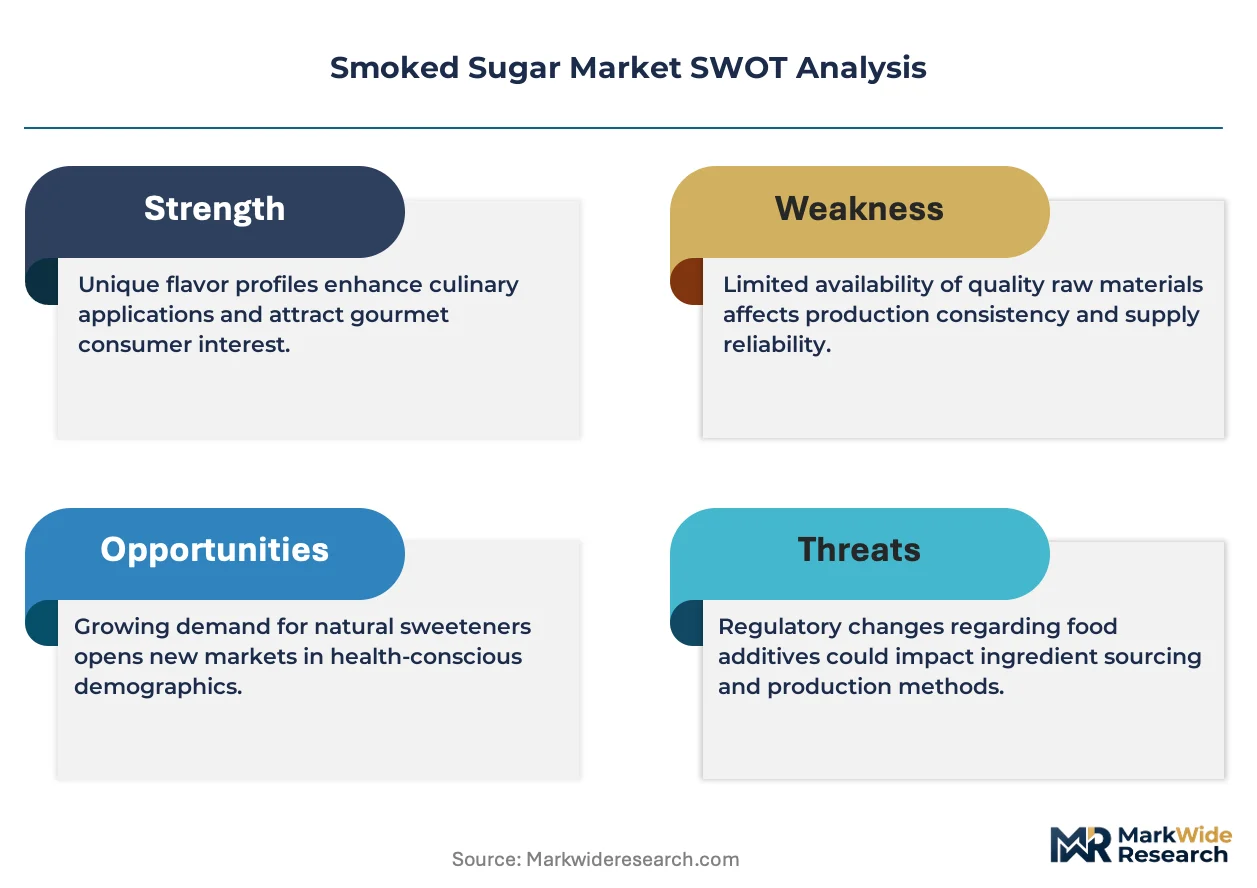
EFSA's advancing PAH detection capabilities constitute a regulatory inflection disrupting incumbent cost structures while rewarding contaminant filtration investments. This high-growth disruption favors technology-licensing archetypes over heritage smokehouse operators.
For Market Incumbents: Compound defensive positioning through backward integration into beechwood sourcing and automated pyrolysis reactor deployment. Liquid smoke substitution threats demand capacity addition in Germany's specialty corridor. FSMA preventive control documentation investments secure food service channel control against emerging reactor technology licensors. For New Entrants and Emerging Players: USDA organic certification fast-tracks unlock white-space penetration in American craft distilling co-marketing partnerships and United Kingdom heritage ingredient marketplaces. Direct-to-consumer subscription infrastructure represents the most penetrable channel. Target beverage flavoring applications requiring documented contaminant filtration as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition groups with underutilized pyrolysis reactor assets. Long-term viability across the analysis window favors technology-licensing specialists with proprietary calibration protocols. Monitor EFSA maximum residue level revisions as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Certification Investment | Pre-approved primary product categories unlock Hamburg-Lower Saxony manufacturing corridor access. |
| Automated Pyrolysis Deployment | Continuous reactor systems replace batch smokehouse operations constrained by collapsing artisanal labor pools. |
| Direct-to-Consumer Channel Buildout | Subscription infrastructure captures margin premiums previously allocated to food service distributors. |
| Backward Integration into Beechwood | Captive supply economics dominate continental European industrial volumes against independent processors. |
| Craft Distilling Partnership | Barrel-aged smoke variants command premium positioning in American co-marketing arrangements. |
Research Methodology
Desk research of EFSA flavoring substance evaluations, FDA GRAS determinations, and USDA organic certification protocols preceded structured interviews with pyrolysis reactor calibration technicians, specialty food manufacturing procurement leads, and craft distilling ingredient sourcing managers. Secondary validation drew from customs trade data on beechwood imports, SEC filings of diversified nutrition groups, and industry association technical standards. Bottom-up volume modeling and top-down value triangulation reconciled segment-level estimates.
Variance decomposition across grade tier, wood species sourcing, application formulation, and regional regulatory cluster shaped analytical framework development over the projection horizon. CAGRs derived from segment-level adoption curves weighted by EFSA protocol implementation timelines and FSMA preventive control compliance phases. Forecast inputs incorporated phenolic concentration targeting precision and continuous reactor replacement rates for batch smokehouse operations.
Underlying assumptions cover EFSA maximum residue level stability, beechwood supply continuity, and artisanal labor pool contraction trajectories, with deviation risk concentrated in advancing PAH detection capability thresholds. Forecasts reflect these conditions with acknowledgment that regulatory acceleration or pyrolysis technology breakthroughs could revise trajectory. Recalibration cycles align with material shifts in EFSA evaluation protocols and automated equipment adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Caramelized Sugars Market
Sweeteners
Agave Nectar Market
Sweeteners
Mannitol Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
Agave Syrup Market
Sweeteners
Liquid Sugar Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Cassava Syrup Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Aspartame Market
Sweeteners
Sugar Market
Sweeteners
Australia Allulose Market
Sweeteners
Corn Syrup Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market