
 Food Encapsulation Market | 2026-2036
Food Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Food Encapsulation Market Analysis
Buyer concentration among functional food and nutraceutical manufacturers is hardening as large CPG houses consolidate supplier rosters and demand turnkey encapsulation services. Givaudan SA leverages its flavor science heritage to anchor premium aroma-retention contracts with beverage multinationals. Cargill, Incorporated sustains massive manufacturing scale across its hydrocolloid and lipid carrier networks. Kerry Group plc differentiates through integrated taste-and-nutrition platforms that span probiotic protection through finished product formulation.
Food encapsulation encloses active ingredients within protective matrices—typically 1–1000 μm diameter shells of modified starch, gum arabic, or lipid carriers—to shield volatiles from oxidation, moisture, and thermal degradation during processing and storage. Spray drying dominates commercial output due to its continuous throughput and cost efficiency with carbohydrate wall materials, though coacervation commands margin pools in high-value flavor and probiotic applications where complex core-shell architecture delivers targeted release. Liposomes remain nascent in food-grade deployment constrained by scale-up costs and phospholipid sourcing, while microcapsules capture the bulk of vitamin stabilization demand across fortified food matrices.
EFSA novel food guidance and EU regulation on nutrition and health claims shape stability validation requirements for encapsulated bioactives, compelling manufacturers to generate release-kinetics dossiers. The FDA GRAS notification pathway governs new wall-material introductions in the United States, creating asynchronous approval timelines that fragment cross-Atlantic product rollouts. Stakeholders must monitor evolving clean-label definitions, as consumer rejection of synthetic emulsifiers threatens certain modified starch carriers and accelerates demand for allergen-free alternatives like pea protein isolates.
Market Dynamics
EFSA stability dossier requirements for encapsulated bioactives are compressing supplier margins while concentrating contract awards among houses with in-house analytical capabilities and GRAS-ready wall material portfolios.
Growth Catalysts
- EFSA Novel Food Guidance:Mandatory release-kinetics validation is locking in long-term supply relationships between encapsulators and functional food manufacturers seeking regulatory certainty across European markets.
- Spray Drying Scale Economics:Continuous carbohydrate-wall throughput is pulling vitamin fortification demand away from batch lipid-carrier alternatives in high-volume bakery and beverage applications.
- German Ingredient Clustering:Düsseldorf-Cologne corridor concentration is creating knowledge spillovers and shared analytical infrastructure that reduces per-dossier compliance costs for regional encapsulation houses.
Market Restraints
- Phospholipid Input Volatility:Food-grade lecithin sourcing constraints are capping liposome commercialization at pilot scale despite superior bioavailability profiles.
- Asynchronous FDA-EFSA Timelines:Divergent GRAS notification and novel food approval pathways are fragmenting cross-Atlantic product rollouts and duplicating stability study expenditures.
- Modified Starch Substitution Threat:Clean-label rejection of synthetic emulsifiers is threatening legacy maltodextrin carriers and accelerating reformulation costs for established encapsulation lines.
Strategic Opportunities
- Pea Protein Isolate Convergence:Allergen-free wall material demand is opening formulation partnerships between pulse processors and encapsulation specialists serving pediatric and free-from nutrition verticals.
- Coacervation Premiumization:Complex core-shell architecture for probiotic protection commands margin pools in high-value applications where targeted intestinal release justifies unit cost premiums.
- Turnkey Service Integration:Consolidating CPG procurement rosters are creating openings for houses that bundle encapsulation with finished product formulation and sensory optimization.
Industry Challenges
- Release-Kinetics Talent Scarcity:Analytical chemists capable of designing and interpreting dissolution profiles under EFSA validation protocols command compensation premiums that strain mid-cap encapsulation houses.
- Capex Intensity for Coacervation Scale-Up:Complex separation and drying infrastructure requirements are limiting commercial deployment of high-performance shell architectures to well-capitalized specialists.
- Clean-Label Reformulation Timelines:Accelerated consumer rejection of synthetic carriers is compressing product redevelopment cycles while alternative wall material qualification extends certification pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Encapsulation Market |
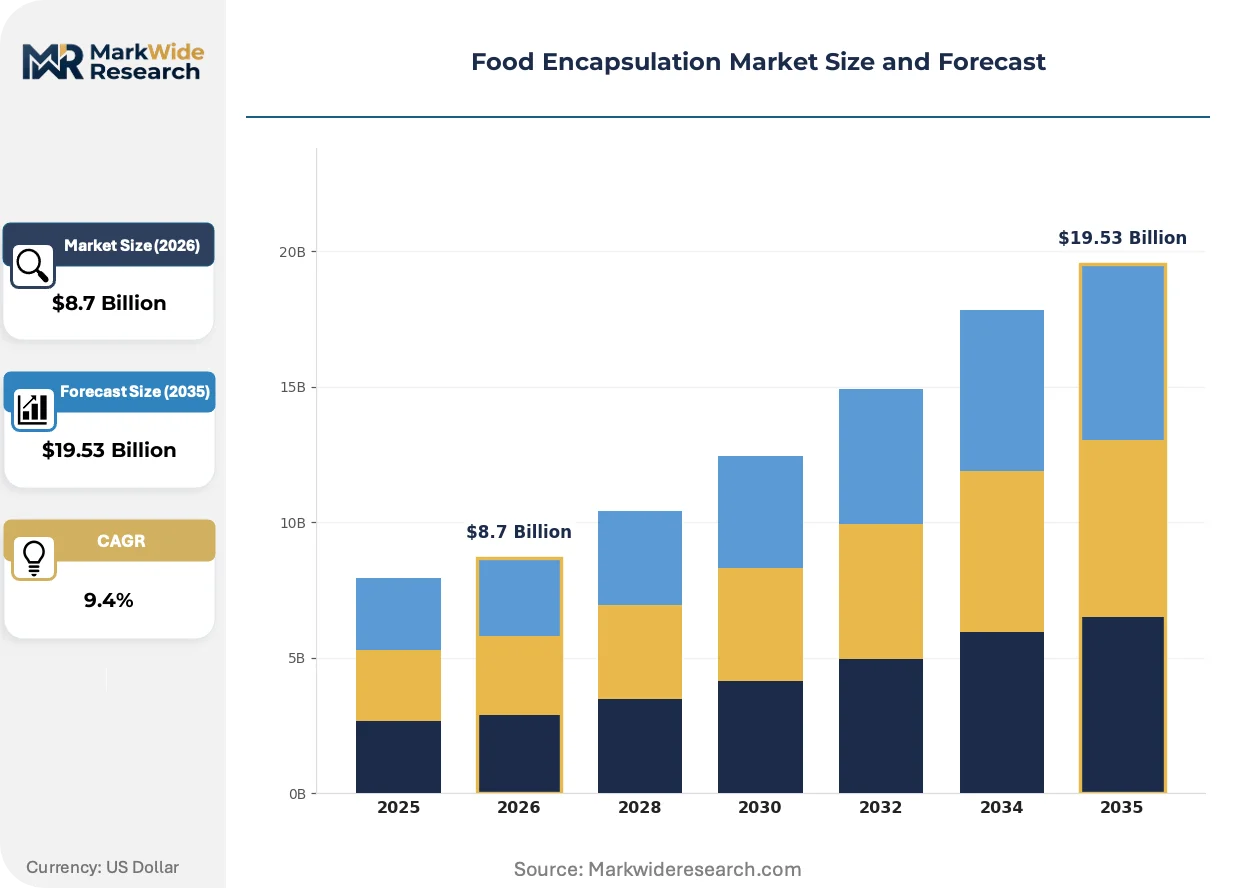
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcapsules, Nanocapsules, Macrocapsules, Liposomes Technology: Spray Drying, Coacervation, Extrusion, Fluid Bed Coating End Use: Functional Foods, Nutraceuticals, Beverages, Confectionery Application: Flavor Encapsulation, Vitamin Stabilization, Probiotic Protection, Aroma Retention |
| Companies Covered | Givaudan SA, Ingredion Incorporated, Cargill, Incorporated, Symrise AG, Koninklijke DSM N.V., BASF SE, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Encapsulation Market Emerging Trajectories
Encapsulation technology maturation is bifurcating the supplier base between high-throughput commodity carriers and precision-release premium architectures, with regulatory validation capabilities becoming the decisive competitive filter.
Electrospraying is overtaking conventional atomization for heat-sensitive bioactives. Probiotic and enzyme manufacturers in infant nutrition are adopting the technology to preserve viability through thermal processing. The method is overtaking spray drying in high-value segments where cell-count retention justifies throughput sacrifices and capital intensity.
EU regulation on nutrition and health claims is tightening evidentiary requirements for stability substantiation. Encapsulators must now generate release-kinetics dossiers correlating matrix protection with bioactive integrity through shelf life. Fortified beverage manufacturers are most affected, accelerating partnerships with houses possessing in-house analytical validation capabilities.
Buyer concentration among multinational CPG houses is consolidating supplier rosters toward turnkey encapsulation services. Procurement teams are bundling wall material supply, core loading, and finished formulation under single-source contracts. Germany's functional food corridor exhibits this pattern most visibly, with Düsseldorf-based ingredient houses capturing multi-year aroma-retention agreements.
Food Encapsulation Market Segmentation
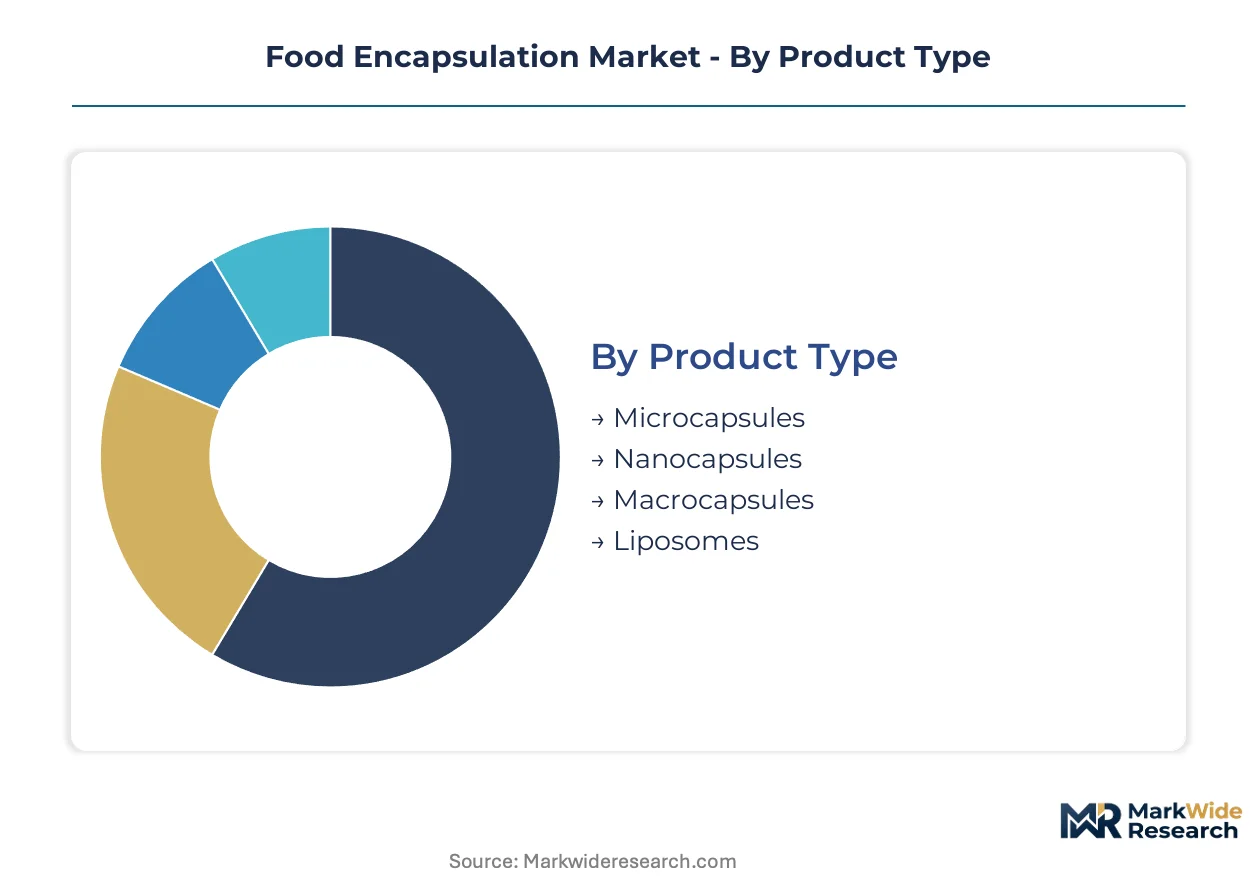
Encapsulation format selection dictates equipment investment, wall material compatibility, and release-kinetics performance. Manufacturers align segment choice with thermal tolerance of bioactives and regulatory validation burden across target markets.
Product Type:
Capital intensity scales inversely with particle size—nanocapsule production demands specialized homogenization and sterile filtration infrastructure that multiplies upfront outlays versus conventional microcapsule lines.
- Microcapsules:1–1000 μm diameter shells of modified starch or gum arabic dominate vitamin fortification across bakery and dairy matrices. Spray drying throughput economics pull demand from German and US functional food manufacturers seeking high-volume, cost-efficient bioactive protection.
- Nanocapsules:Sub-micron carriers below 1 μm achieve enhanced bioavailability for lipophilic nutraceuticals. Pharmaceutical-grade cleanroom requirements and electrohydrodynamic processing equipment restrict commercial deployment to well-capitalized houses serving premium supplement verticals in Switzerland and Japan.
- Macrocapsules:Particles exceeding 1000 μm enable visual differentiation and burst-release applications in confectionery.
- Liposomes:Phospholipid bilayer vesicles offer superior encapsulation efficiency for hydrophilic actives but remain pilot-scale constrained.
Microcapsules absorb the bulk of installed capacity; nanocapsules are expanding most quickly.
Technology:
Process selection hinges on thermal sensitivity of core materials and architectural complexity required for targeted release profiles.
- Spray Drying:Continuous atomization and rapid carbohydrate-wall solidification delivers lowest unit costs for heat-stable vitamins and minerals. High-throughput lines in the US Midwest and India's PLI-supported food processing corridors capture fortified beverage contract volumes.
- Coacervation:Complex phase-separation builds multi-layer core-shell architectures enabling intestinal-targeted probiotic release. EFSA stability dossier requirements for substantiated health claims concentrate demand among European houses with in-house analytical validation capabilities.
- Extrusion:Melt-based carrier formation suits lipid-soluble flavor and aroma compounds in high-temperature processing environments.
- Fluid Bed Coating:Layer-by-layer deposition onto solid particulates enables controlled release for chewable nutraceutical applications.
Spray drying commands the greatest installed base; coacervation claims the steepest expansion trajectory.
End Use:
Customer procurement sophistication varies—multinational CPG houses demand turnkey formulation integration while regional manufacturers prioritize carrier cost minimization.
- Functional Foods:Fortified dairy, bakery, and meat alternatives requiring bioactive stability through thermal processing and shelf life. German ingredient clusters around Düsseldorf and Cologne leverage shared analytical infrastructure to reduce per-dossier compliance costs for regional encapsulation houses.
- Nutraceuticals:Supplement tablets, softgels, and powders demanding precise release kinetics and label-claim integrity. FDA GRAS notification pathways in the US and TGA therapeutic goods requirements in Australia fragment approval timelines and duplicate stability expenditures.
- Beverages:Liquid matrices with unique solubility and clarity constraints for encapsulated actives.
- Confectionery:Heat-resistant flavor delivery systems for chocolate and hard candy applications.
Functional foods represent the largest addressable revenue pool; nutraceuticals are climbing the fastest on premiumization and regulatory substantiation demands.
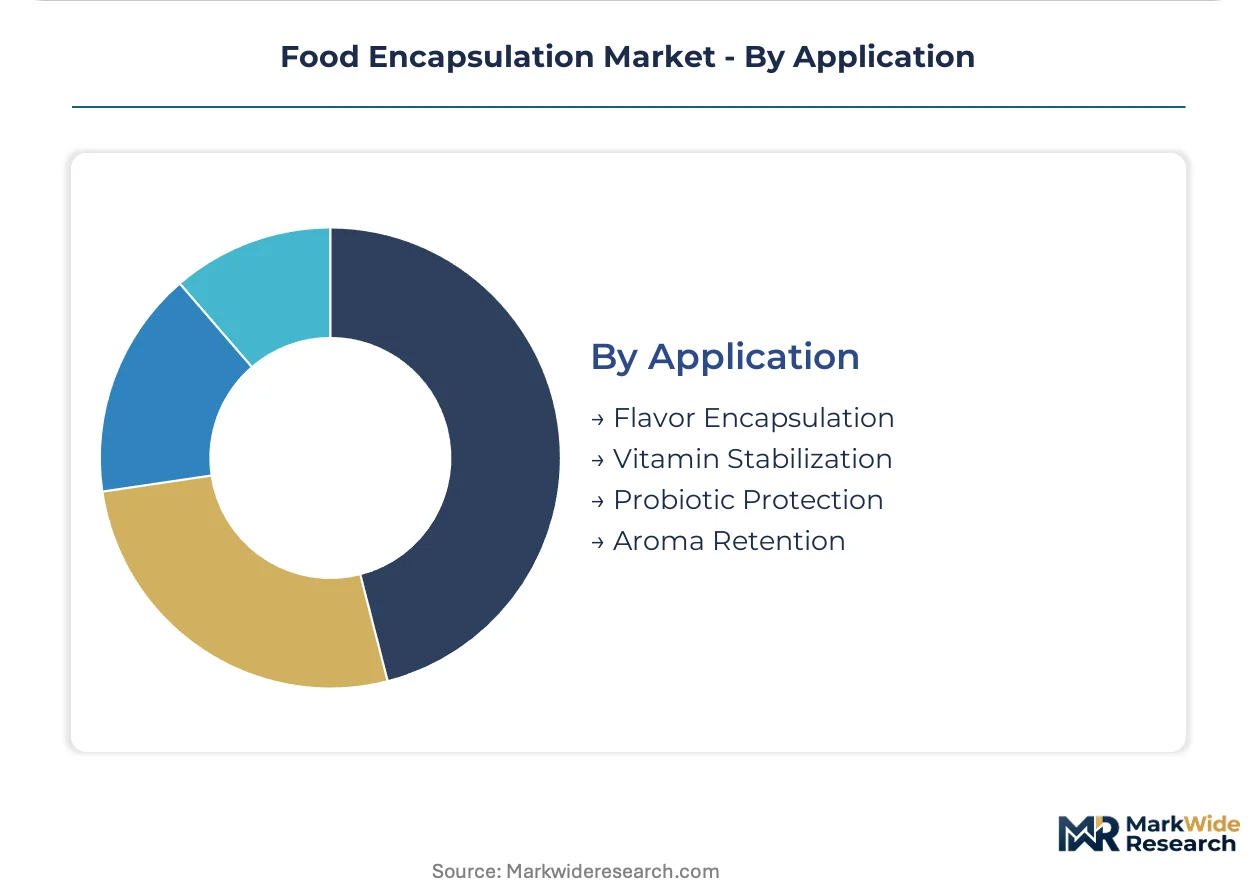
Application:
Technical performance requirements differ sharply—volatiles demand oxygen barriers while living cultures need moisture exclusion and gastric bypass.
- Flavor Encapsulation:Aroma retention through baking and frying thermal stress requires modified starch or lipid carriers with glass transition temperatures above processing peaks. Givaudan's flavor science heritage anchors premium contracts with beverage multinationals seeking consistent sensory profiles.
- Probiotic Protection:Viable cell delivery to intestinal sites demands complex coacervation shell architectures or electrosprayed matrices that sacrifice throughput for thermal gentleness. Infant nutrition manufacturers in Japan and South Korea adopt electrospraying where cell-count retention justifies capital intensity.
- Vitamin Stabilization:Oxidation-sensitive fat-soluble actives require oxygen-impermeable wall materials.
- Aroma Retention:Volatile compound preservation in ready-to-drink and instant beverage formats.
Flavor encapsulation captures the greatest contract value concentration; probiotic protection is gaining share fastest on clean-label and gut-health positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration among functional food and nutraceutical manufacturers is hardening across developed economies, with large CPG houses consolidating supplier rosters toward turnkey encapsulation services in specific national markets.
United States
Fortified beverage manufacturers drive contract volumes for vitamin stabilization through high-throughput spray drying lines in the Midwest. FDA GRAS notification pathways govern new wall-material introductions, creating distinct approval timelines versus European counterparts. Minneapolis-based ingredient houses leverage proximity to grain processing infrastructure for carbohydrate carrier supply security.
Germany
Functional food producers cluster around Düsseldorf and Cologne, generating knowledge spillovers and shared analytical infrastructure for EFSA stability dossiers. EFSA novel food guidance mandates release-kinetics validation, locking in long-term supply relationships between encapsulators and manufacturers seeking regulatory certainty. Regional houses capture multi-year aroma-retention agreements with beverage multinationals.
Switzerland
Premium supplement verticals in Geneva and Basel sustain demand for pharmaceutical-grade nanocapsule production despite electrohydrodynamic processing costs. Swissmedic therapeutic goods requirements enforce cleanroom standards that restrict commercial deployment to well-capitalized specialists. Zürich-area houses serve infant nutrition manufacturers adopting electrospraying for probiotic viability preservation.
Japan
Infant nutrition and probiotic protection applications command electrospraying adoption where cell-count retention justifies capital intensity. METI industrial policy supports food processing technology upgrades, including thermal-gentle encapsulation infrastructure. Osaka-based manufacturers partner with encapsulation specialists for complex coacervation shell architectures enabling intestinal-targeted release.
India
PLI scheme-supported food processing corridors in Gujarat and Maharashtra attract spray drying capacity for fortified beverage export manufacturing. FSSAI fortification standards drive demand for oxidation-stable vitamin carriers in bakery and dairy matrices. Mumbai-area ingredient traders coordinate hydrocolloid sourcing for regional encapsulation houses serving domestic CPG brands.
Food Encapsulation Market Vendor Landscape
German and Swiss producers anchor one tier of regulatory-validated premium encapsulation; US and Irish specialists hold scale-driven commodity carrier positions. Market structure bifurcates between high-throughput carbohydrate-wall manufacturers and precision-release architecture houses with in-house analytical capabilities. Three archetypes dominate: flavor-science heritage players, integrated taste-and-nutrition platforms, and hydrocolloid-lipid network scale operators. Competitive moves concentrate on M&A for turnkey service bundling and coacervation capacity expansion for probiotic protection margins.
Within the flavor-science heritage tier, Givaudan SA and International Flavors & Fragrances Inc. exemplify positioning anchored in aroma-retention contract concentration with beverage multinationals. Kerry Group plc occupies an integrated platform position spanning probiotic protection through finished formulation, while Cargill, Incorporated represents scale-driven network leverage across hydrocolloid and lipid carrier manufacturing. BASF SE and Koninklijke DSM N.V. sit within the nutrition-specialist archetype, with Ingredion Incorporated and Sensient Technologies Corporation occupying mid-scale formulation partnership roles. Symrise AG rounds out the competitive set within flavor and fragrance-anchored encapsulation services.
| Leading Market Players |
|---|
| Givaudan SA |
| Ingredion Incorporated |
| Cargill, Incorporated |
| Symrise AG |
| Koninklijke DSM N.V. |
| BASF SE |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Kerry Group plc |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up encapsulation specialists in Germany and the United States anchor supply concentration while enforcing pricing discipline through long-term contract structures with multinational CPG houses. This ownership pattern concentrates analytical validation capabilities among fewer players, compressing margin pools for mid-cap houses lacking in-house EFSA dossier generation.
Pricing Analysis
High-volume spray drying operations compete on throughput economics while coacervation commands premium unit economics for targeted-release applications. Three-tier pricing structure across premium, standard, and economy levels separates validated EFSA-compliant houses from commodity carbohydrate-wall suppliers and emerging electrospraying specialists. Pricing pressure stems from clean-label reformulation costs as manufacturers abandon modified starch carriers for allergen-free alternatives. Regional bakery and dairy manufacturers exhibit highest price sensitivity; infant nutrition and premium beverage multinationals absorb premiums for proven stability validation.
Supply Chain Analysis
Direct-to-CPG channels handle multinational contract volumes while regional distributors serve mid-tier functional food manufacturers in fragmented markets. Manufacturing gravity centers on Germany, the United States, and India, with spray drying capacity concentrating in Gujarat's PLI-supported corridors and the US Midwest. Raw material dependencies include food-grade lecithin from South American soy processors, gum arabic from Sudanese and Senegalese harvests, and modified starches from Midwest grain processors. Single-source vulnerability in phospholipid inputs constrains liposome scale-up despite superior bioavailability profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food encapsulation is transitioning from commodity carbohydrate-wall supply toward precision-release architectures, with electrospraying displacing conventional spray drying for heat-sensitive probiotics and enzymes.
For Market Incumbents: Extend analytical validation capabilities through captive laboratory infrastructure in the Düsseldorf-Cologne corridor to defend EFSA contract concentration against emerging electrospraying specialists. Prioritize backward integration into pea protein isolate supply to secure allergen-free wall material positioning ahead of clean-label substitution acceleration. For New Entrants and Emerging Players: Begin with electrospraying capacity for infant nutrition probiotic protection in Japan and South Korea, where cell-count retention premiums justify capital intensity. Target turnkey formulation partnerships with mid-tier CPG houses bypassing consolidated supplier rosters of multinational competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap encapsulation houses with GRAS-ready portfolios in the United States, where asynchronous FDA-EFSA timelines have stranded product development pipelines. Watch EFSA stability dossier approval velocity as inflection indicator for European contract award momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Coacervation Capacity Expansion | Captures probiotic protection premiums under EFSA novel food guidance validation requirements. |
| Pea Protein Isolate Partnership | Secures allergen-free wall material supply for pediatric and free-from nutrition verticals. |
| Turnkey Service Integration | Bundles encapsulation with sensory optimization to match consolidating CPG procurement patterns. |
| Electrospraying Infrastructure Deployment | Preserves bioactive viability for infant nutrition manufacturers prioritizing cell-count retention. |
| Regulatory Validation Laboratory Buildout | Generates release-kinetics dossiers compulsory for European functional food contract eligibility. |
Methodological Framework
EFSA guidance documents, FDA GRAS notifications, and FSSAI fortification standards formed the secondary backbone, supplemented by customs records on hydrocolloid trade flows and SEC filings from listed ingredient houses. Primary fieldwork encompassed plant managers at spray drying facilities, procurement leads at German functional food manufacturers, regulatory affairs directors navigating novel food pathways, and R&D heads at flavor science houses. Bottom-up and top-down triangulation reconciled installed capacity estimates with contract value disclosures across the value chain.
Bottom-up modeling anchored segment-level projections while top-down macro constraints validated aggregate market boundaries across the projection horizon. Segmentation dimensions encompassed encapsulation format, process technology, end-use vertical, application type, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for technology substitution effects, with forecast inputs including PLI scheme capacity announcements and EFSA dossier approval timelines.
Underlying measurement precision varies by segment; electrospraying and nanocapsule forecasts carry wider confidence intervals than mature spray drying volumes given pilot-scale constraints. Forecasts reflect assumptions on clean-label substitution velocity and phospholipid supply normalization that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market