
 Sodium Saccharin Market | 2026-2036
Sodium Saccharin Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Saccharin Market Outlook
Pharmaceutical-grade excipient revenue is rewriting margin distribution across the sodium saccharin value chain. Kaifeng Xinghua Fine Chemical leverages its Henan province manufacturing base to supply bulk powder to domestic and export markets. Merck KGaA anchors the high-purity segment through its pharmaceutical-grade certification programs. Vishnu Chemicals Ltd. competes on backward integration into sulfonation chemistry, controlling feedstock costs.
Sodium saccharin is the sodium salt of benzoic sulfimide, a high-intensity sweetener approximately 300-500 times sweeter than sucrose, manufactured through the Maumee process involving toluene sulfonation and amination. The compound serves primarily as a non-caloric sweetening agent in food systems and as a taste-masking excipient in pediatric and geriatric drug formulations. Powder and granulated product types carry the bulk of industrial volume, while liquid formulations gain traction in beverage processing lines seeking automated dosing. Pharmaceutical end users command premium pricing over commodity food-grade supply, with tablets emerging as the fastest-growing format for direct compression in nutraceutical applications.
The FDA's food additive regulations and the EU's REACH chemical safety framework govern purity thresholds and labeling requirements for sodium saccharin across Atlantic markets. China's SAMR enforces GB 1886.18 standards for food-grade saccharin, while India's FSSAI mandates specific labeling for artificial sweetener content in packaged foods. Stakeholders must monitor evolving pharmaceutical excipient monographs and regional bans on cyclamate alternatives that could accelerate or constrain saccharin substitution patterns.
Market Dynamics
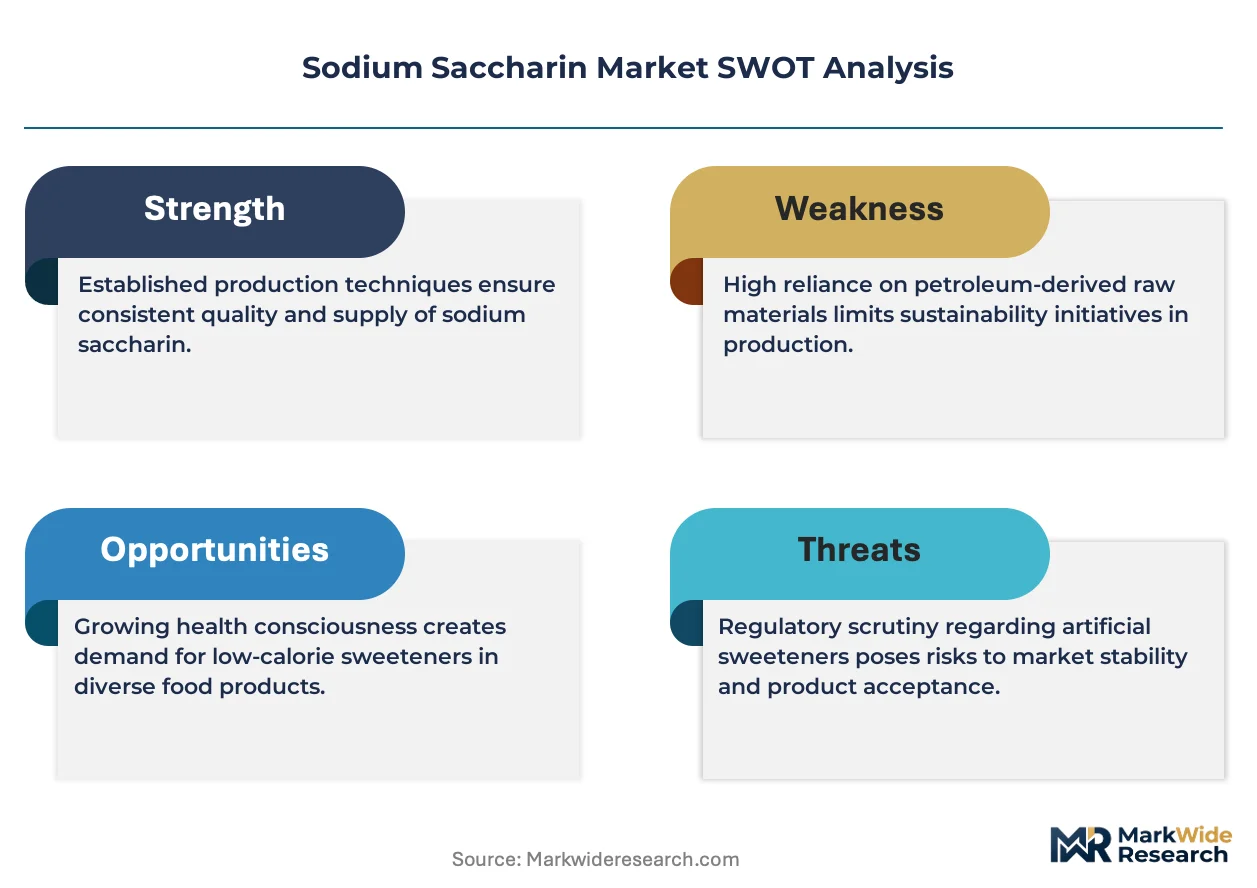
Pharmaceutical excipient certification requirements are compressing supply options and concentrating volume among producers capable of meeting dual food-grade and USP-grade specifications simultaneously.
Growth Catalysts
- India's pharmaceutical export expansion:Domestic API manufacturers in Hyderabad and Ahmedabad are absorbing saccharin volumes for taste-masked pediatric formulations destined for regulated markets.
- REACH registration deadlines:ECHA's substance evaluation protocols are filtering out non-compliant suppliers, creating volume consolidation opportunities for certified European importers.
- Continuous sulfonation technology:Process intensification is reducing batch-to-batch variability, enabling real-time quality release for pharmaceutical customers.
Market Restraints
- Toluene feedstock volatility:Petrochemical pricing swings directly compress margins for Maumee process operators without long-term supply contracts.
- Henan province concentration:China's saccharin manufacturing clusters in Kaifeng and Xinxiang create single-geography exposure for global supply continuity.
- Stevia glycoside substitution:Natural high-intensity sweeteners are capturing clean-label beverage formulations previously dependent on saccharin.
Strategic Opportunities
- Brazil's ANVISA excipient pathway:Simplified pharmaceutical ingredient registration is opening direct supply relationships with São Paulo-based generic drug manufacturers.
- Liquid dosing systems integration:Automated beverage production lines in Germany and Italy are specifying pre-diluted saccharin solutions to eliminate powder handling.
- Dual carbon compliance in China:MEE emissions standards are accelerating plant consolidation, creating acquisition targets for capitalized operators seeking GB 1886.18-certified capacity.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent USP, EP, and JP monograph specifications force parallel inventory management and analytical method validation.
- Sulfonation chemistry expertise scarcity:Experienced process engineers capable of optimizing ortho/para selectivity in toluene sulfonation are concentrated among retiring cohorts in legacy production regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Saccharin Market |
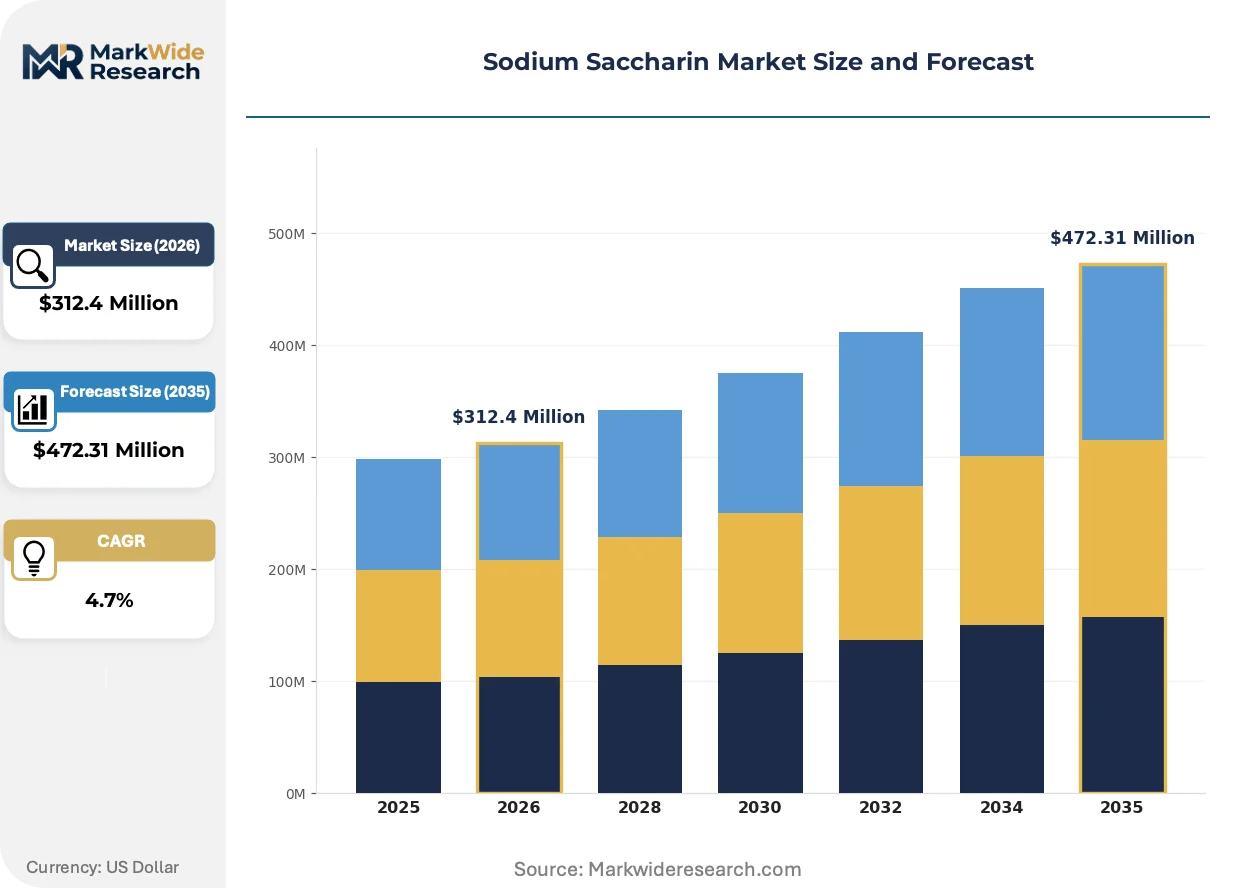
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulated, Tablets End User: Food & Beverage, Pharmaceuticals, Personal Care, Industrial Application: Beverages, Confectionery, Dairy Products, Frozen Desserts Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Merck KGaA, Sigma-Aldrich, Kaifeng Xinghua Fine Chemical Ltd., Vishnu Chemicals Ltd., Shanghai Merry Yang Enterprise Co., Ltd., PMC Specialties Group, JMC Corporation, Blue Jet Healthcare Limited, Tianjin North Food Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Saccharin Market Strategic Shifts
Process analytical technology and regulatory data harmonization are converging to reshape how saccharin producers validate quality and access pharmaceutical supply chains.
Inline near-infrared spectroscopy is digitizing real-time moisture and particle size monitoring during spray-drying operations. Contract manufacturers serving nutraceutical tablet producers are adopting these systems to eliminate offline testing delays. The technology is digitizing batch release workflows, compressing lead times from days to hours for certified excipient shipments.
EU REACH authorization requirements for substances of very high concern are tightening impurity disclosure thresholds for saccharin imports. ECHA's 2024 updated guidance on aromatic amine trace limits is forcing analytical method upgrades at toll manufacturers. Pharmaceutical-grade suppliers with in-house LC-MS capabilities are capturing volume from commodity traders unable to demonstrate compliance.
Direct procurement relationships between API formulators and certified excipient producers are displacing traditional distributor intermediaries in regulated markets. Large pharmaceutical manufacturers in New Jersey and Basel are implementing supplier qualification programs that bypass regional chemical traders. This pattern concentrates procurement leverage among buyers with dedicated quality audit resources.
Sodium Saccharin Market Segmentation
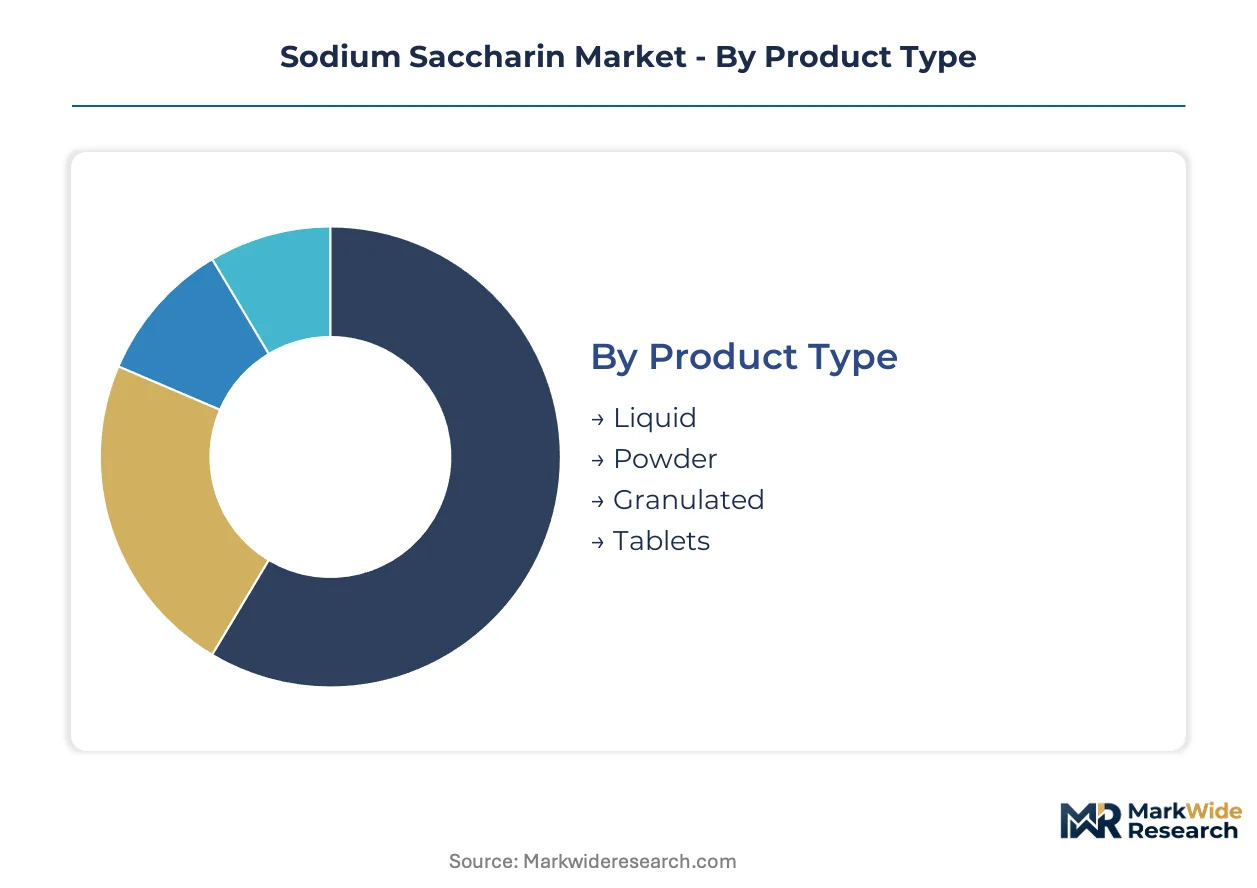
Sodium saccharin demand fragments across formulation formats, end-use specifications, and channel economics. Each segment carries distinct purity requirements, pricing tiers, and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Use-case spectrum spans automated beverage dosing lines to solid-dose pharmaceutical manufacturing, with physical form dictating handling infrastructure and customer qualification pathways.
- Powder:Fine crystalline material serves bulk food manufacturing and pharmaceutical excipient applications. India's API formulators in Hyderabad absorb volumes for taste-masked pediatric tablets bound for regulated export markets.
- Granulated:Free-flowing agglomerated particles eliminate dust generation during high-speed tablet compression. German nutraceutical contract manufacturers specify this grade for direct-blend operations requiring consistent particle size distribution.
- Liquid:Pre-diluted aqueous solutions enable automated metering in continuous beverage processing. Italian and German bottling lines are specifying this format to eliminate powder handling and dissolution steps.
- Tablets:Compressed unit-dose formats target small-scale food service and institutional catering applications. Convenience-driven procurement in Brazil's food service sector favors this ready-to-use presentation.
The dominant share belongs to Powder, while Liquid is closing the gap fastest.
End User:
Margin concentration tracks regulatory stringency, with pharmaceutical certification commanding substantial premia over commodity food-grade supply.
- Pharmaceuticals:USP-grade and EP-grade excipient specifications govern taste-masking in pediatric and geriatric drug formulations. CDSCO-registered Indian API manufacturers represent the fastest-expanding demand pool for certified saccharin sodium.
- Food & Beverage:Calorie-reduced product formulations across carbonated drinks, tabletop sweeteners, and processed foods. China's SAMR enforces GB 1886.18 purity thresholds that filter supplier eligibility for domestic packaged food producers.
- Personal Care:Toothpaste and oral hygiene products leverage saccharin's non-cariogenic sweetness without fermentation substrate properties. Formulators prioritize cost efficiency over pharmaceutical-grade certification in this segment.
- Industrial:Electroplating brightener applications and specialty chemical synthesis consume technical-grade material with relaxed purity specifications. Demand correlates with metal finishing activity in manufacturing clusters.
Pharmaceuticals captures the steepest margin expansion, while Food & Beverage retains volume leadership.
Application:
Processing temperature and pH environment determine saccharin stability requirements across finished product categories.
- Beverages:Acidic carbonated and still drinks represent the historic core application, with saccharin stability outperforming aspartame in thermal processing. Brazilian and Mexican bottlers maintain substantial formulation dependence despite clean-label substitution pressure.
- Confectionery:Hard candies and chewing gums leverage saccharin's heat stability during high-temperature cooking operations. India's domestic confectionery producers in Maharashtra and Gujarat specify food-grade powder for regional distribution.
- Dairy Products:Fermented and flavored milk applications require compatibility with live culture systems. Limited penetration reflects consumer preference for nutritive sweeteners in dairy positioning.
- Frozen Desserts:Ice cream and frozen novelties utilize saccharin in combination sweetener systems to manage freezing point depression. Seasonal demand patterns concentrate procurement in Q2-Q3 production cycles.
Beverages maintains installed base dominance, though Confectionery demonstrates the most resilient volume trajectory.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic proximity to manufacturing clusters.
- Distributors:Regional chemical traders aggregate smaller food manufacturer orders and provide logistics consolidation. REACH-registered European distributors are capturing volume from de-registered competitors following ECHA substance evaluation deadlines.
- Online:E-procurement platforms serve small-scale food service operators and institutional buyers seeking spot purchases. Limited penetration in pharmaceutical supply due to qualification audit requirements.
- Supermarkets:Retail tabletop sweetener sales reach consumer households through mass merchandising. Brand recognition and packaging format drive shelf placement decisions.
- Specialty Stores:Health food and professional baking supply outlets target clean-label skeptical consumers and artisanal producers. Niche positioning limits volume contribution.
Distributors command the largest transaction flow, while Online is gaining transaction frequency fastest among smaller accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes sodium saccharin primarily as pharmaceutical-grade excipients, while China deploys it across food manufacturing and industrial applications—a divergence that shapes supplier certification requirements and margin structures in each geography.
China
Henan province manufacturing clusters in Kaifeng and Xinxiang supply bulk powder to domestic food processors and export markets. SAMR enforces GB 1886.18 purity standards that filter supplier eligibility for packaged food producers. MEE emissions standards are accelerating plant consolidation, creating acquisition targets for capitalized operators seeking certified capacity.
India
Hyderabad and Ahmedabad API manufacturers absorb saccharin volumes for taste-masked pediatric formulations bound for regulated export markets. CDSCO registration requirements govern excipient qualification for pharmaceutical supply. Domestic producers supply API manufacturers across South Asia, concentrating demand in the pharmaceutical excipient sector.
Germany
Automated beverage production lines in Bavaria and Baden-Württemberg specify pre-diluted saccharin solutions to eliminate powder handling. ECHA's REACH substance evaluation protocols filter out non-compliant suppliers, creating volume consolidation opportunities for certified European importers. Nutraceutical contract manufacturers in the Rhineland specify granulated grades for direct-blend operations.
United States
New Jersey-based pharmaceutical manufacturers implement supplier qualification programs that bypass regional chemical traders. FDA food additive regulations govern purity thresholds and labeling requirements across Atlantic markets. Large formulators are establishing direct procurement relationships with certified excipient producers, displacing traditional distributor intermediaries.
Brazil
São Paulo-based generic drug manufacturers seek simplified pharmaceutical ingredient registration pathways. ANVISA's excipient registration framework is opening direct supply relationships with certified producers. Food service operators in the Southeast region favor compressed unit-dose formats for institutional catering applications.
Sodium Saccharin Market Competitive Environment
Capability concentration sits with pharmaceutical-grade specialists; scale advantage sits with bulk chemical manufacturers serving commodity food and industrial channels. The vendor base separates into three tiers: multinational excipient certifiers, integrated sulfonation operators, and regional toll manufacturers. Consolidation pressure is filtering out non-compliant suppliers under REACH deadlines and China's MEE emissions standards. Competitive moves center on backward integration into toluene sulfonation chemistry and acquisition of GB 1886.18-certified capacity in Henan province.
Among Asia-Pacific-based producers, Kaifeng Xinghua Fine Chemical Ltd. and Vishnu Chemicals Ltd. exemplify the integrated manufacturing archetype. Merck KGaA occupies a position representing the multinational pharmaceutical-grade certifier tier. Shanghai Merry Yang Enterprise Co., Ltd. and Tianjin North Food Co., Ltd. sit within the regional bulk supply segment serving domestic Chinese food manufacturers. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Merck KGaA |
| Sigma-Aldrich |
| Kaifeng Xinghua Fine Chemical Ltd. |
| Vishnu Chemicals Ltd. |
| Shanghai Merry Yang Enterprise Co., Ltd. |
| PMC Specialties Group |
| JMC Corporation |
| Blue Jet Healthcare Limited |
| Tianjin North Food Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Henan province manufacturing clusters compresses supplier margins while simultaneously concentrating pricing power among GB 1886.18-certified operators capable of serving pharmaceutical-grade demand. This utilization asymmetry creates divergent pricing postures across commodity food-grade and certified excipient tiers.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical supply relationships, insulating certified producers from toluene feedstock volatility while spot-market transactions govern food-grade powder sales to regional distributors. Three-tier pricing structure across USP-grade, food-grade, and technical-grade specifications anchors differentiation, with certification investment and volume scale as primary drivers. Cost compression in commodity food-grade tiers is intensifying because stevia glycoside substitution erodes saccharin's clean-label positioning. Food manufacturers exhibit highest price sensitivity, while pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes governing chemical substance registration filter supplier eligibility, with ECHA's REACH authorization requirements and China's dual carbon compliance standards limiting cross-border flows. Manufacturing concentrates in China, India, and Germany, with raw material dependencies on toluene feedstock, sulfuric acid, and ammonia. Single-source vulnerability from Henan province concentration creates supply continuity exposure for global pharmaceutical customers. Distribution runs through REACH-registered European distributors and direct procurement relationships with large API manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous sulfonation technology adoption sits as a high-growth disruption, with real-time quality release capabilities separating certified pharmaceutical suppliers from commodity batch operators. ECHA's updated aromatic amine trace limits accelerate this bifurcation.
For Market Incumbents: Pre-empt stevia substitution pressure by deepening backward integration into toluene sulfonation chemistry and securing long-term feedstock contracts. Invest in LC-MS analytical capabilities to capture volume from toll manufacturers unable to meet ECHA's tightened impurity disclosure thresholds. Kaifeng-based capacity with GB 1886.18 certification represents a defensible moat.
For New Entrants and Emerging Players: Pursue ANVISA's simplified excipient registration pathway to establish direct supply relationships with São Paulo-based generic drug manufacturers. Brazil's pharmaceutical sector offers the most penetrable entry point among regulated markets. Lead with liquid dosing system integration for automated beverage production lines in Germany and Italy.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MEE emissions standards and REACH deadlines are filtering out non-compliant suppliers, creating acquisition targets for capitalized operators. Target GB 1886.18-certified capacity in Henan province with existing pharmaceutical customer relationships. The signal to watch is CDSCO registration velocity among Indian API manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Sulfonation | Captive feedstock supply insulates margins from petrochemical pricing swings. |
| Pharmaceutical-Grade Certification Investment | USP-grade qualification unlocks premium pricing from pediatric formulation manufacturers. |
| Liquid Dosing System Development | Pre-diluted solutions align with automated beverage lines in Bavaria and Baden-Württemberg. |
| GB 1886.18-Certified Capacity Acquisition | SAMR-compliant production assets filter competitor eligibility in China's packaged food sector. |
| REACH Registration Compliance Program | ECHA authorization maintains European market access amid substance evaluation deadlines. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and pharmaceutical excipient monographs. Interviews with plant managers at sulfonation facilities, procurement leads at downstream API manufacturers, distribution channel partners, and technical R&D directors informed supply-side dynamics. Secondary validation drew from ECHA substance registration databases, CDSCO filings, SAMR food additive standards, and SEC disclosures from listed chemical producers. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use segments.
Forecast inputs span pharmaceutical excipient certification rates, food-grade substitution patterns, and regional regulatory enforcement intensity. Segmentation dimensions include product physical form, end-use industry, application category, and distribution channel structure. CAGRs were derived from regression analysis of historical volume trajectories and projected demand elasticity across the analysis window. Toluene feedstock pricing volatility and REACH registration compliance timelines served as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in petrochemical pricing cycles or pharmaceutical export demand from India would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and technology adoption curves. Material shifts in ECHA authorization requirements or MEE emissions standard implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Galactose Market
Sweeteners
Russia Food Sweetener Market
Sweeteners
Invert Sugar Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Mannitol Market
Sweeteners
Oligofructose Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
South Korea Allulose Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Fructose Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Europe Starch Sweetener Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Cassava Syrup Market